Research
Equity research, cross-asset trade ideas, a hedging strategy and its models, an infrastructure plan and econometrics, each answering a set brief.
Overview
Research on companies and markets: where a price looks wrong, which trade suits a client's portfolio, how a borrower should hedge and where a state should put its infrastructure money. Each piece answers a brief and was written to a deadline. Most were for case competitions and defended in front of a panel; the rest were for university courses. None of it was a live position, and none of it is advice.
Cross-asset trades
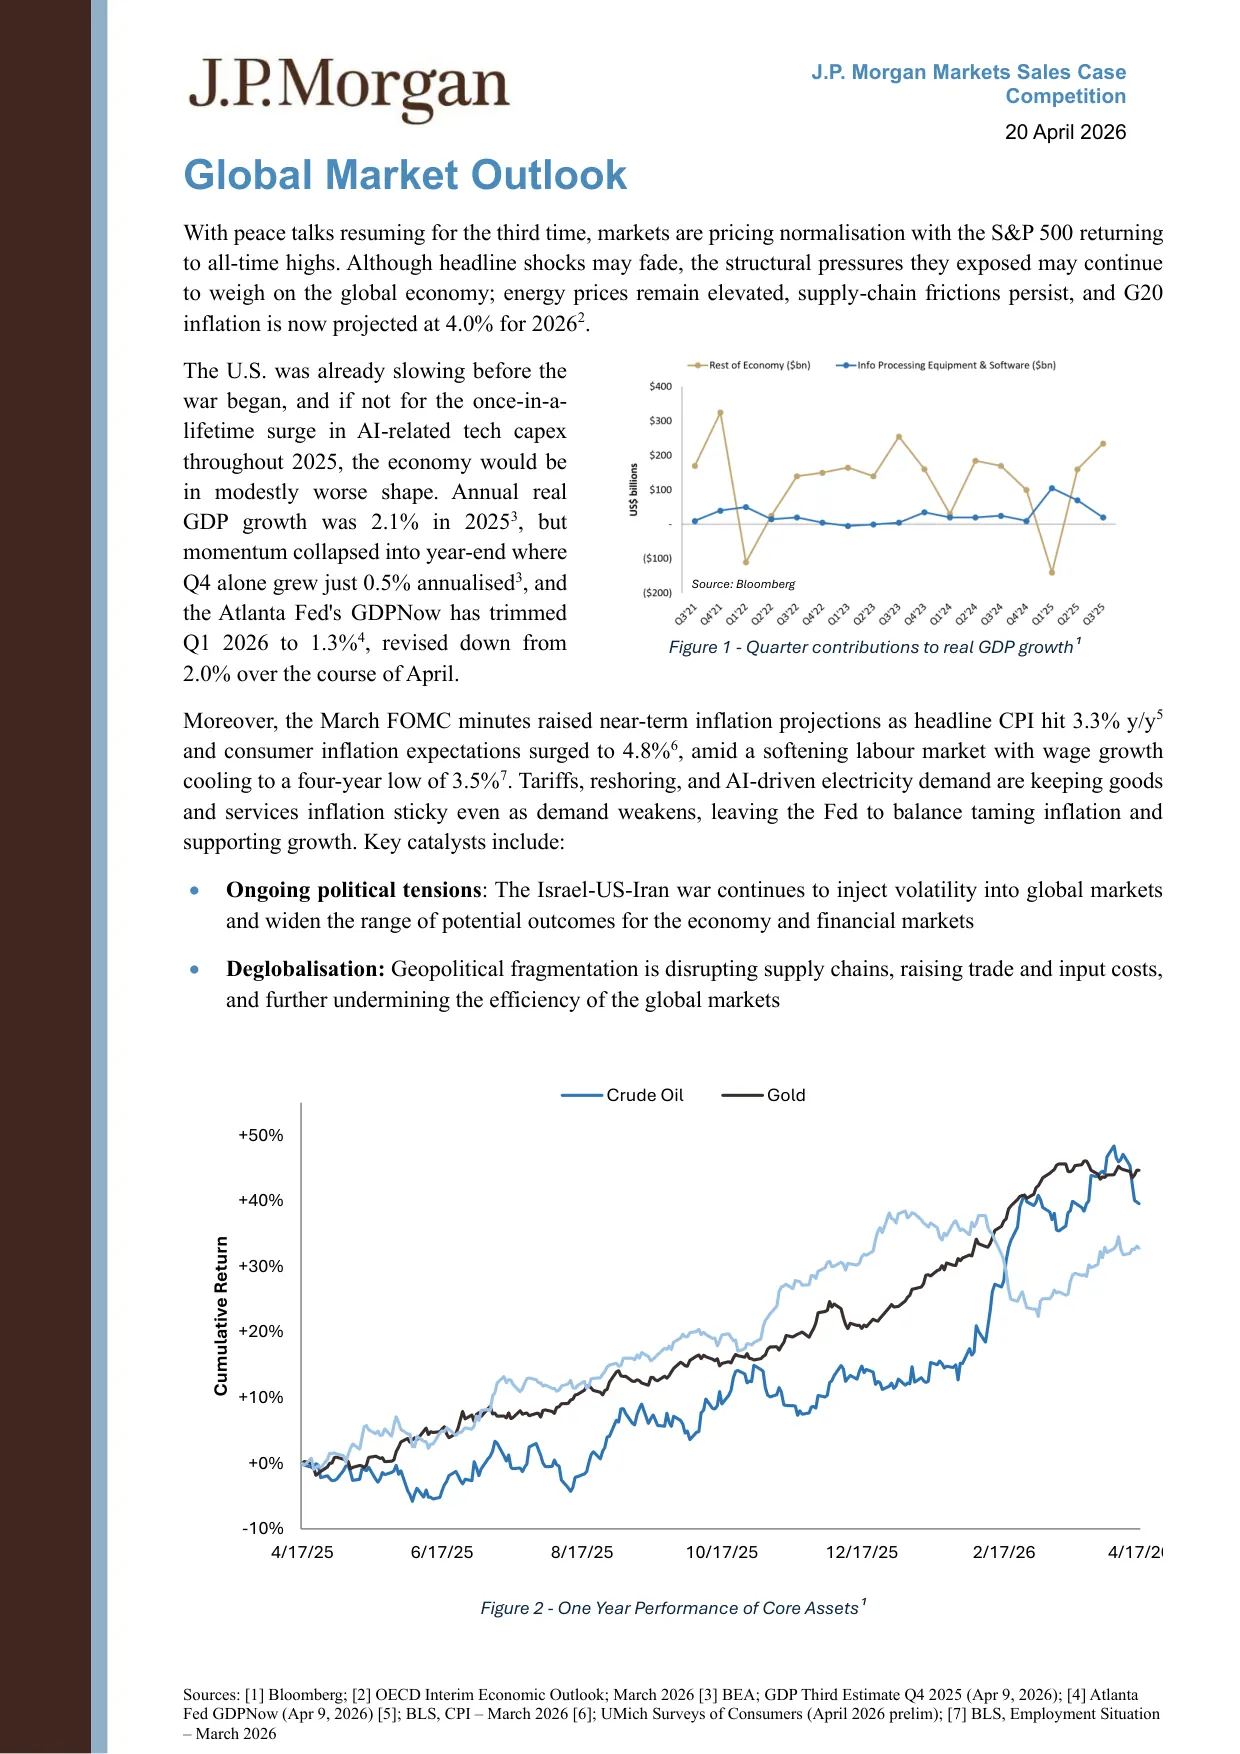
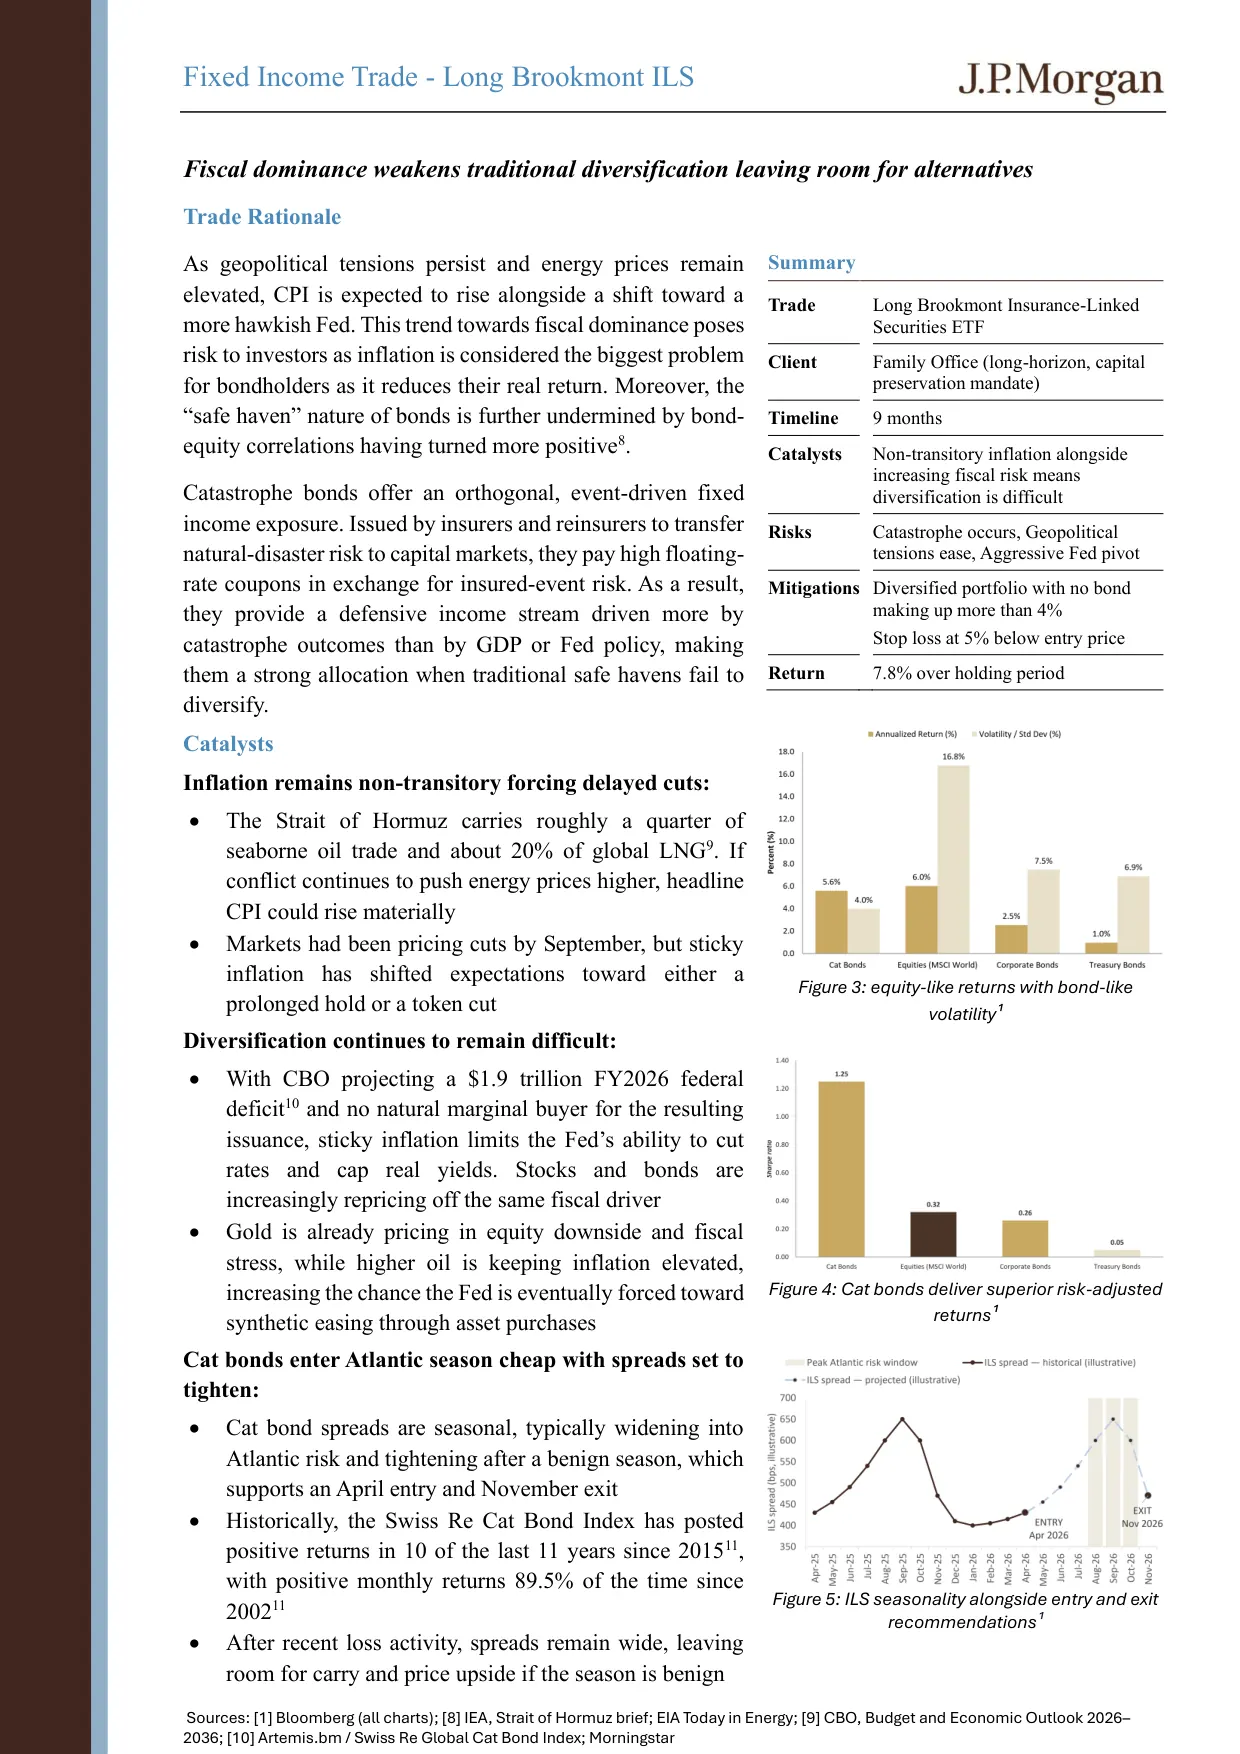
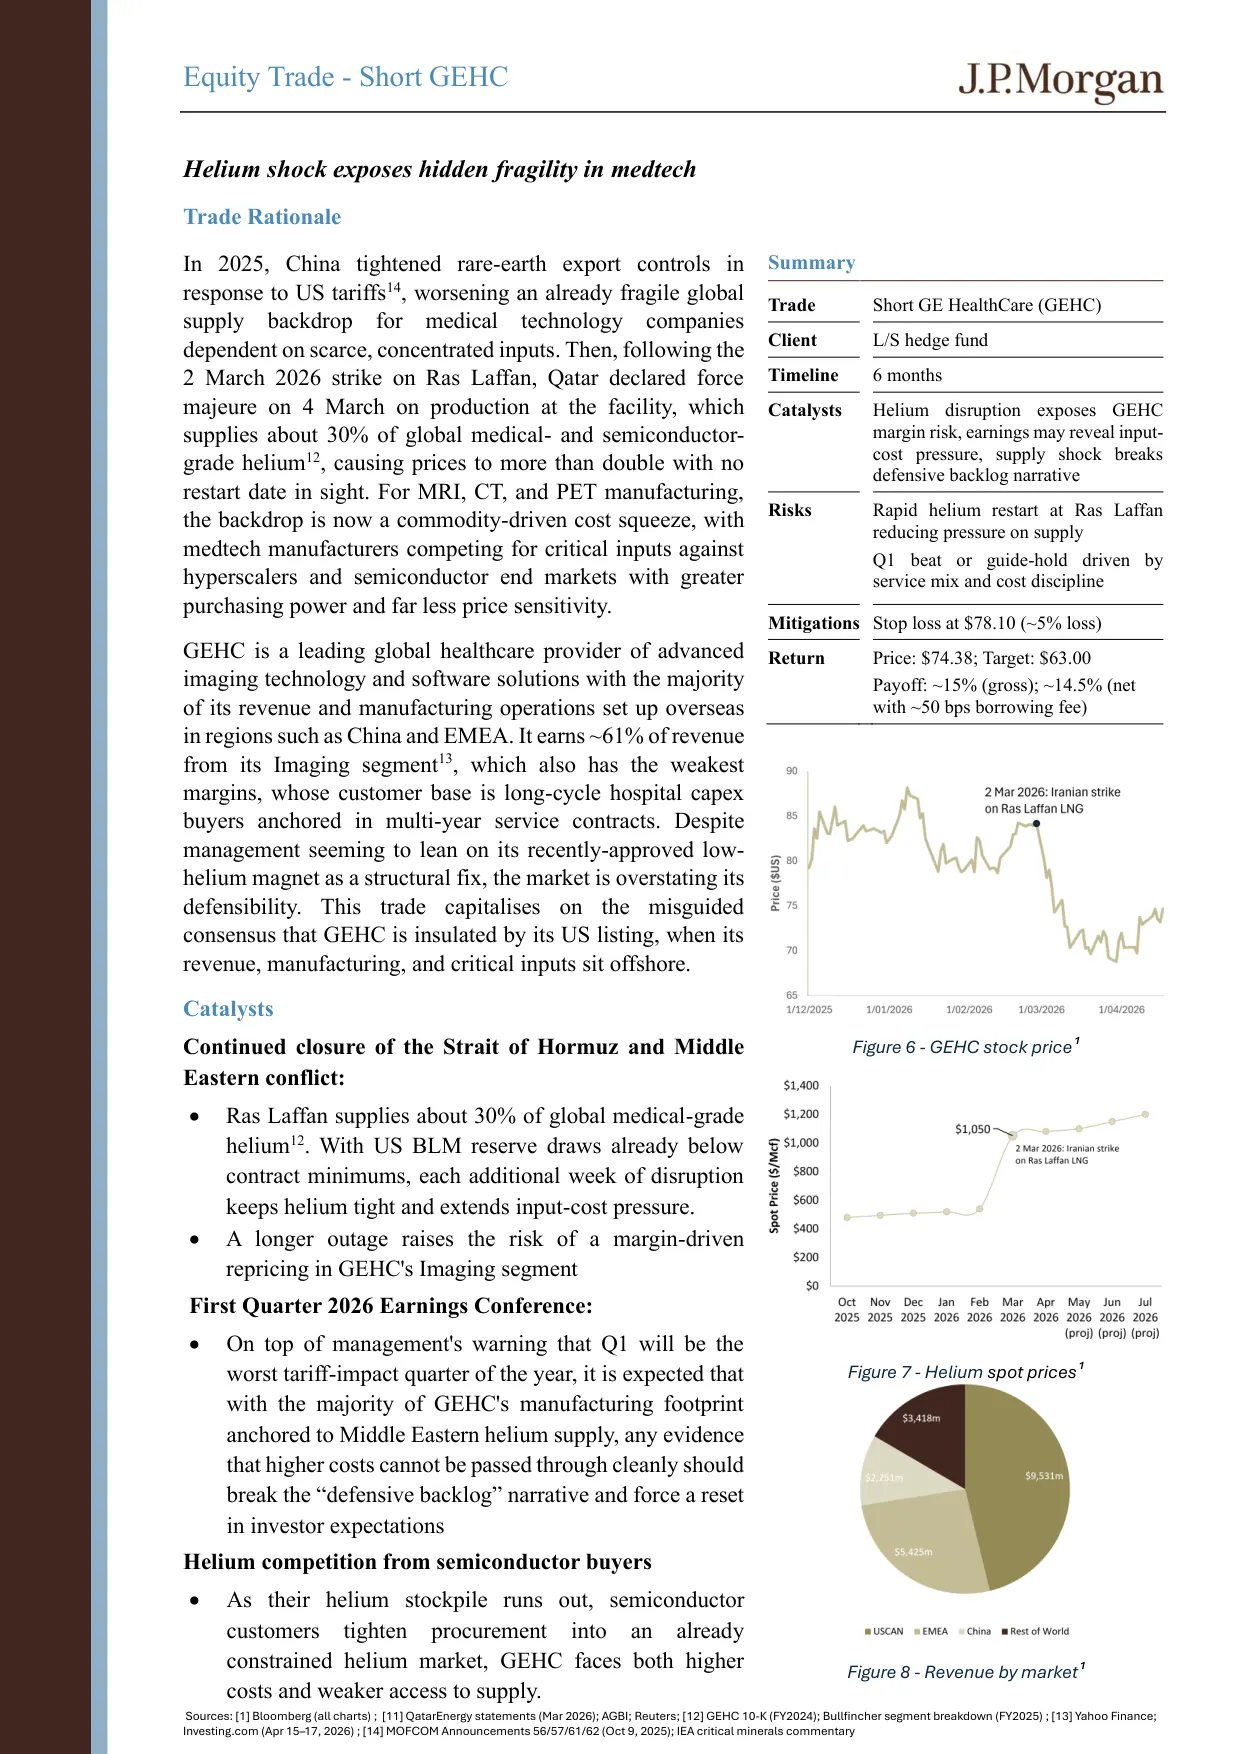
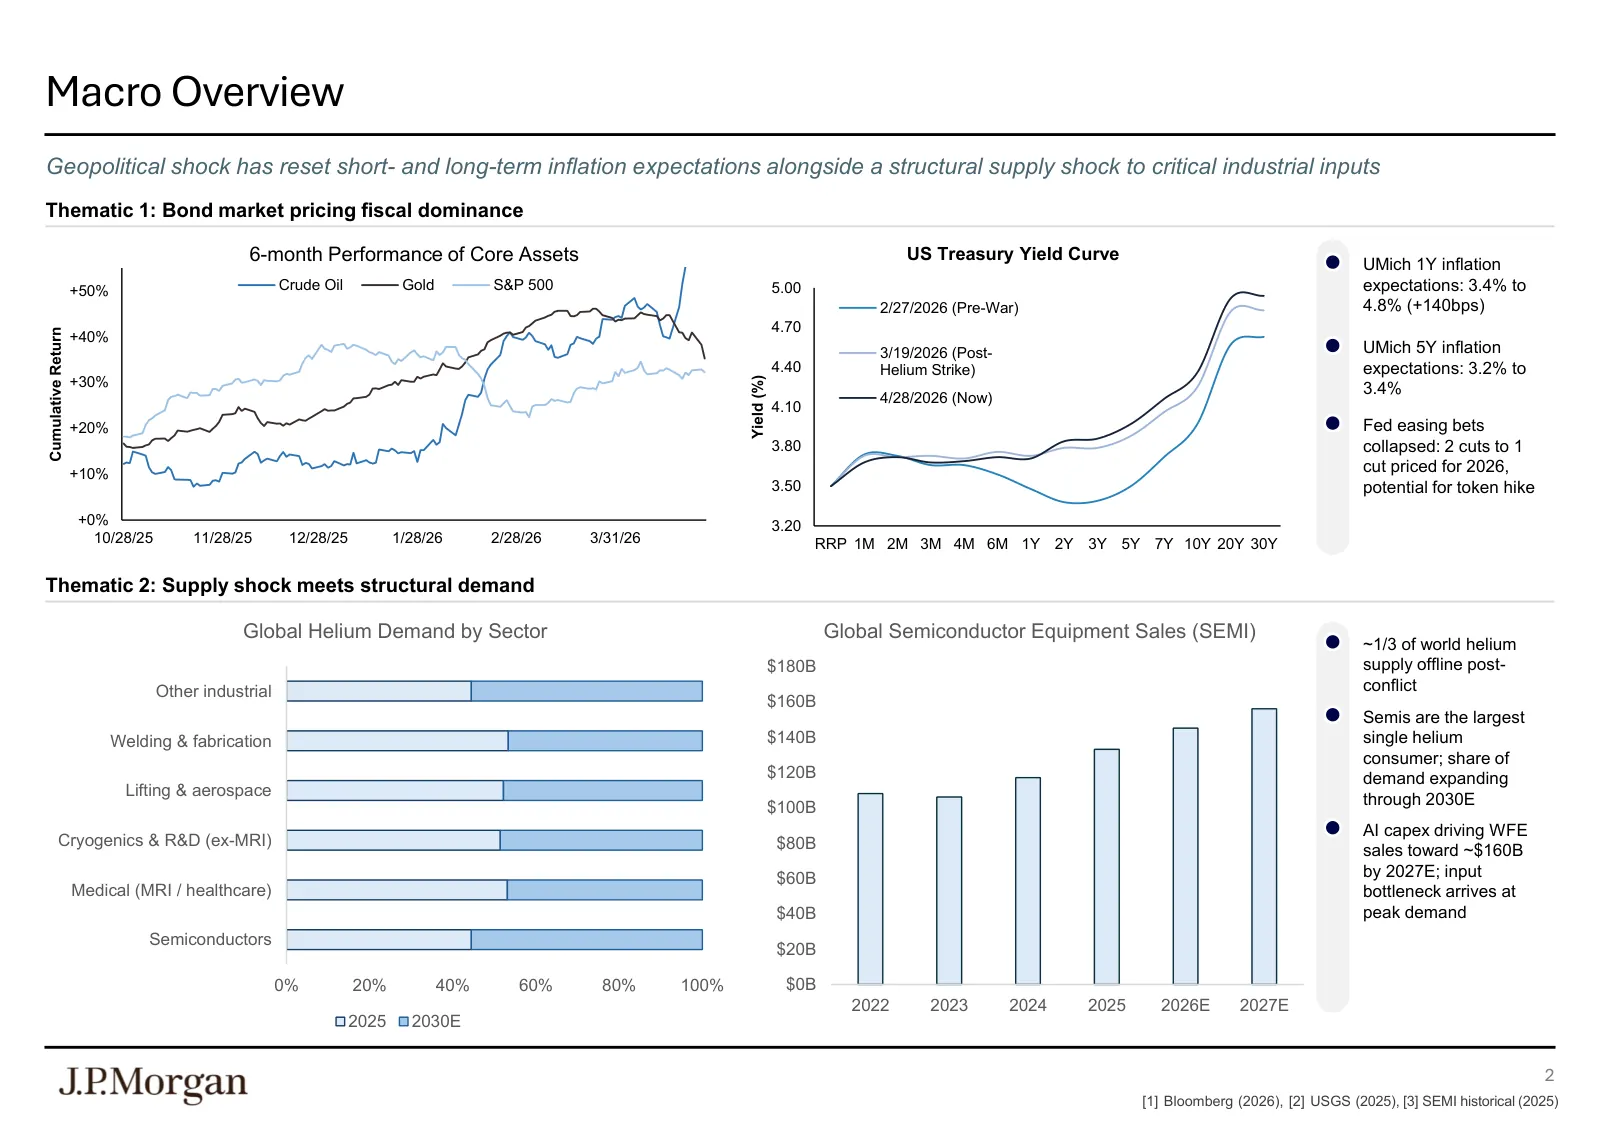
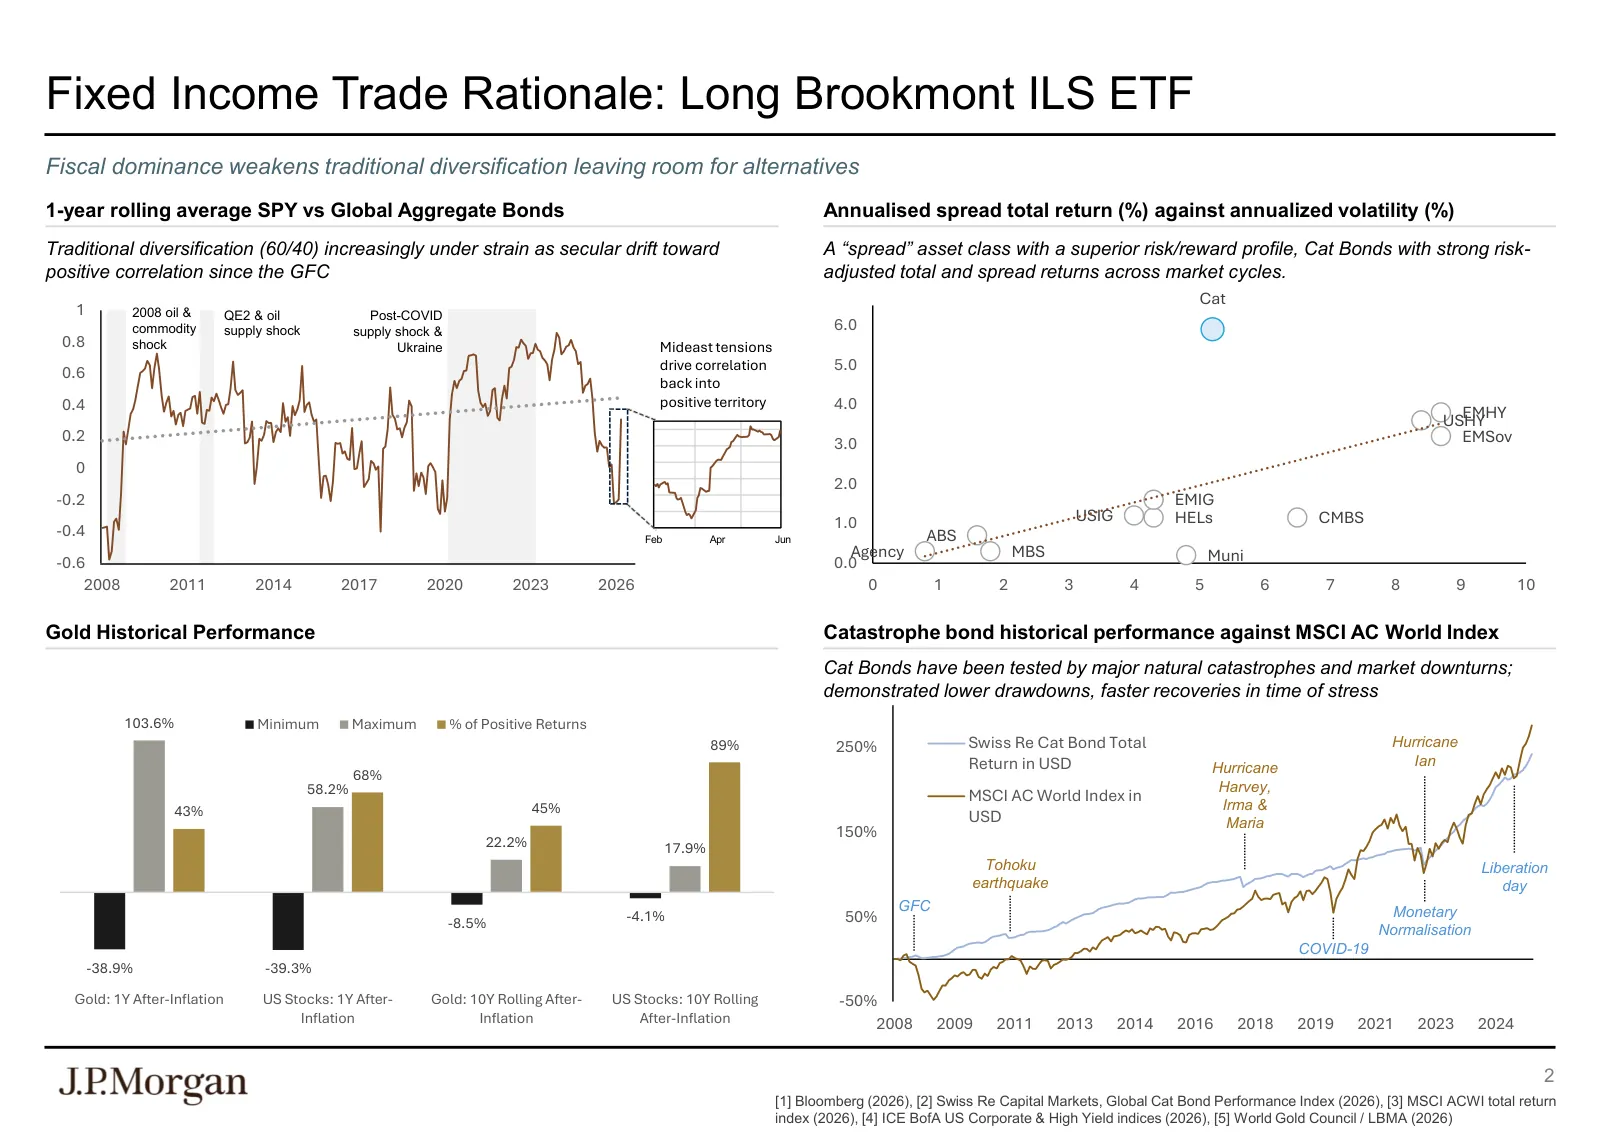
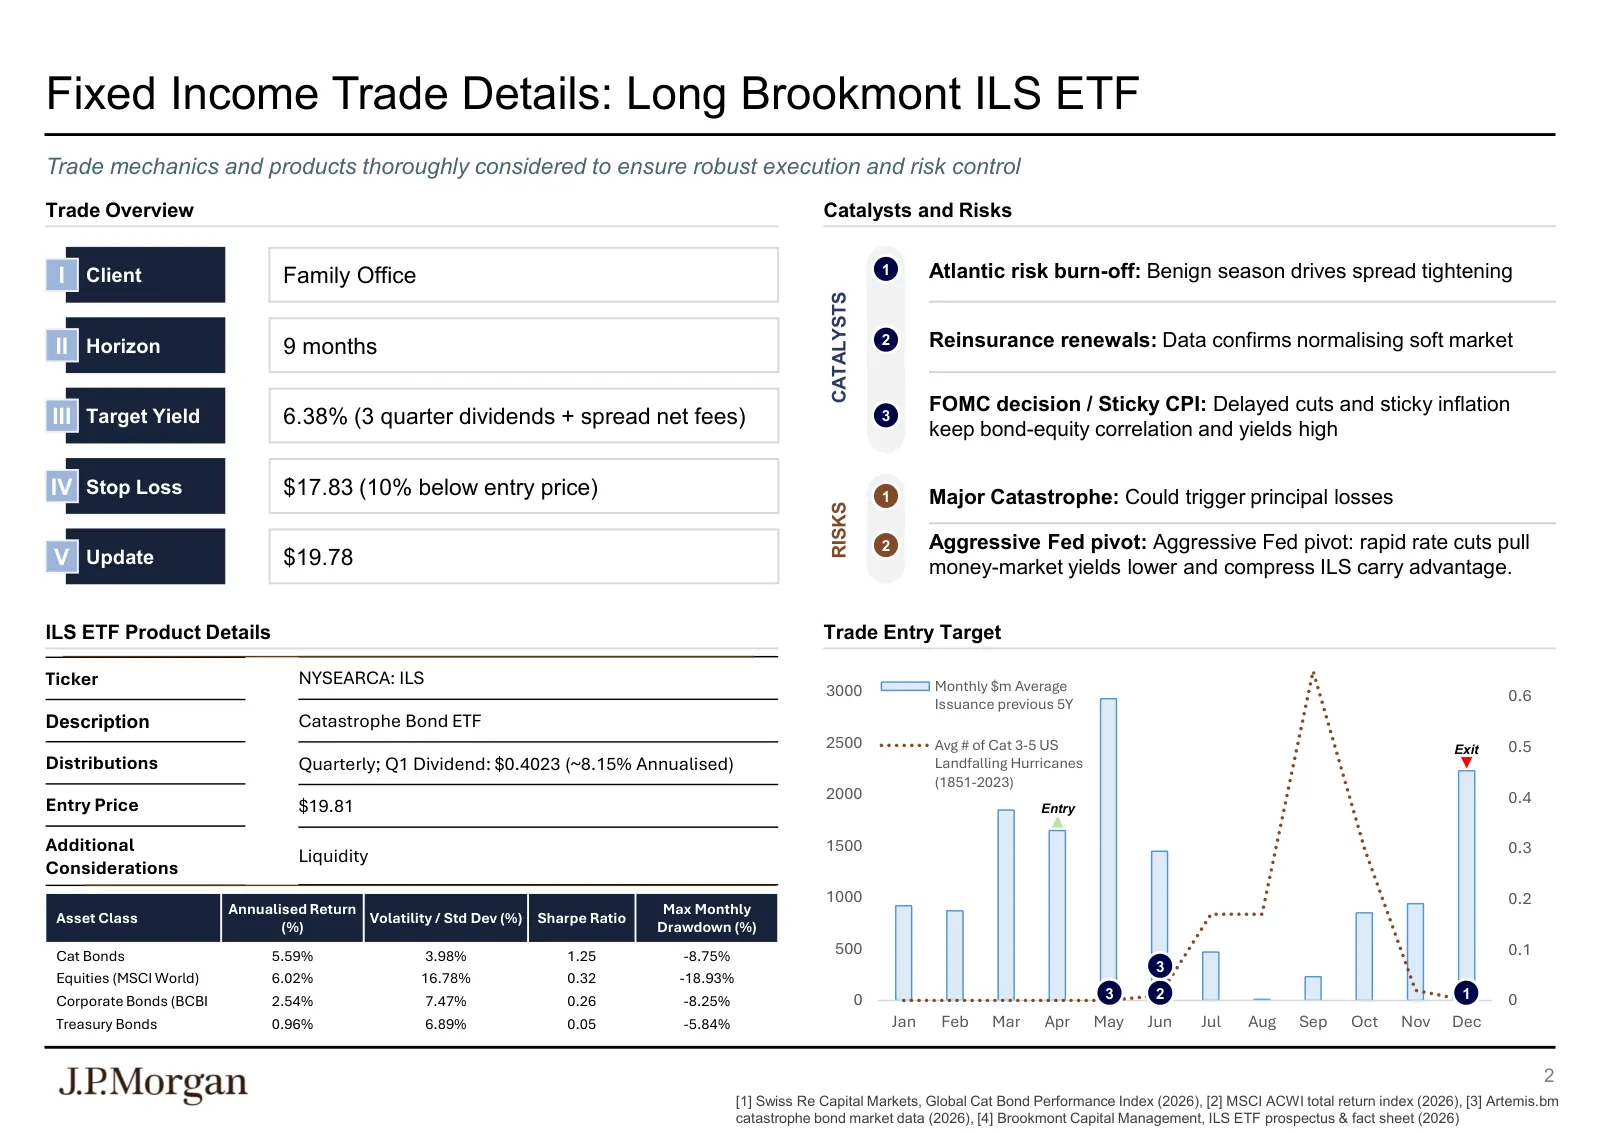
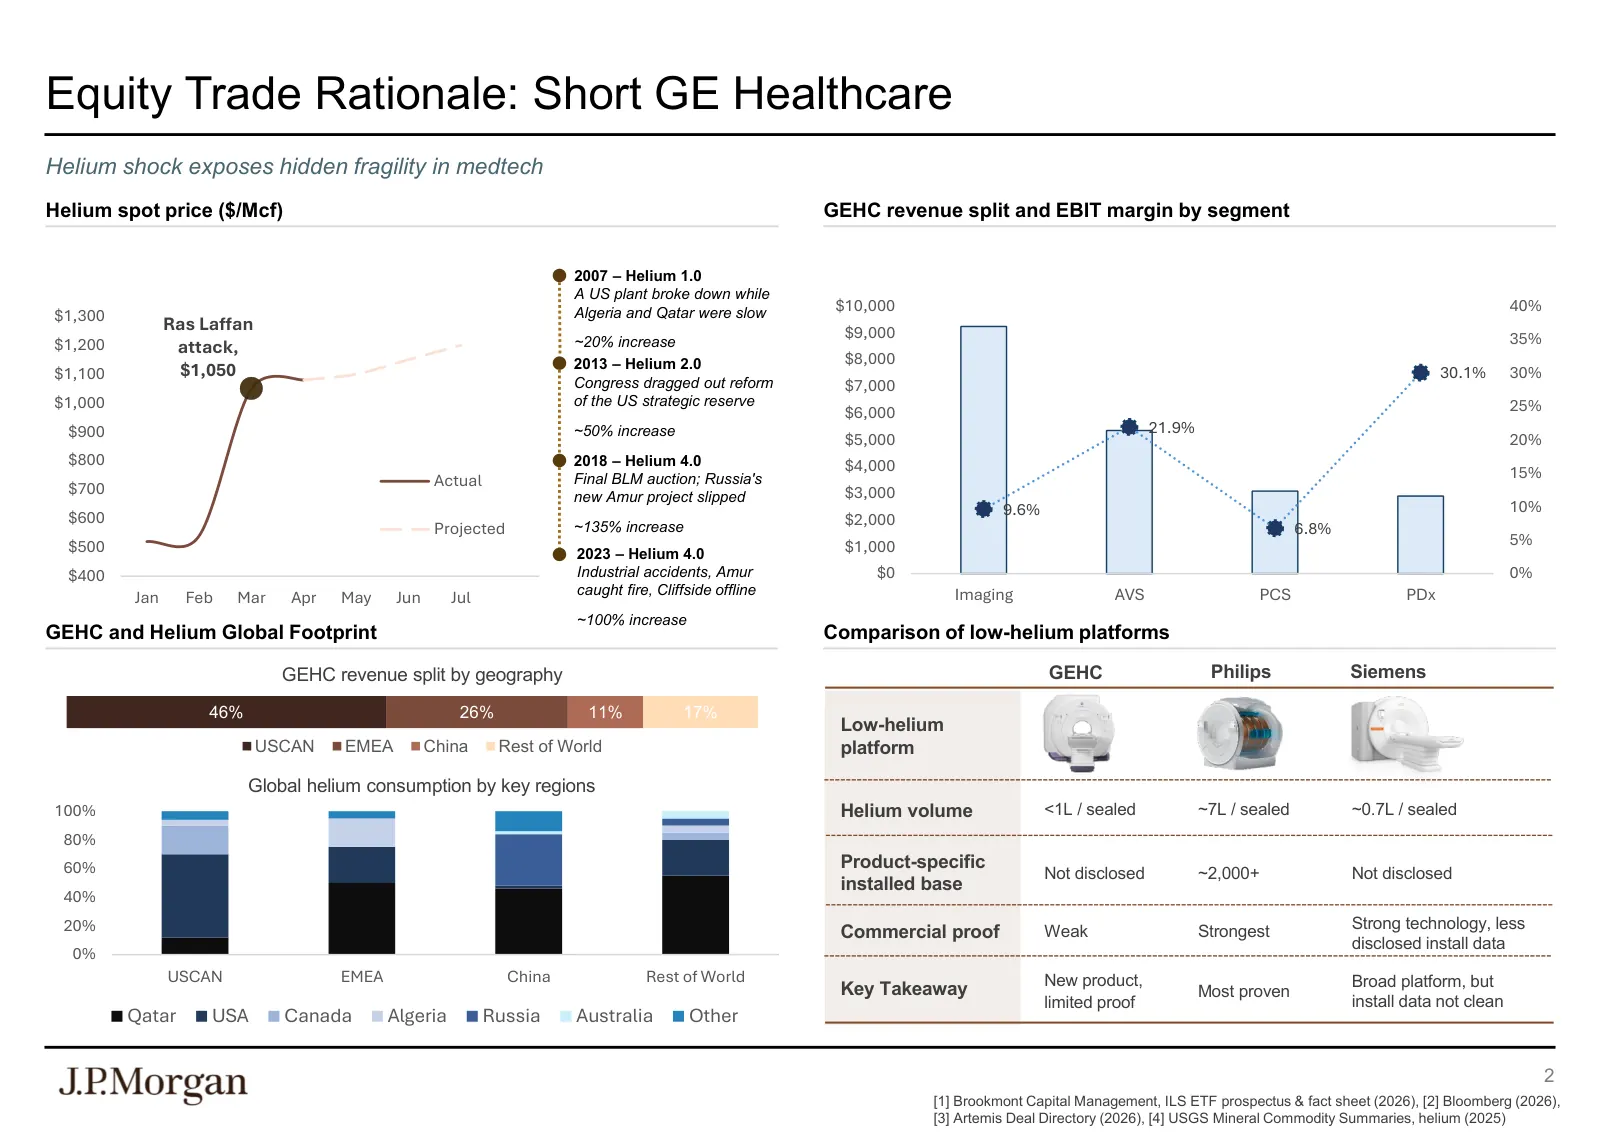
Two trade ideas for J.P. Morgan's markets sales team. April 2026. Individual.
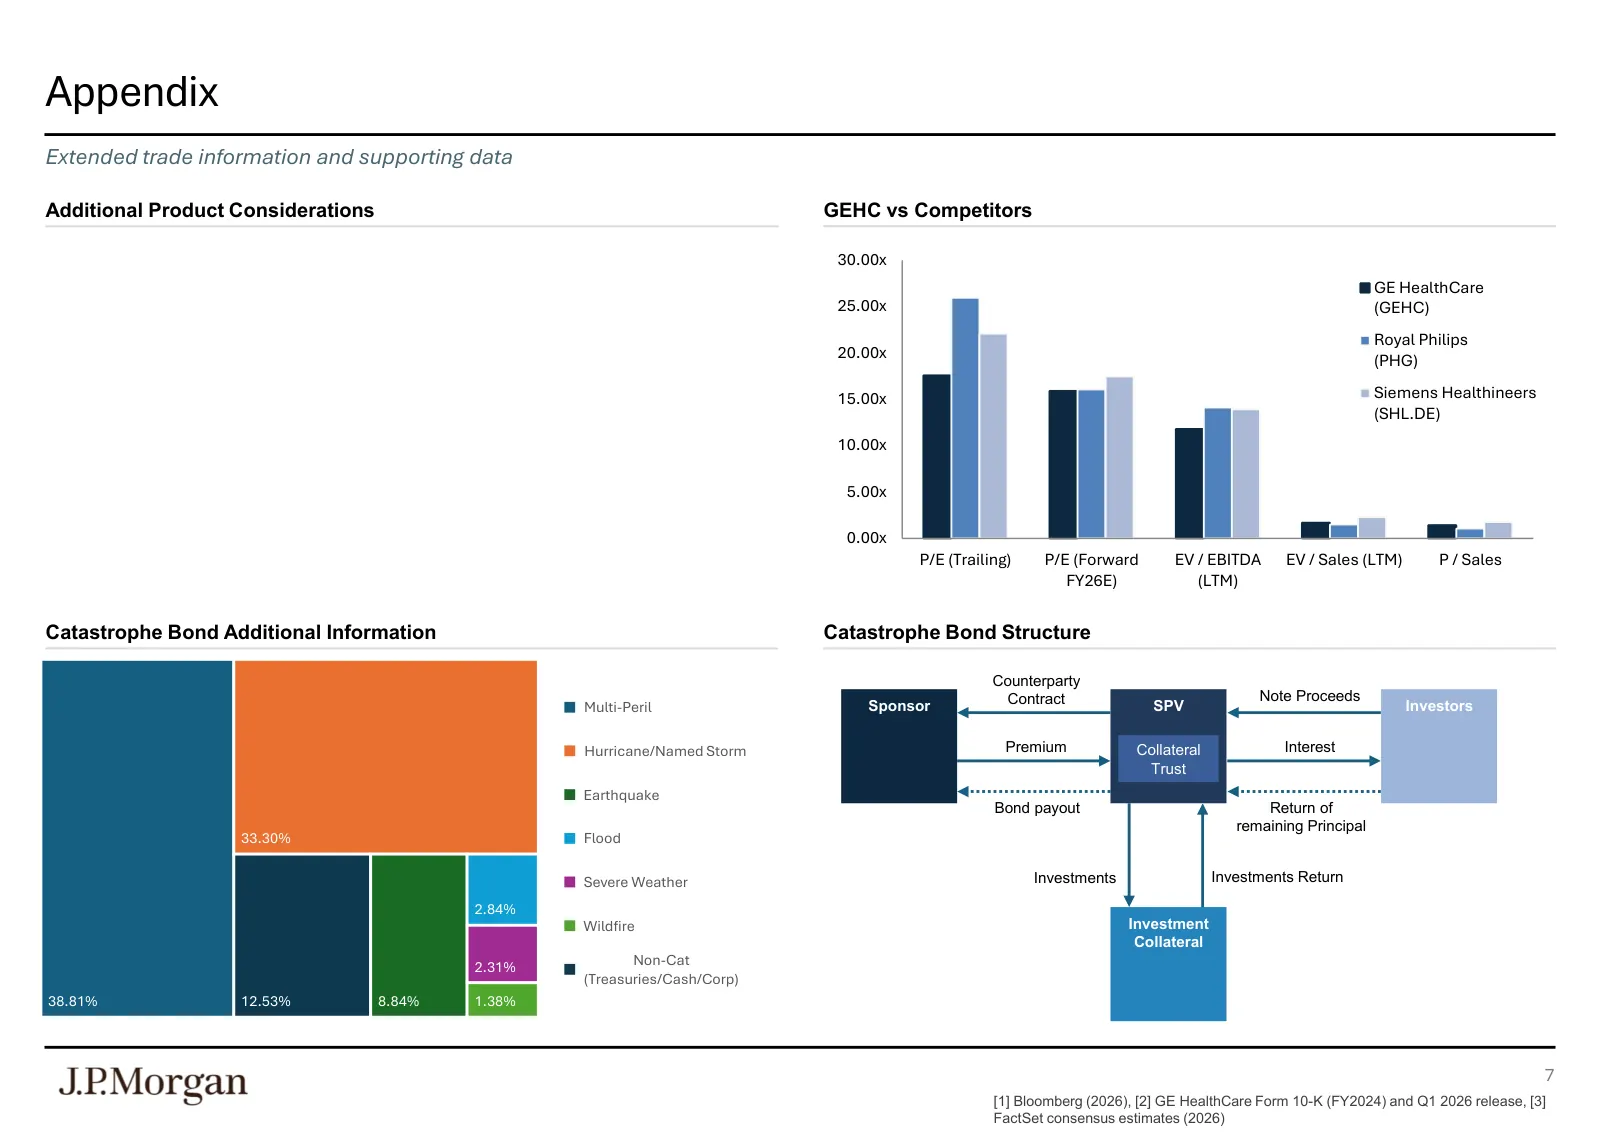
- Long the Brookmont catastrophe bond ETF, for a family office. Stocks and bonds had started moving together, and cat bond returns depend on disasters, not the Fed.
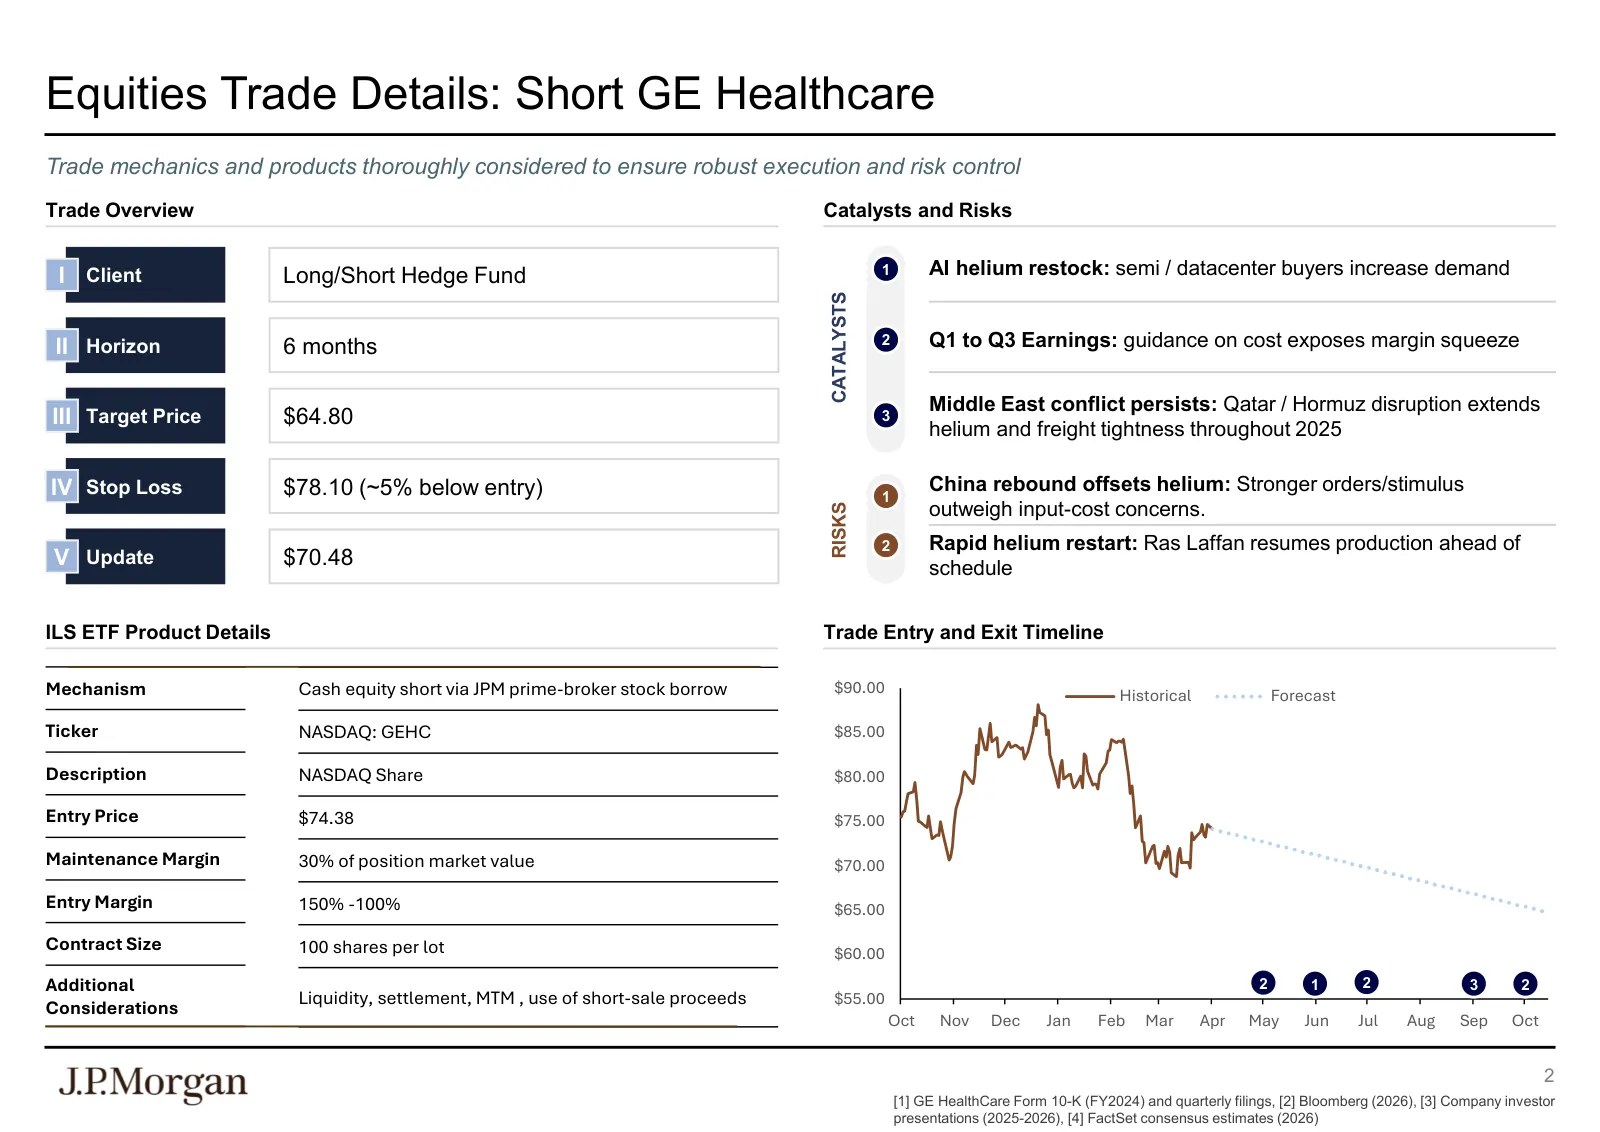
- Short GE HealthCare, for a long/short fund. The strike on Ras Laffan took out about 30% of the world's medical-grade helium supply.
Hedging
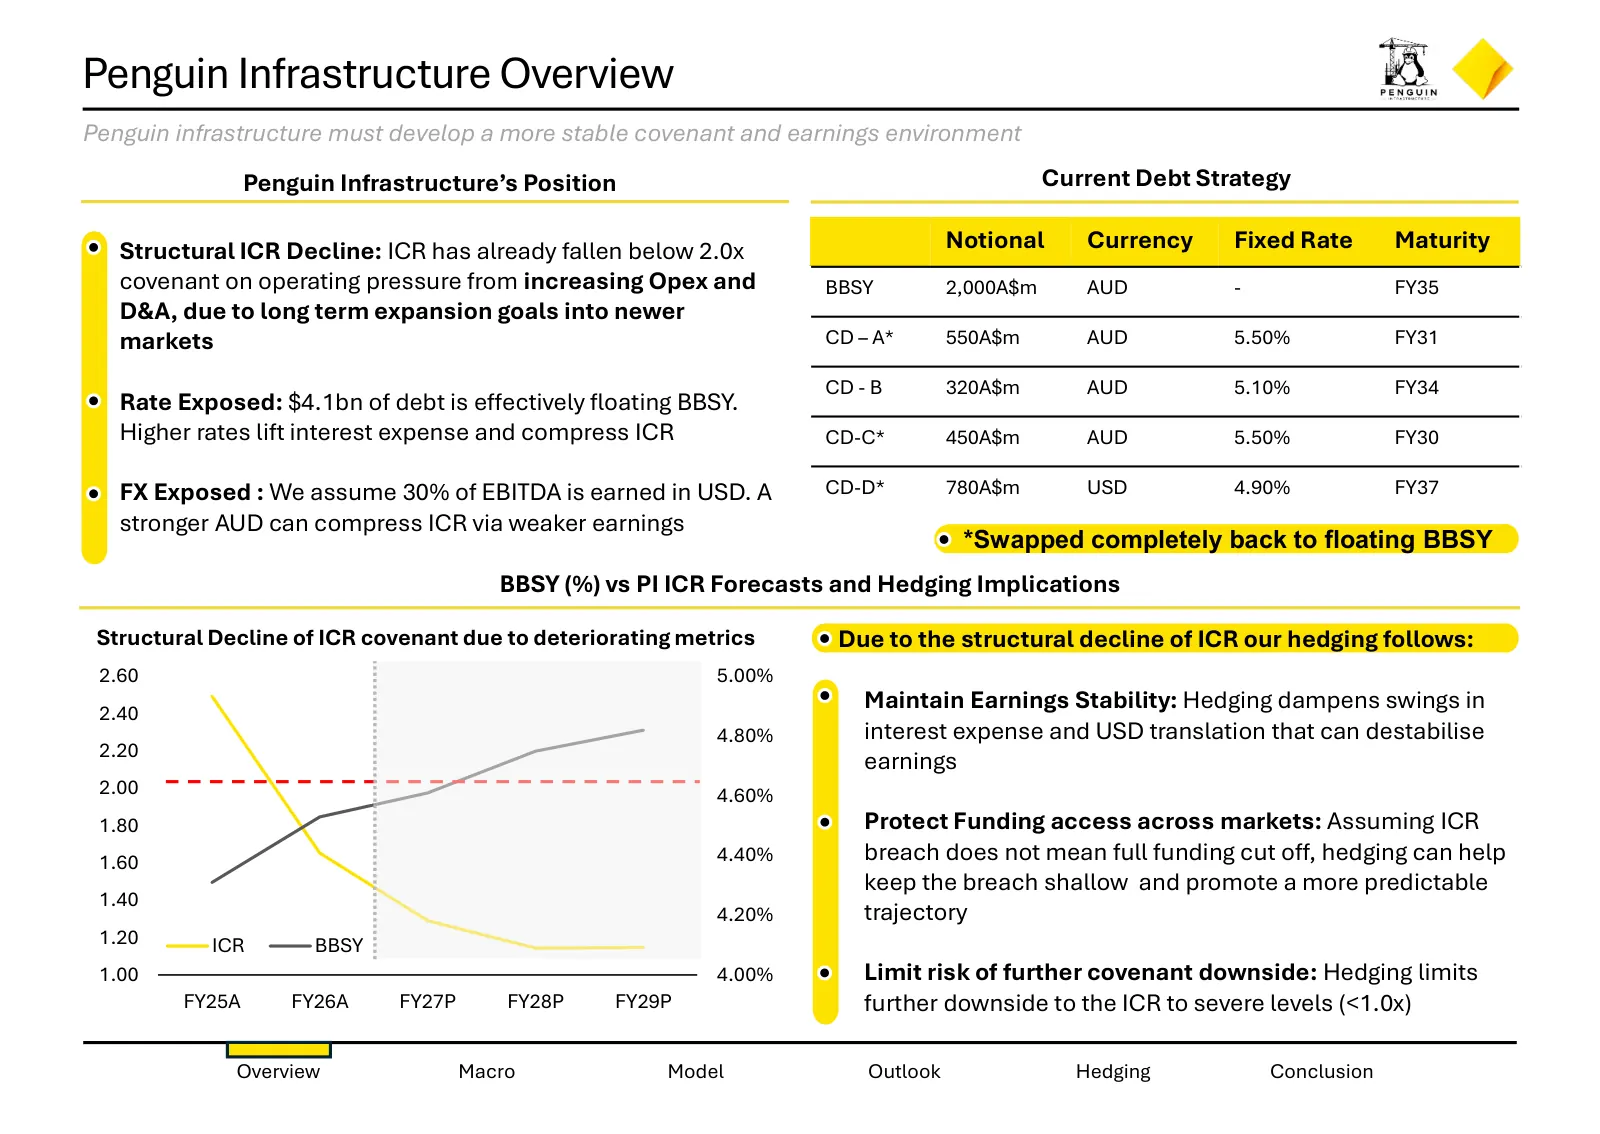
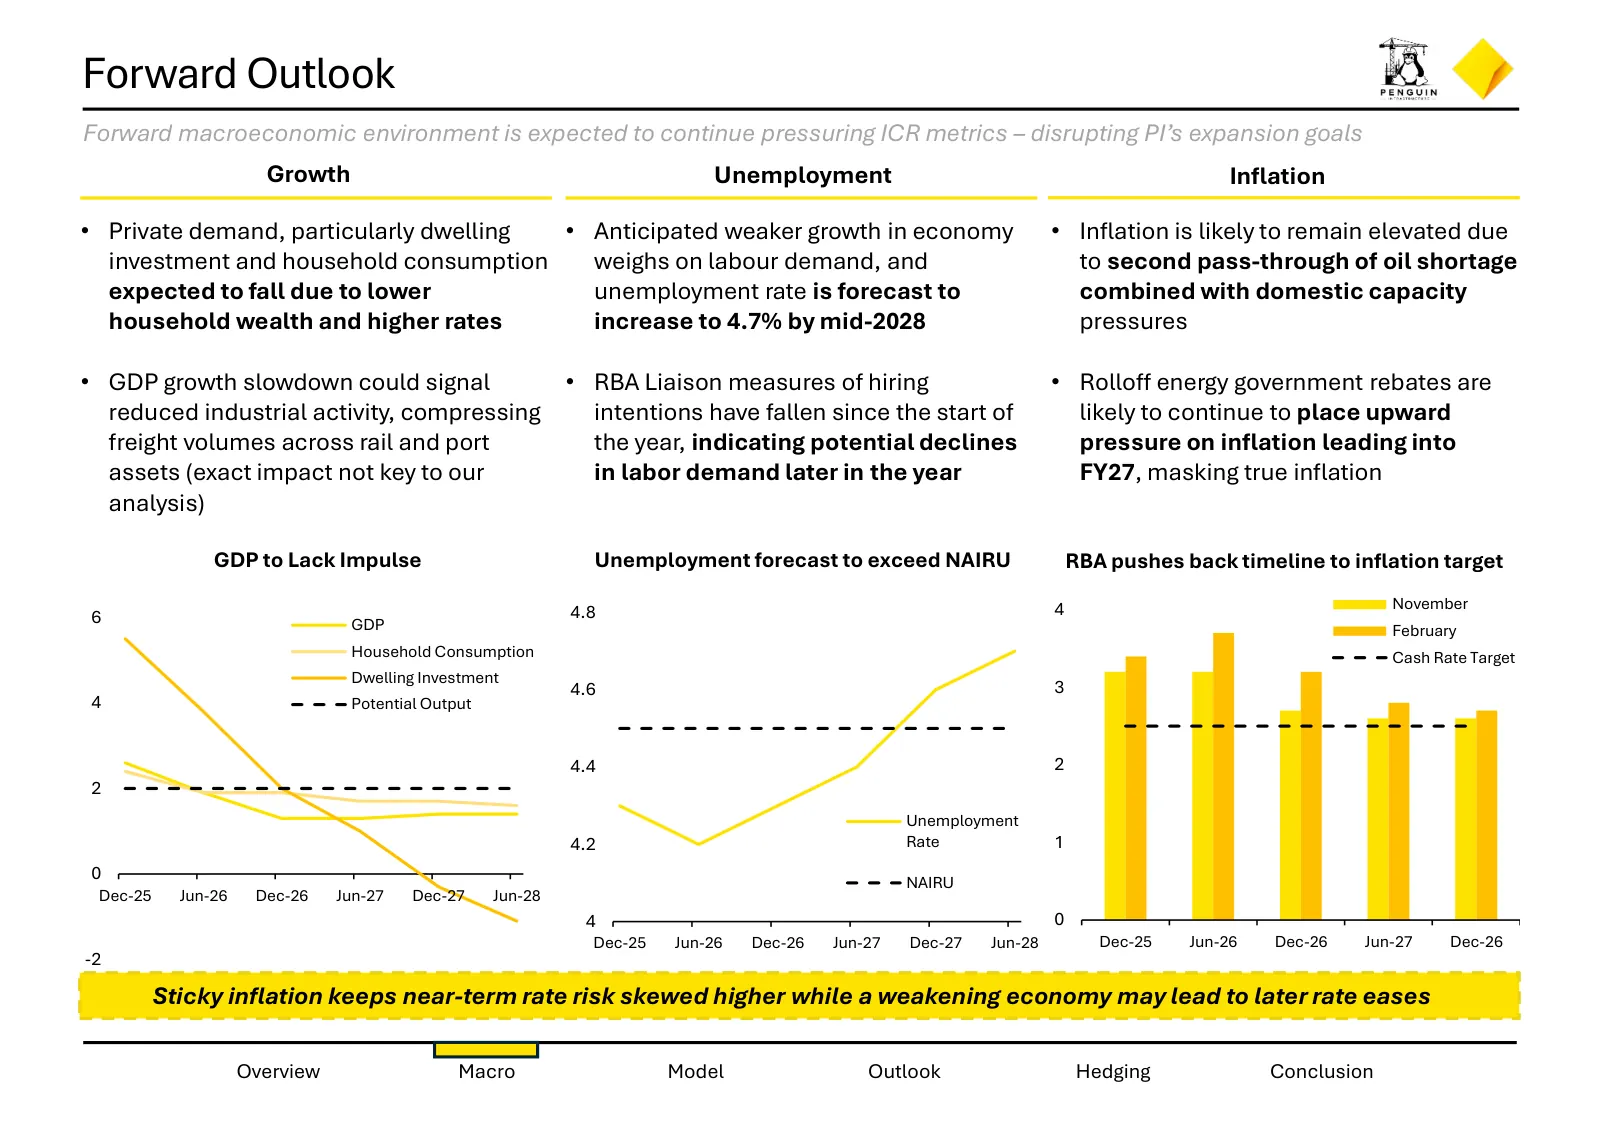
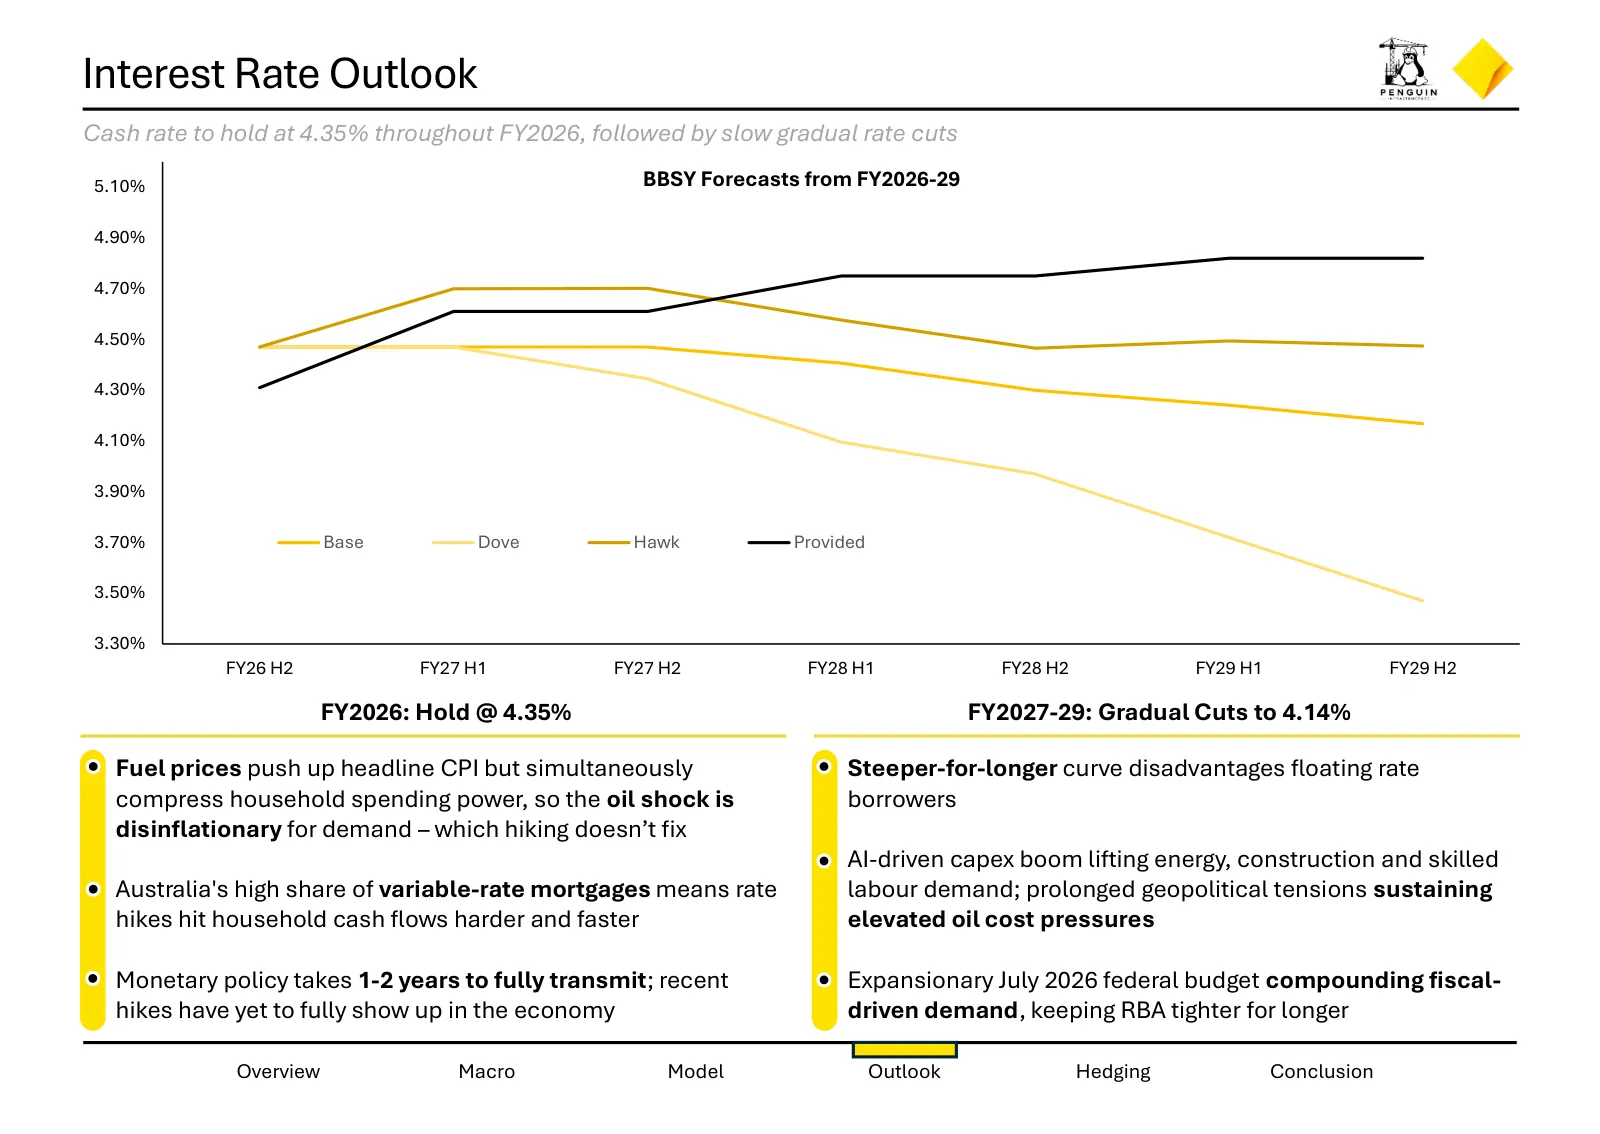
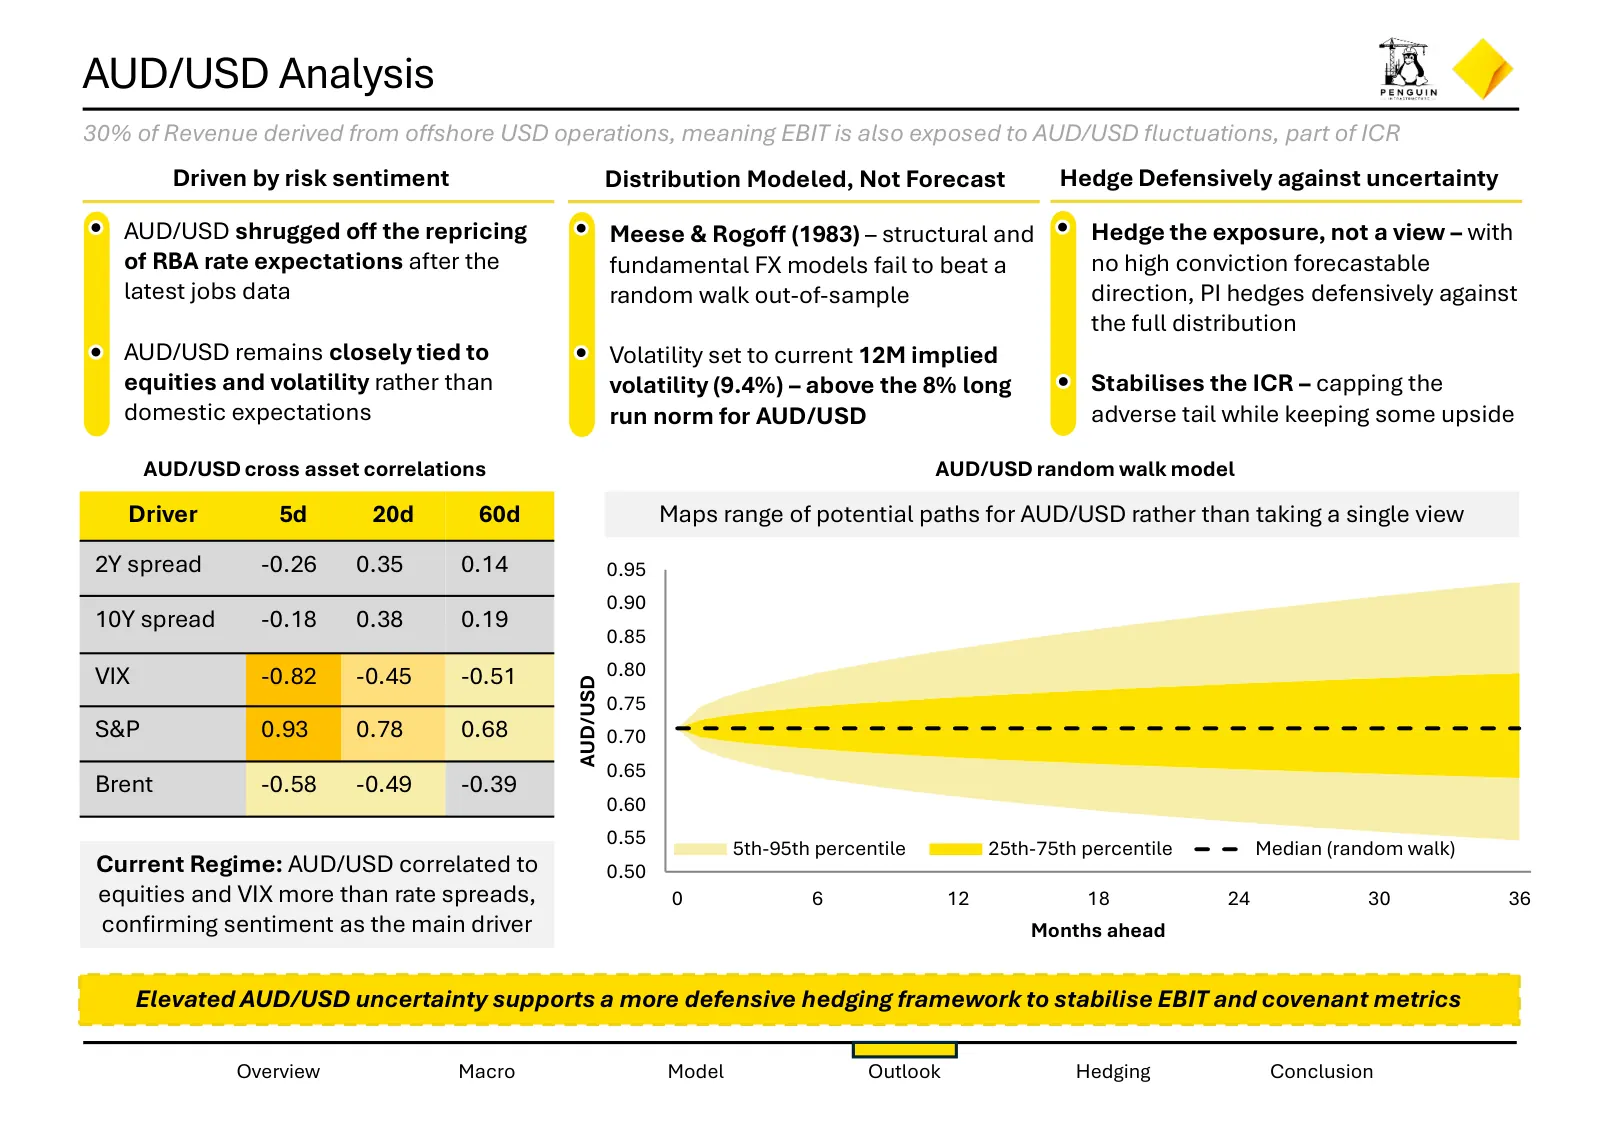
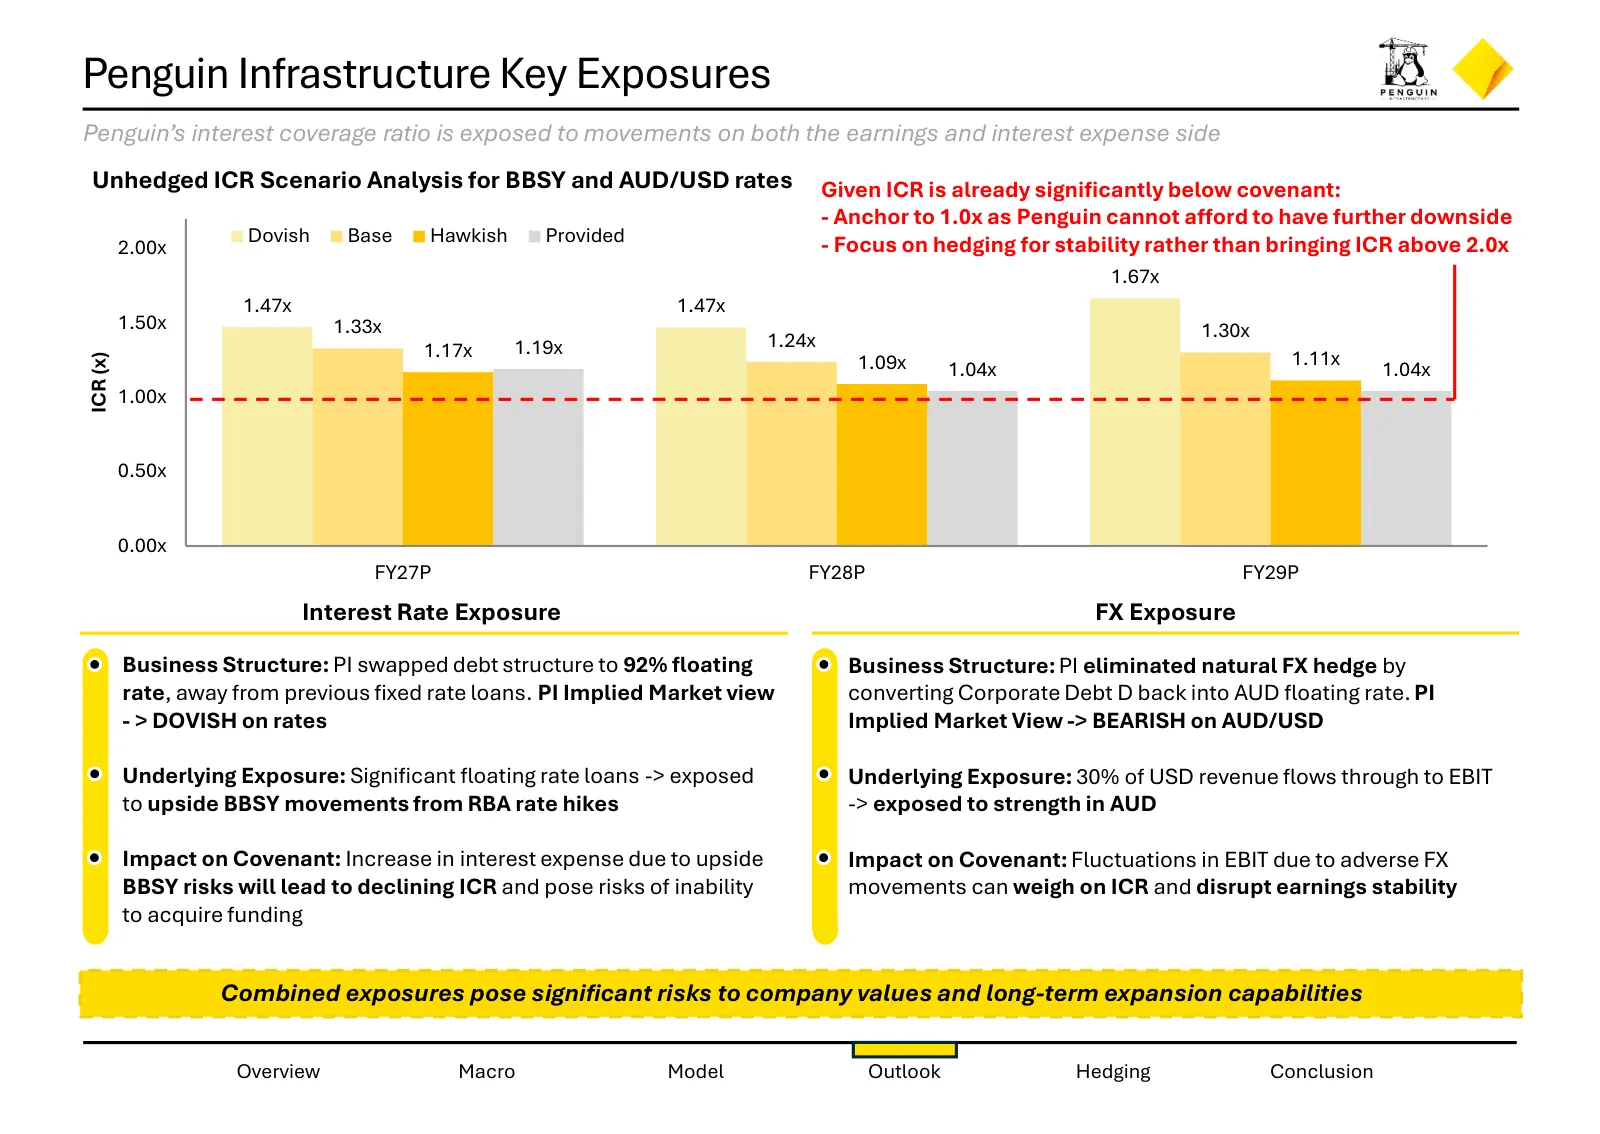
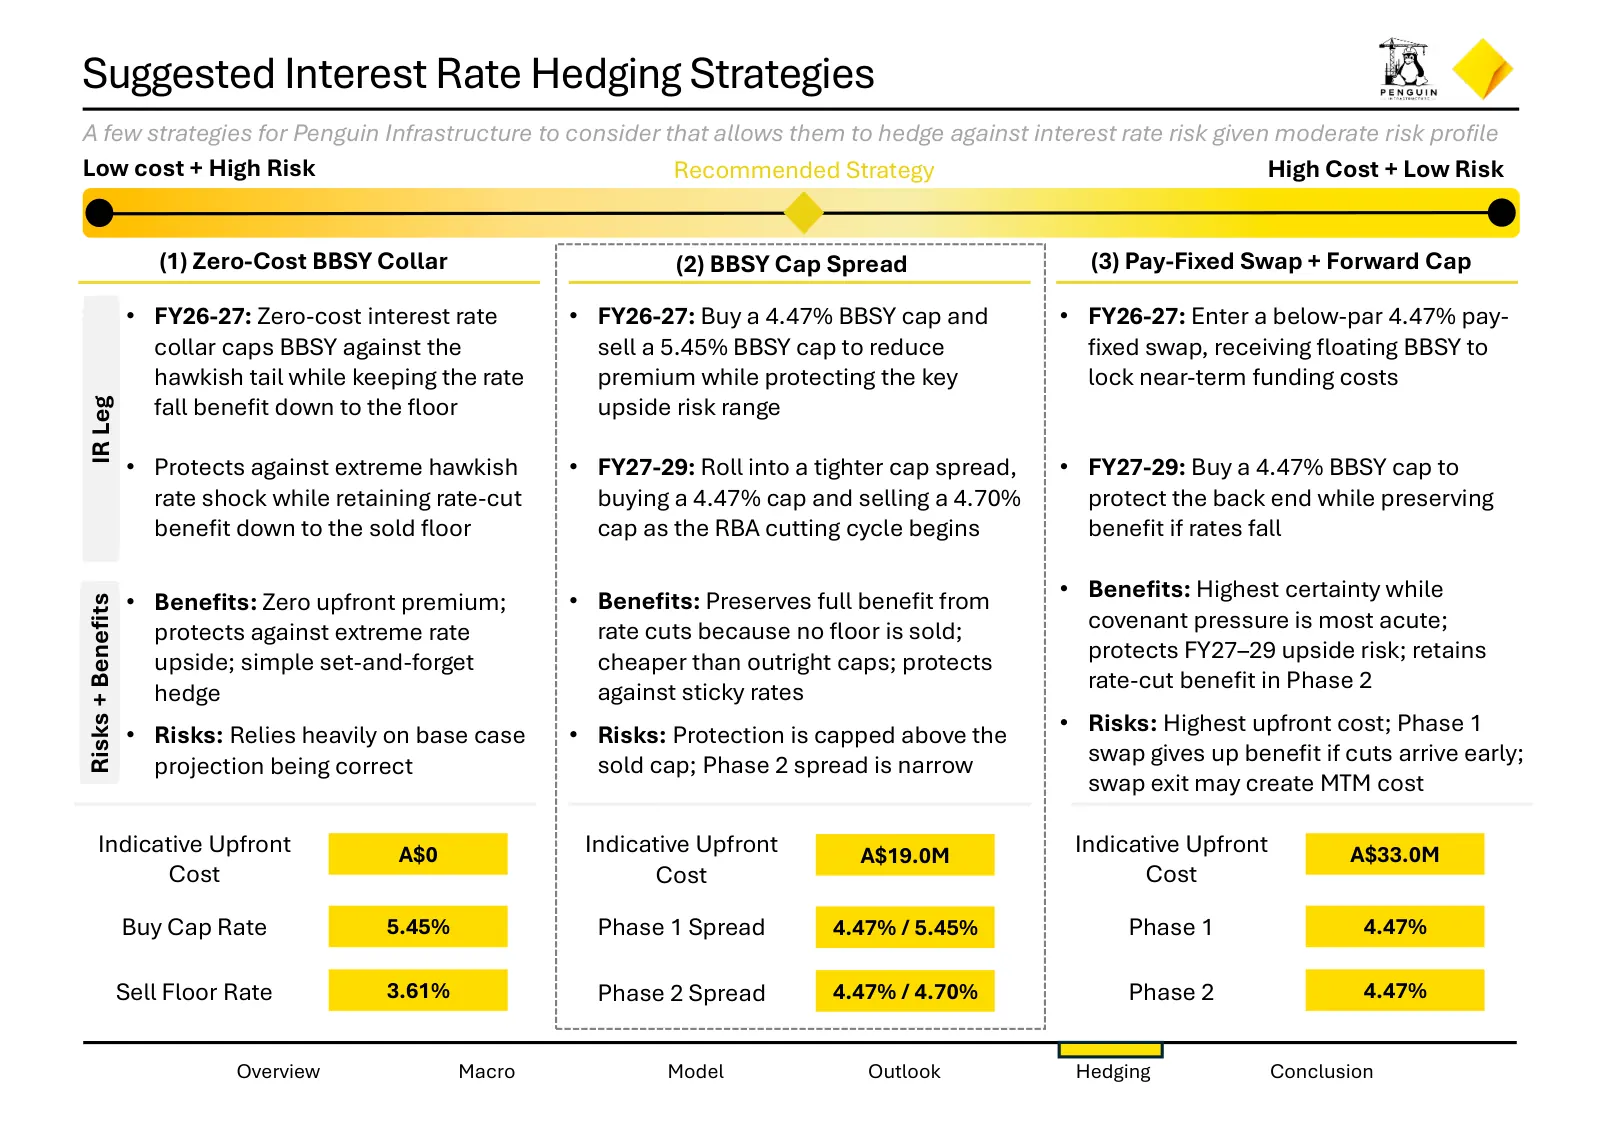
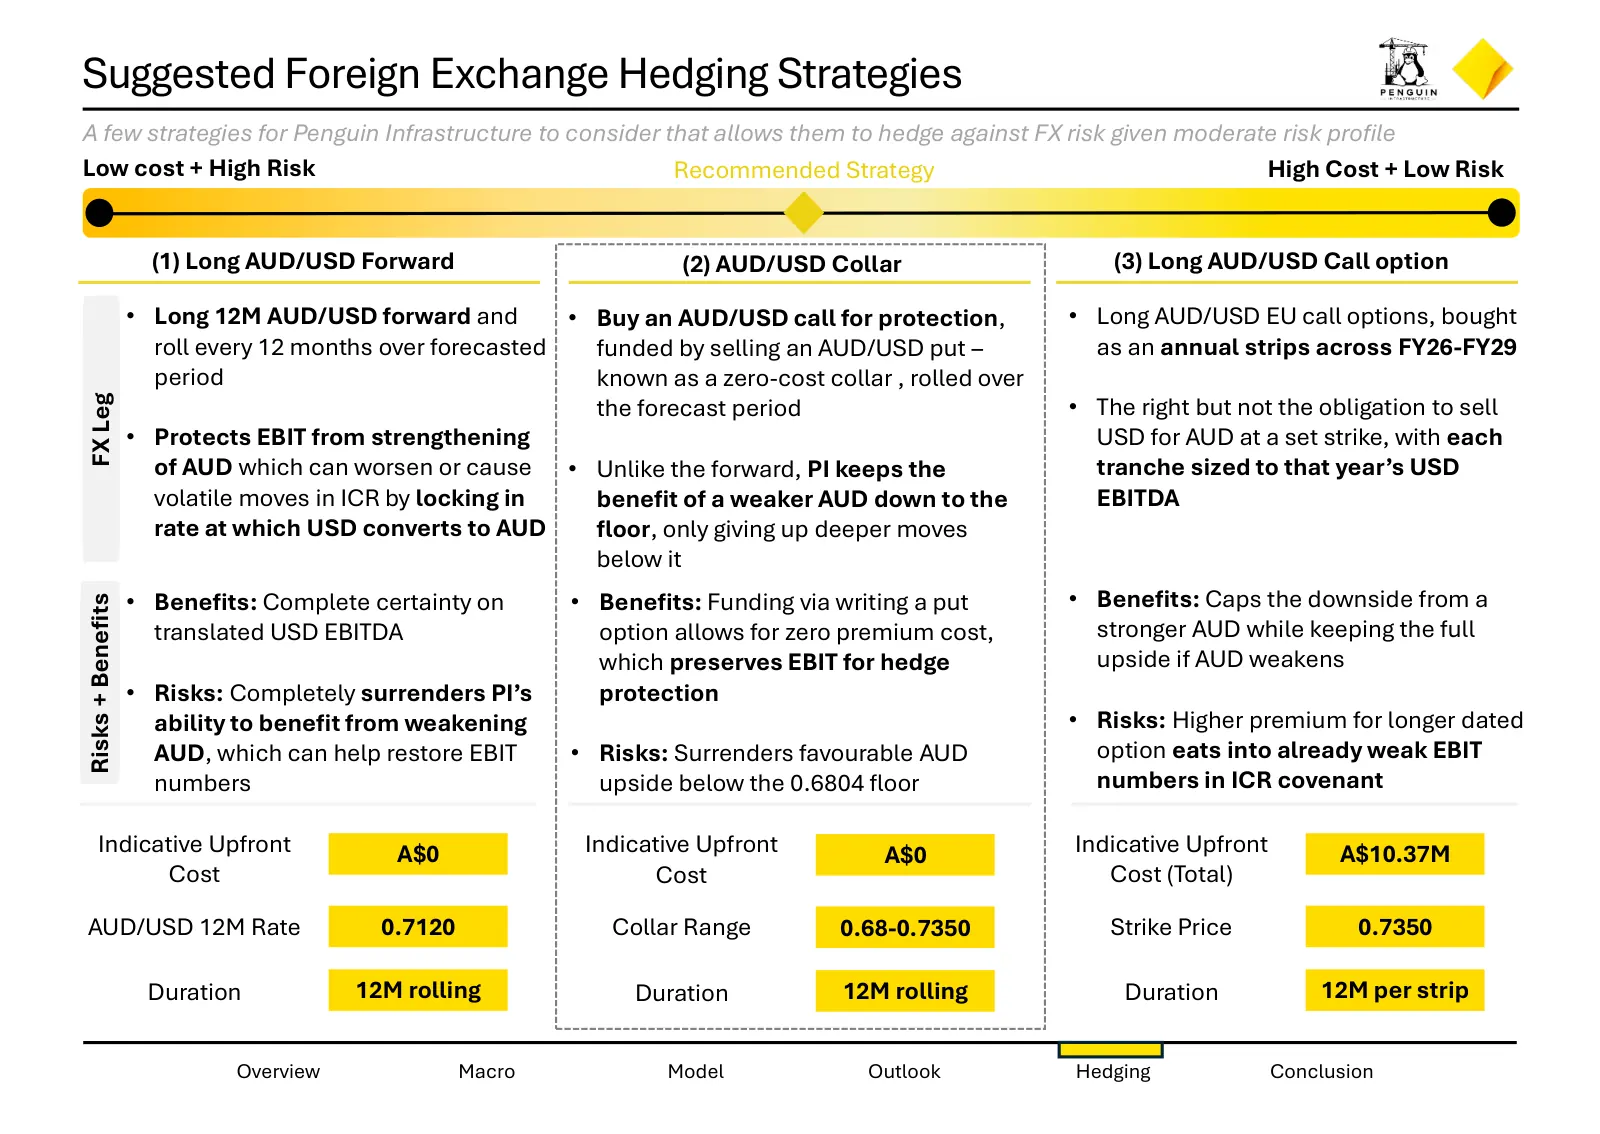
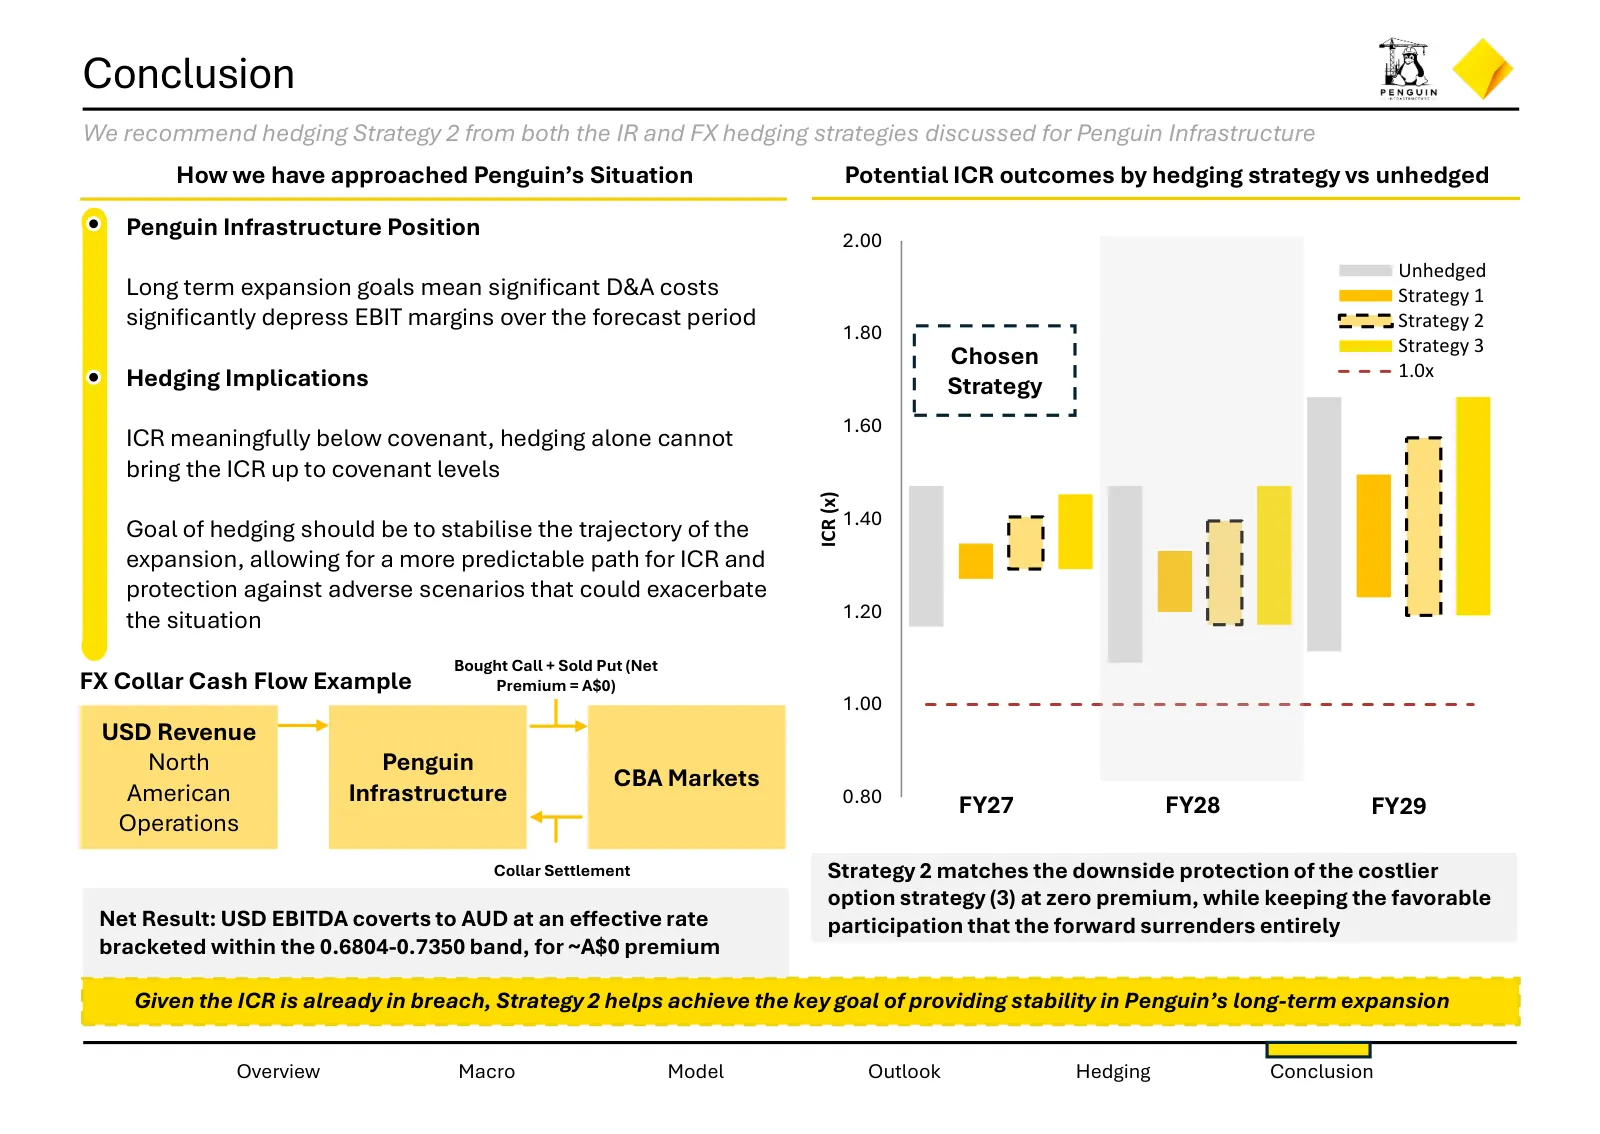
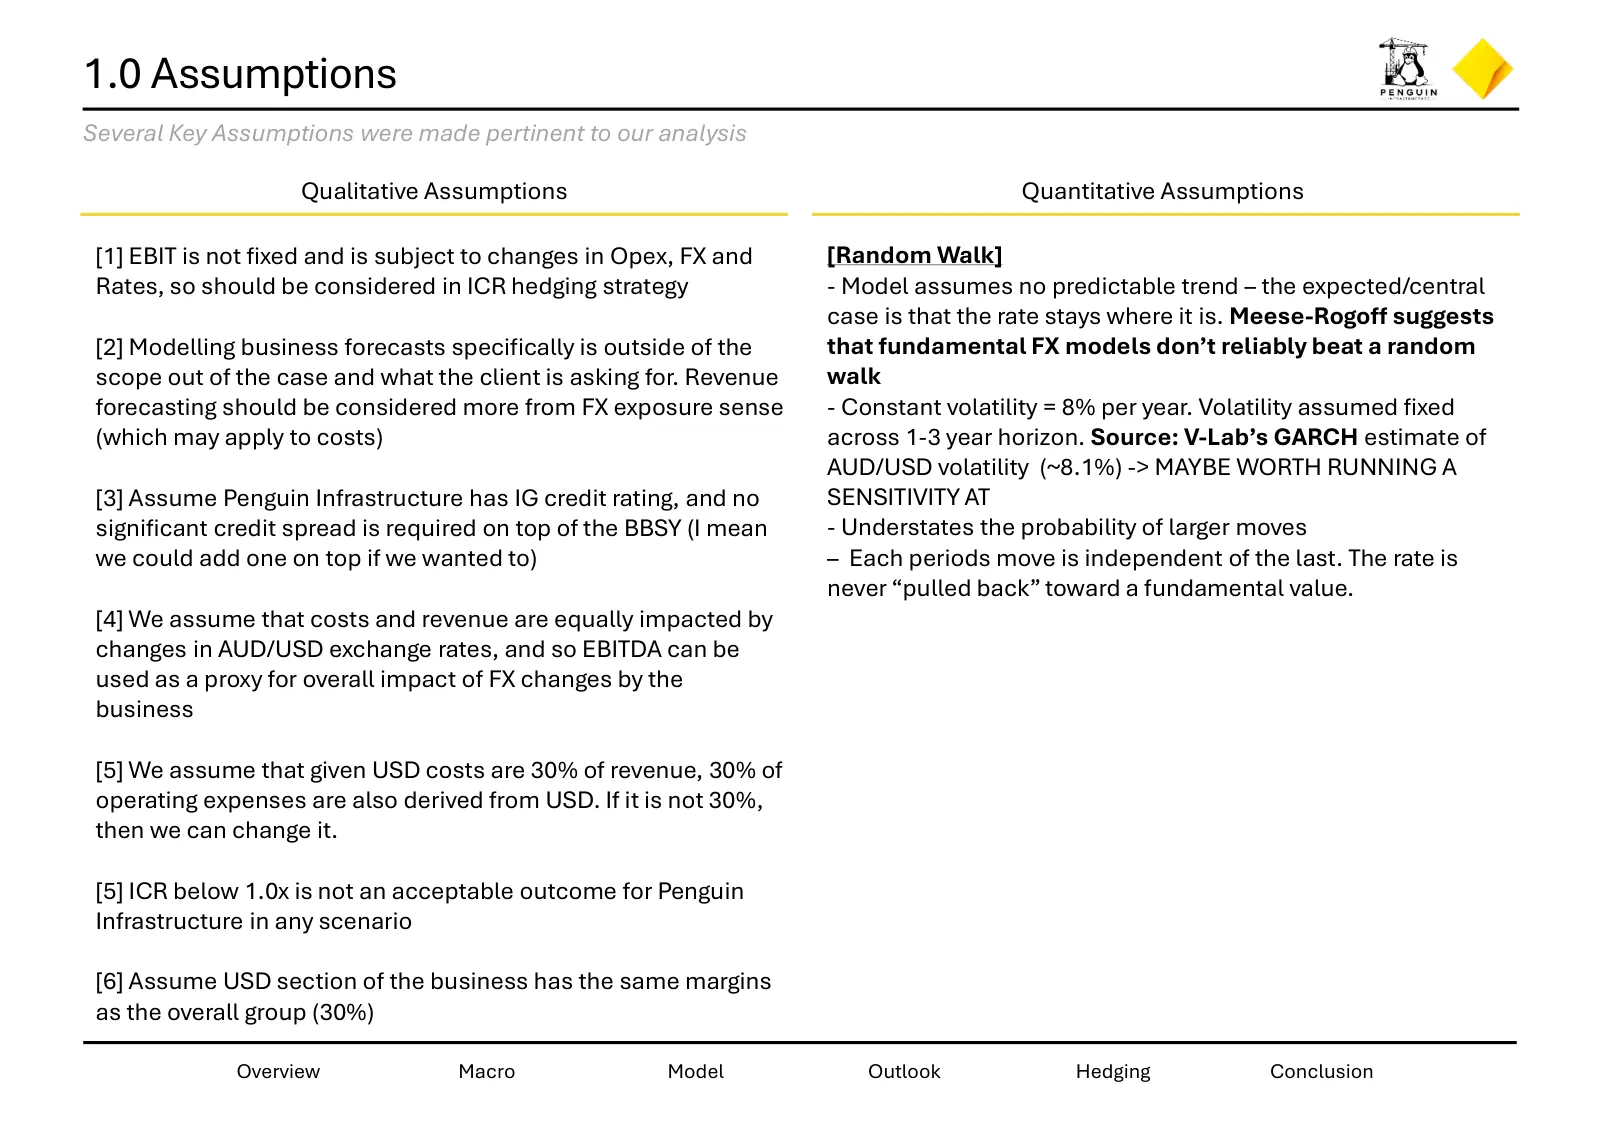
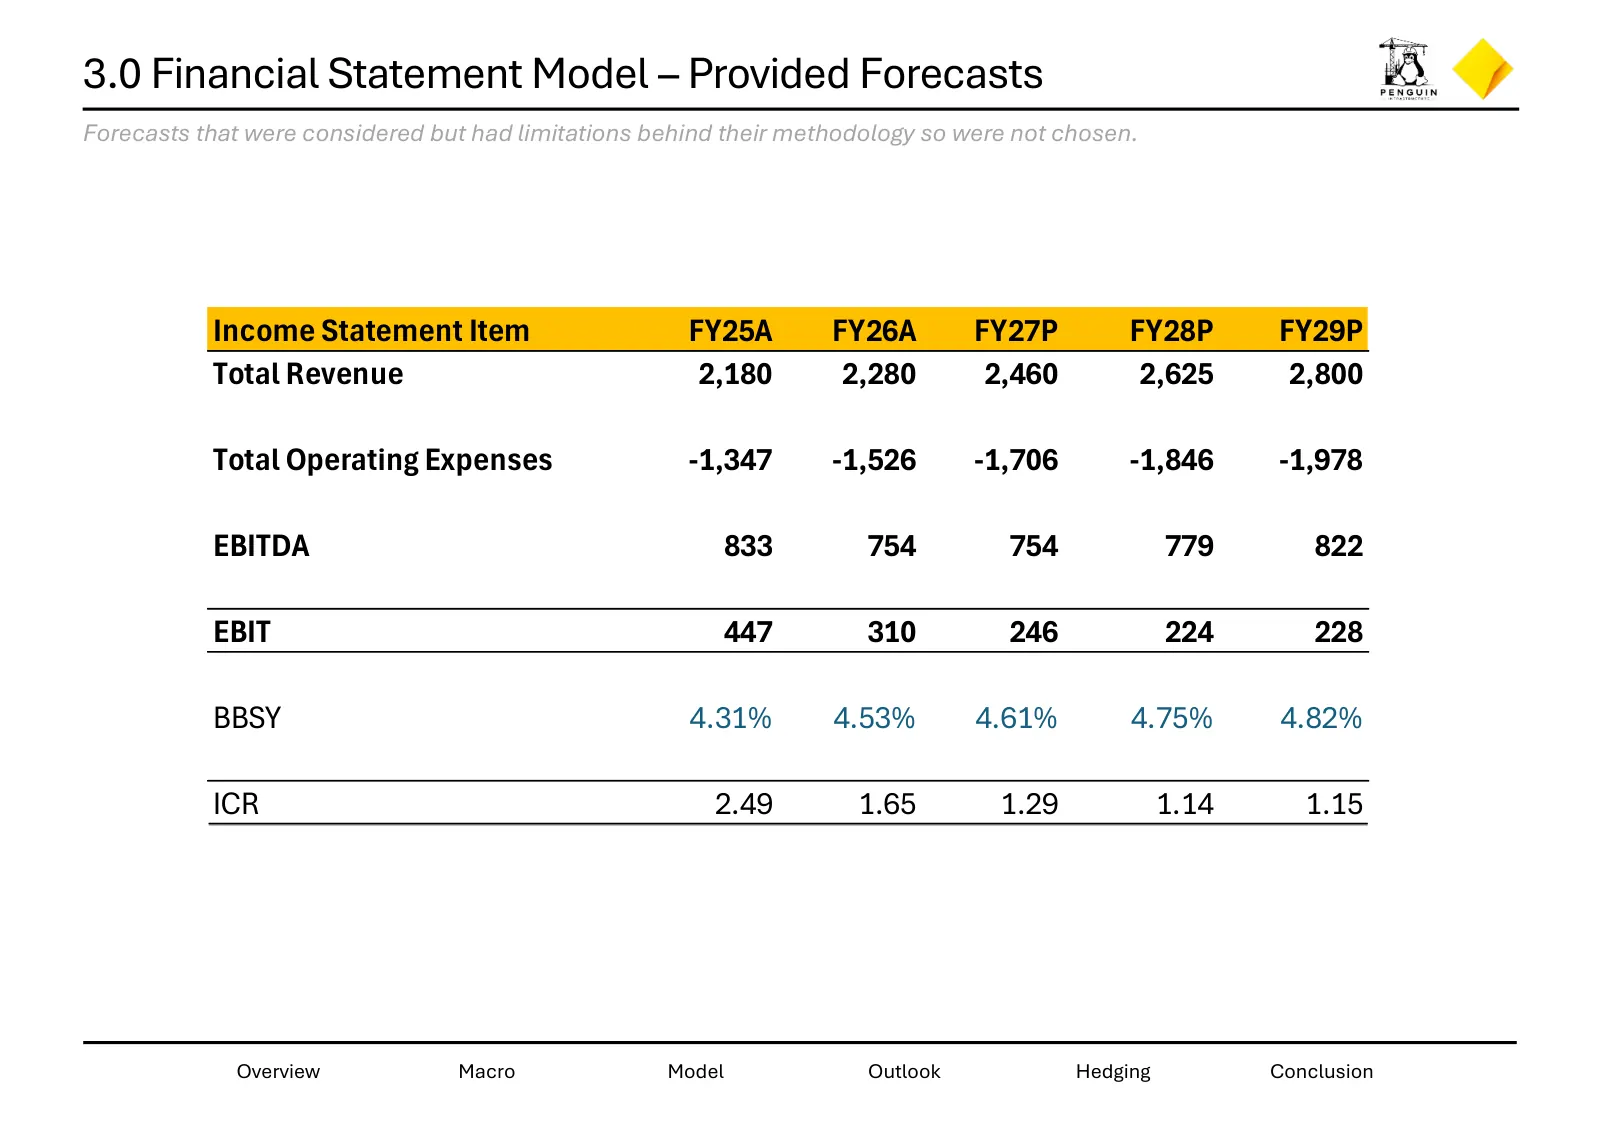
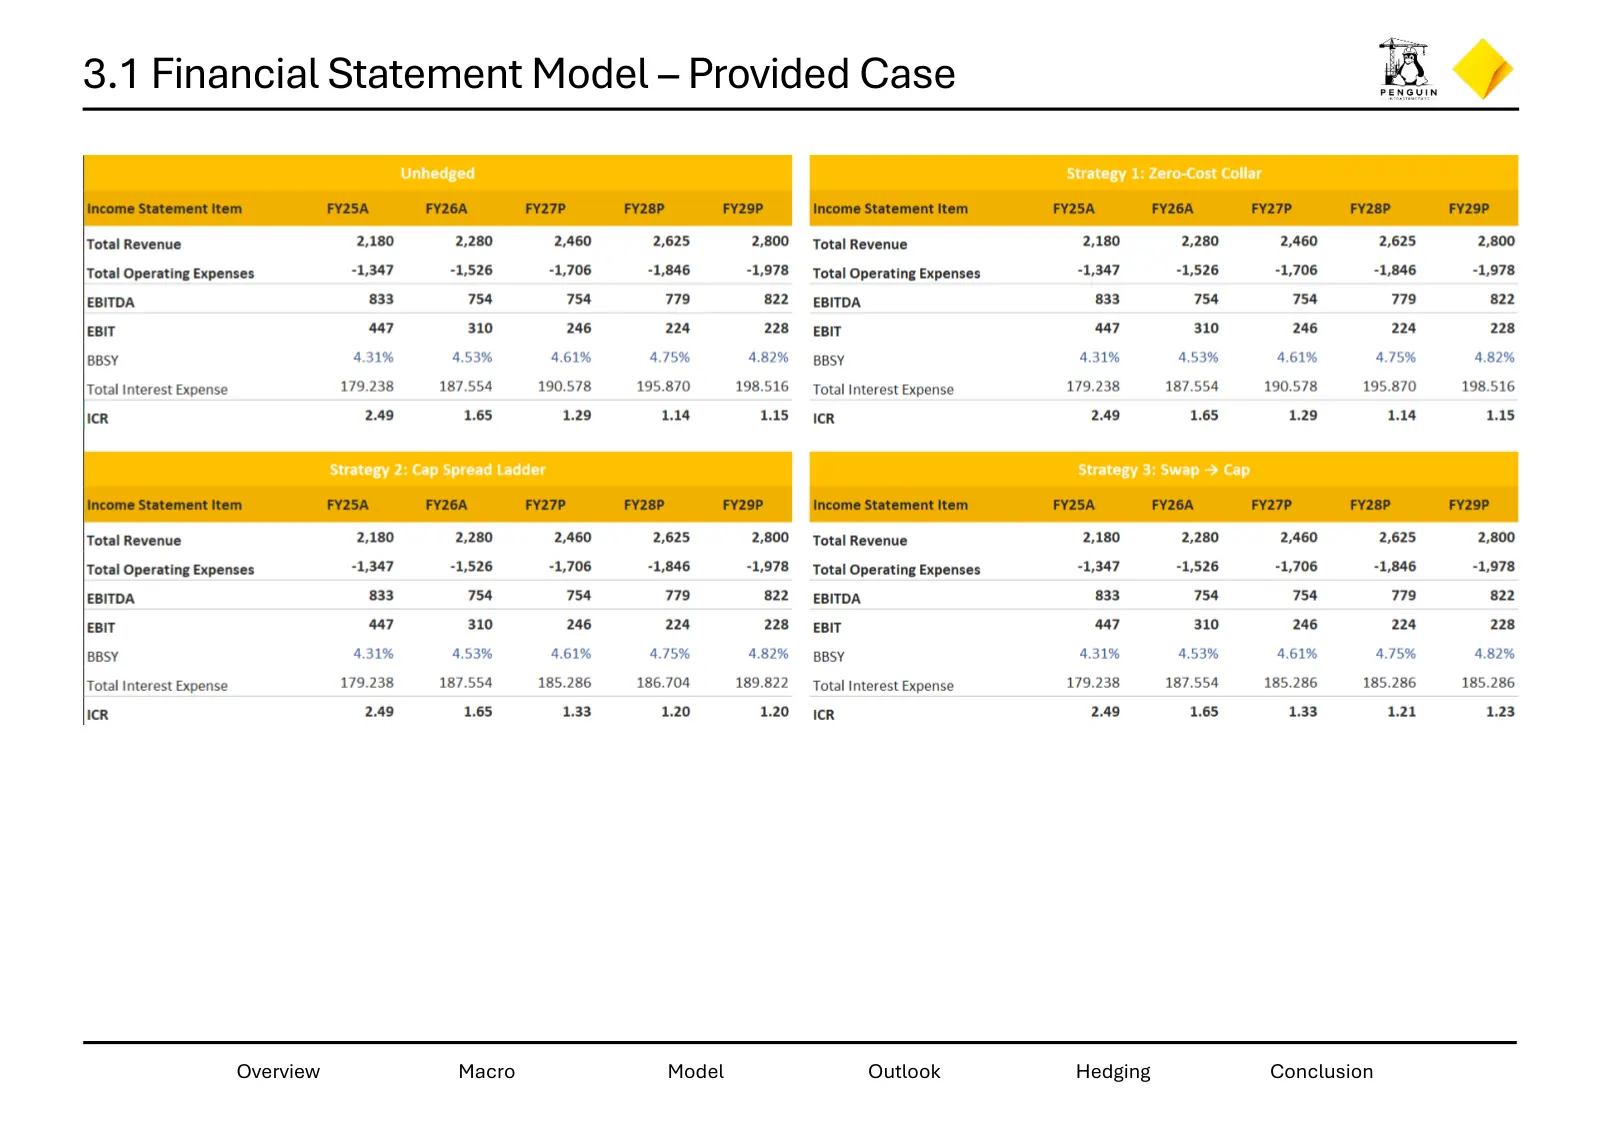
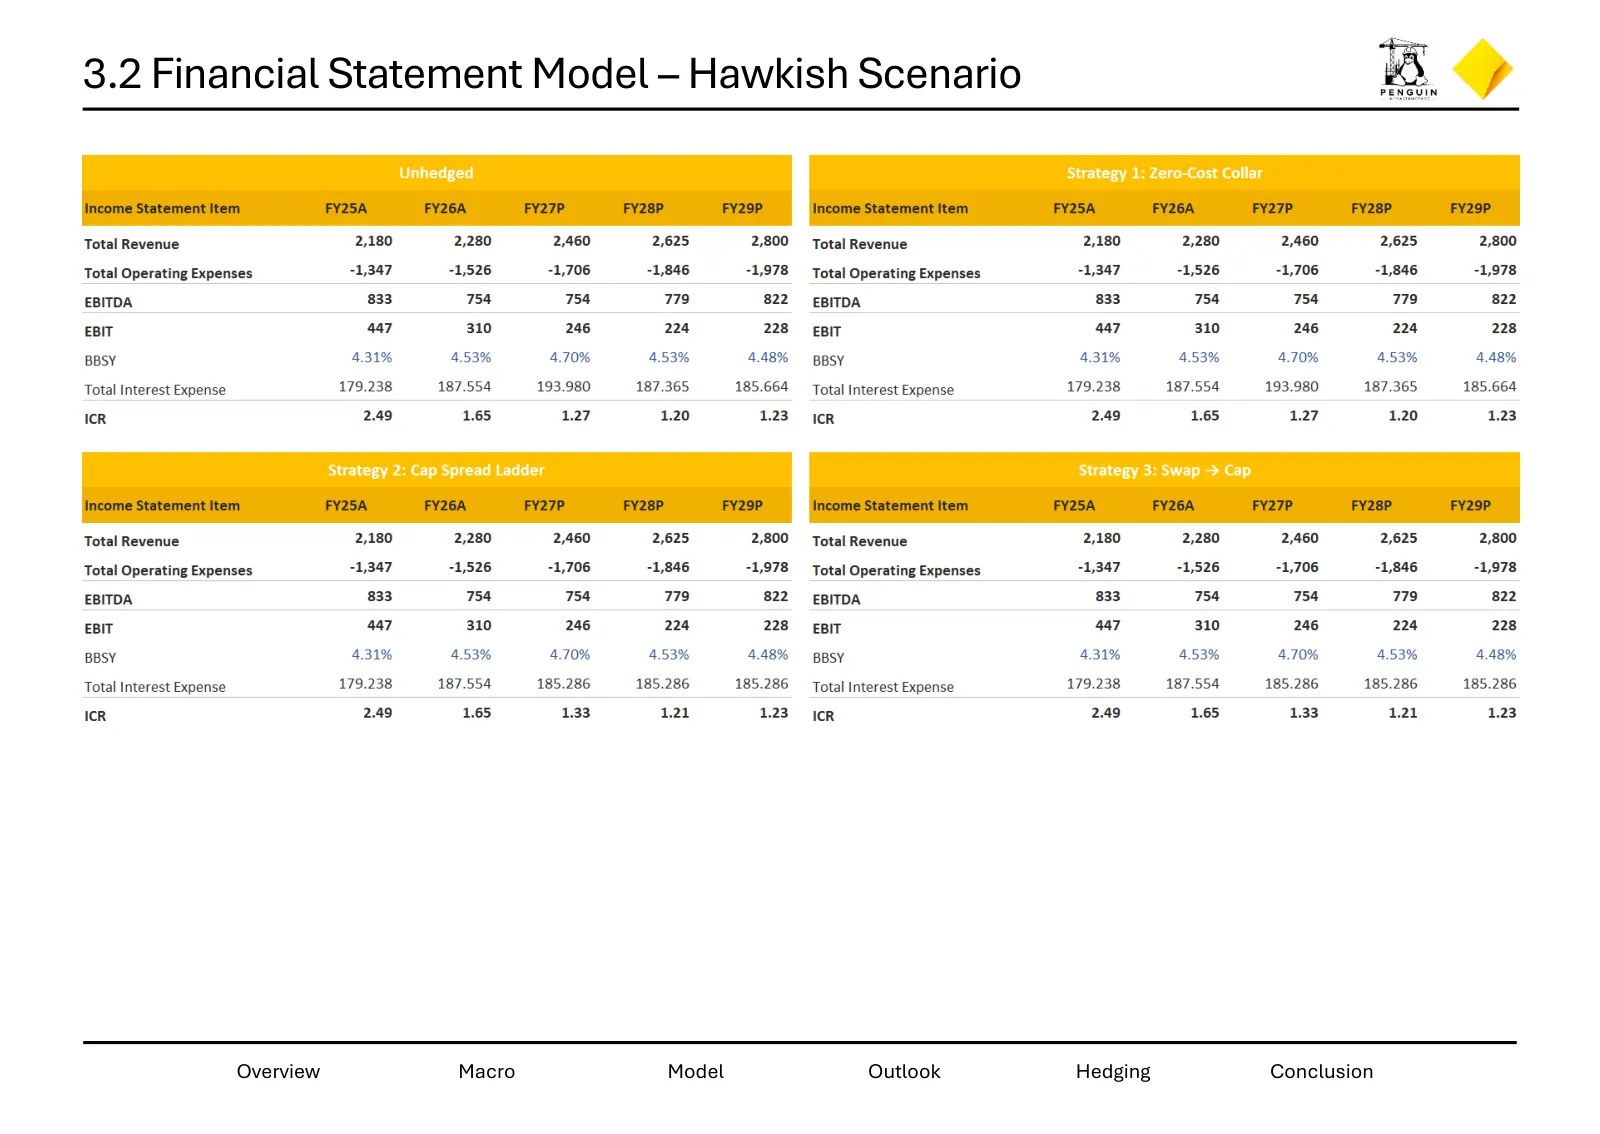
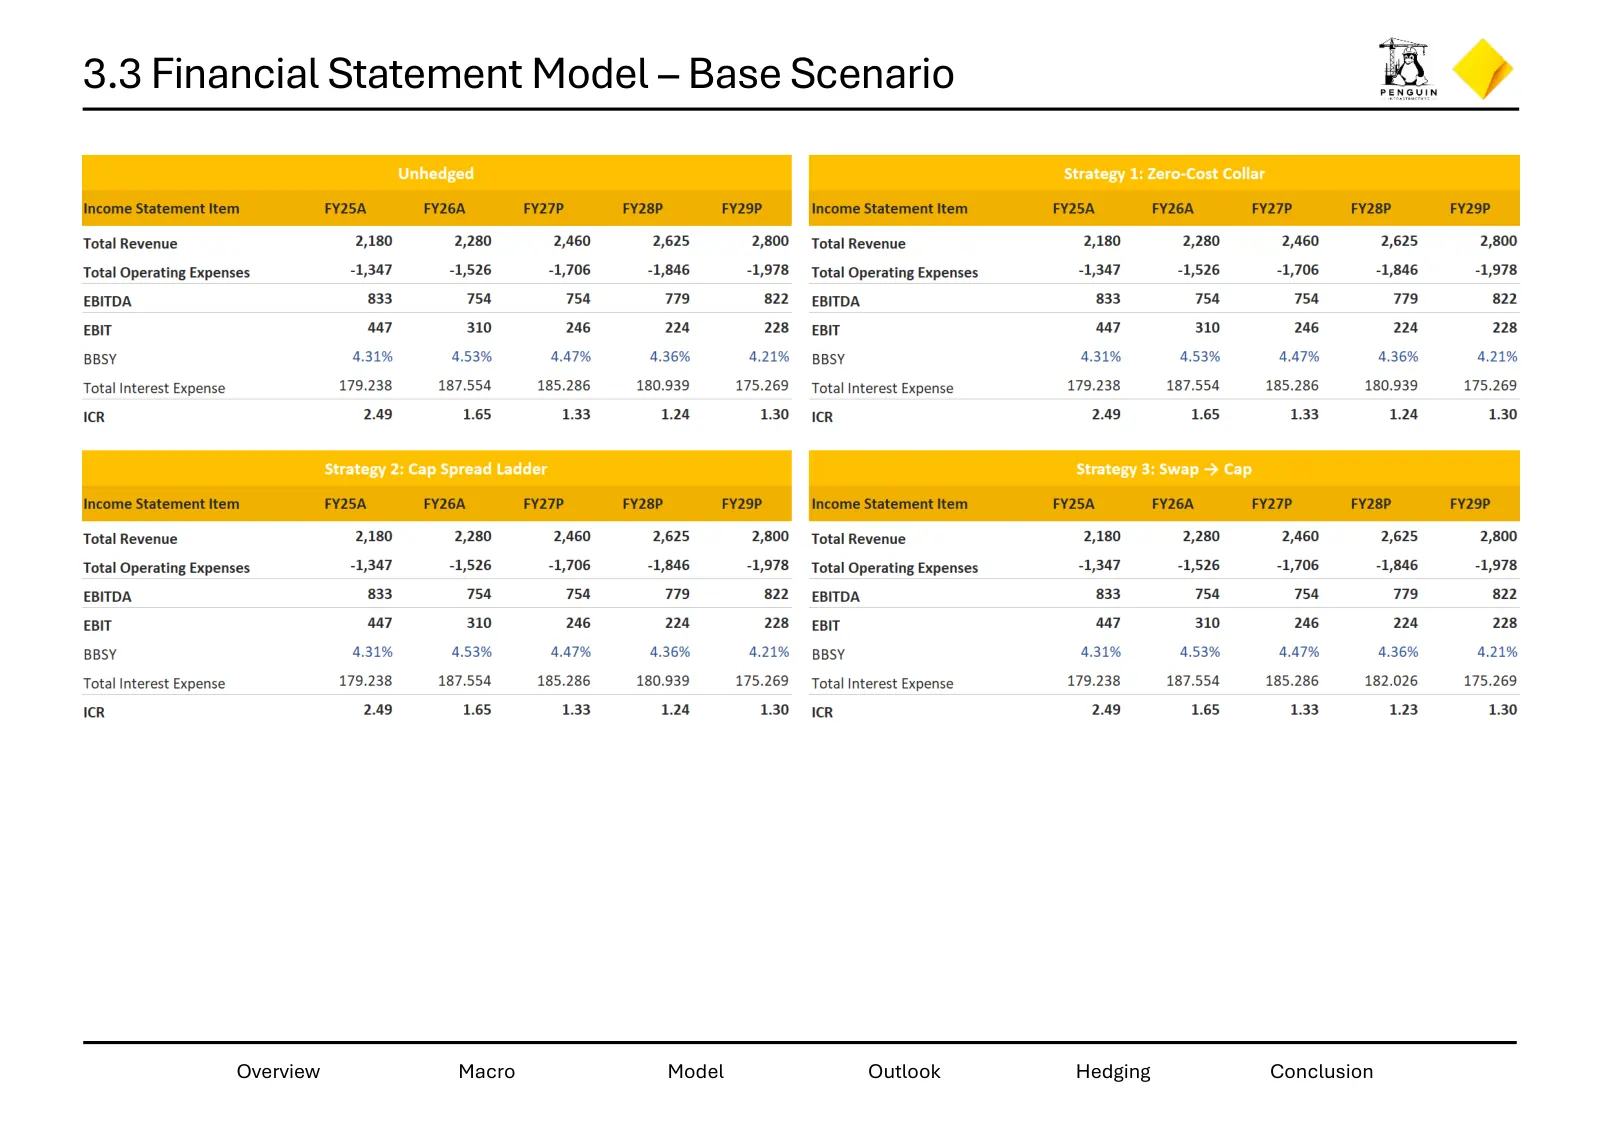
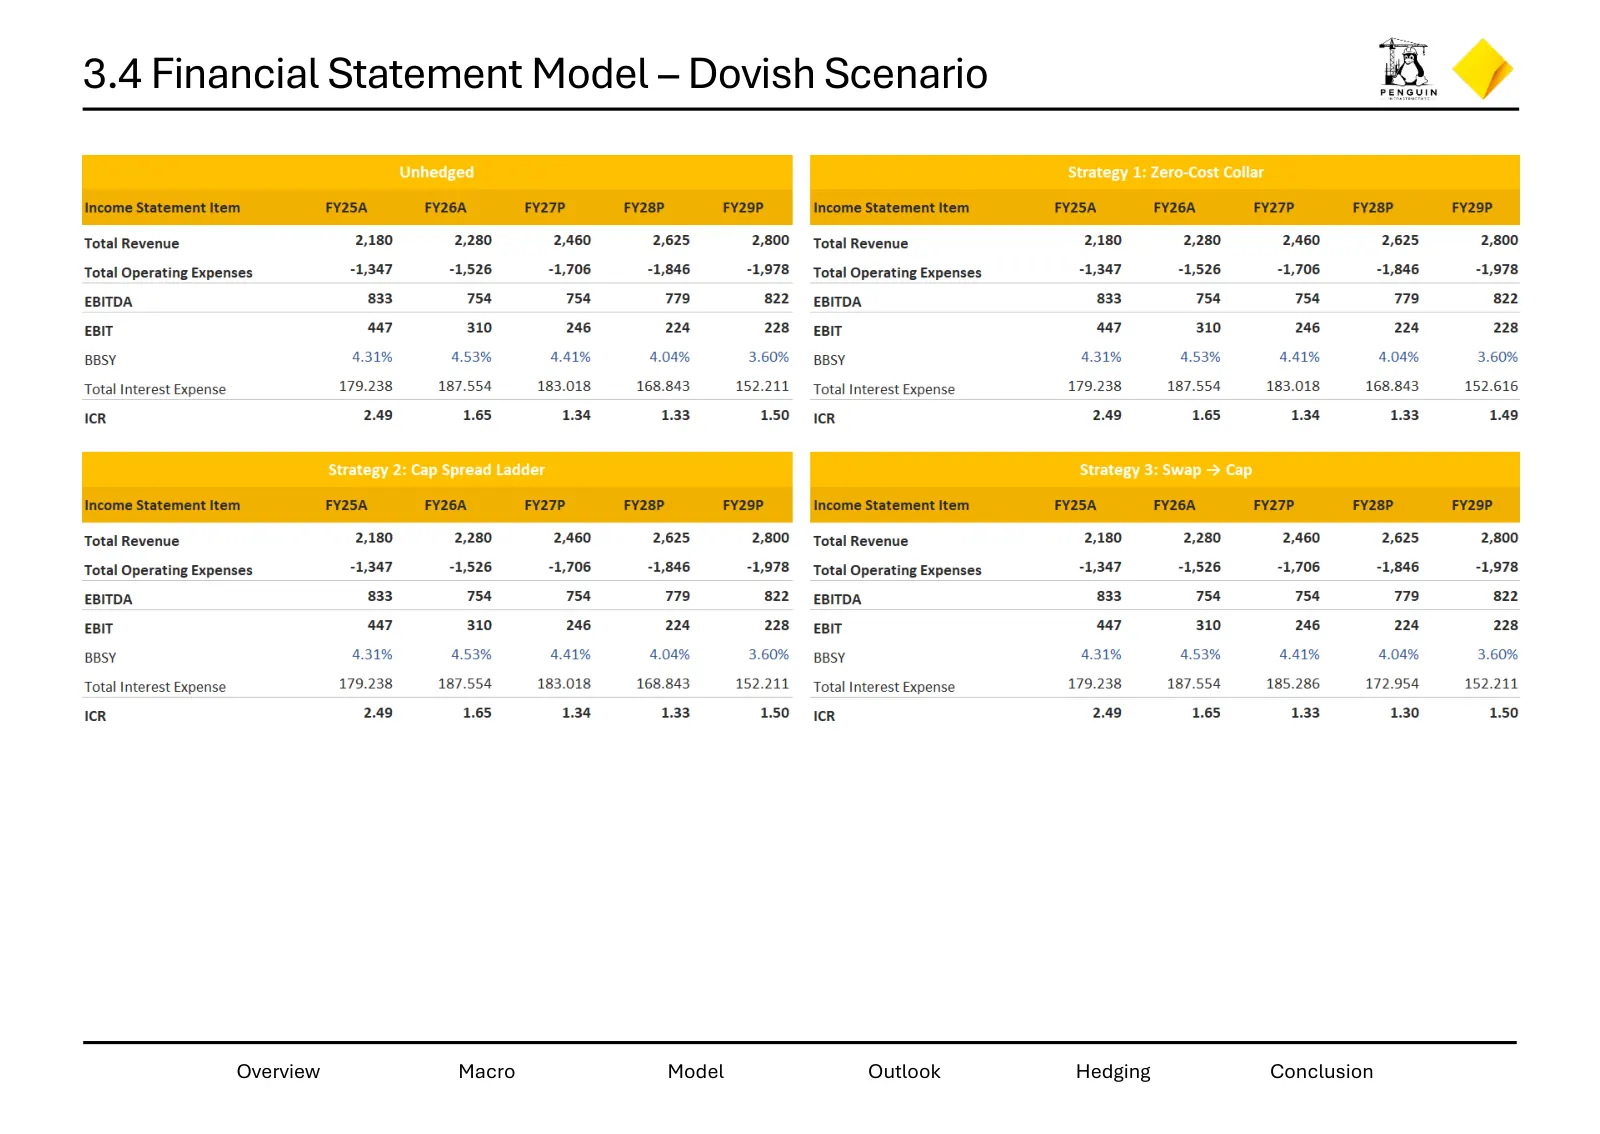
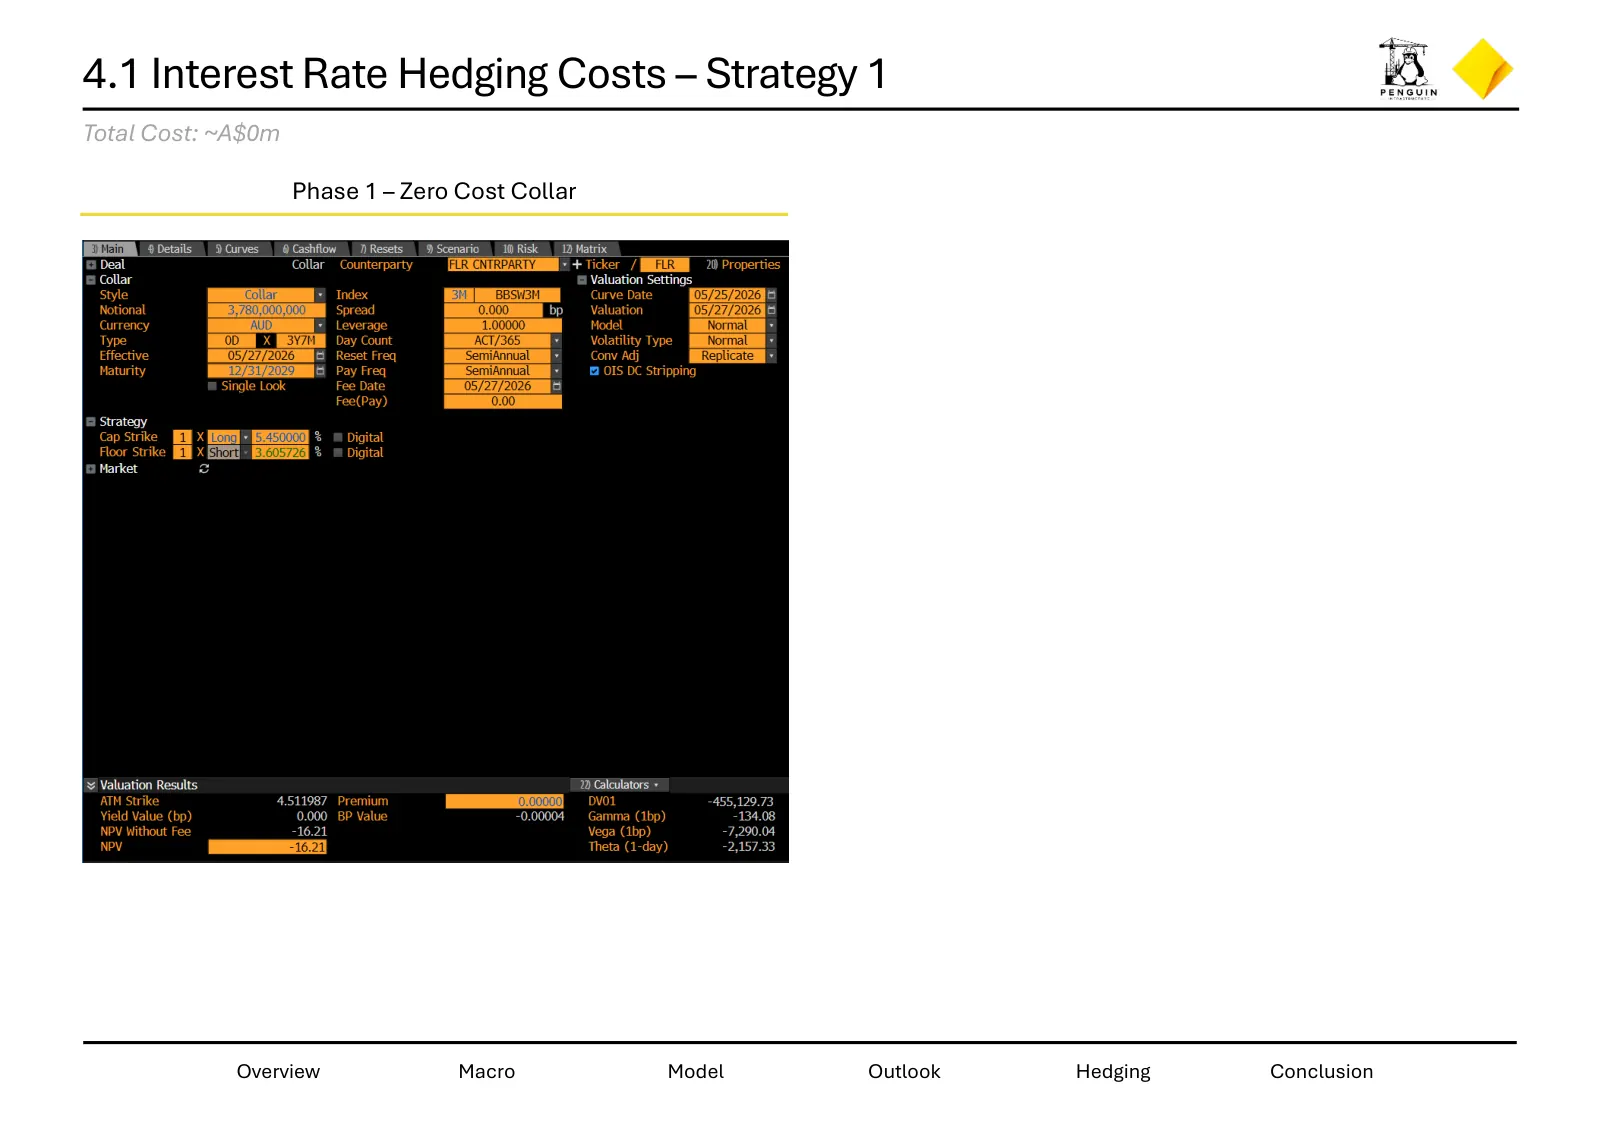
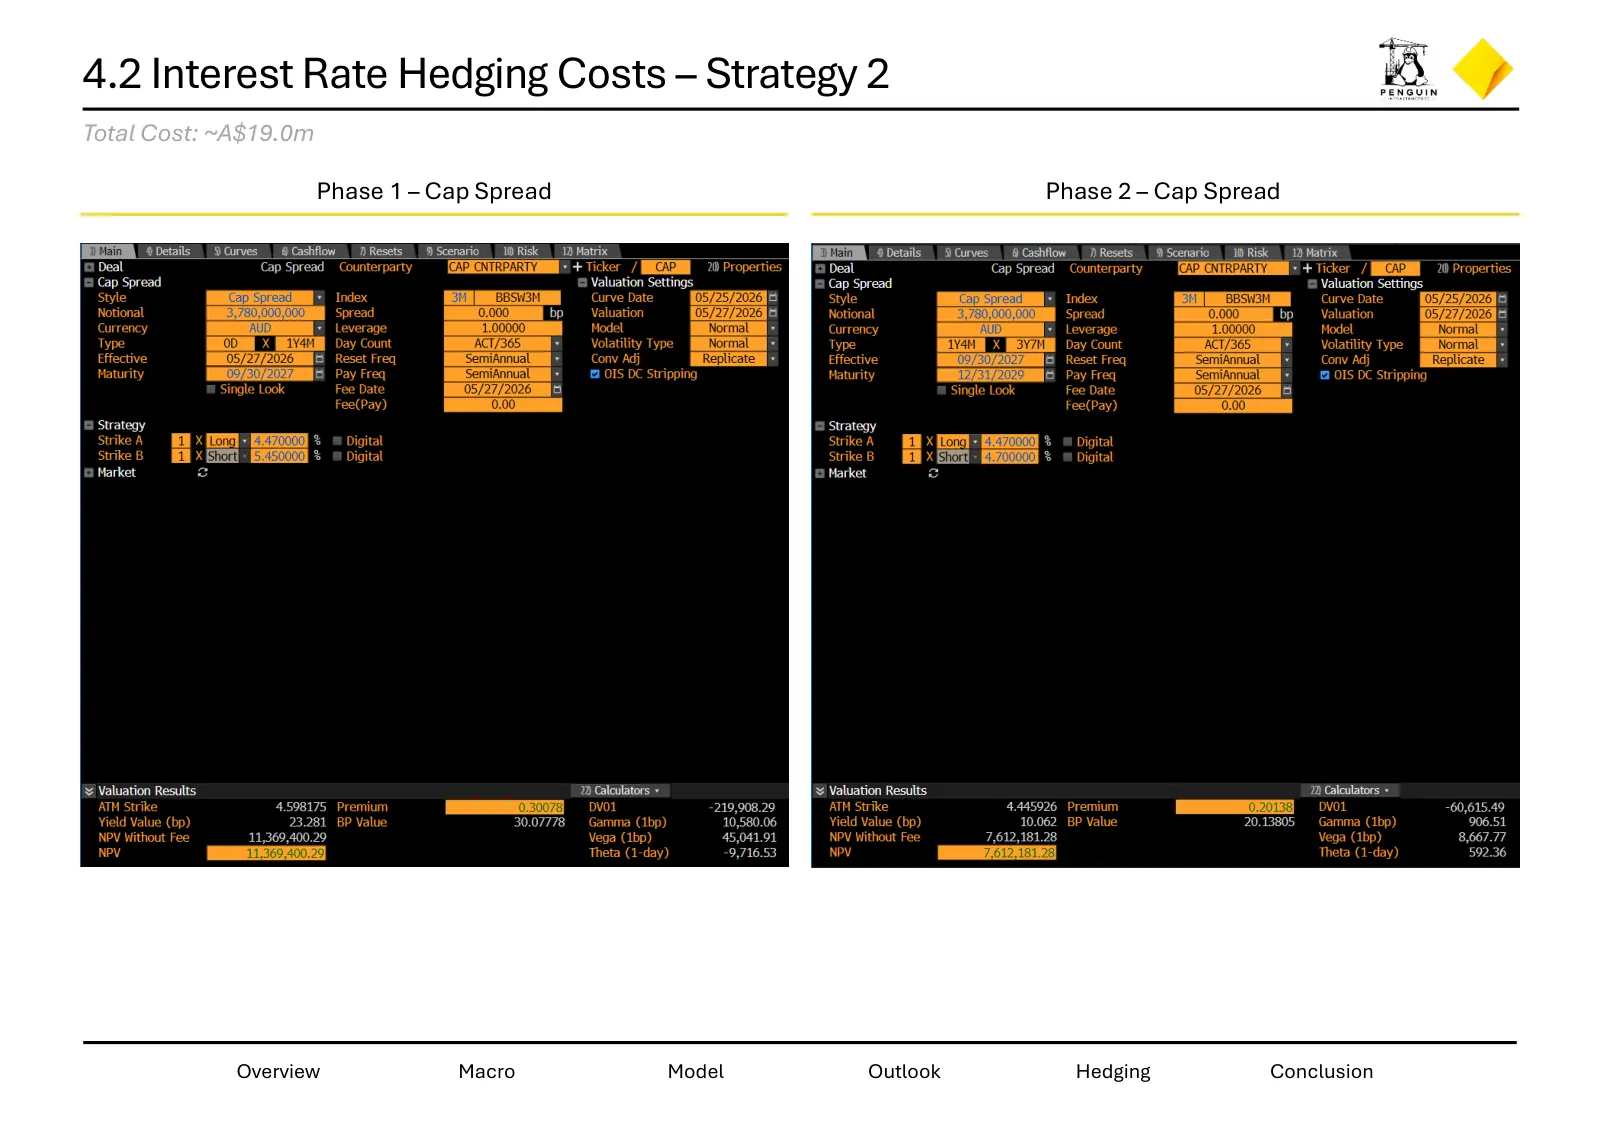
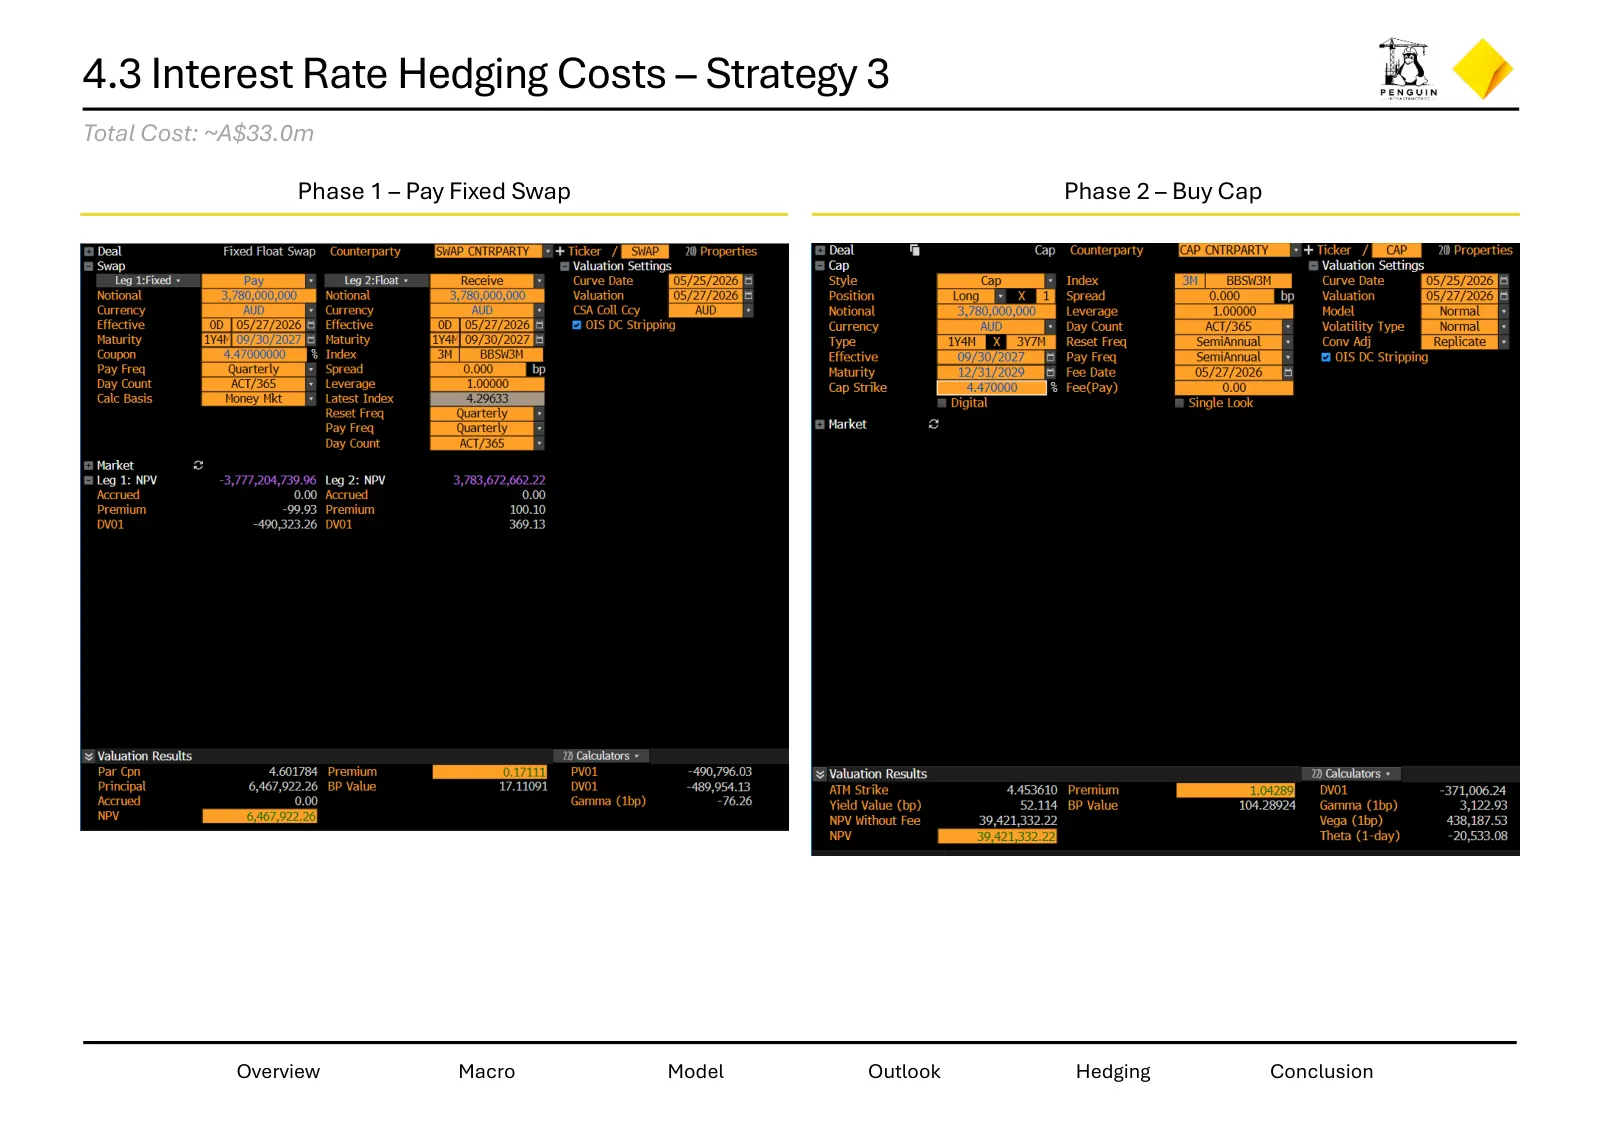
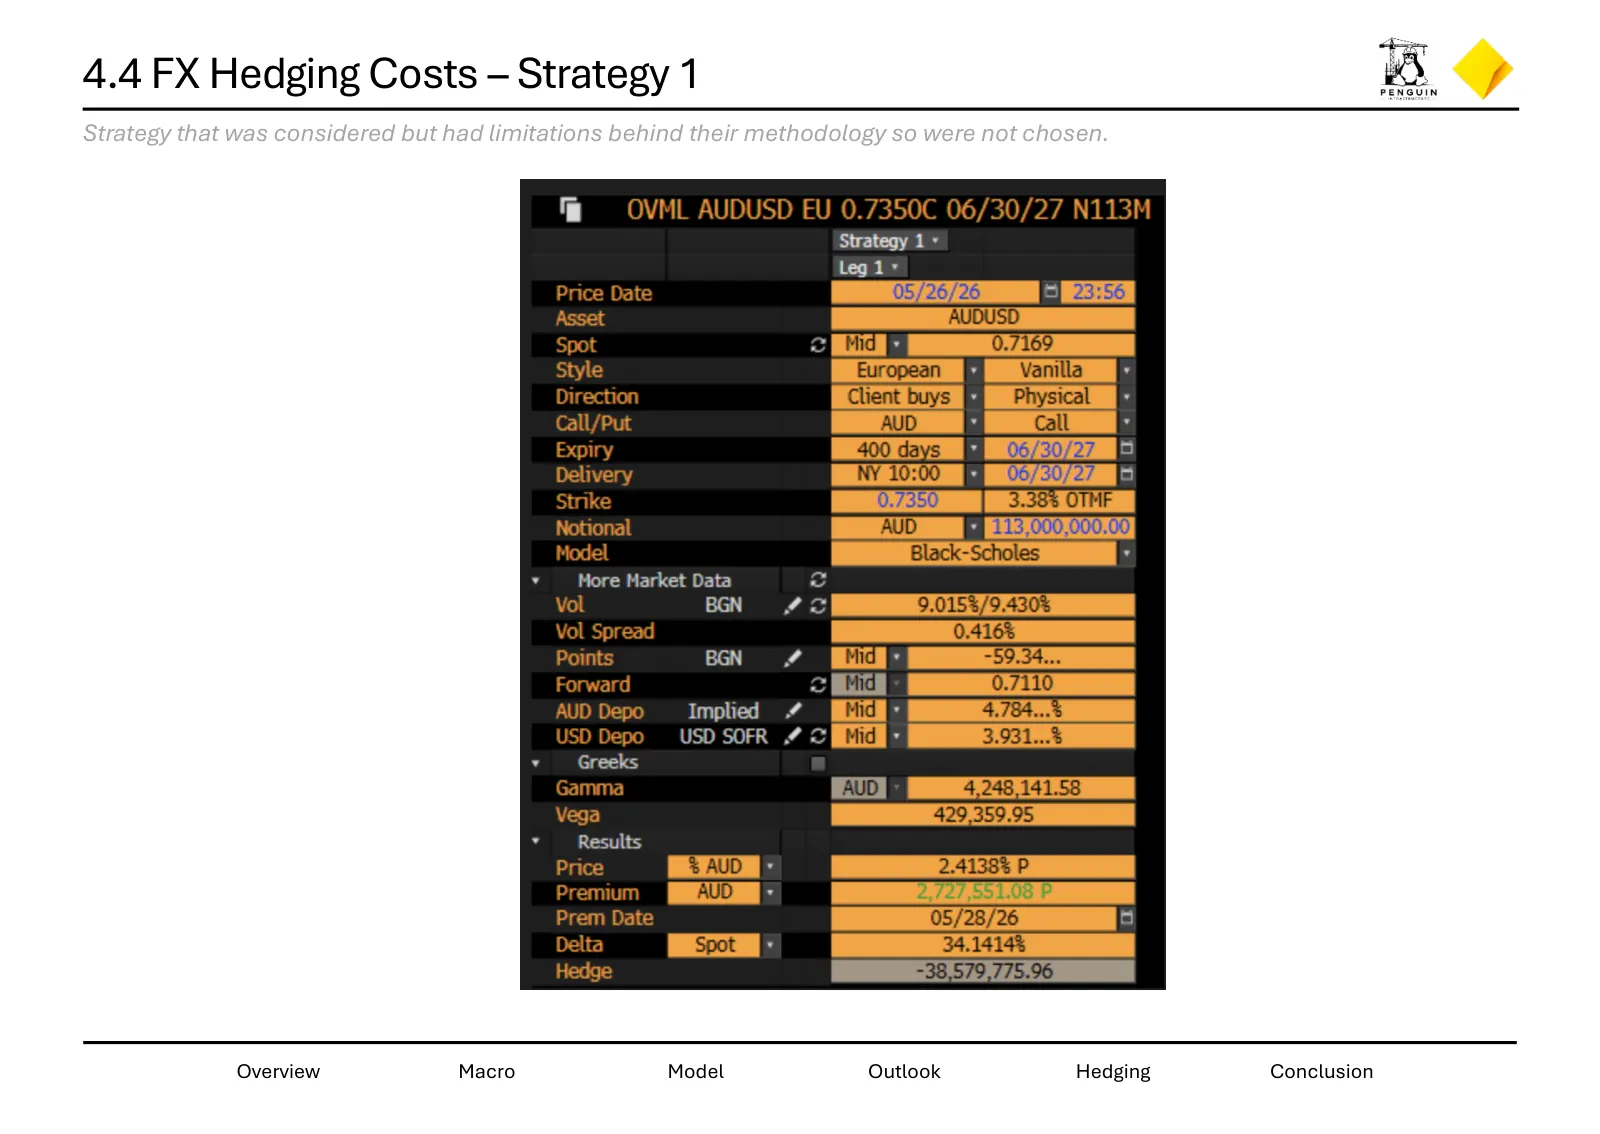
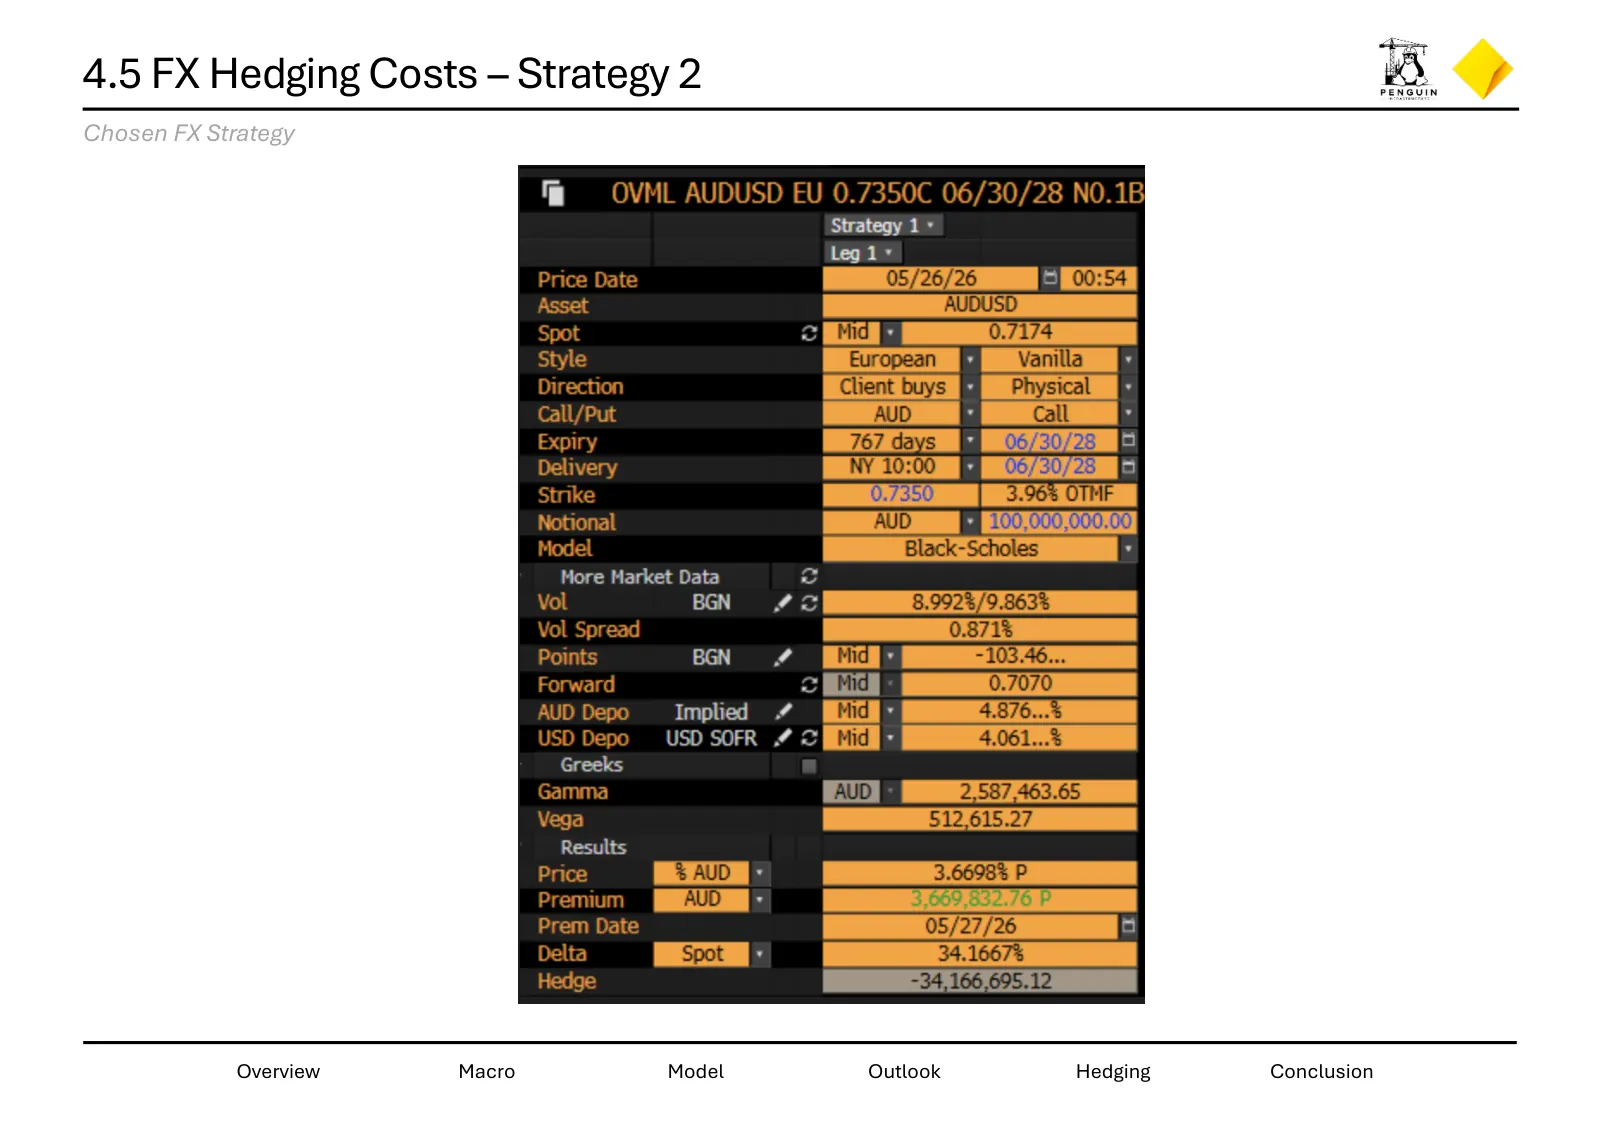
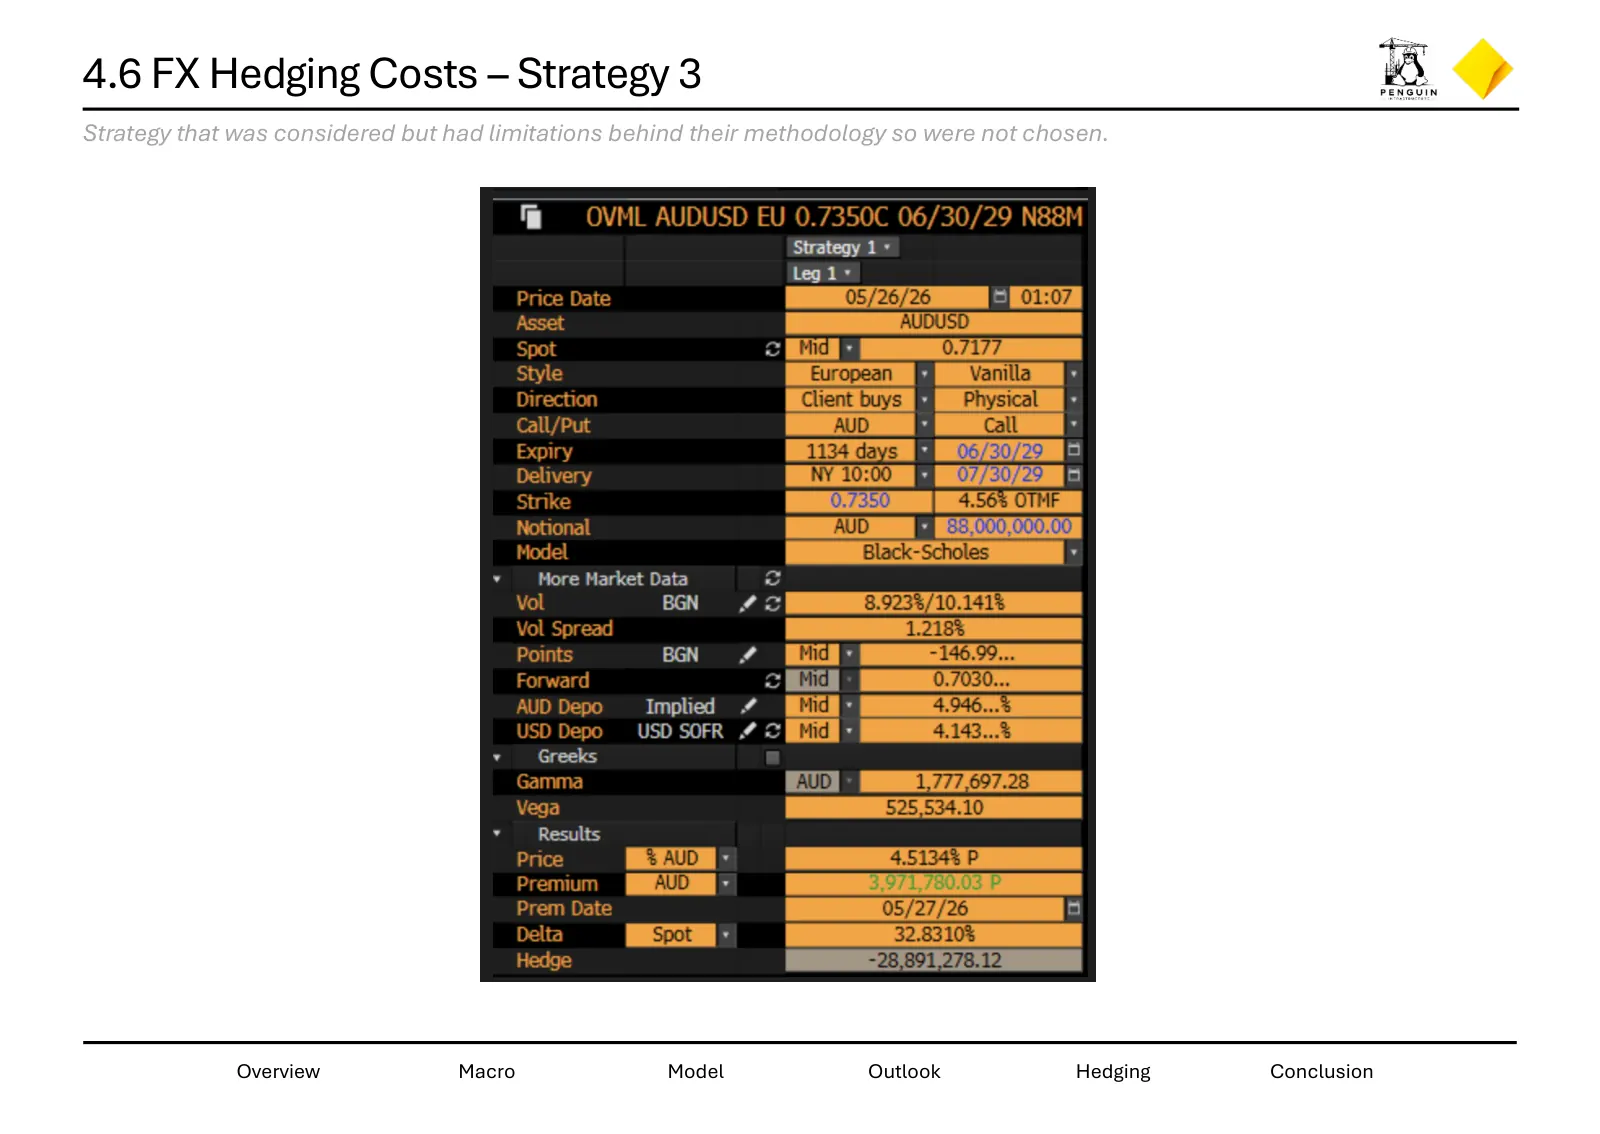
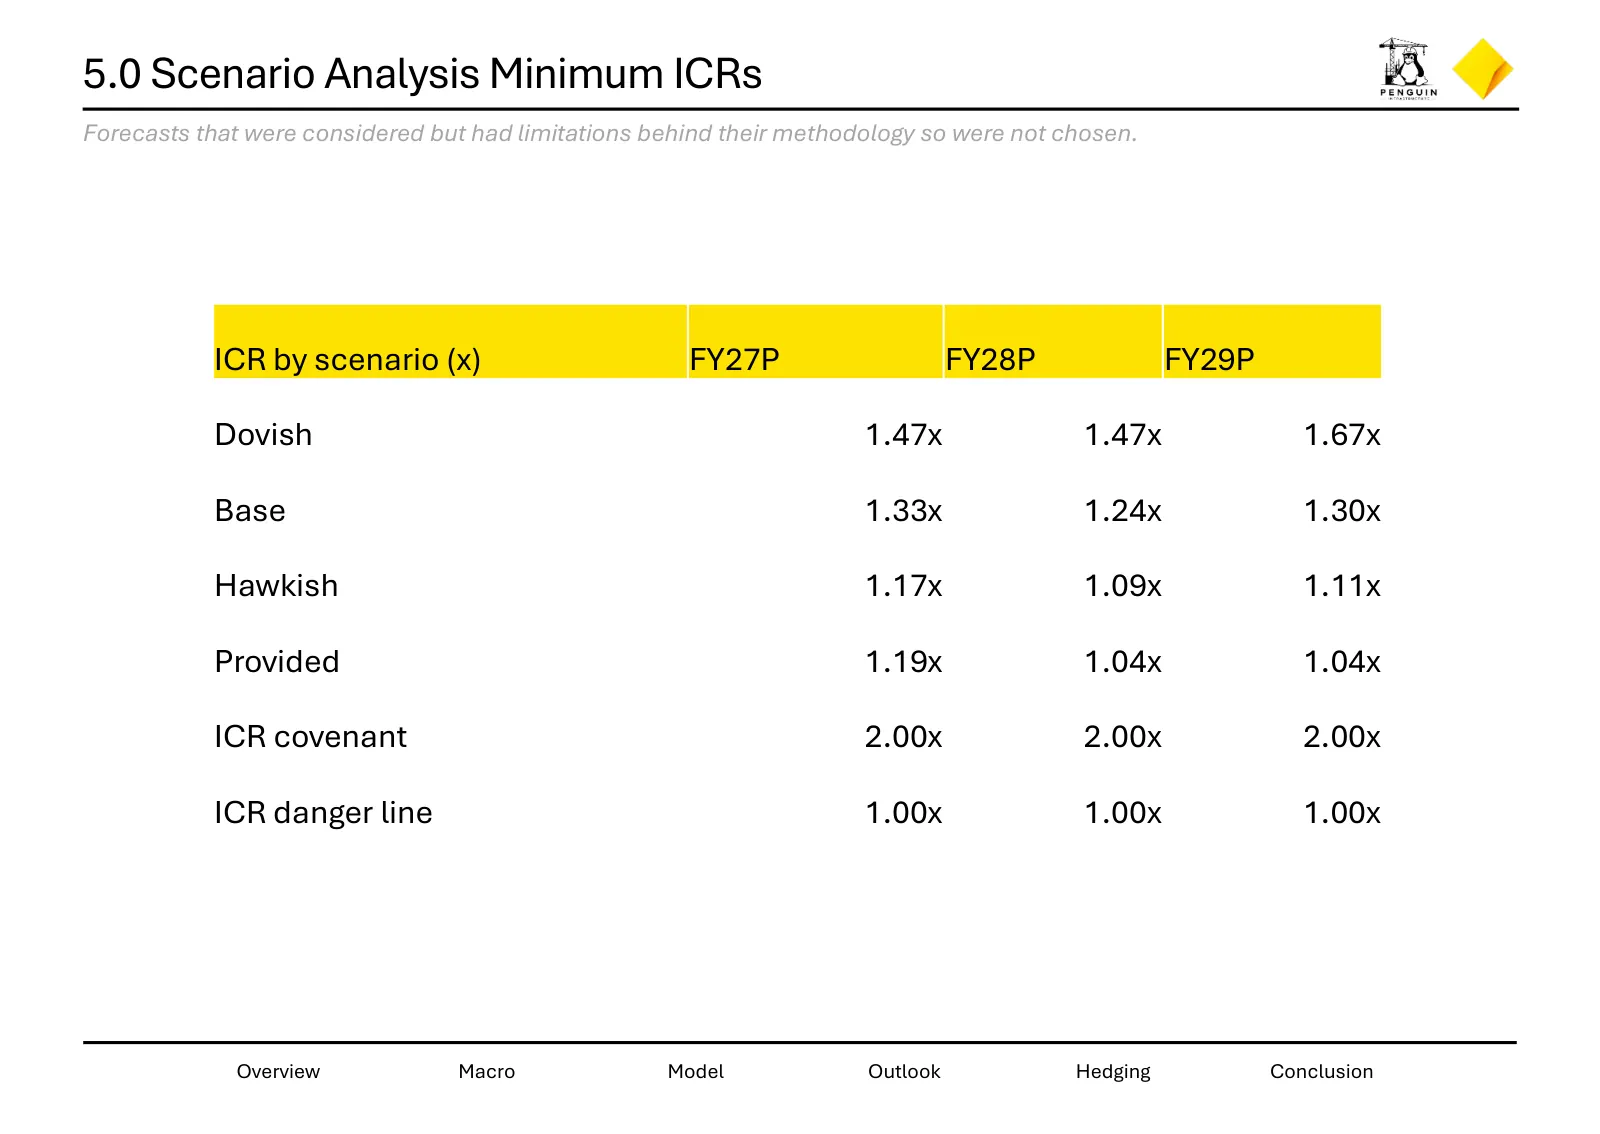
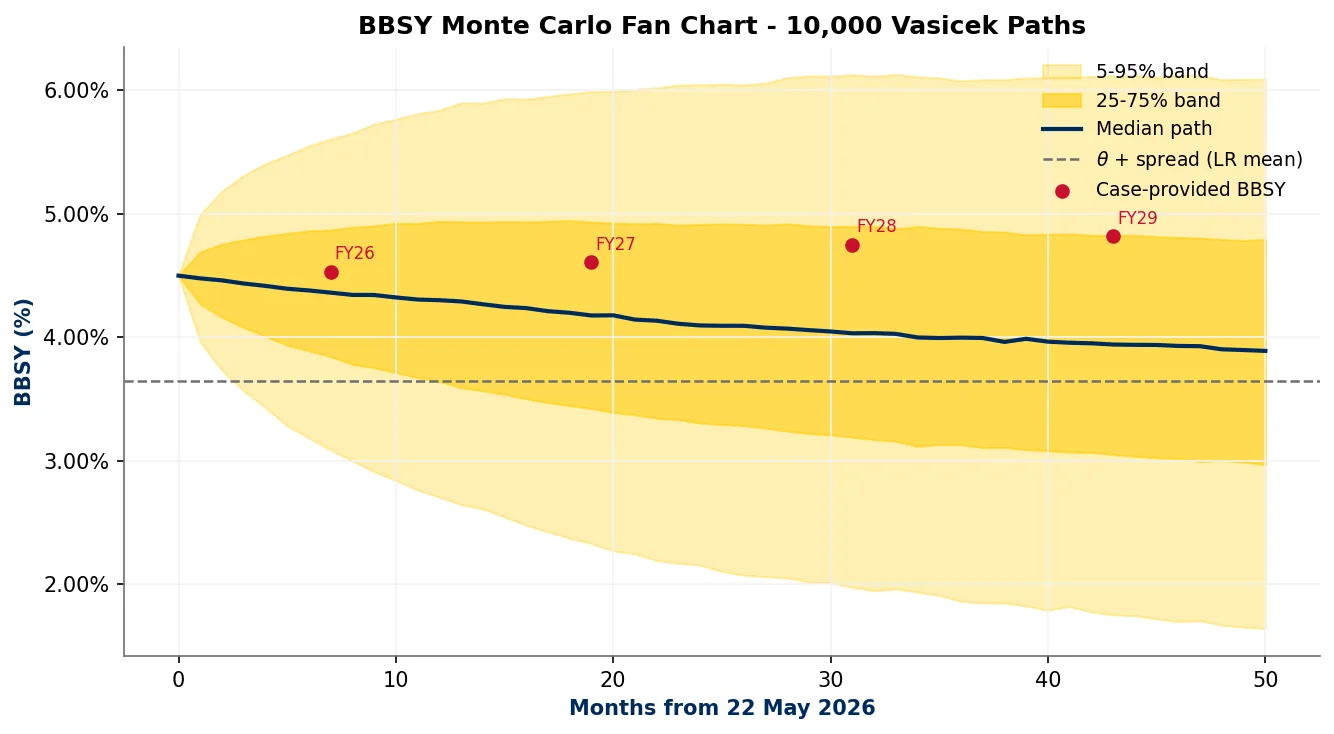
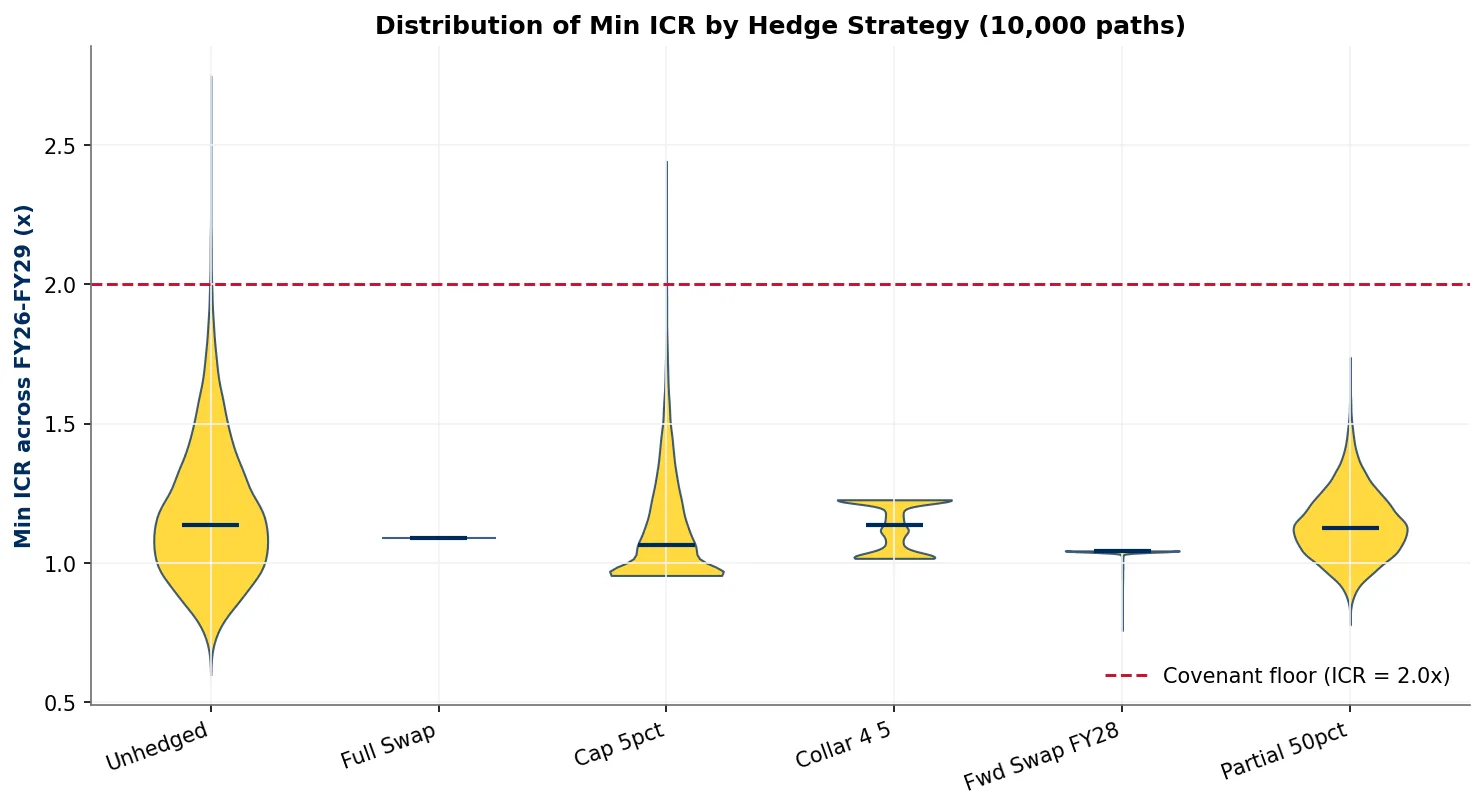
Interest-rate and currency hedging for Penguin Infrastructure. May 2026, for CBA Global Markets. The client's interest cover was already below its 2.0x covenant, and no hedge could lift it back. We recommended a BBSY cap spread and a zero-cost AUD/USD collar to steady the path at low cost, rather than pay for full protection. Team of four, as PWSK Capital.
The models behind it
I built the quantitative models behind the recommendation, in Python.
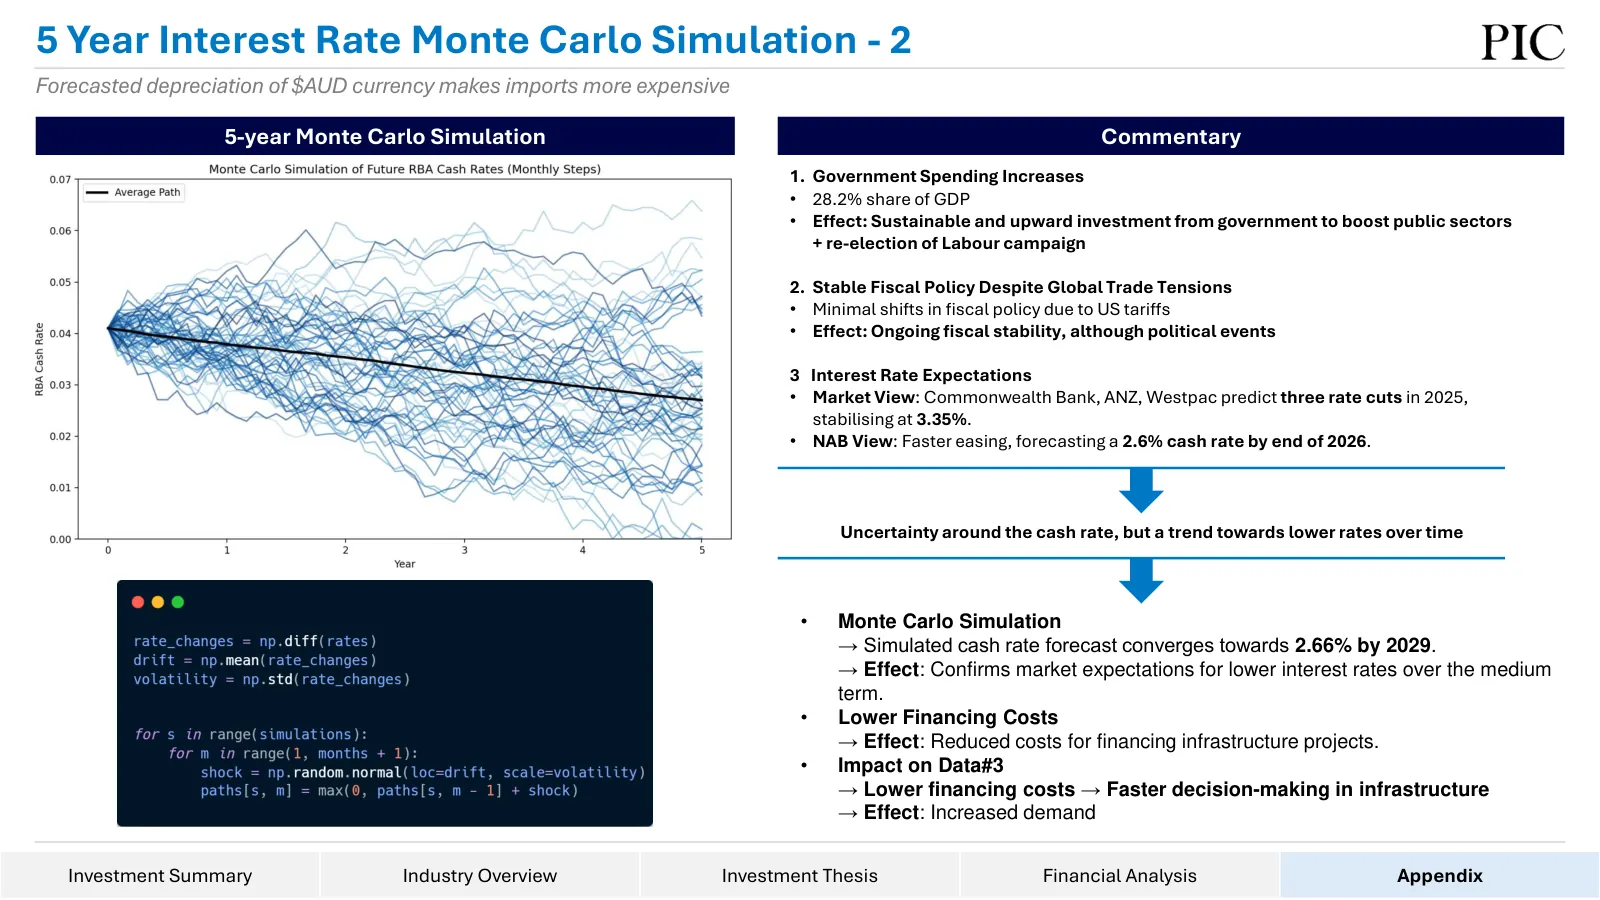
- Rate simulation. 10,000 paths of BBSY out to 2029 from a Vasicek and Hull-White model, fitted to the case's rate path. It gives the chance of a covenant breach under each hedge, not just a base case.
- Hedge optimiser. Finds the mix of seven hedges (swaps, a cap, a collar, a forward-start swap and a swaption) that keeps the worst outcomes smallest for the premium paid, and tests that mix in four different rate regimes.
- Currency hedge optimiser. Scores 3,380 combinations of the cross-currency swap and a two-stage hedge of US dollar revenue, within a A$50 million premium budget.
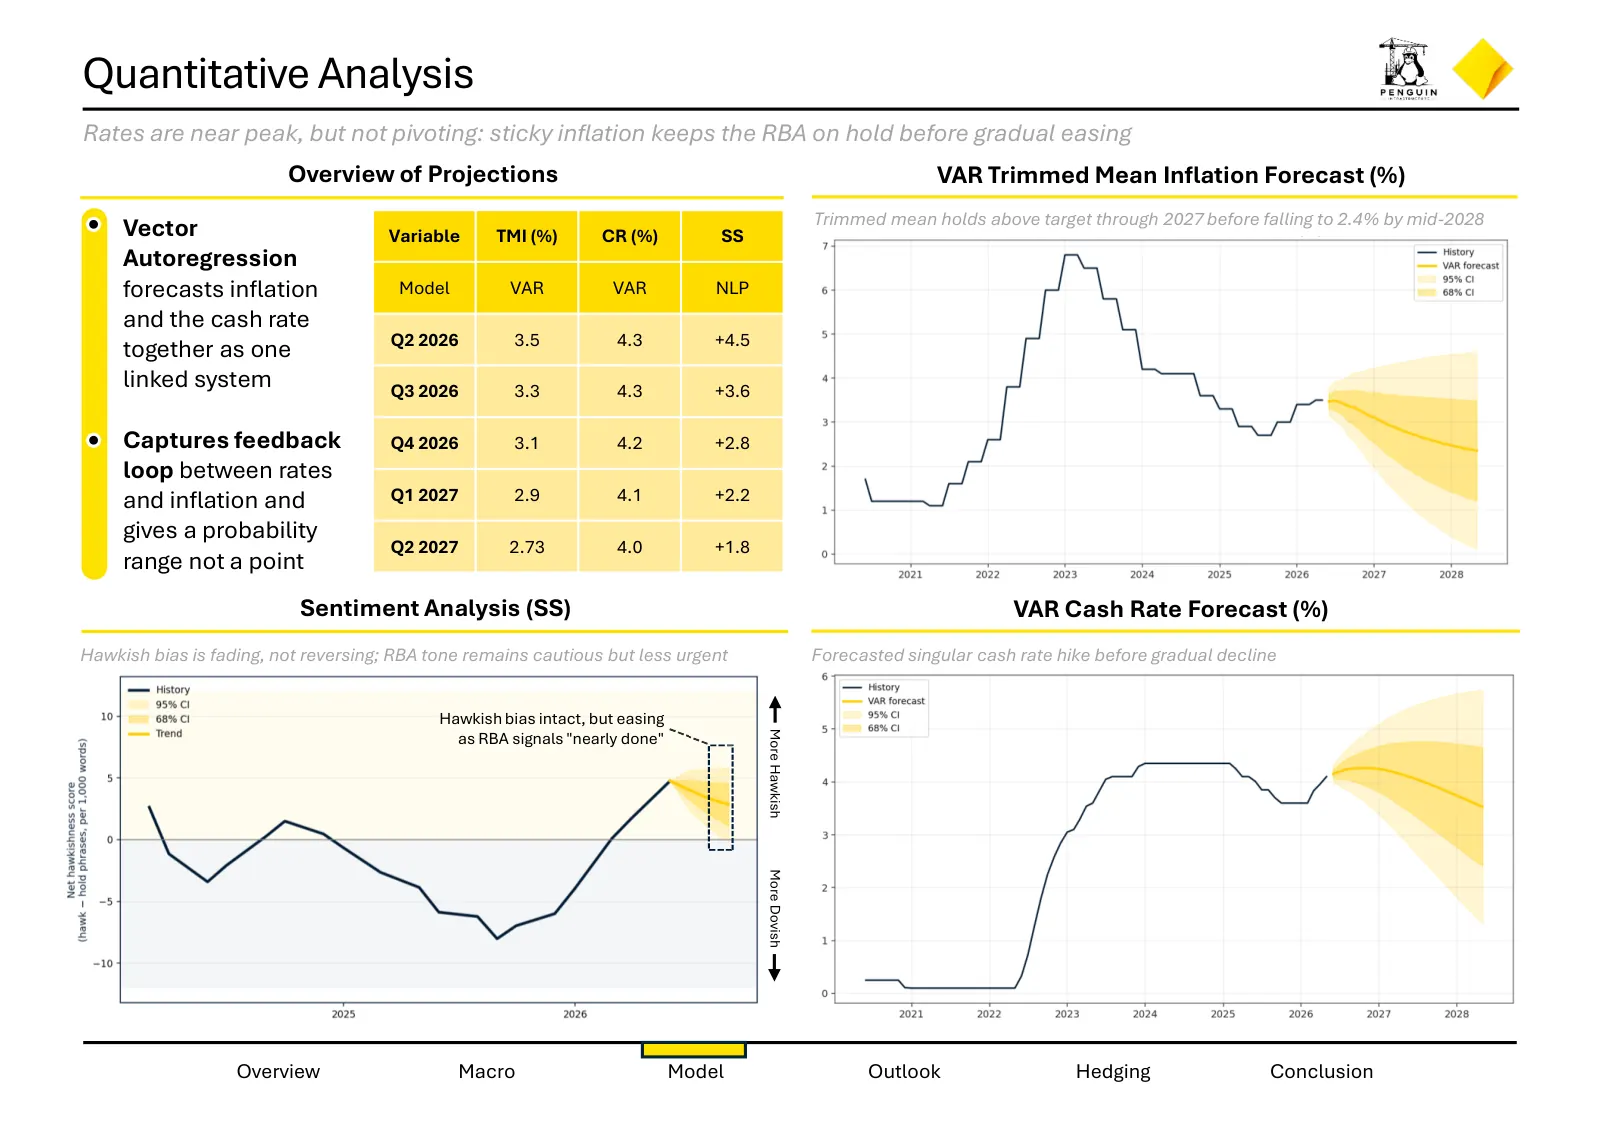
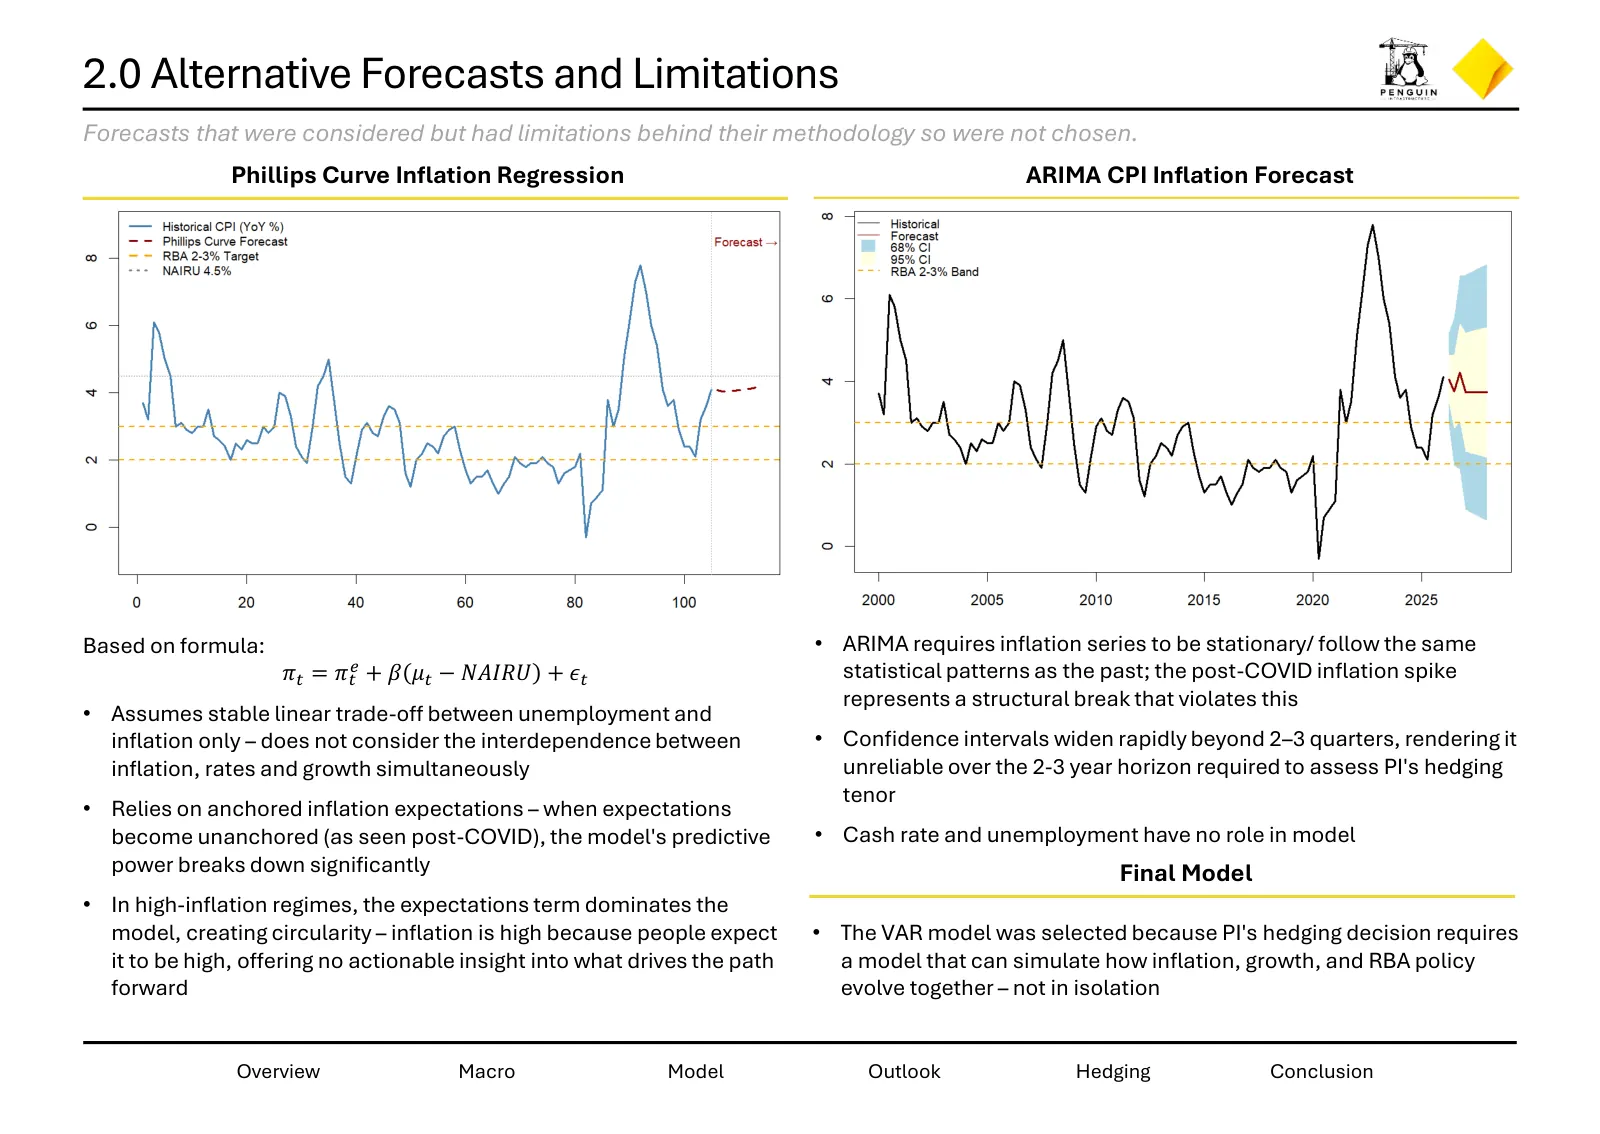
- Macro forecasts. A VAR of the cash rate, inflation, wages, unemployment and the dollar, checked against a Taylor rule and the forward curve.
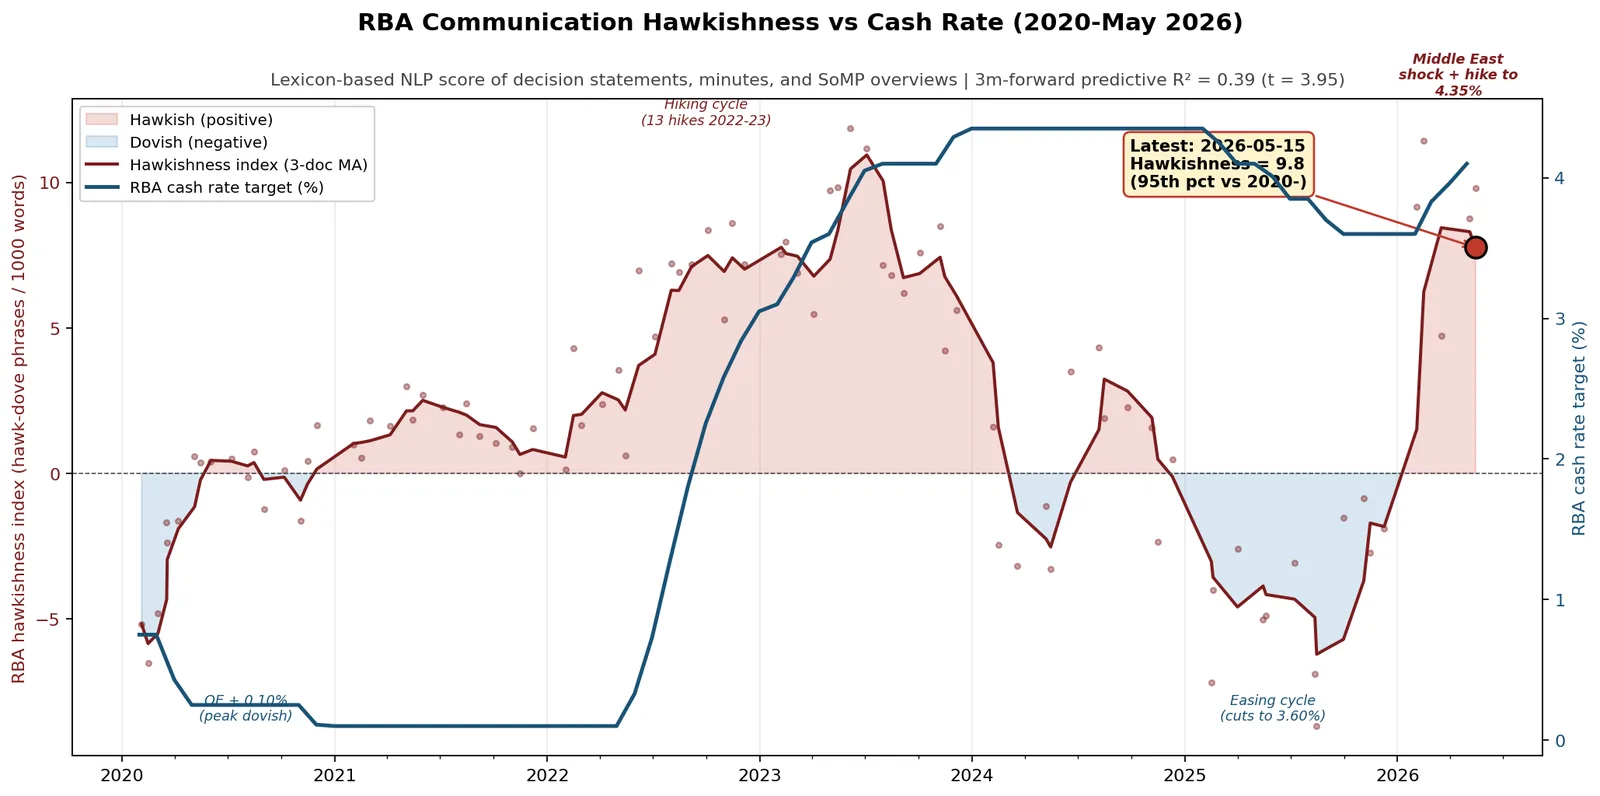
- RBA tone index. Scores 154 RBA statements, minutes and policy statements since 2020 by their hawkish and dovish phrases. The score explains 39% of the change in the cash rate over the next three months.
- Financial model. Penguin's earnings, interest cost and covenant headroom under five rate and operating scenarios.
Equity research
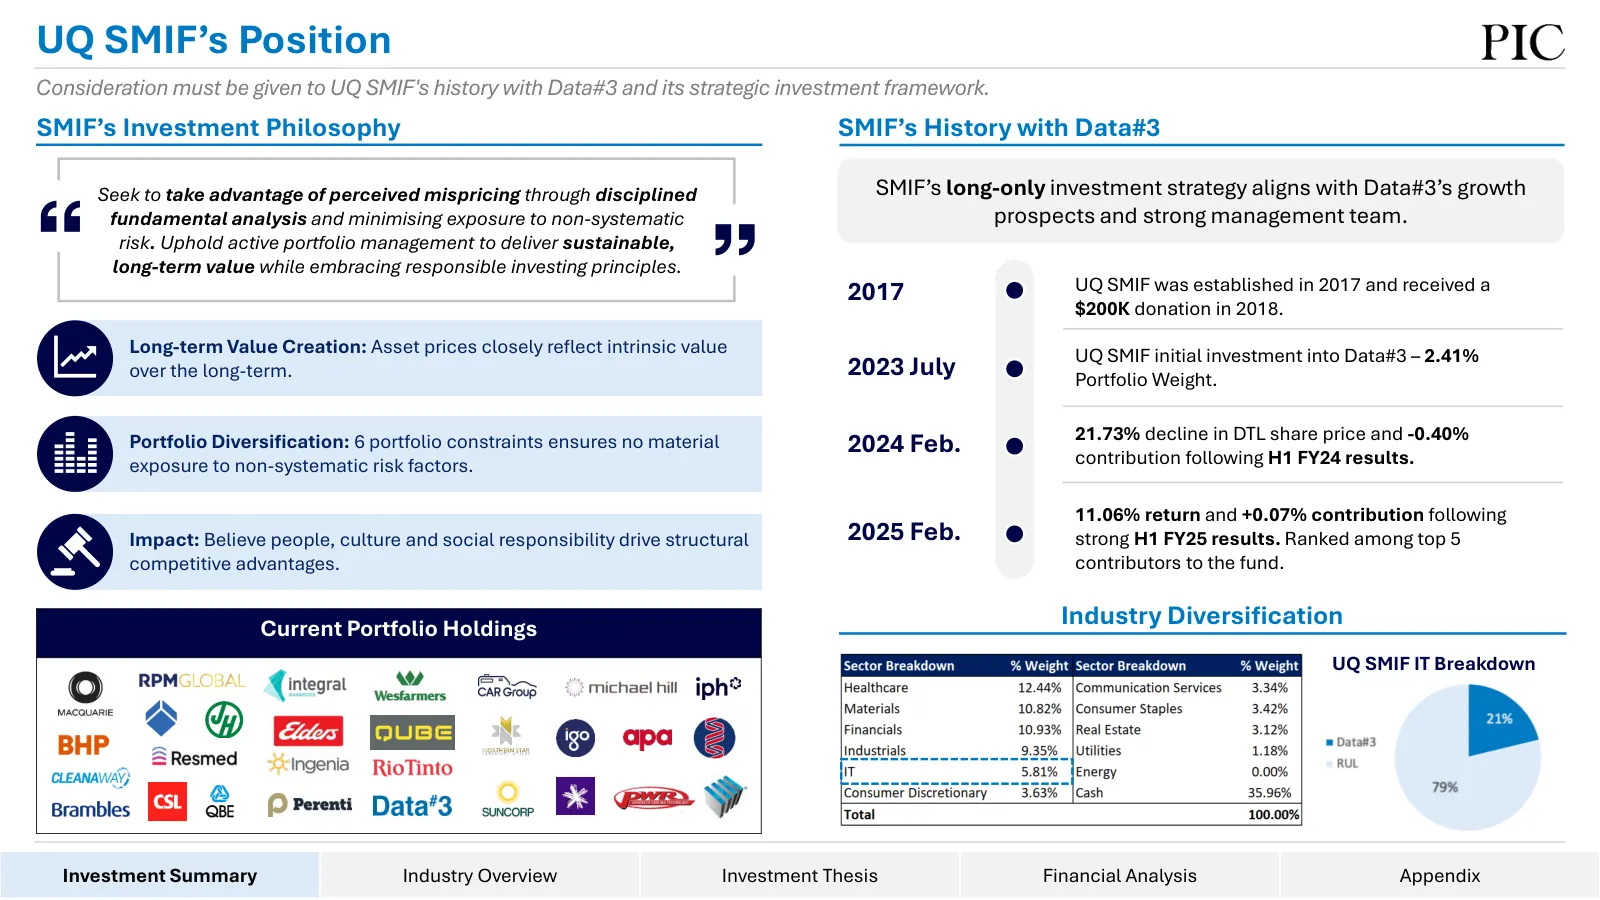
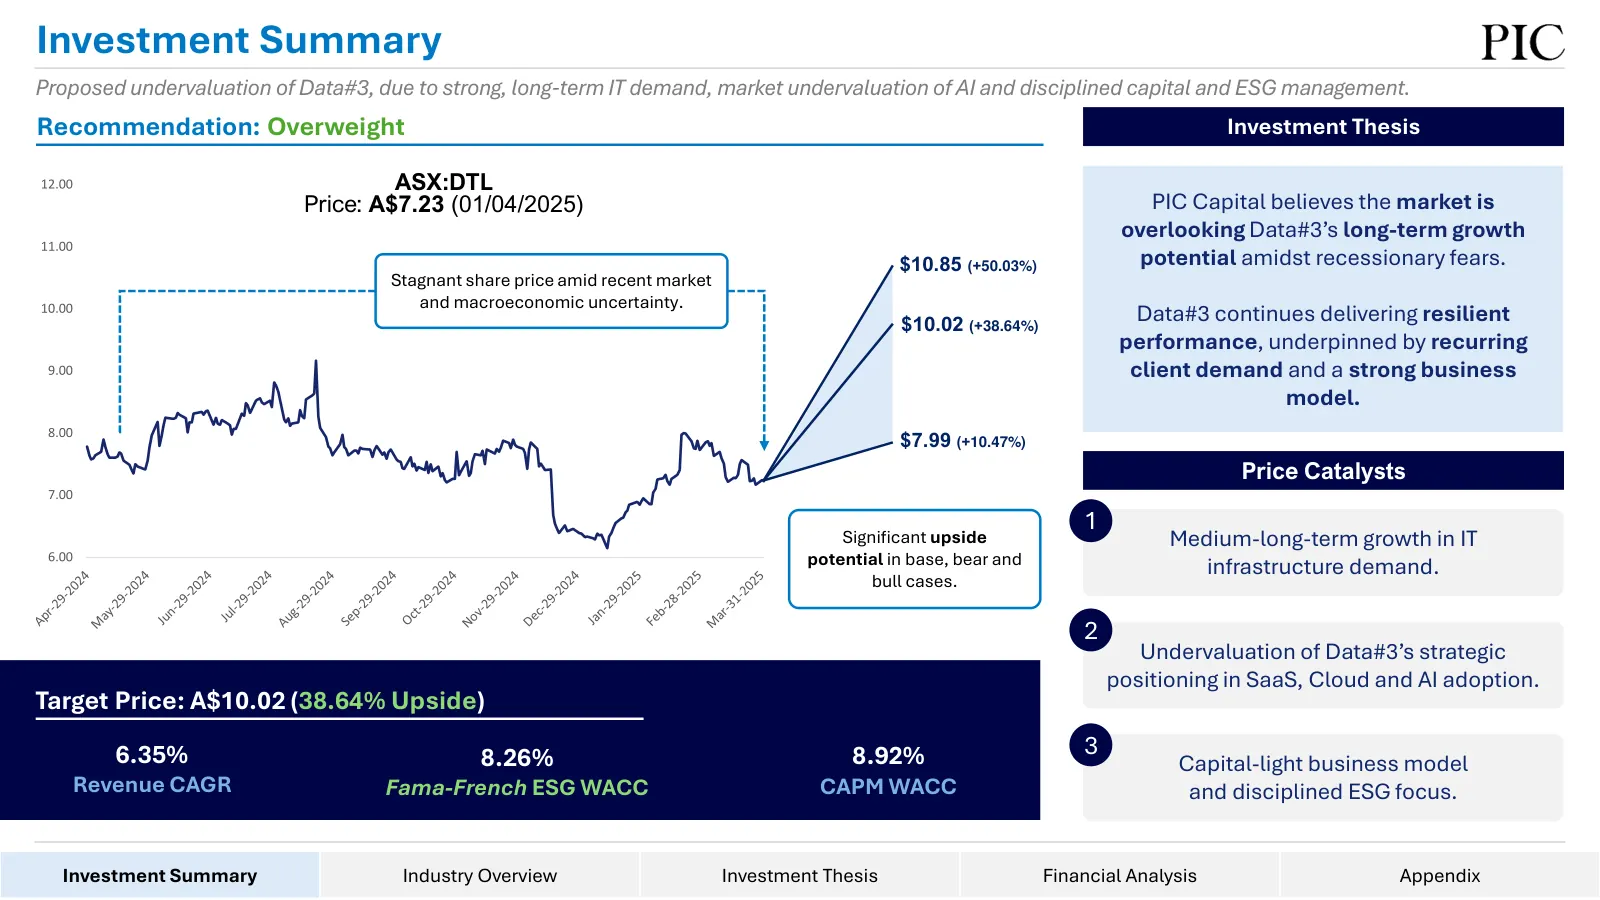
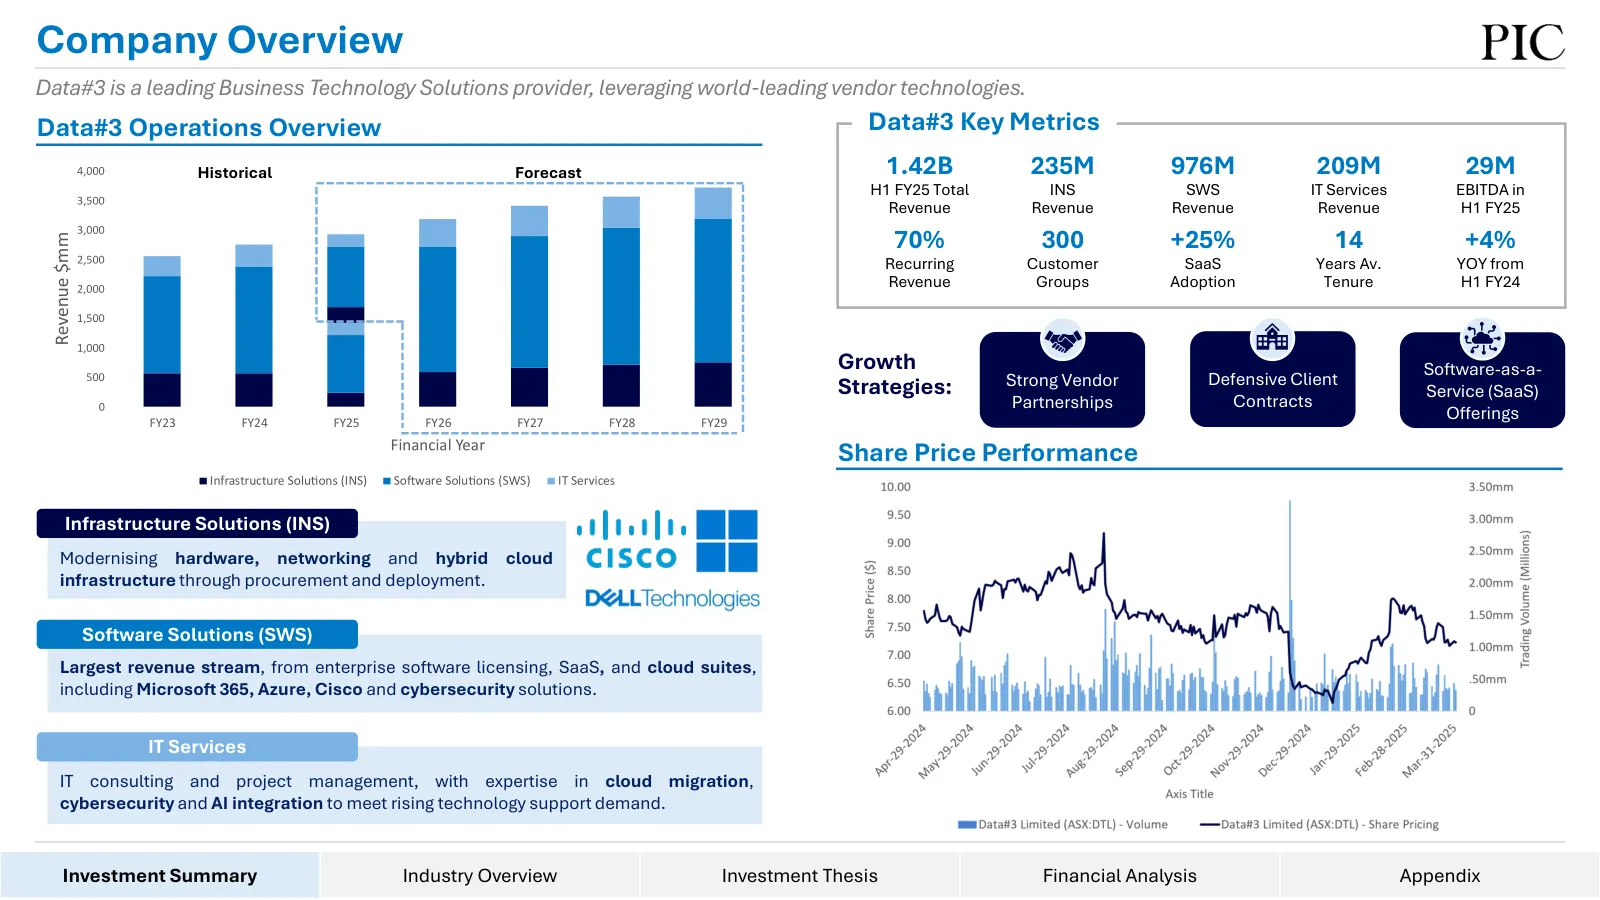
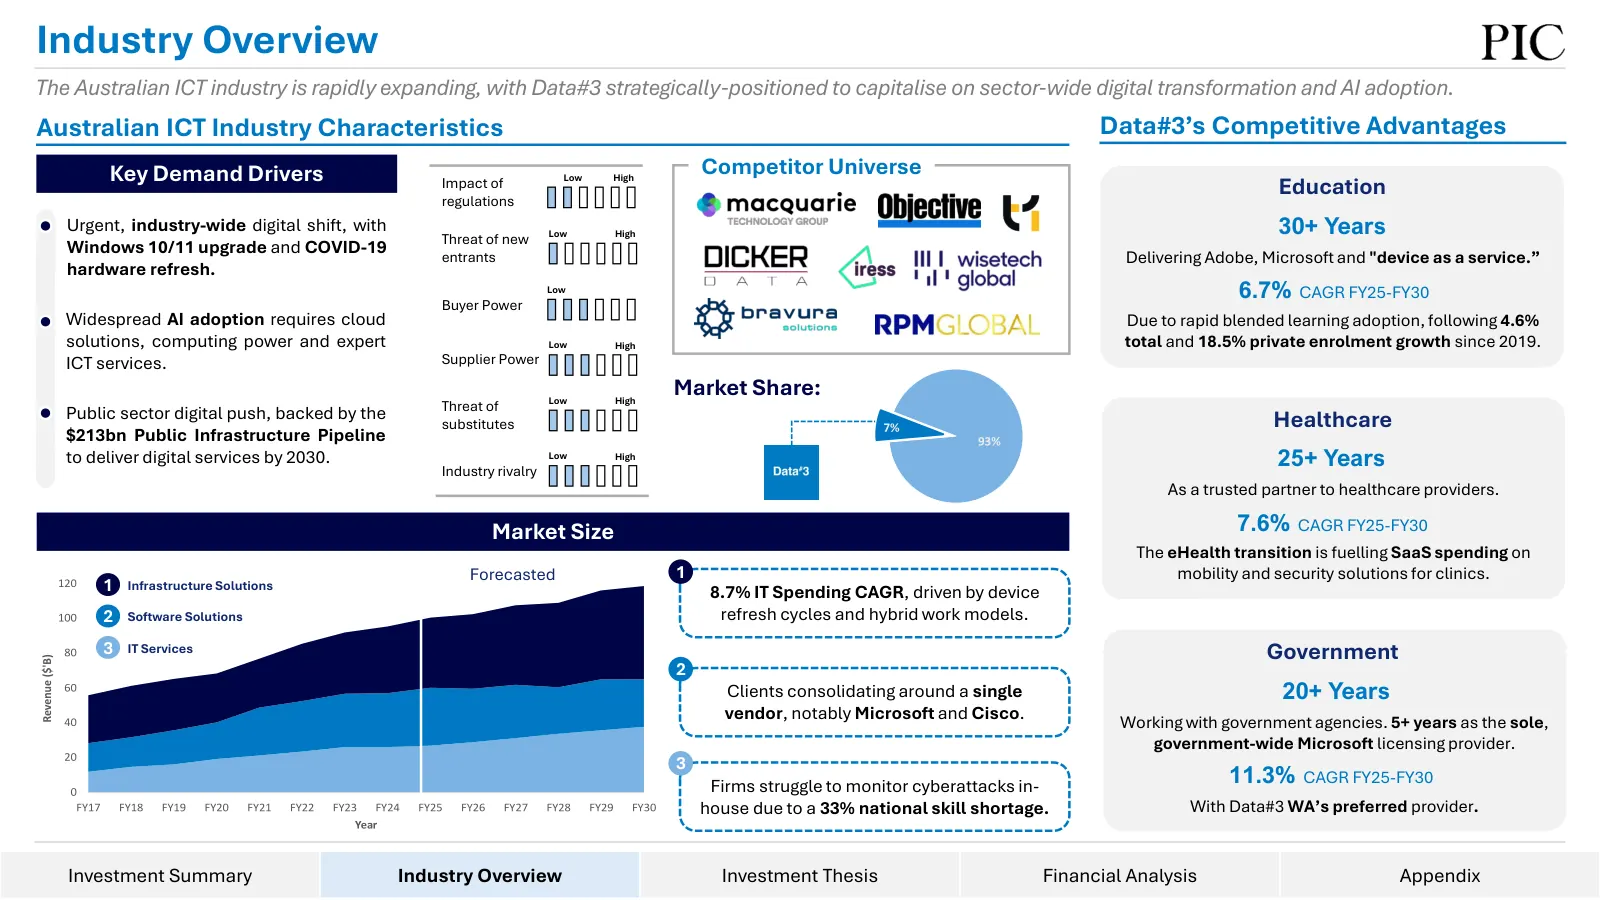
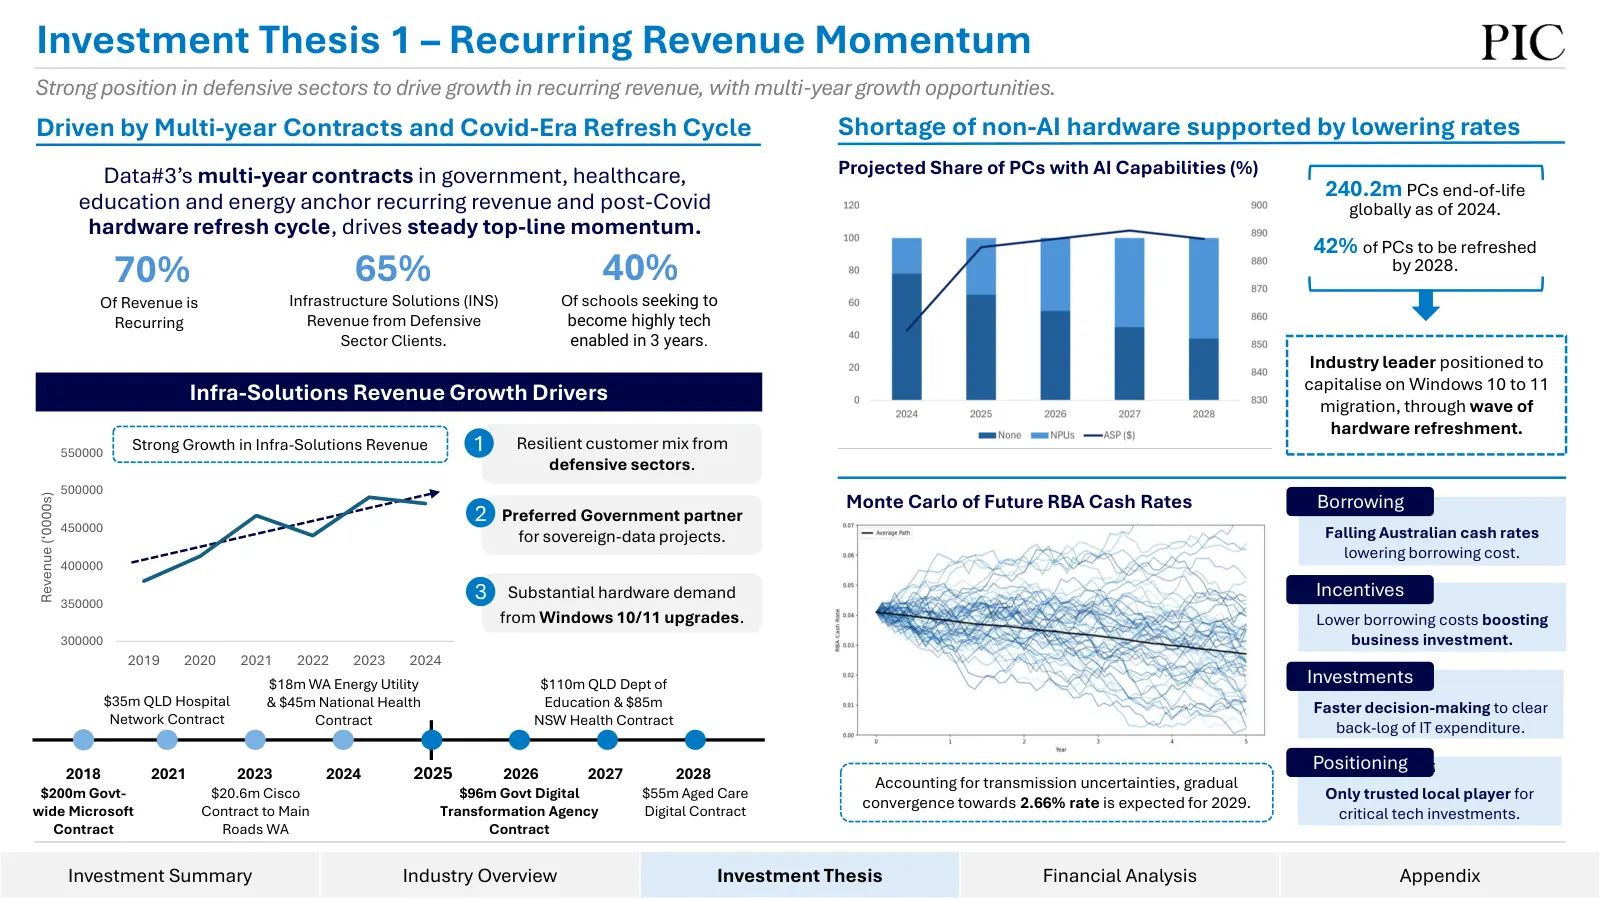
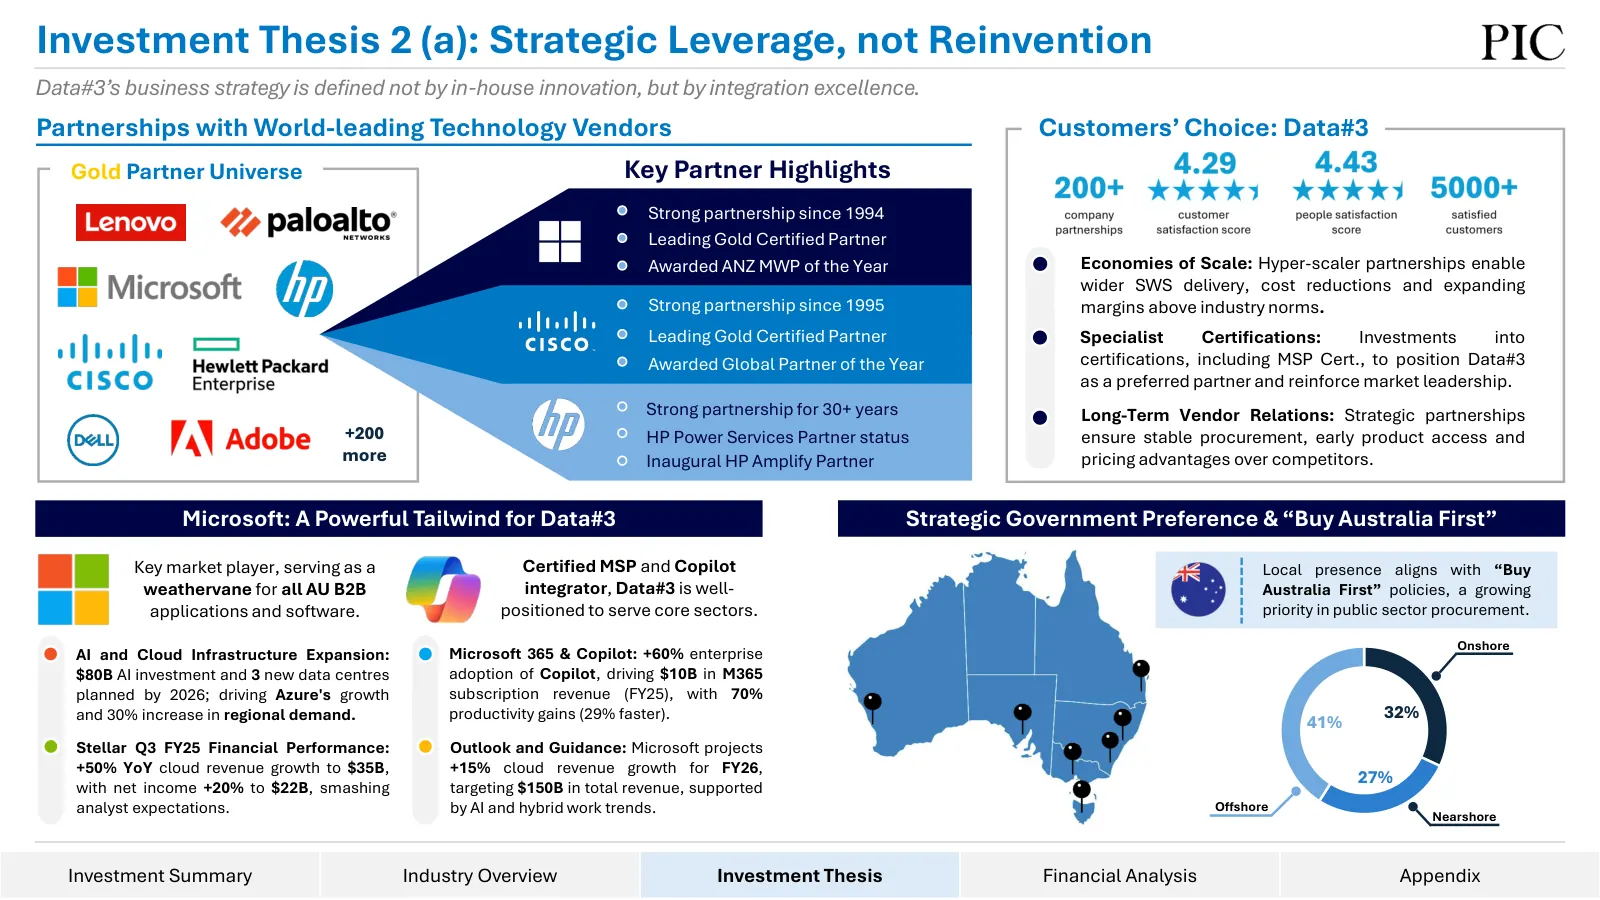
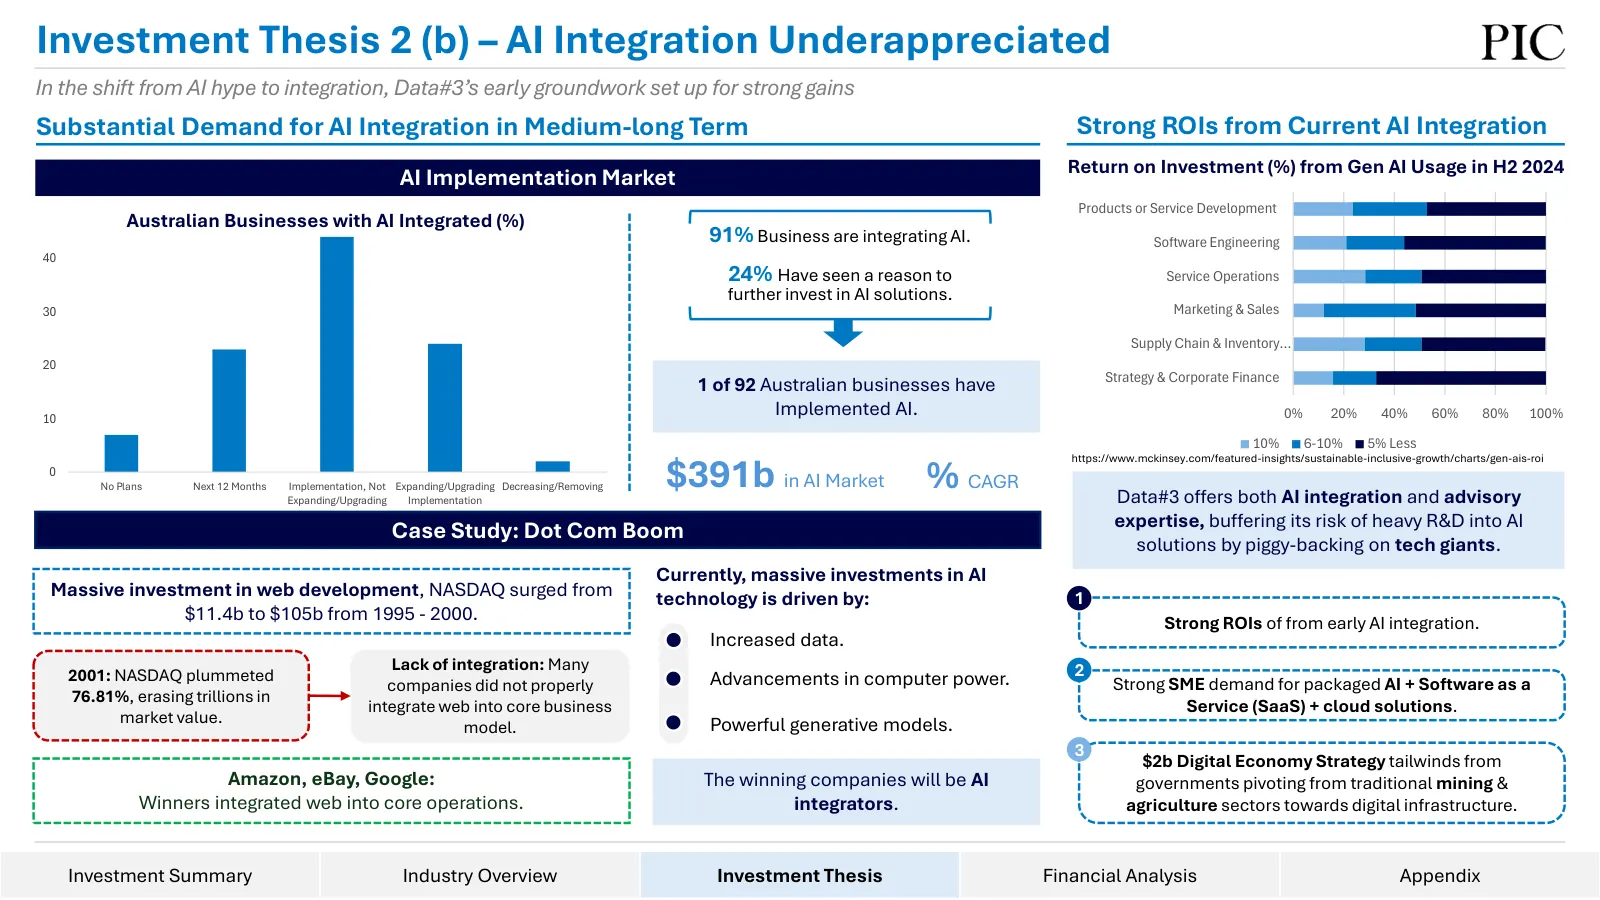
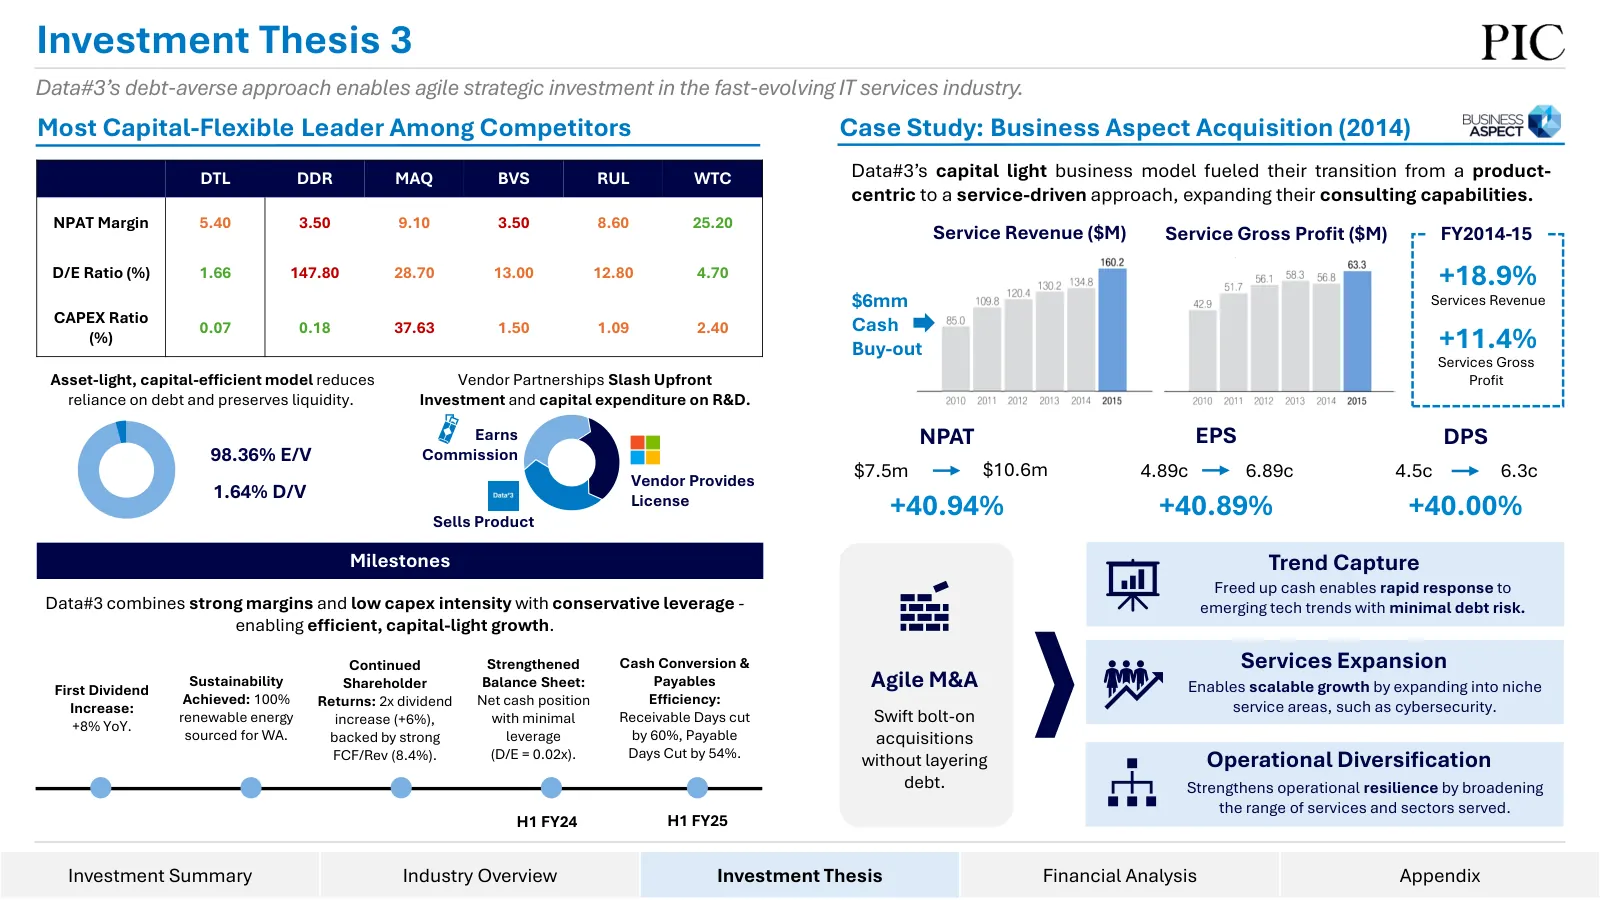
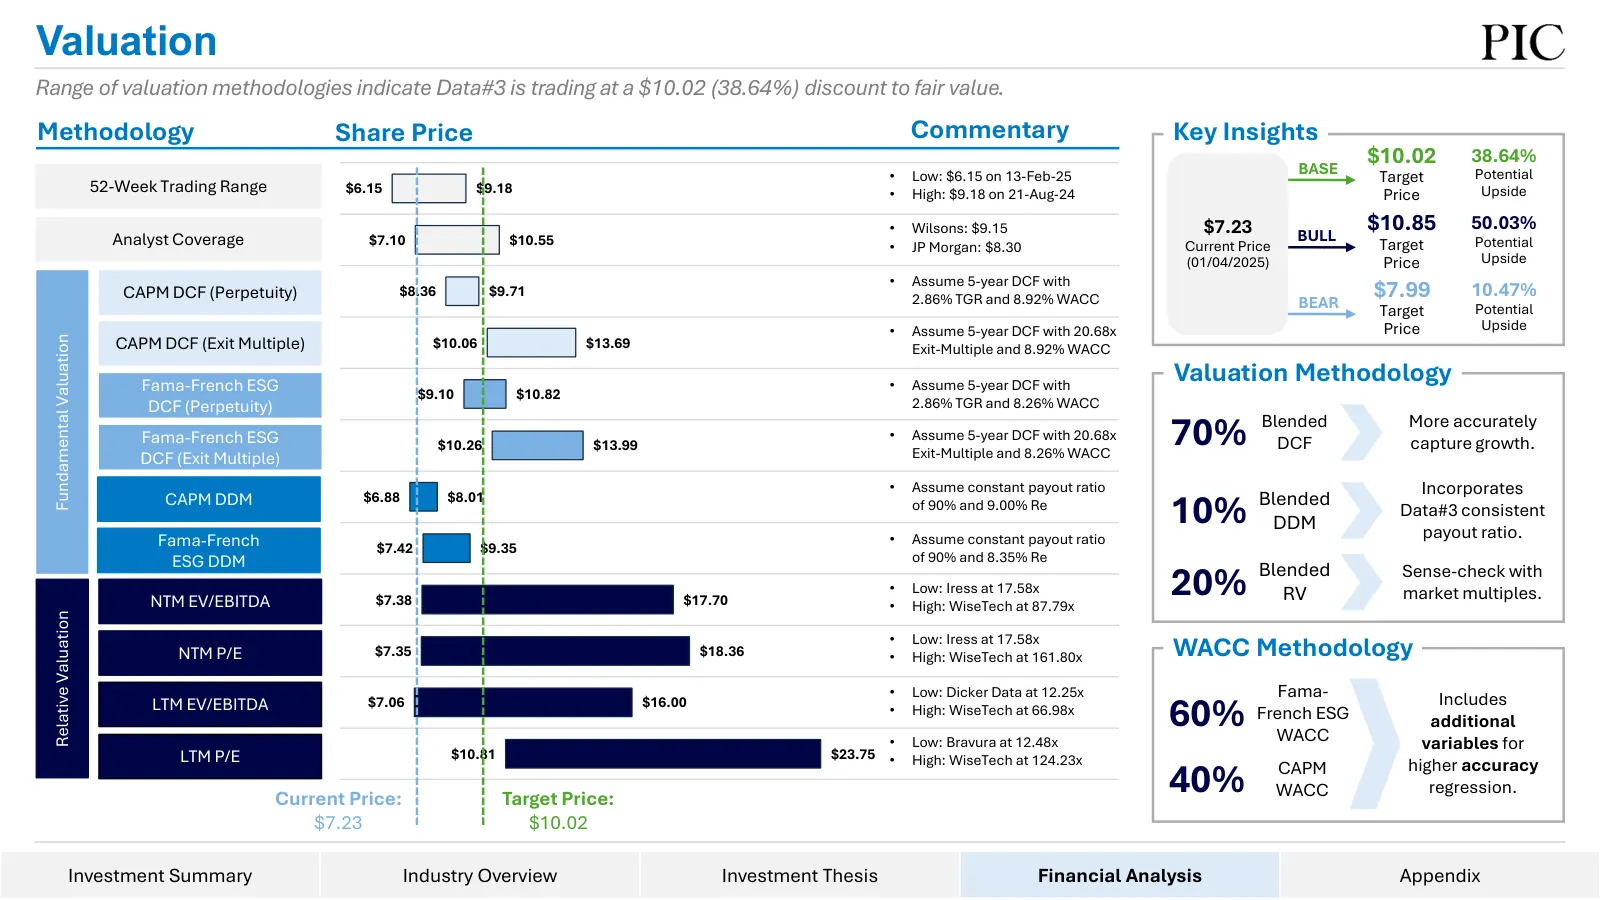
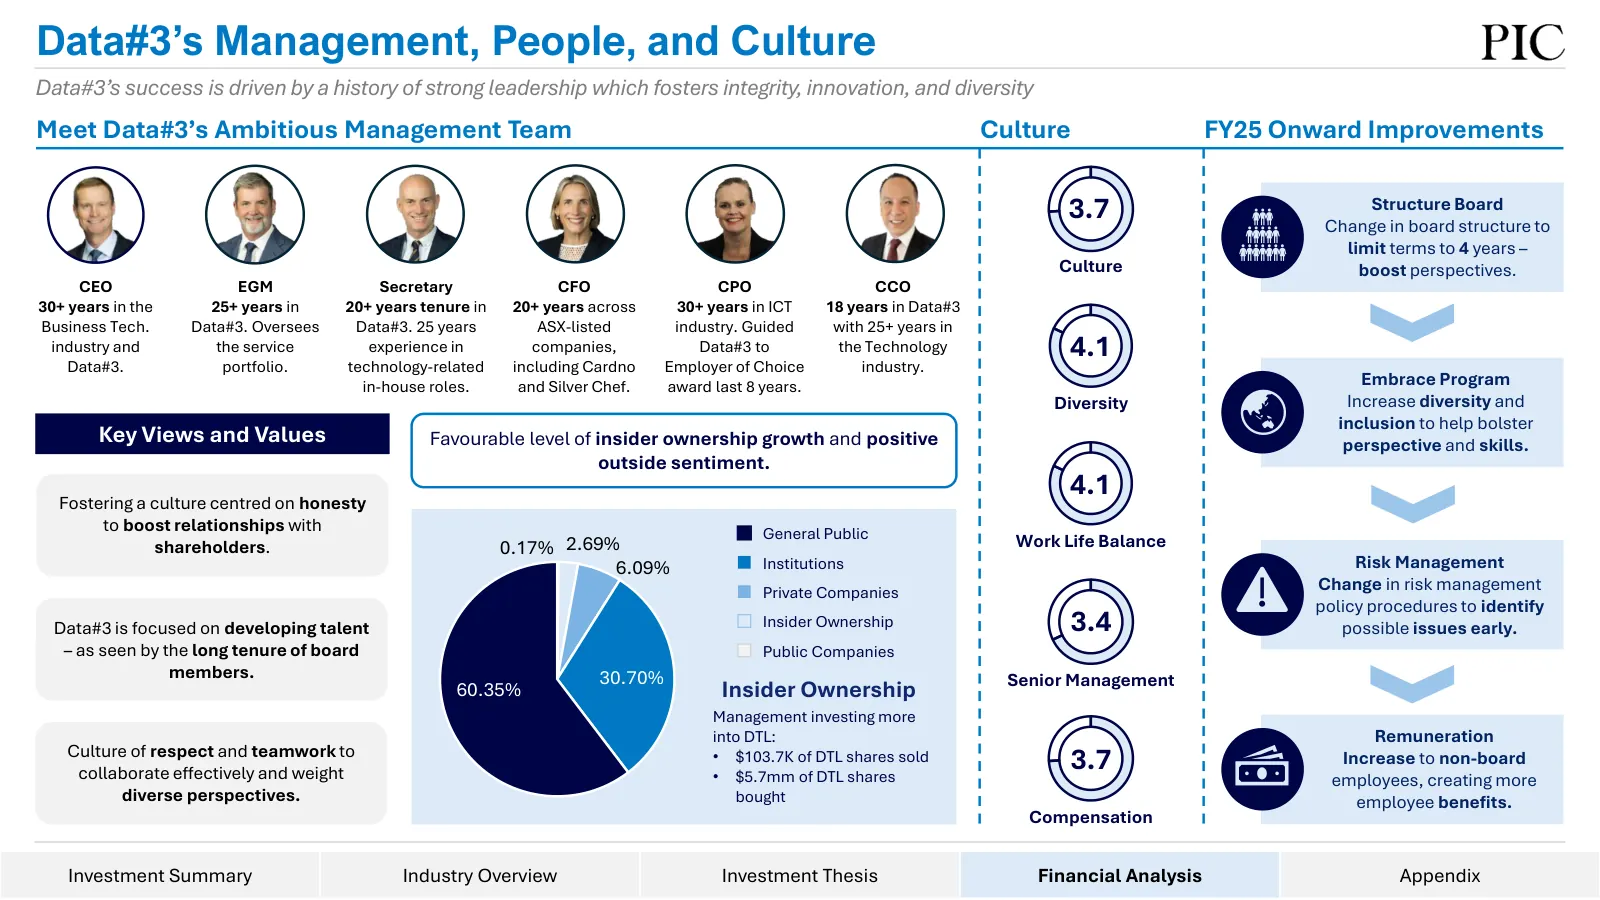
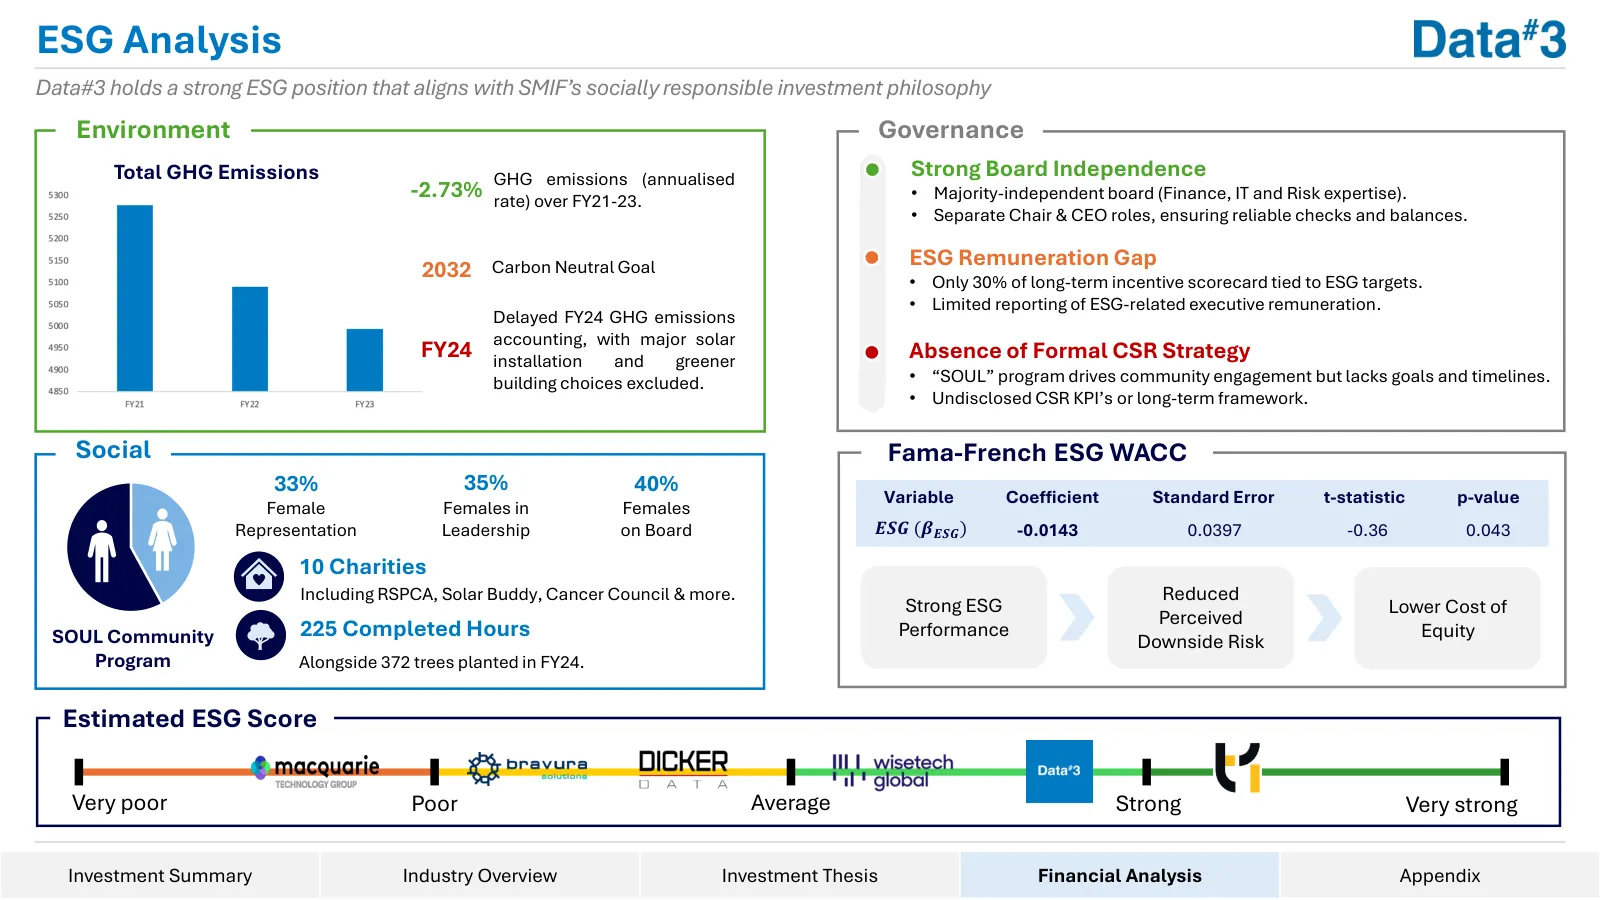
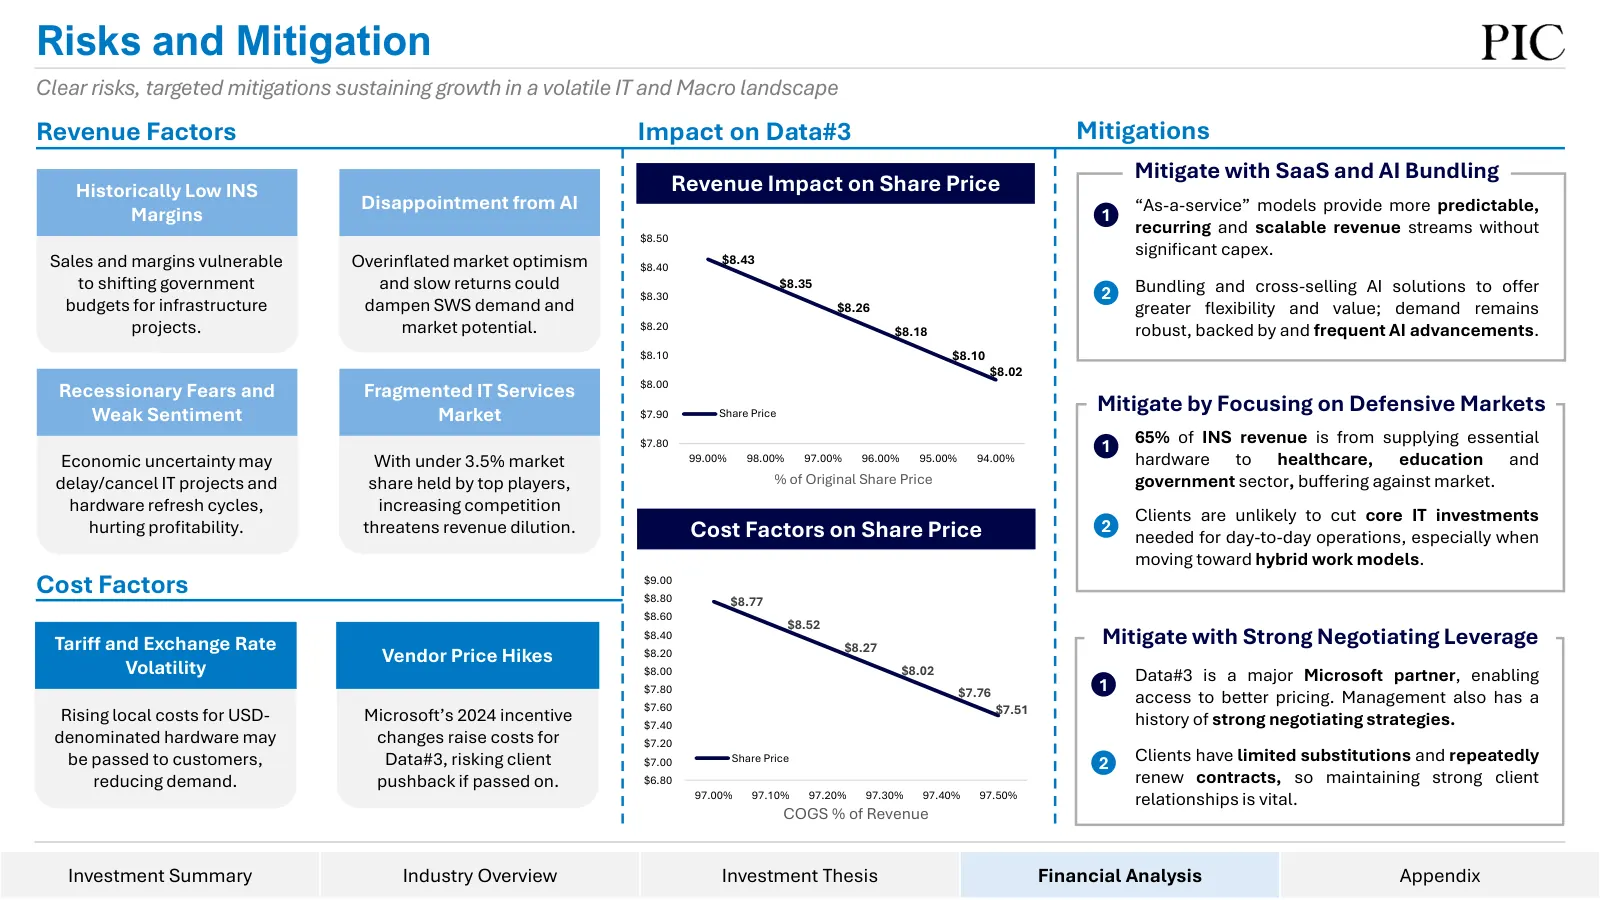
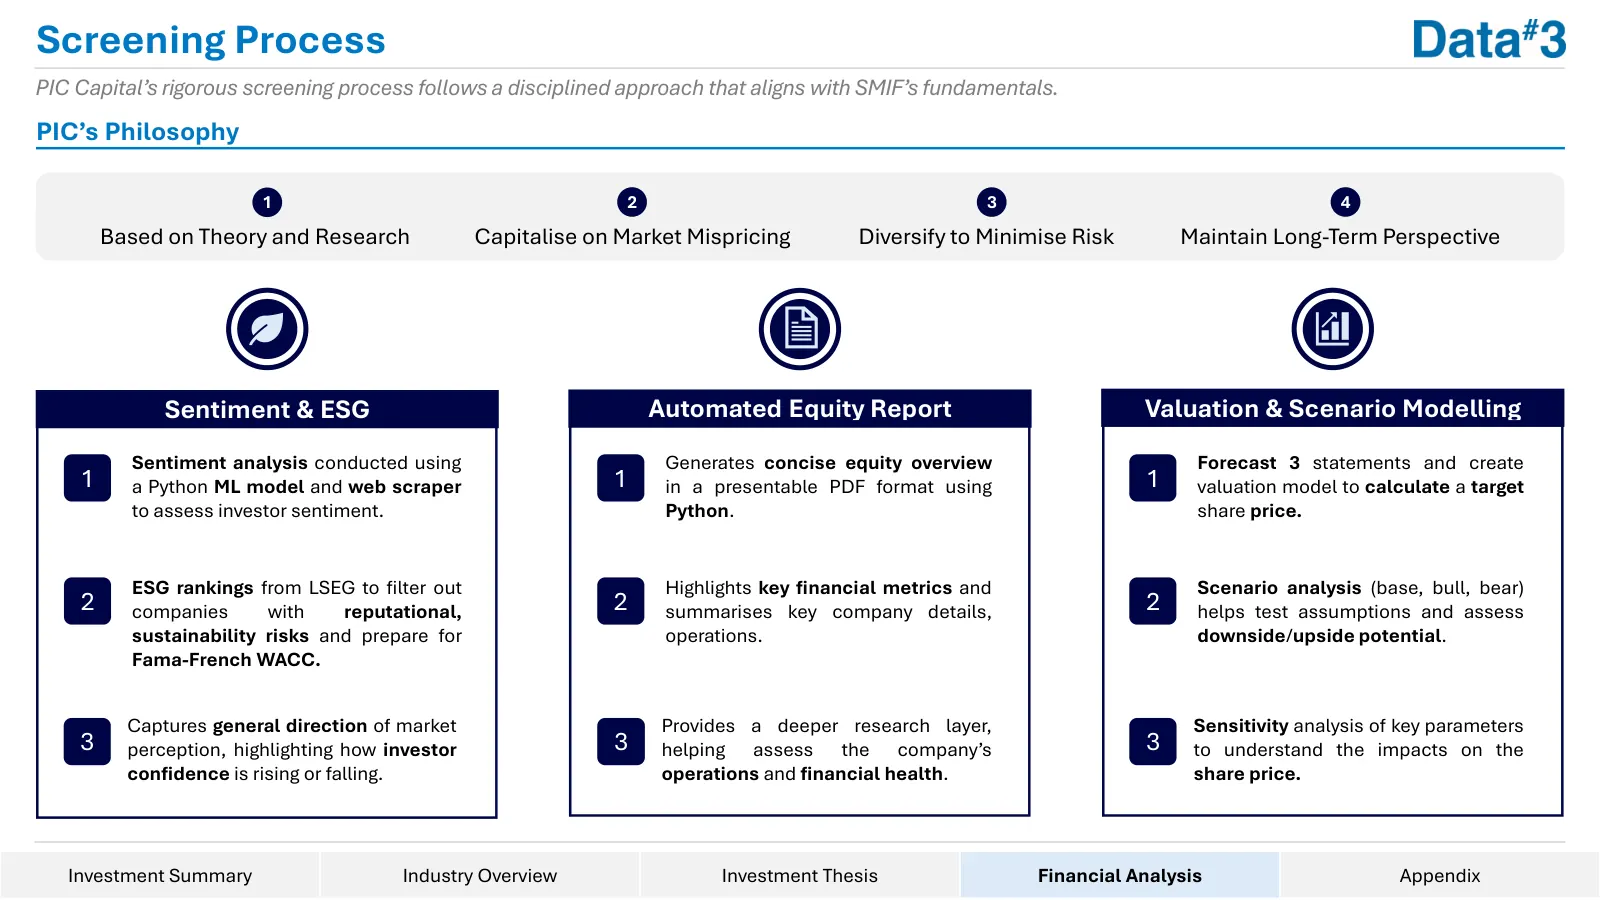
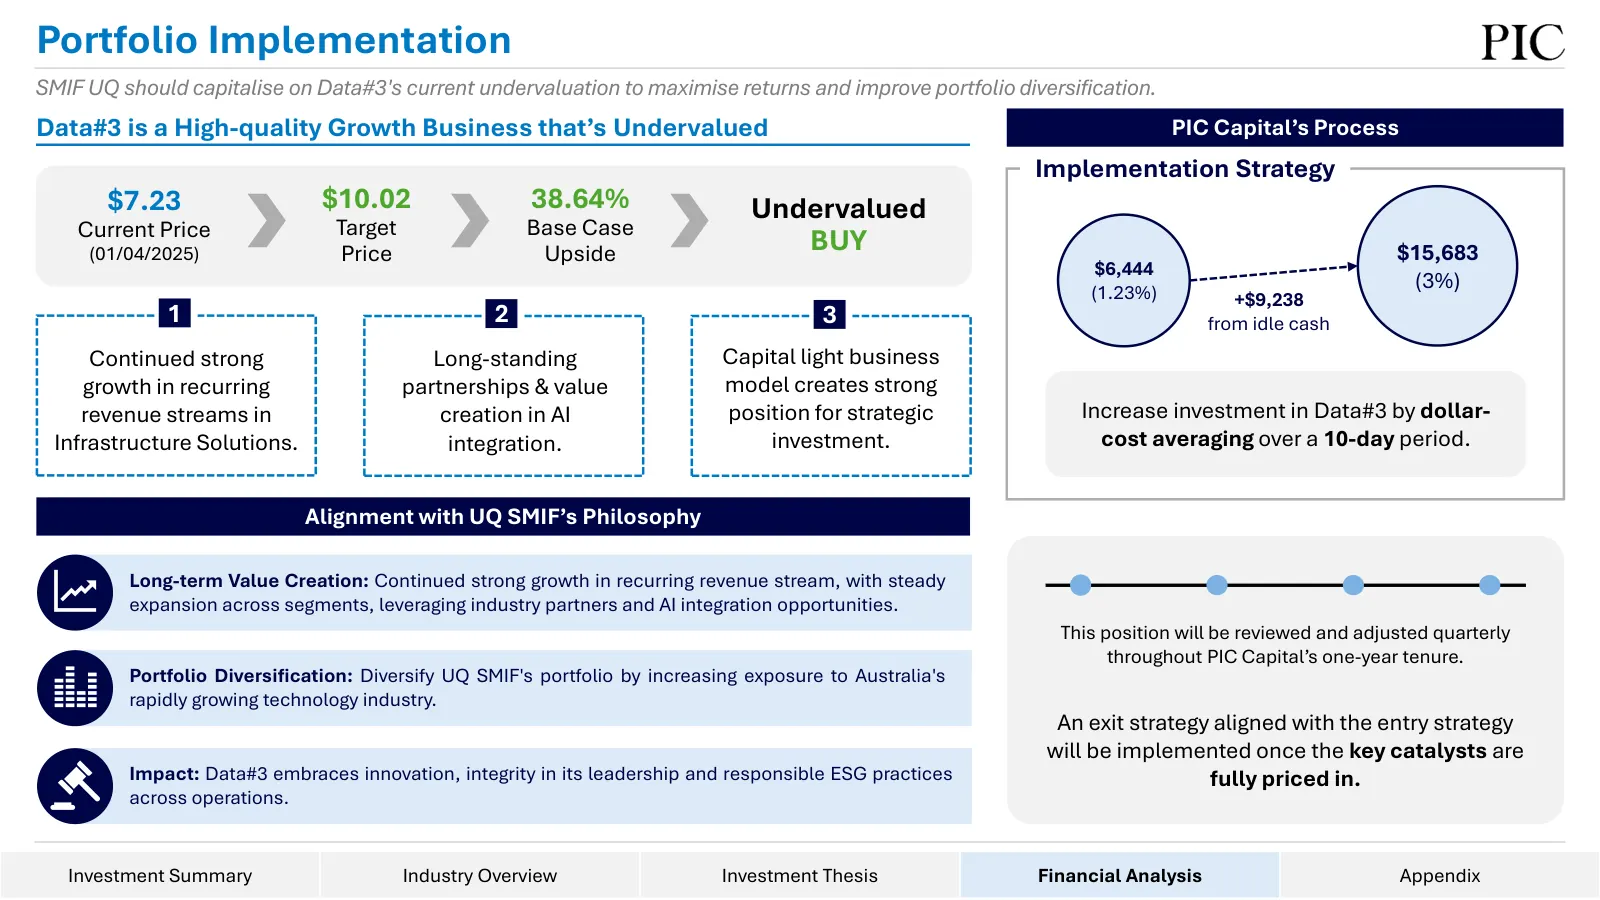
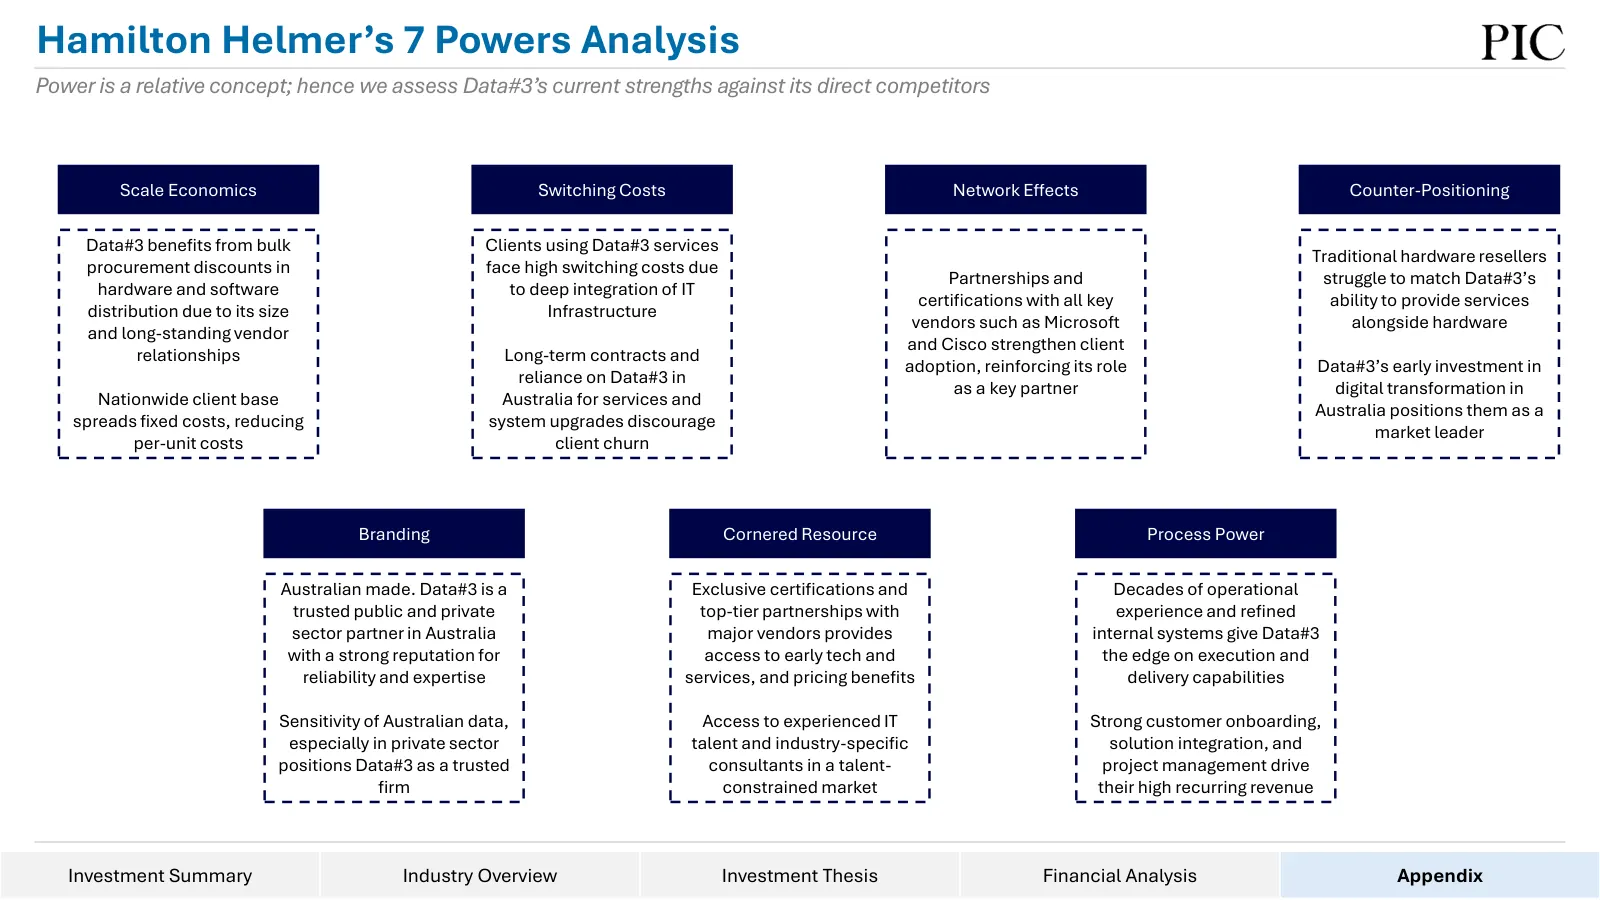
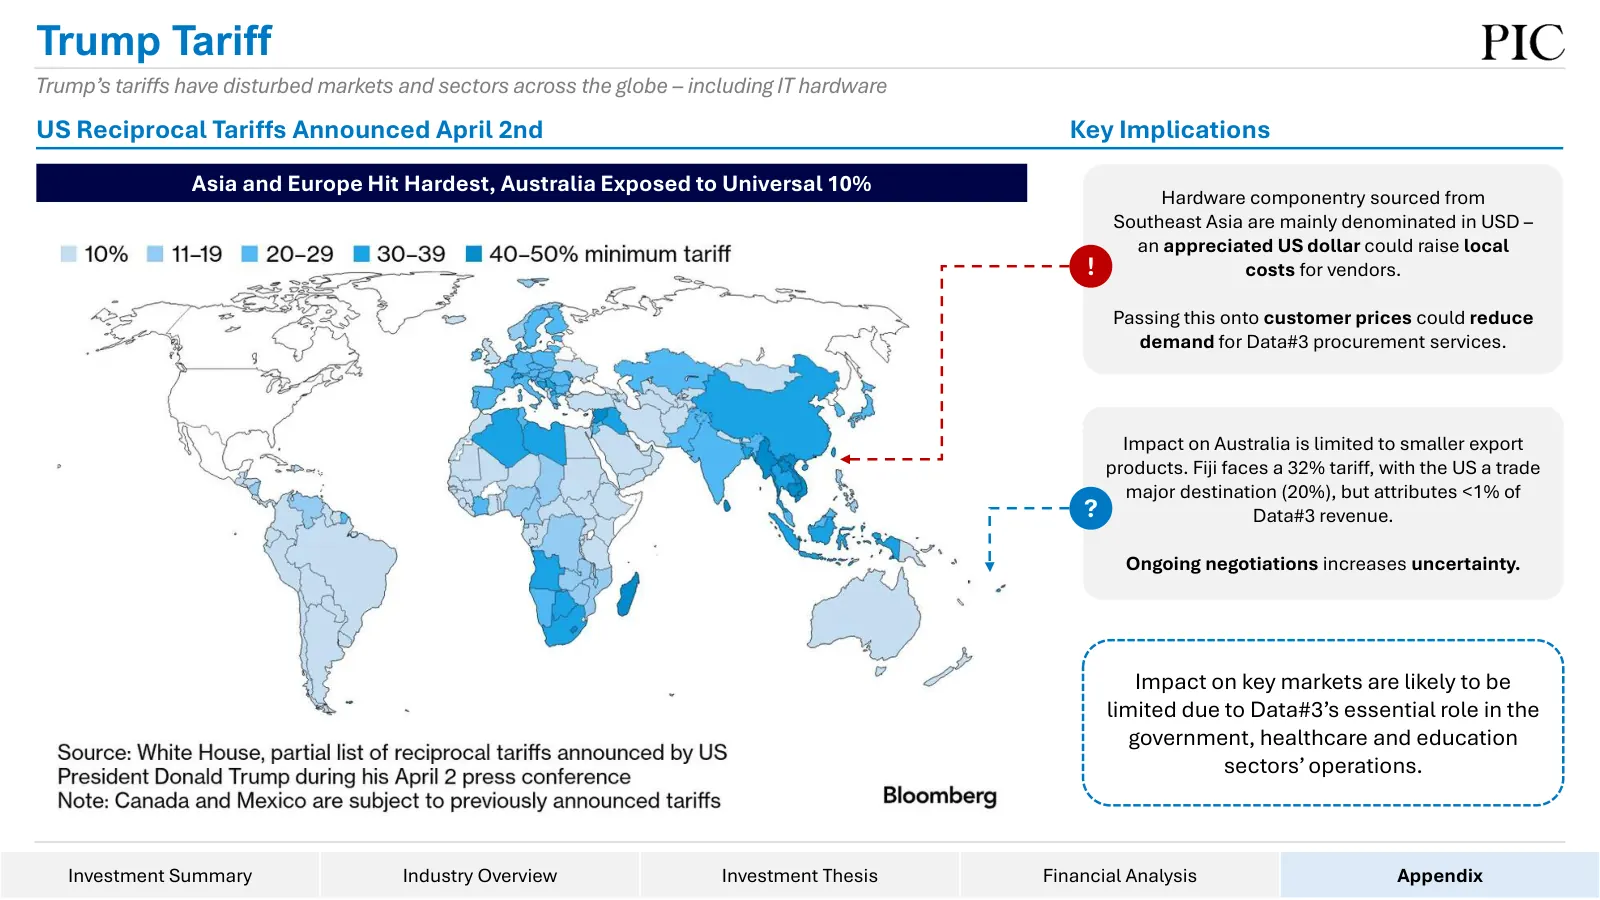
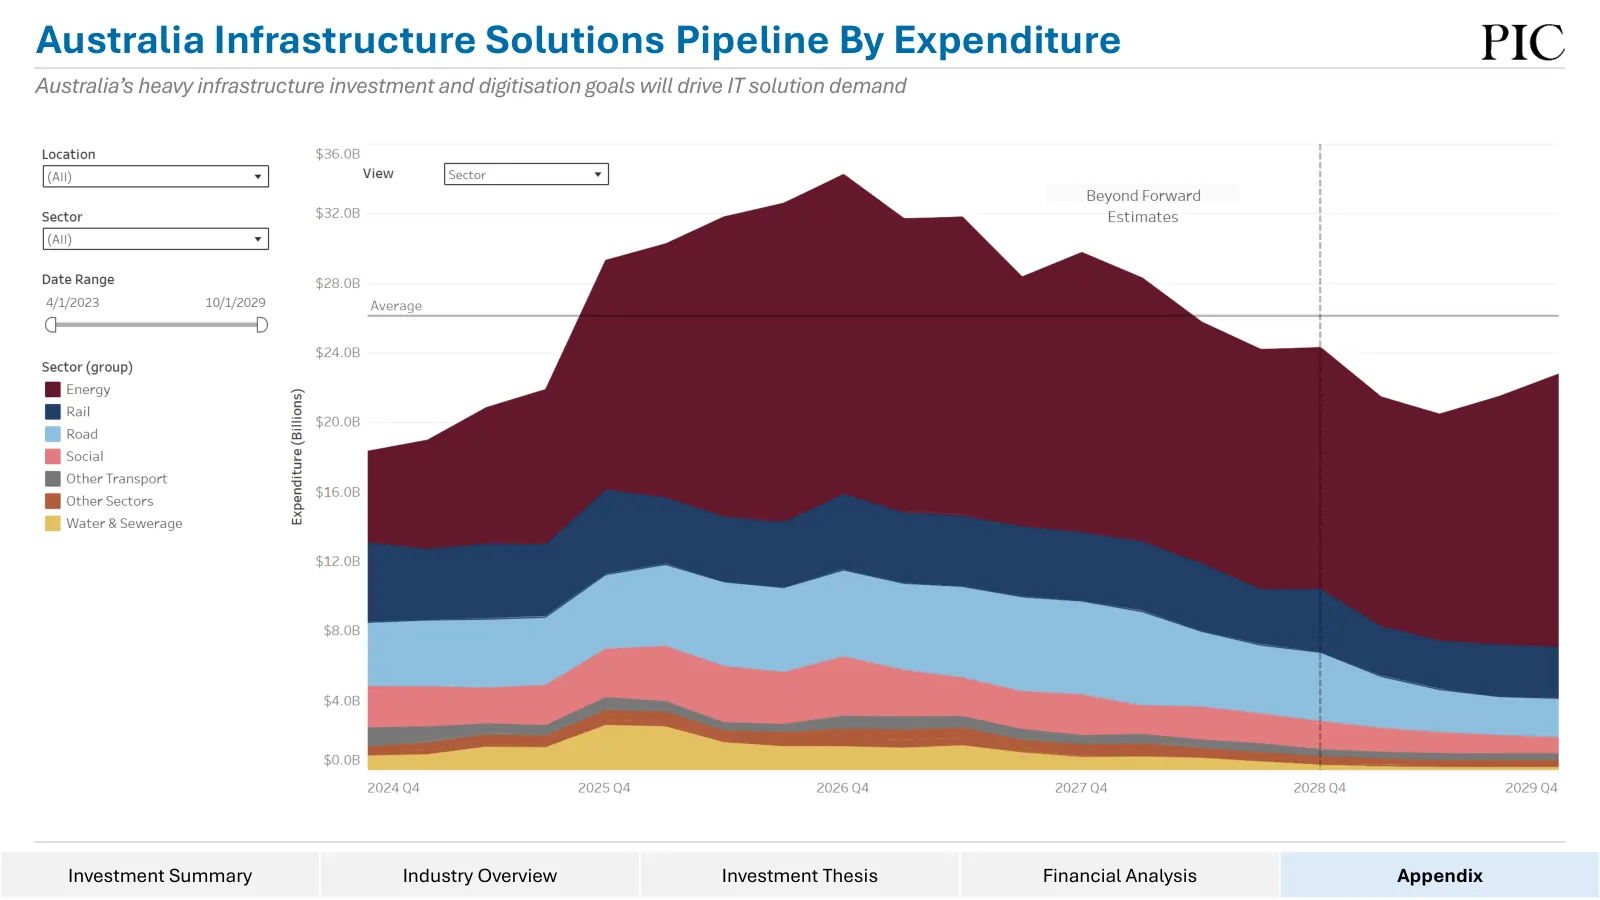
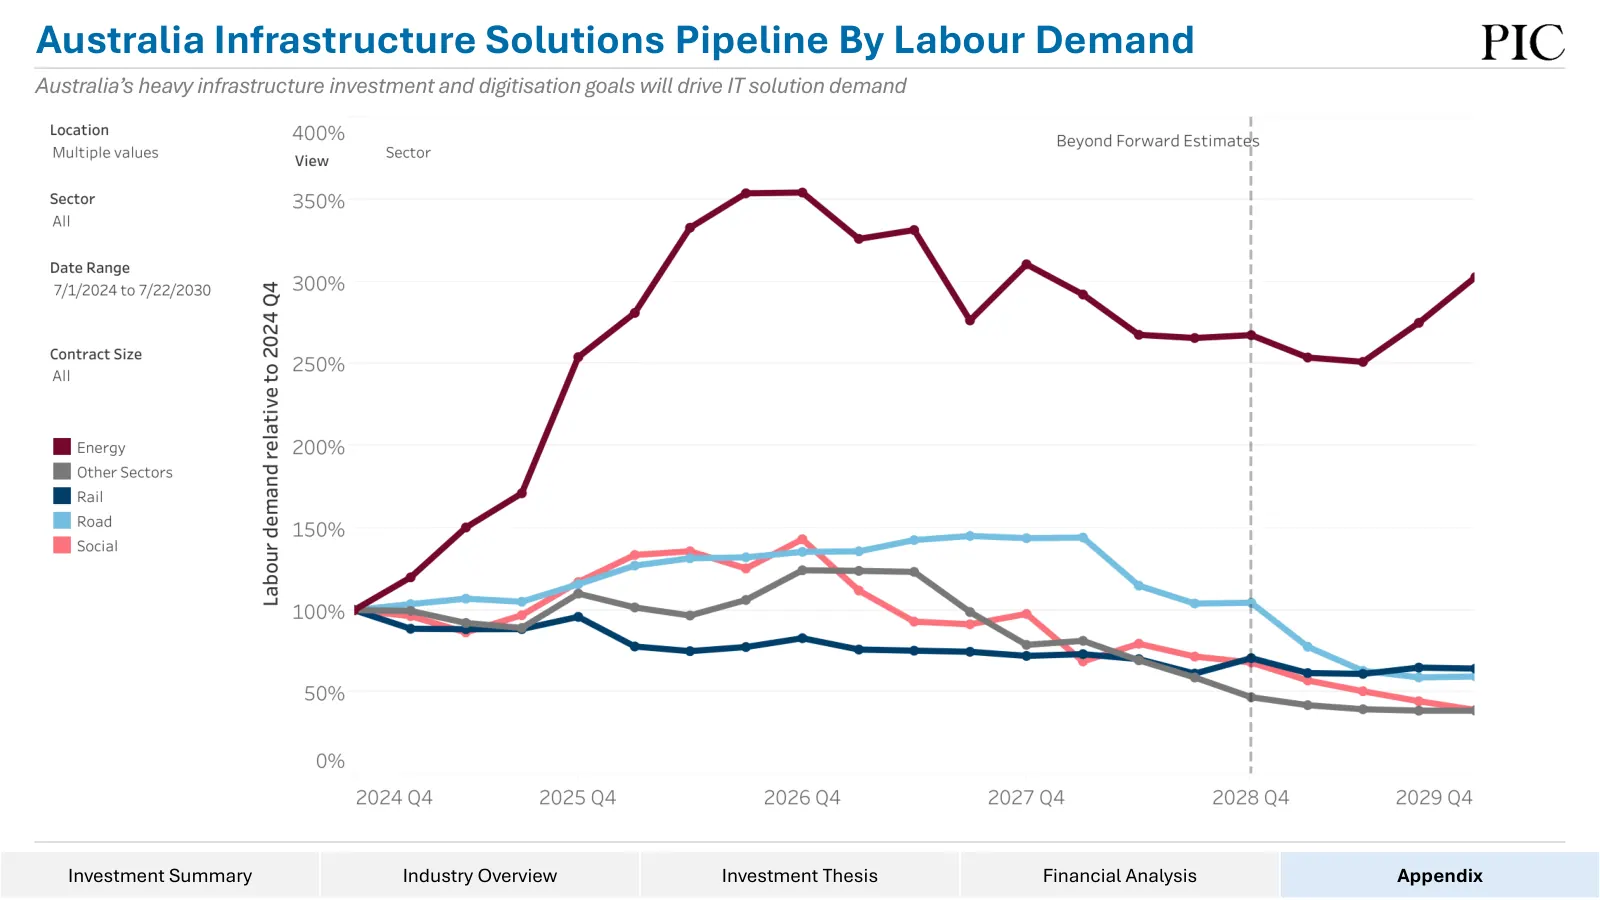
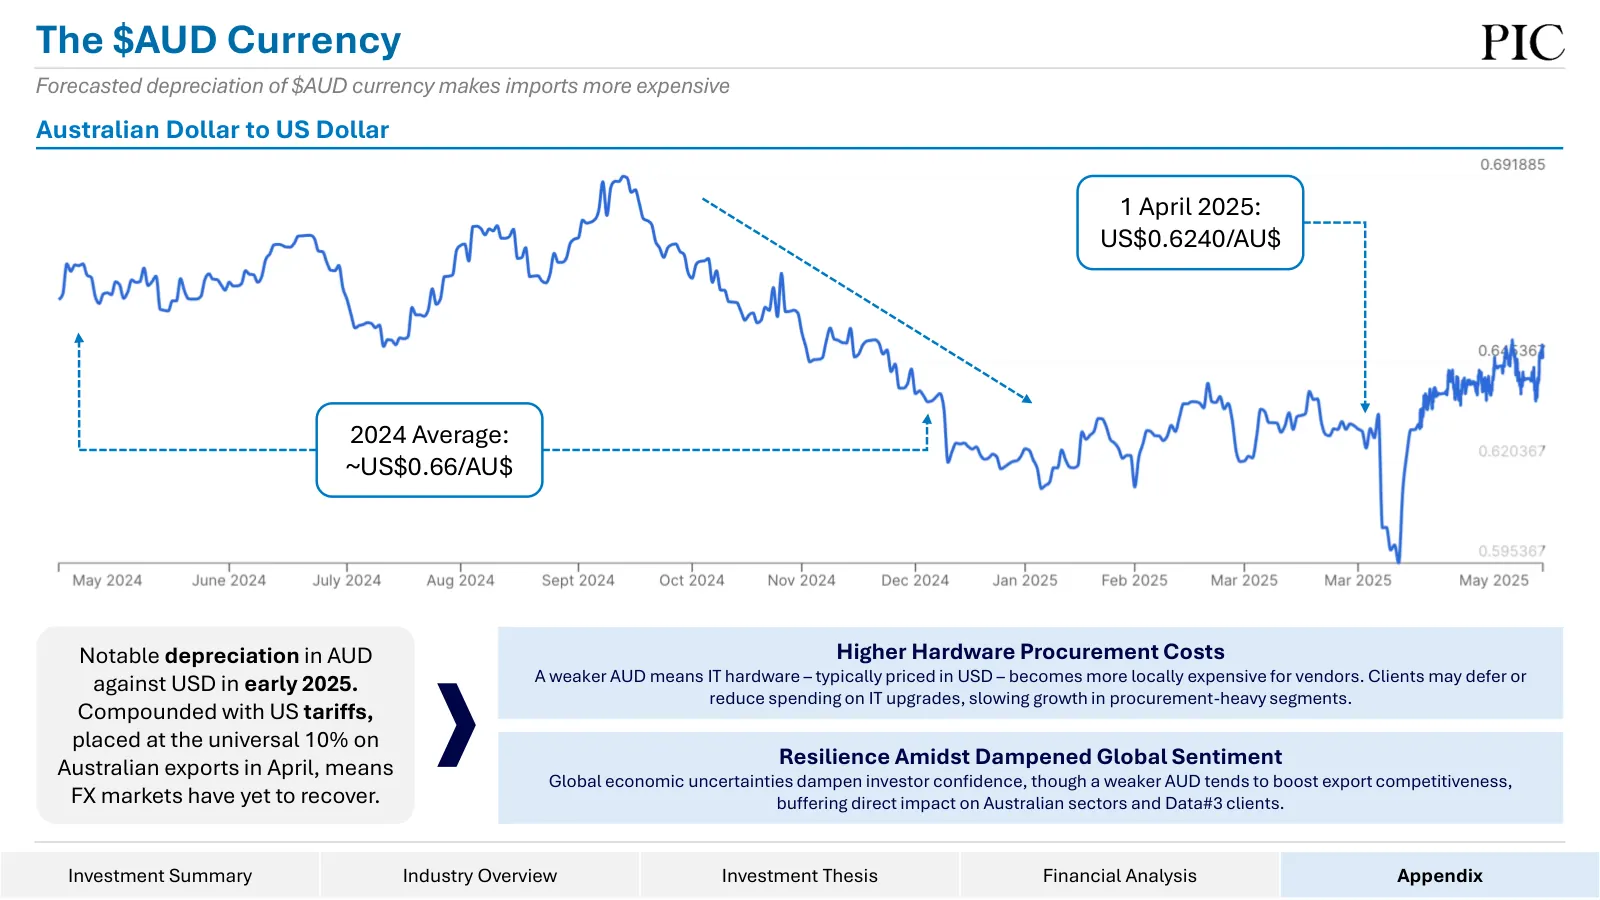
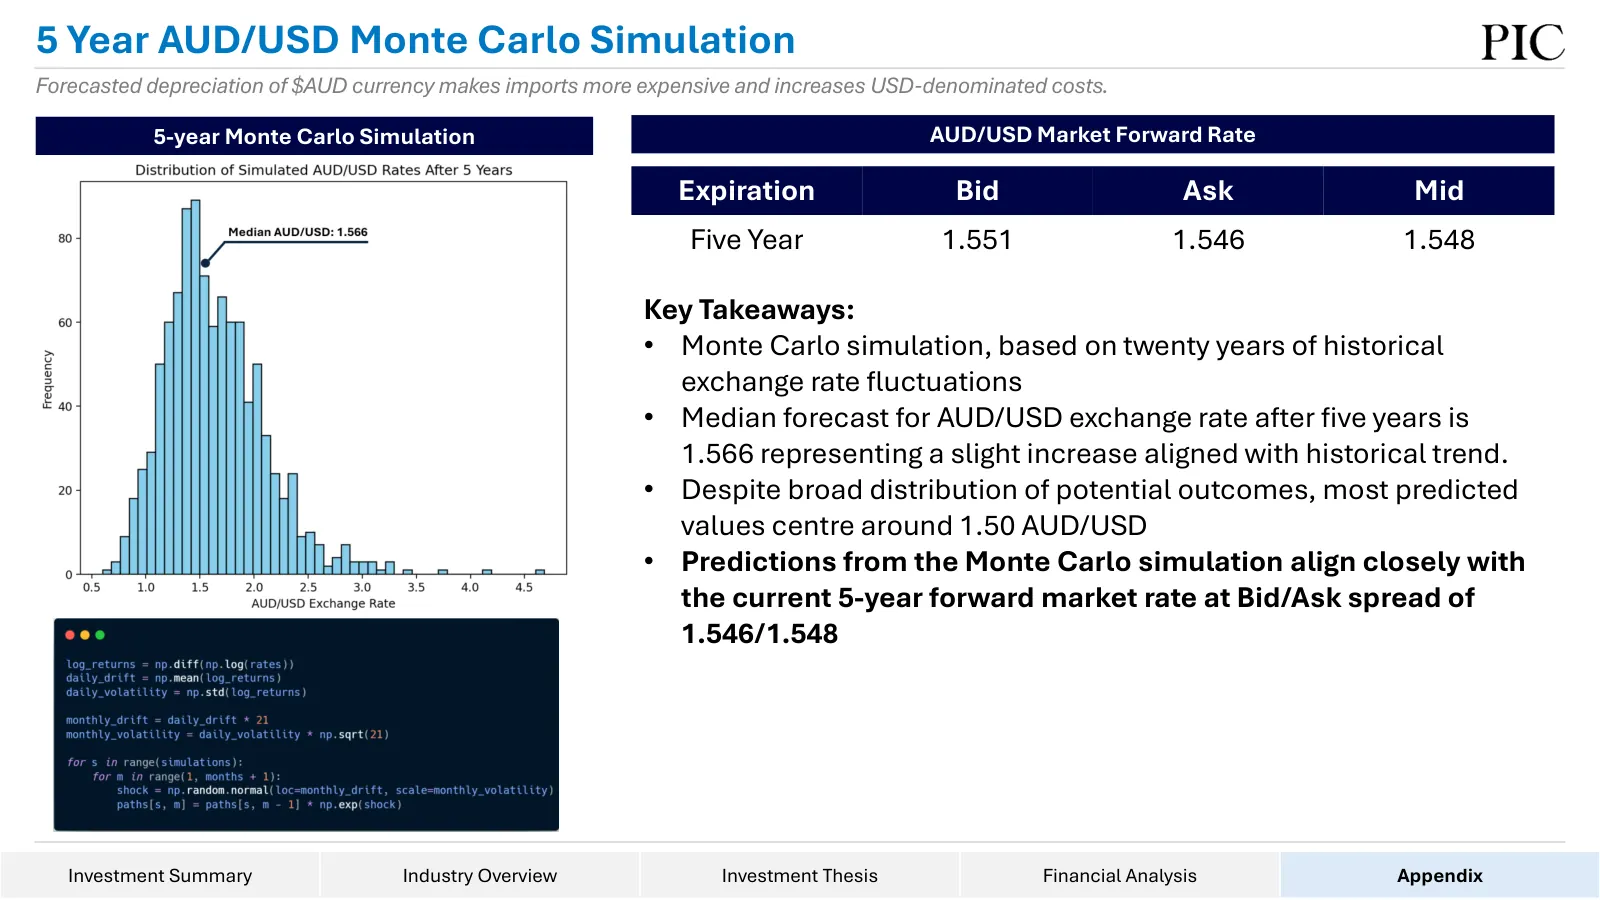
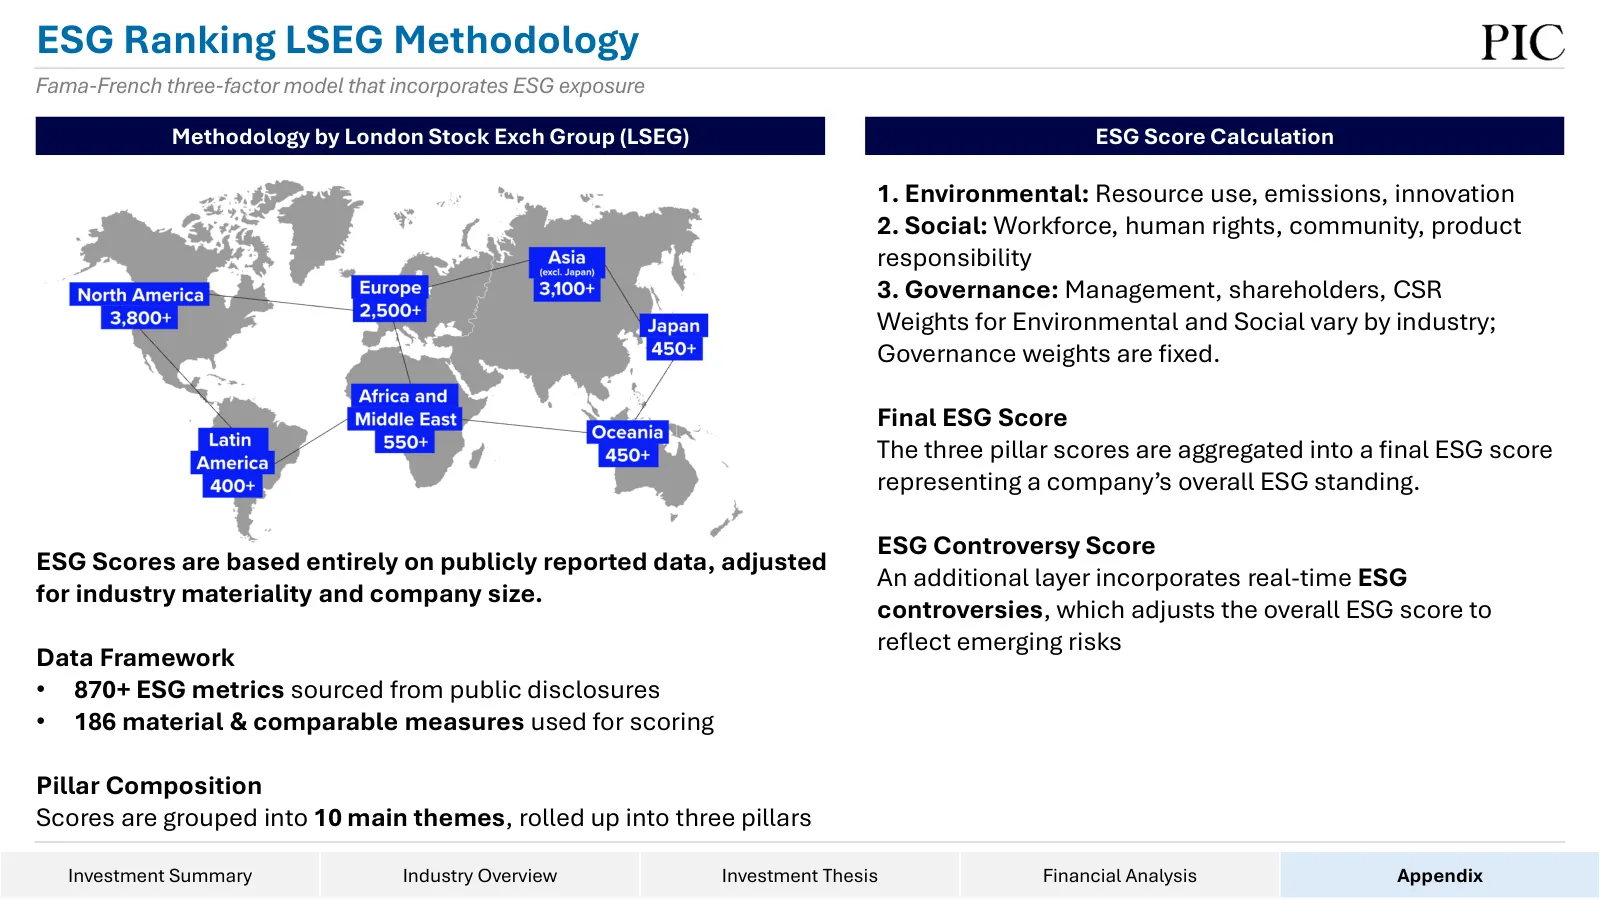
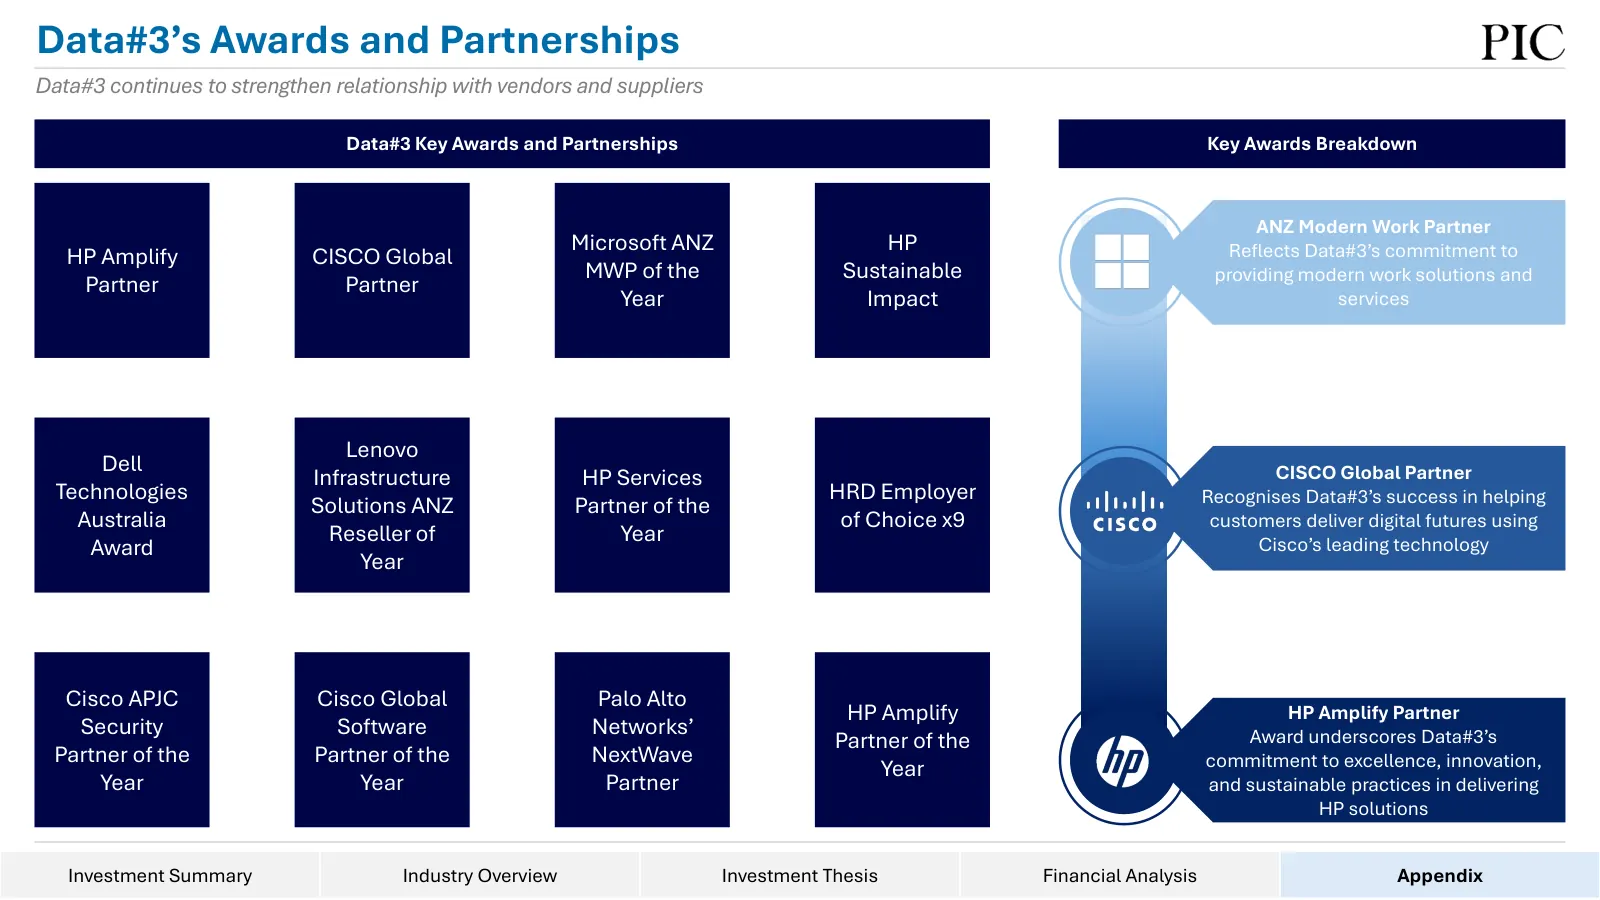
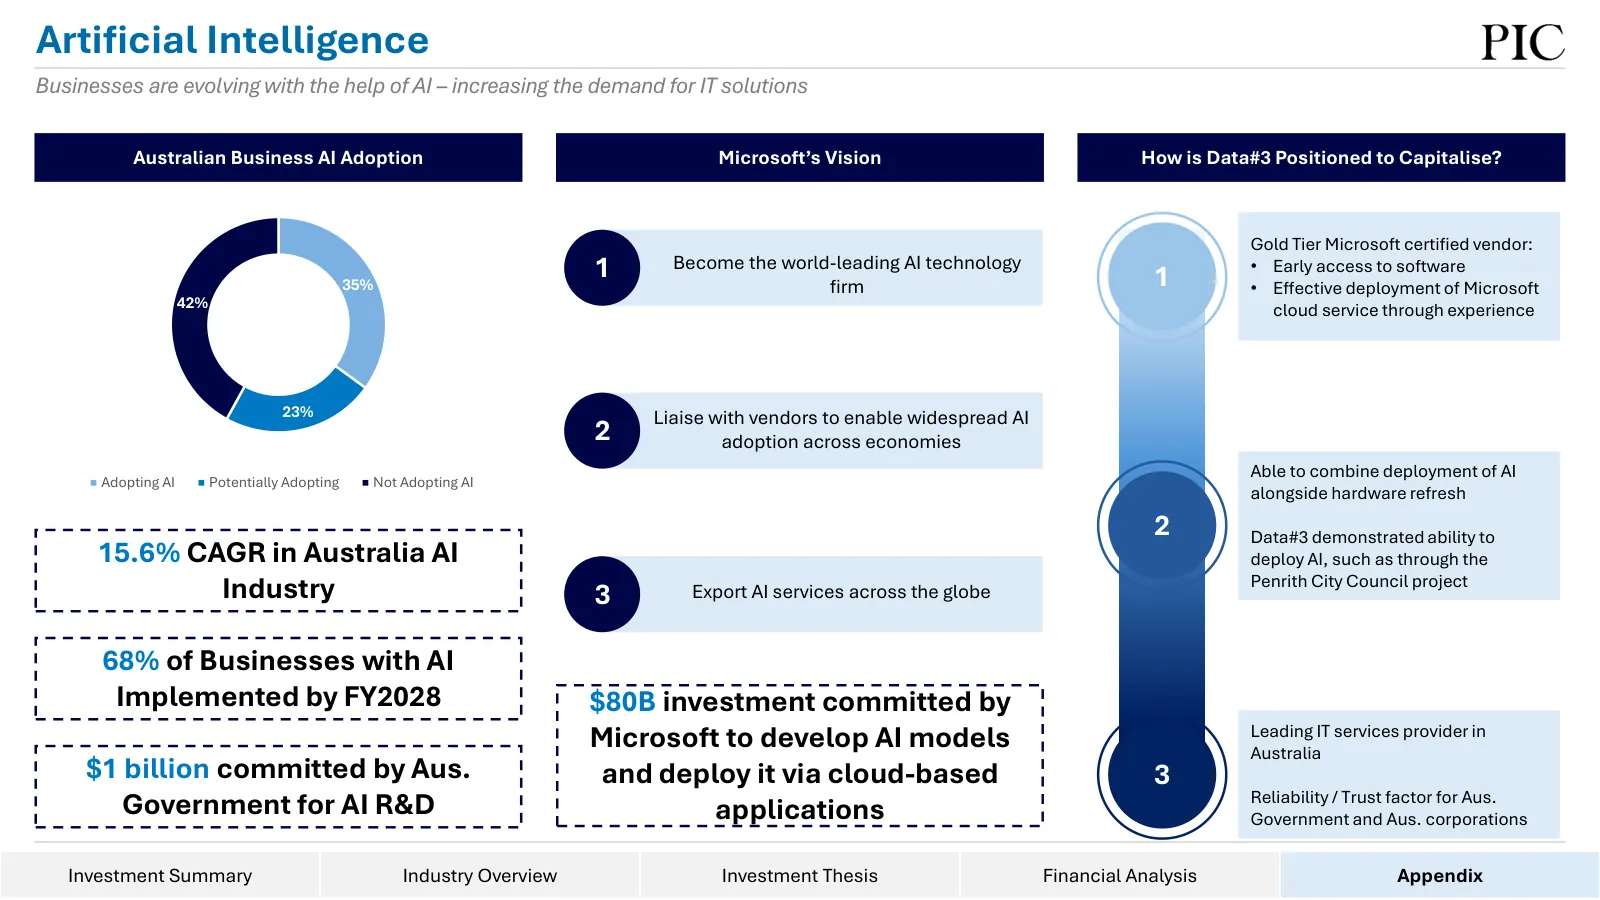
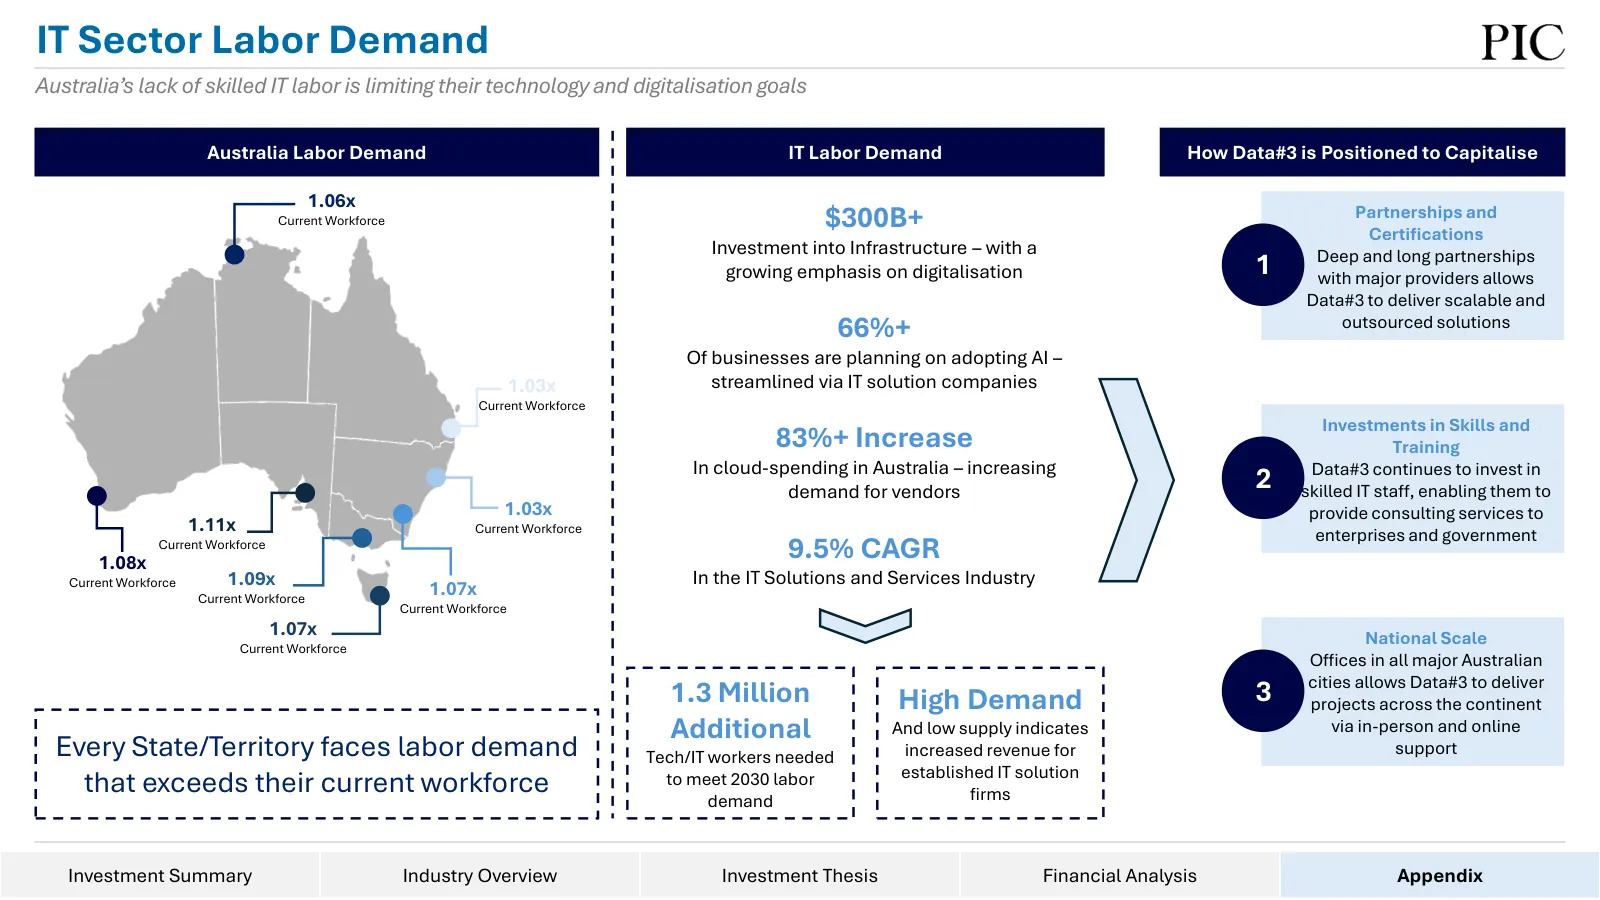
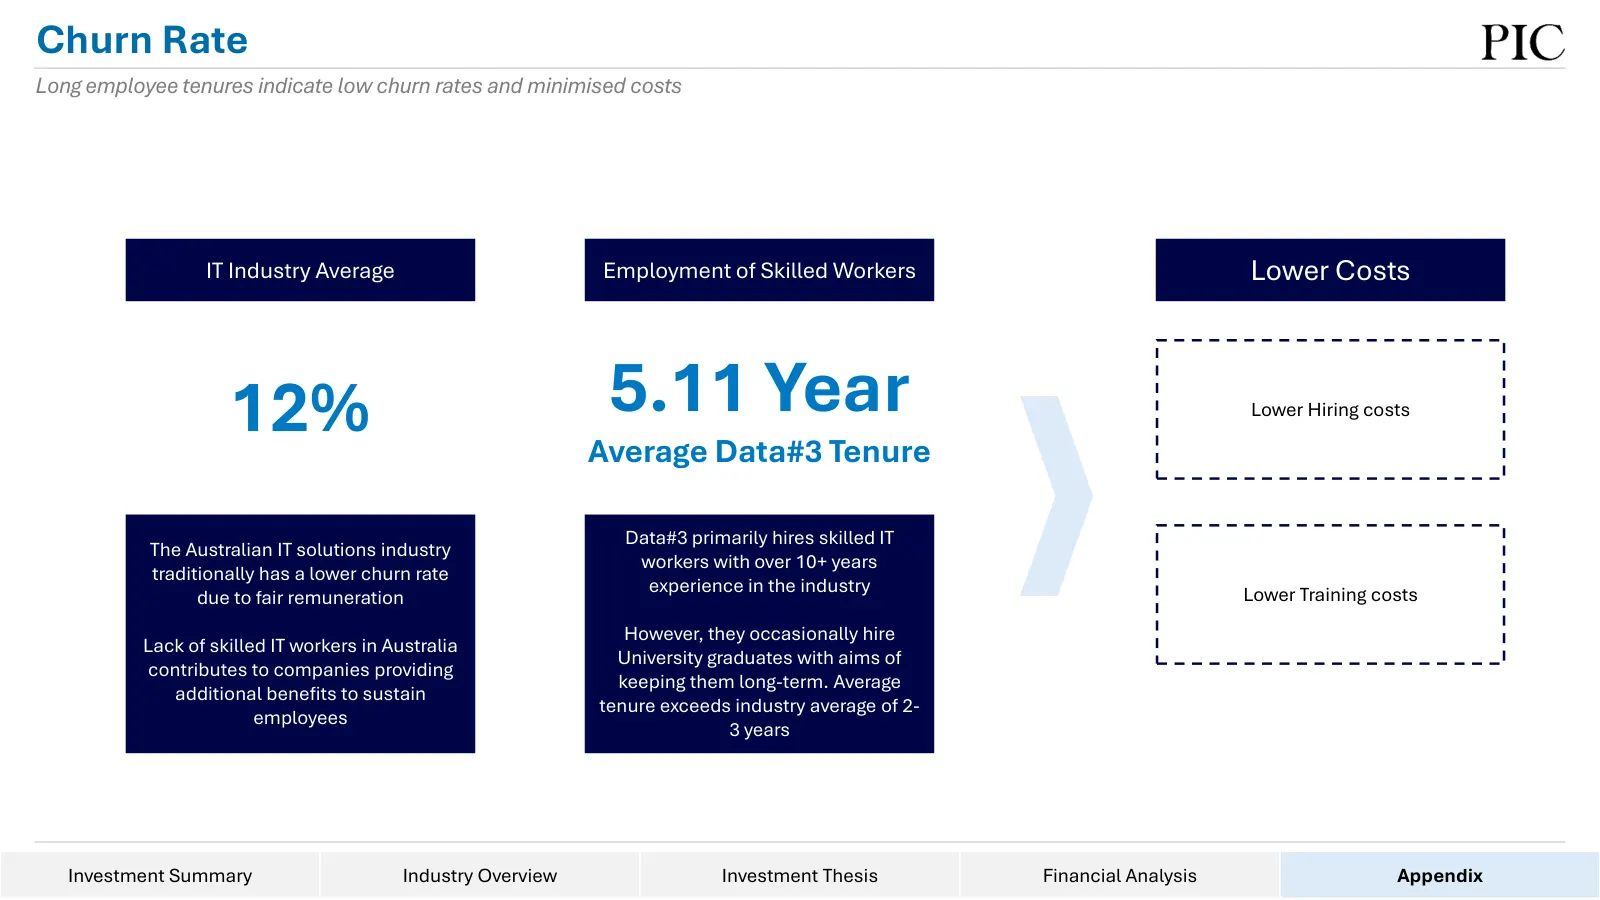
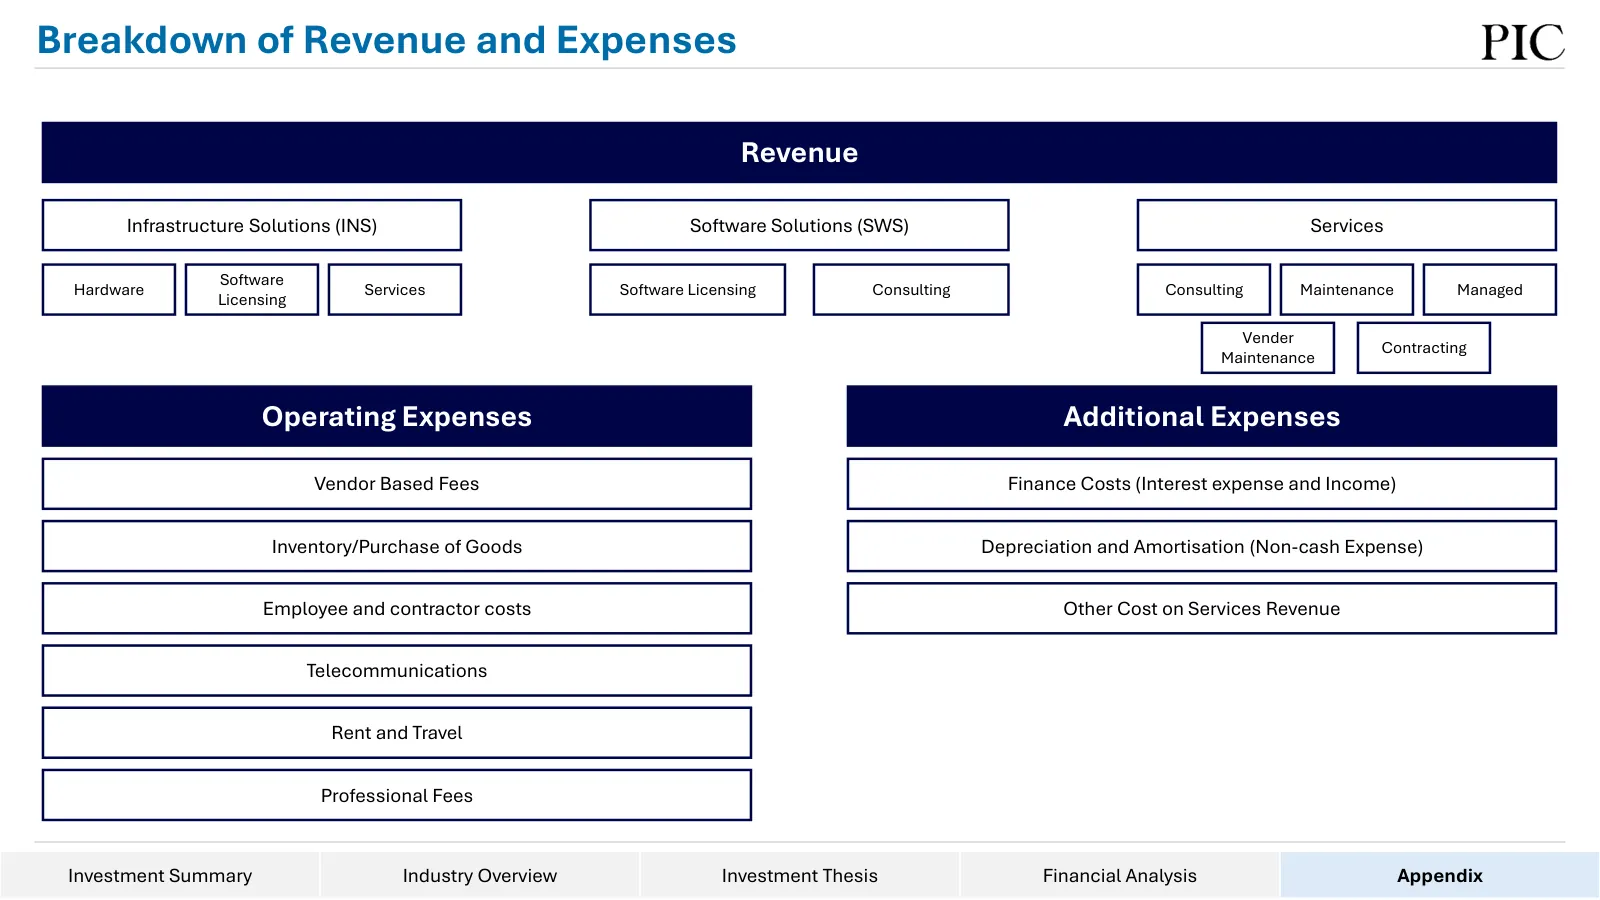
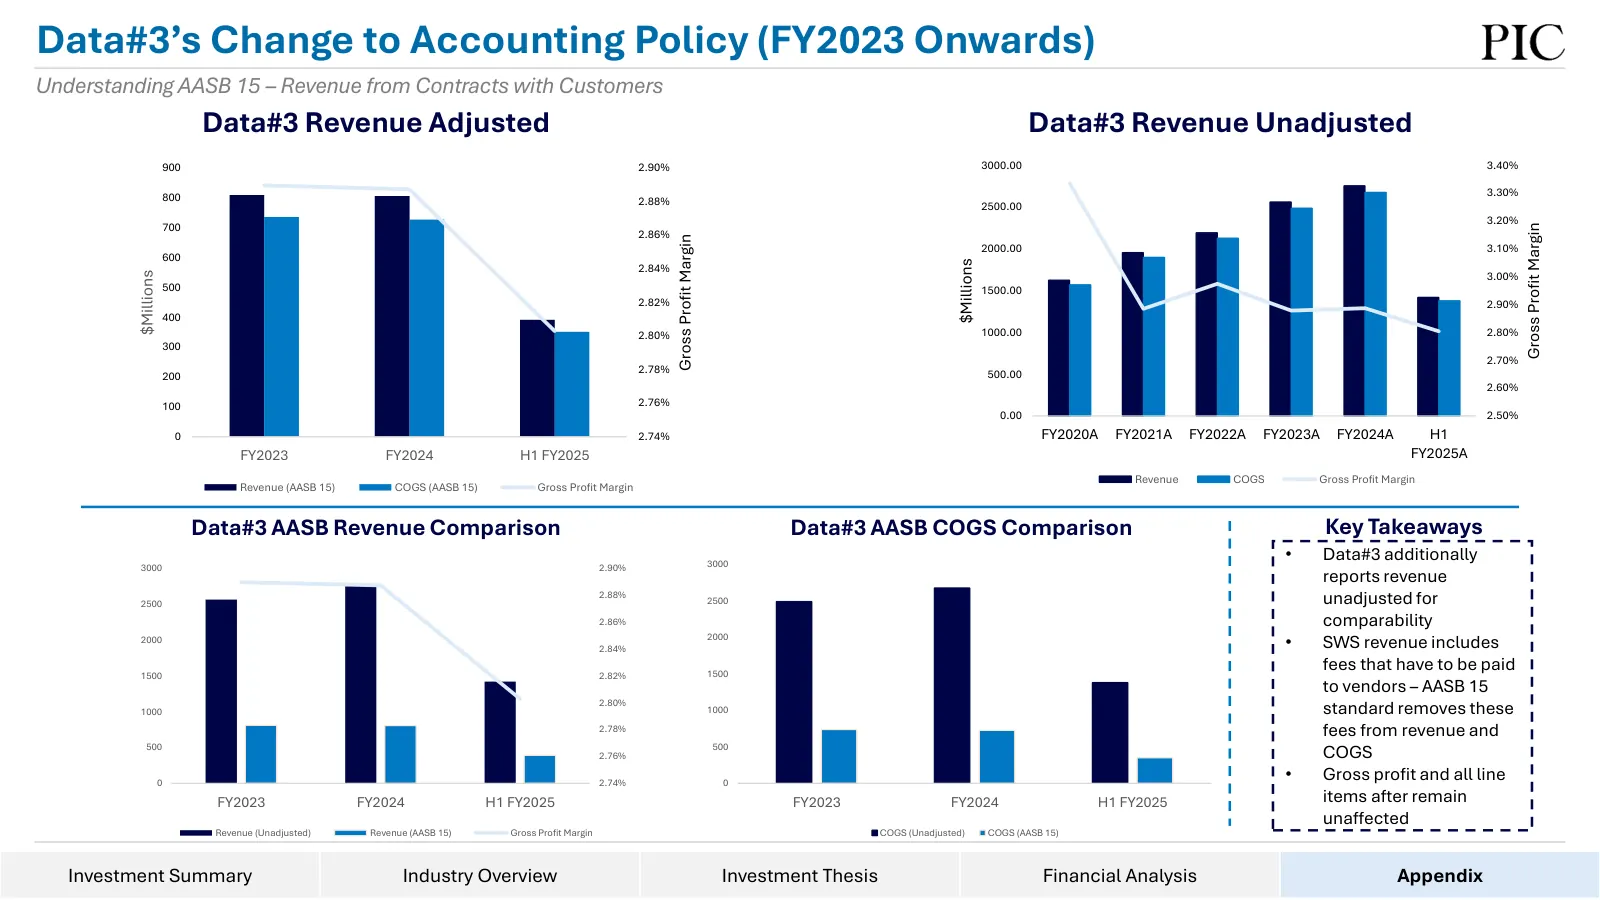
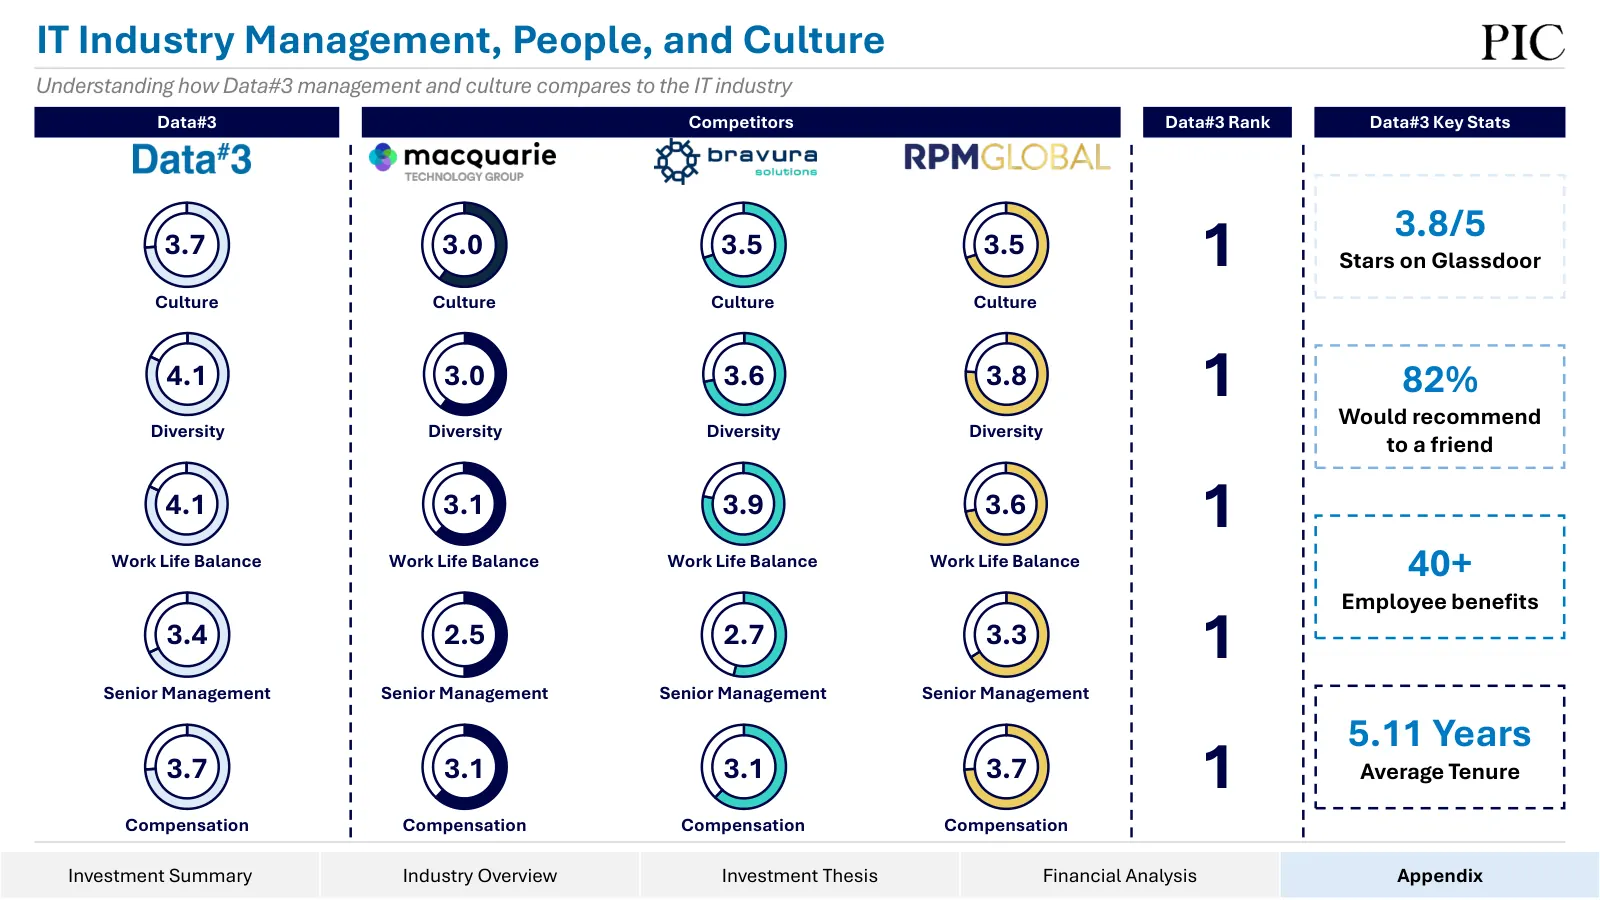
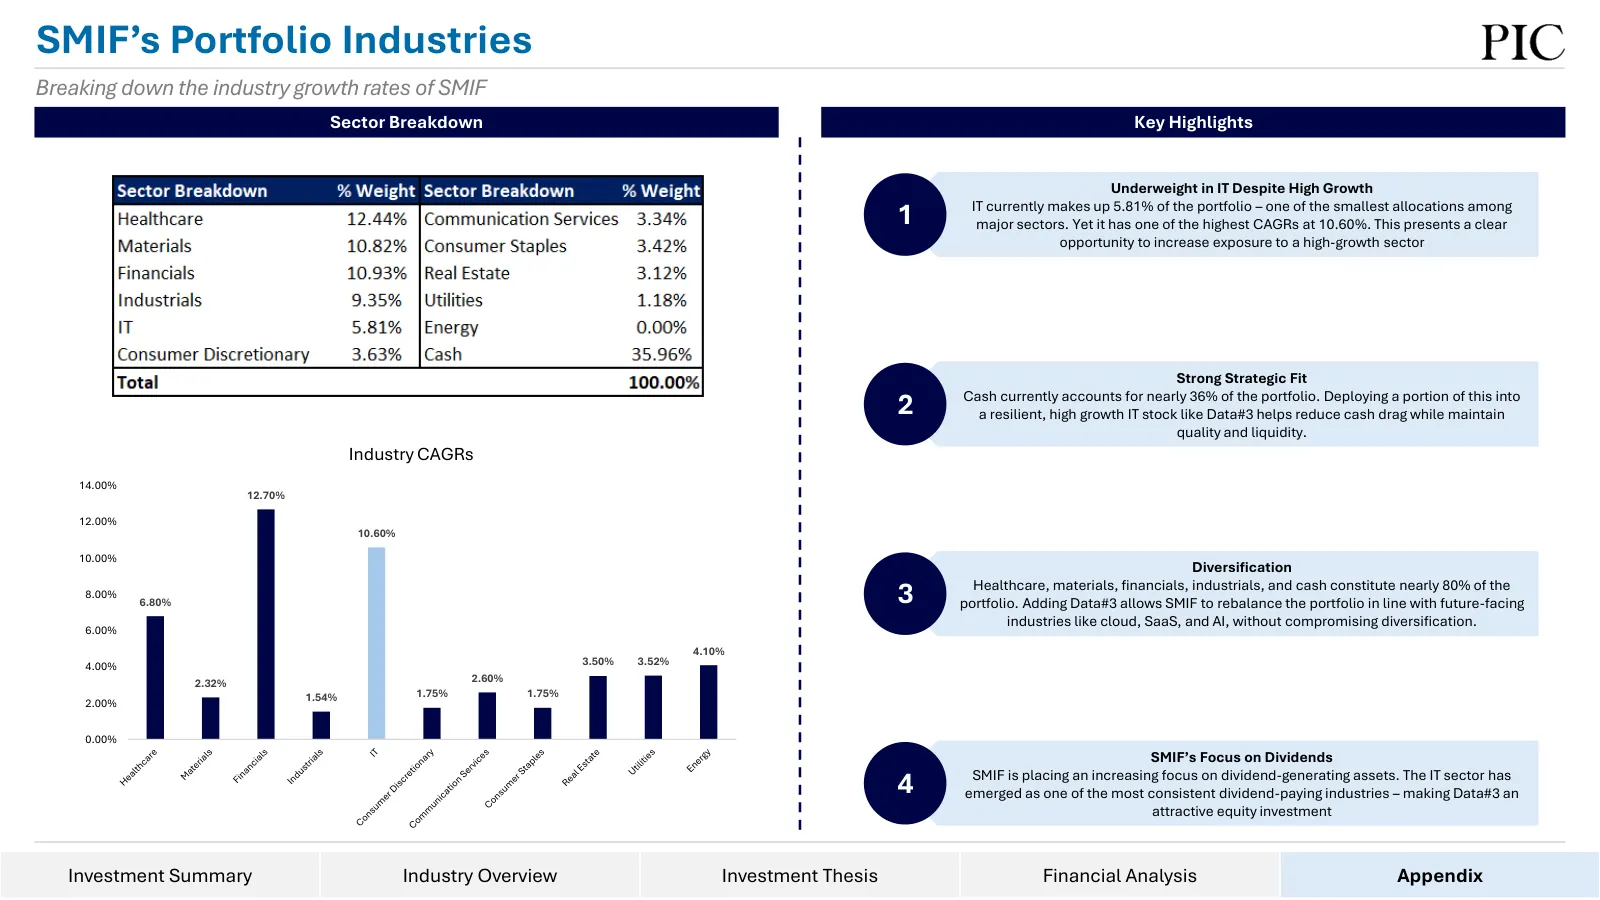
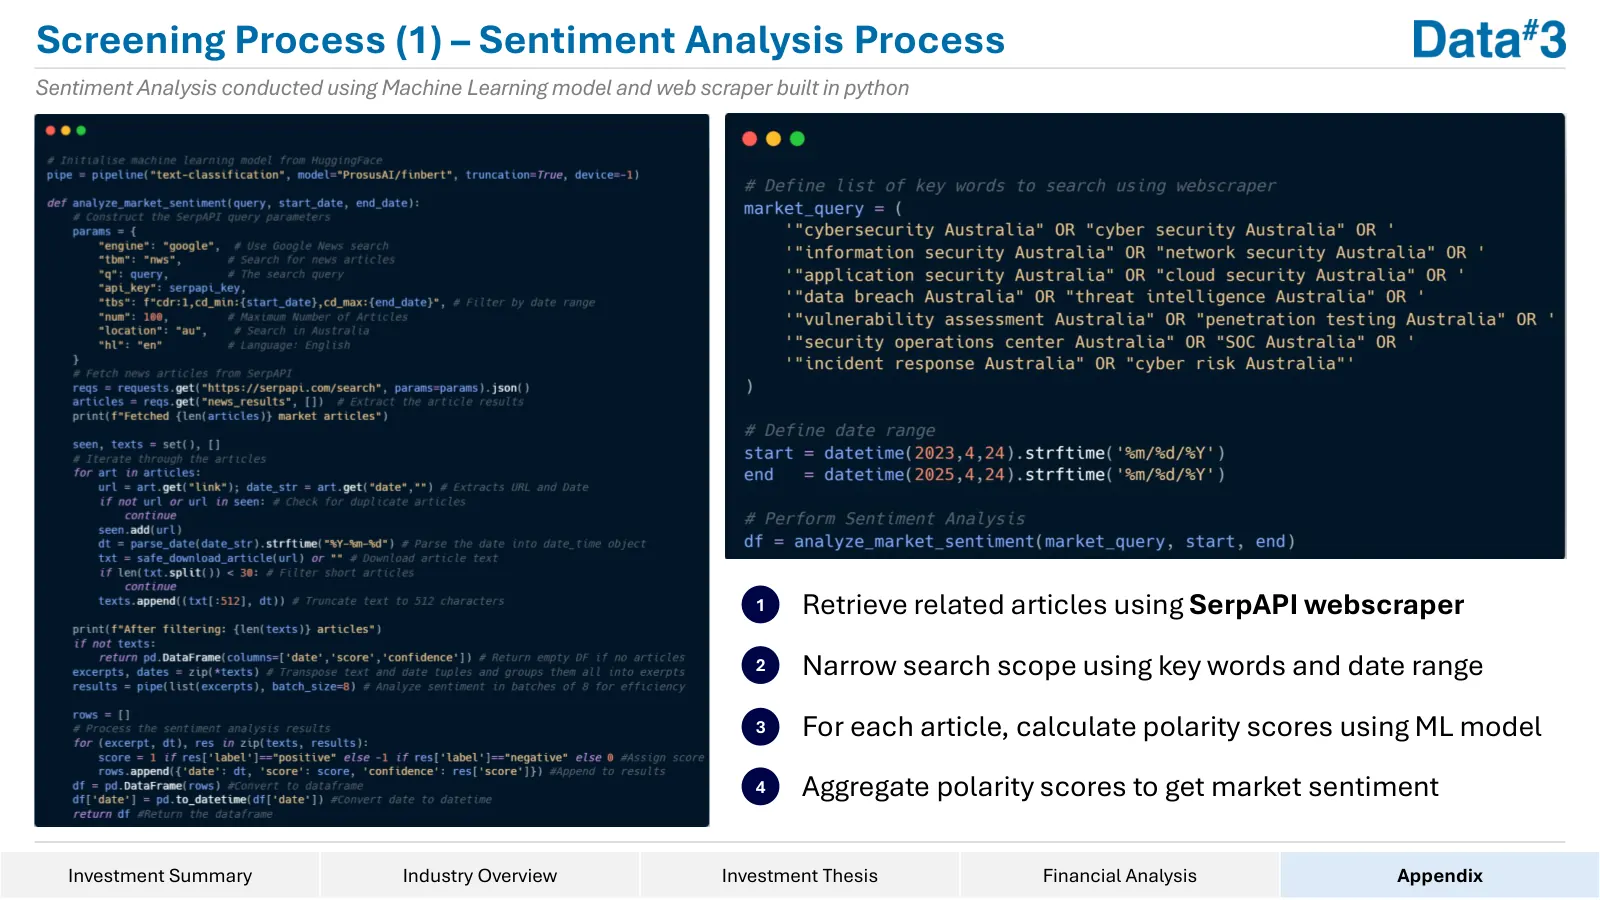
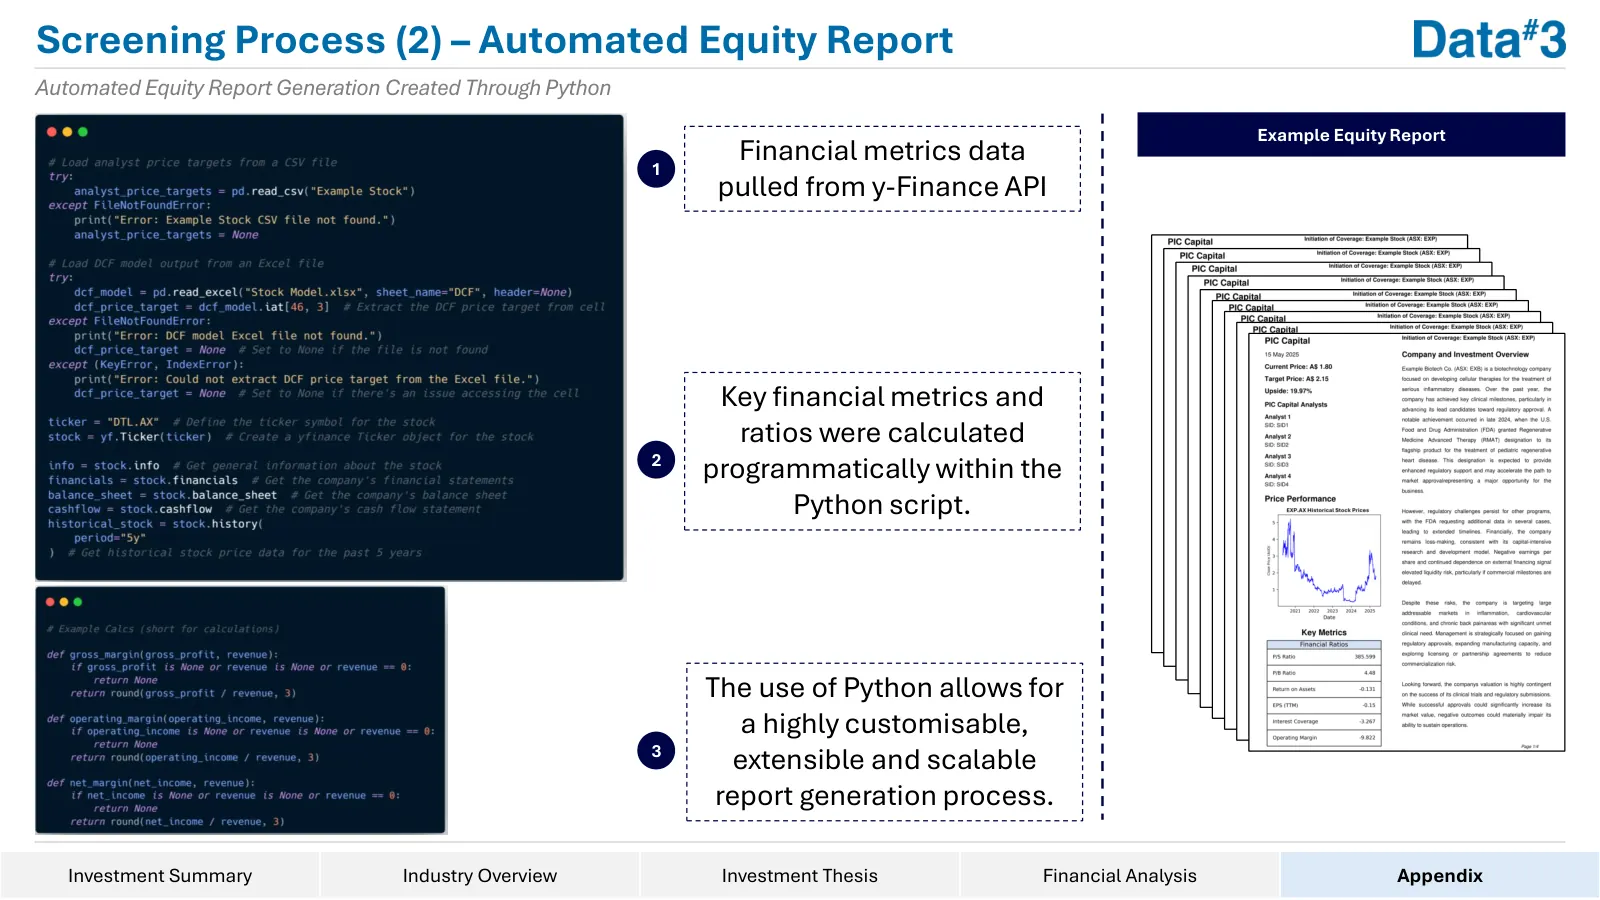
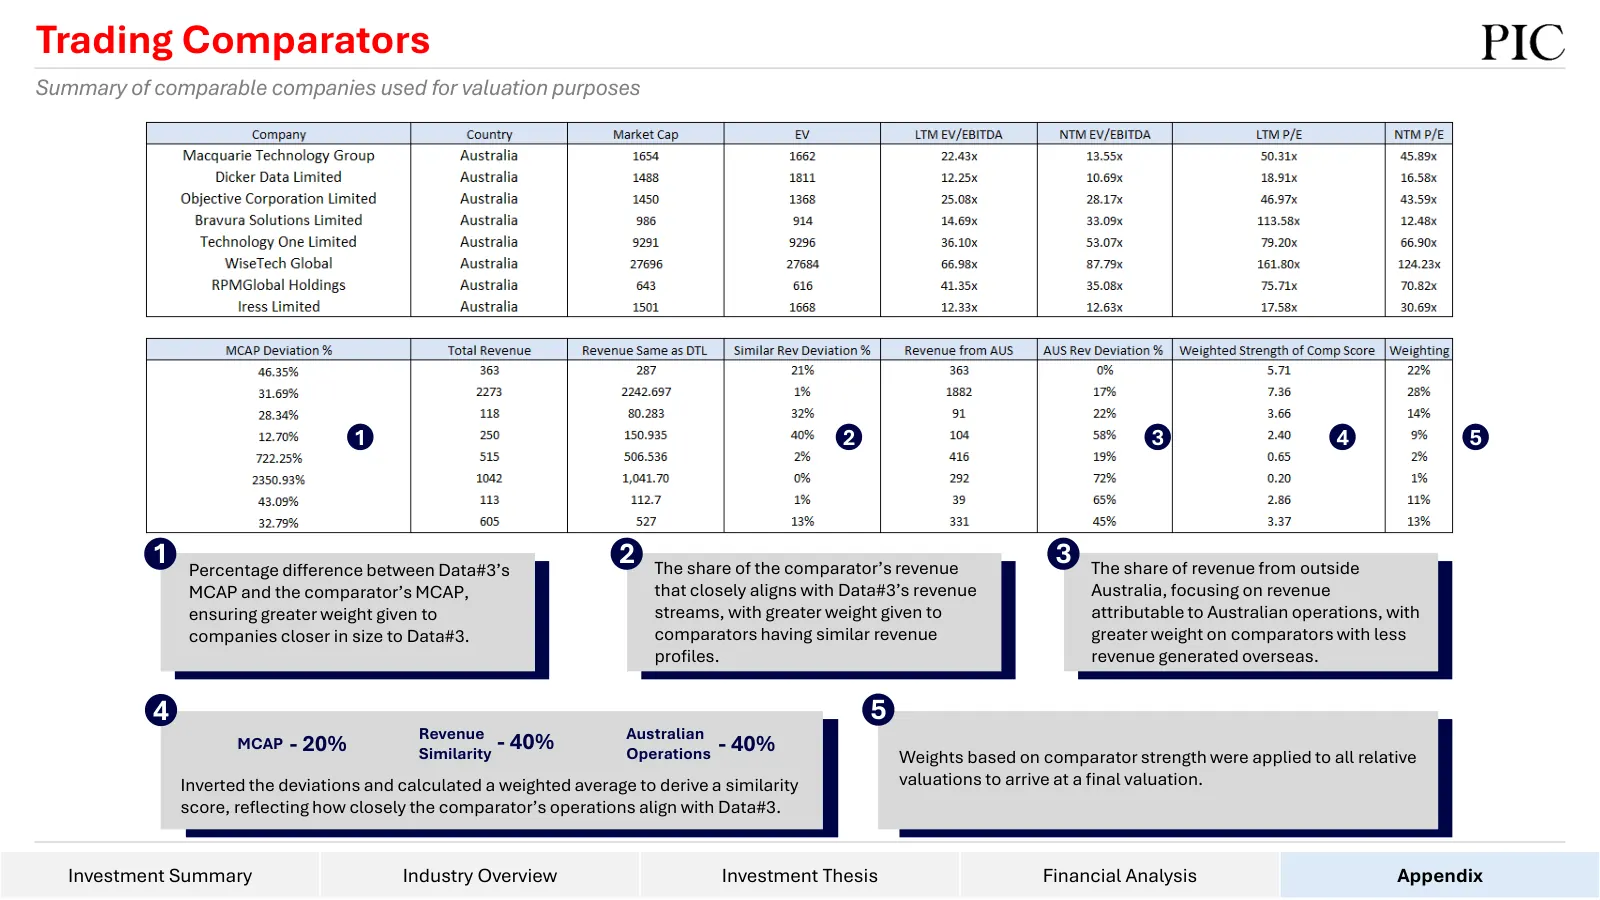
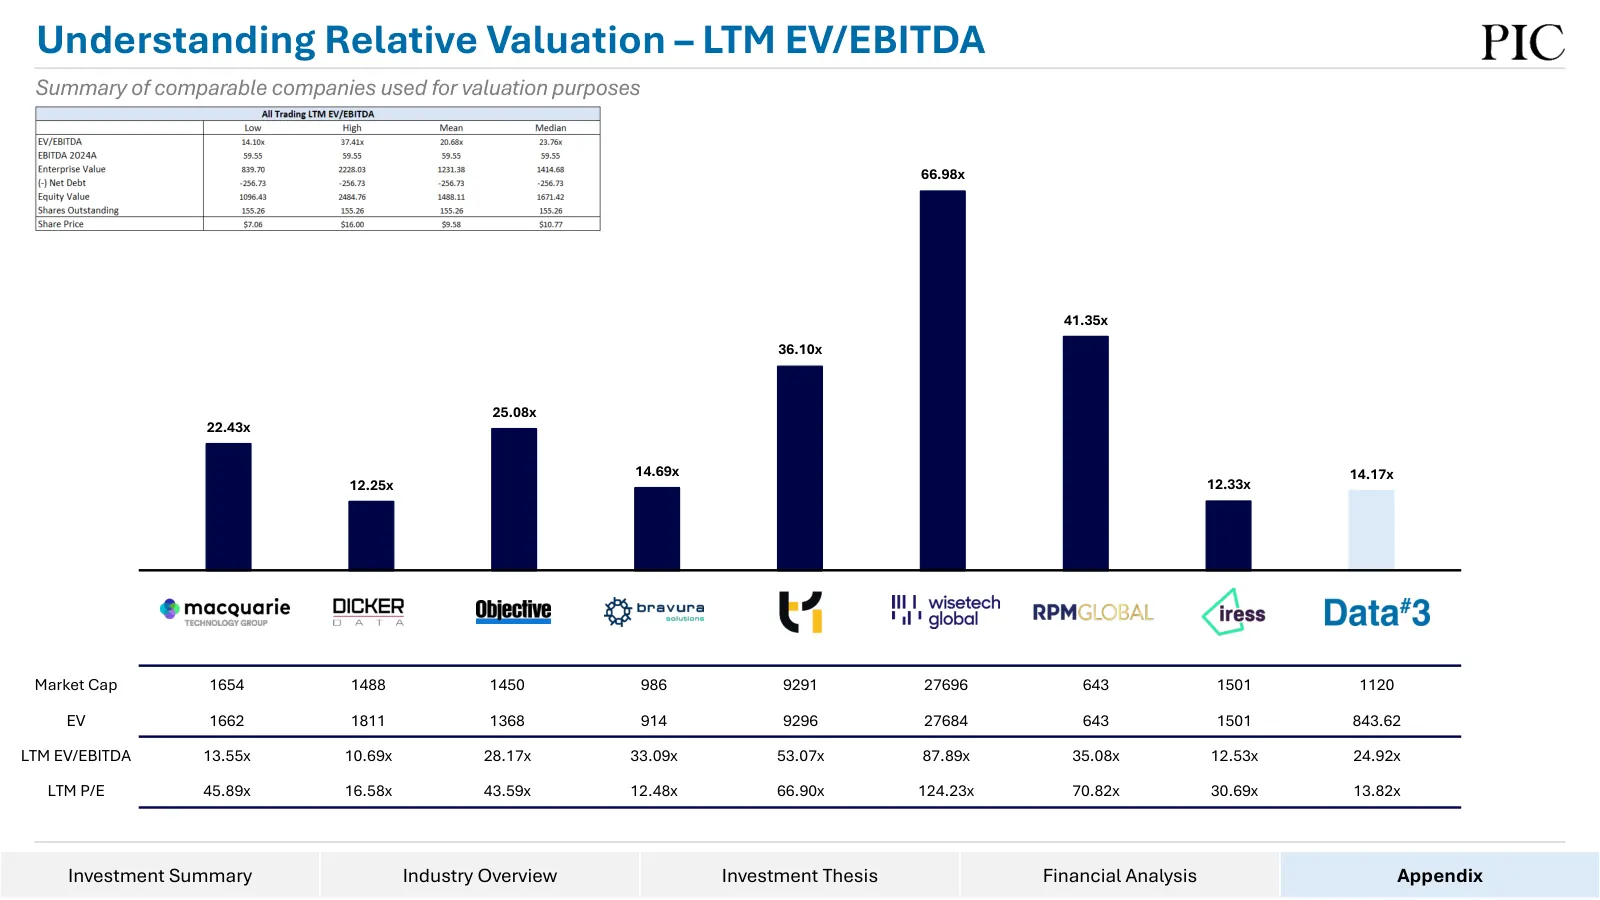
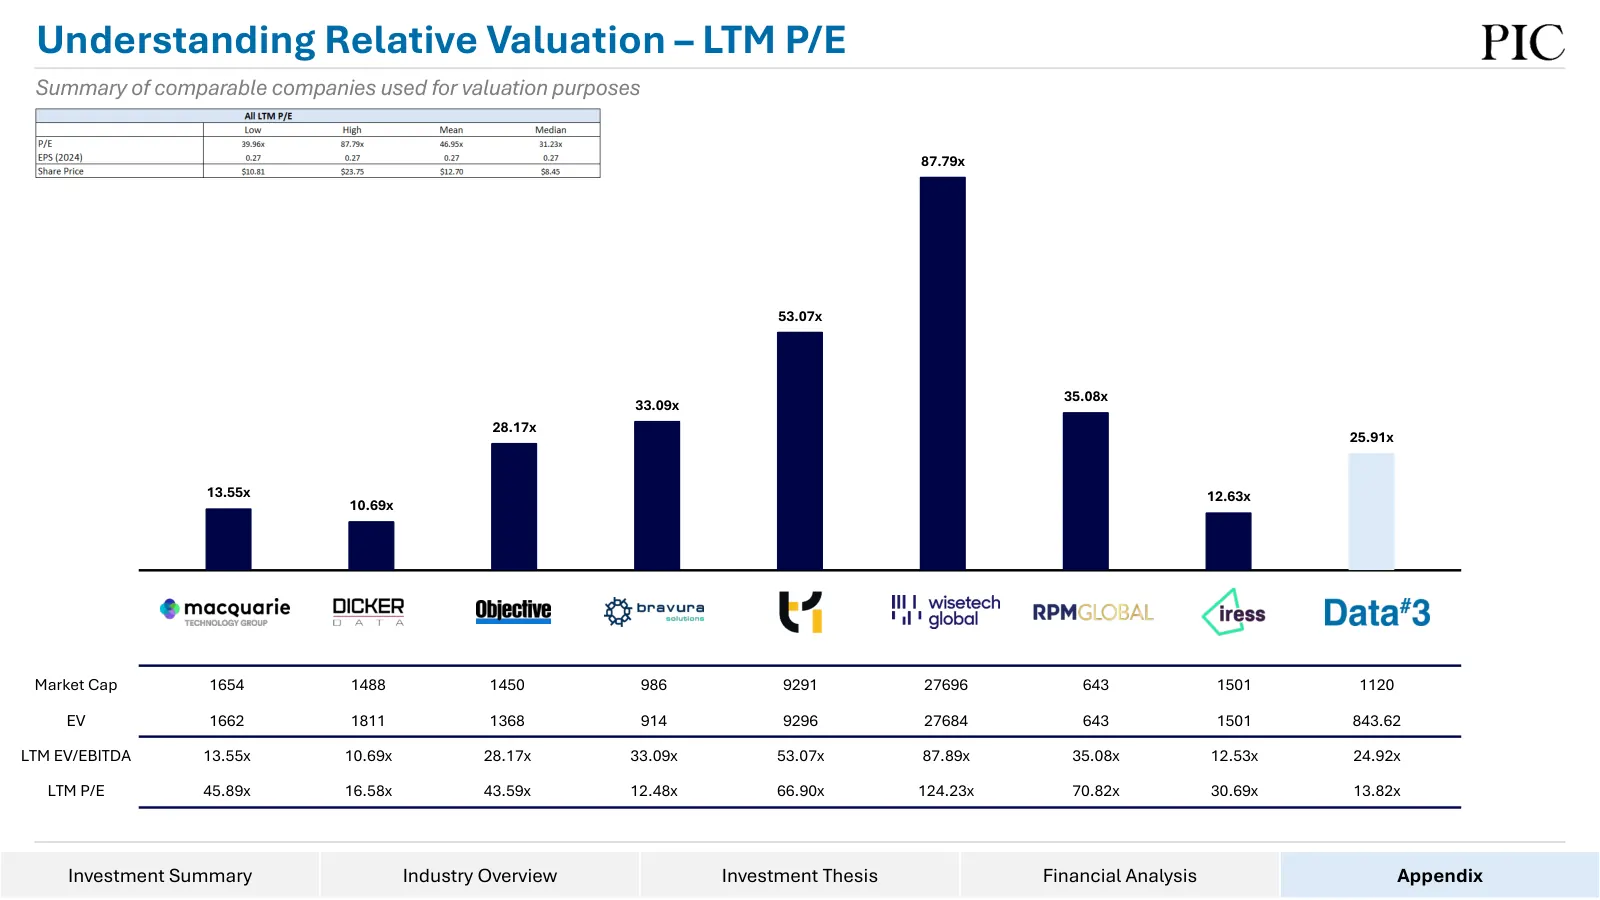
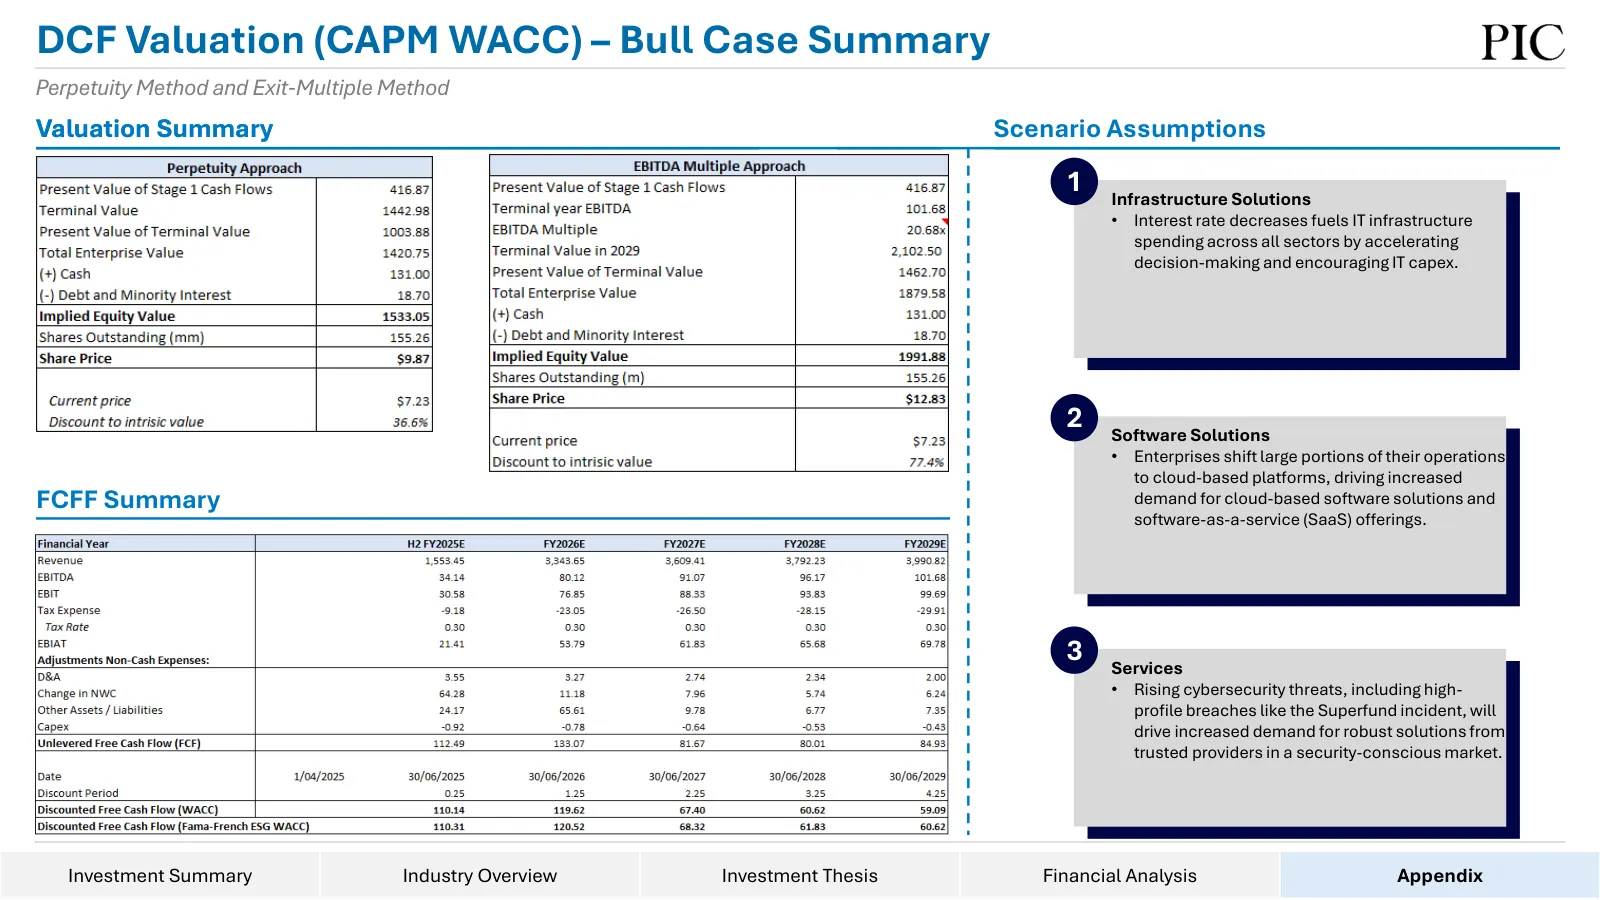
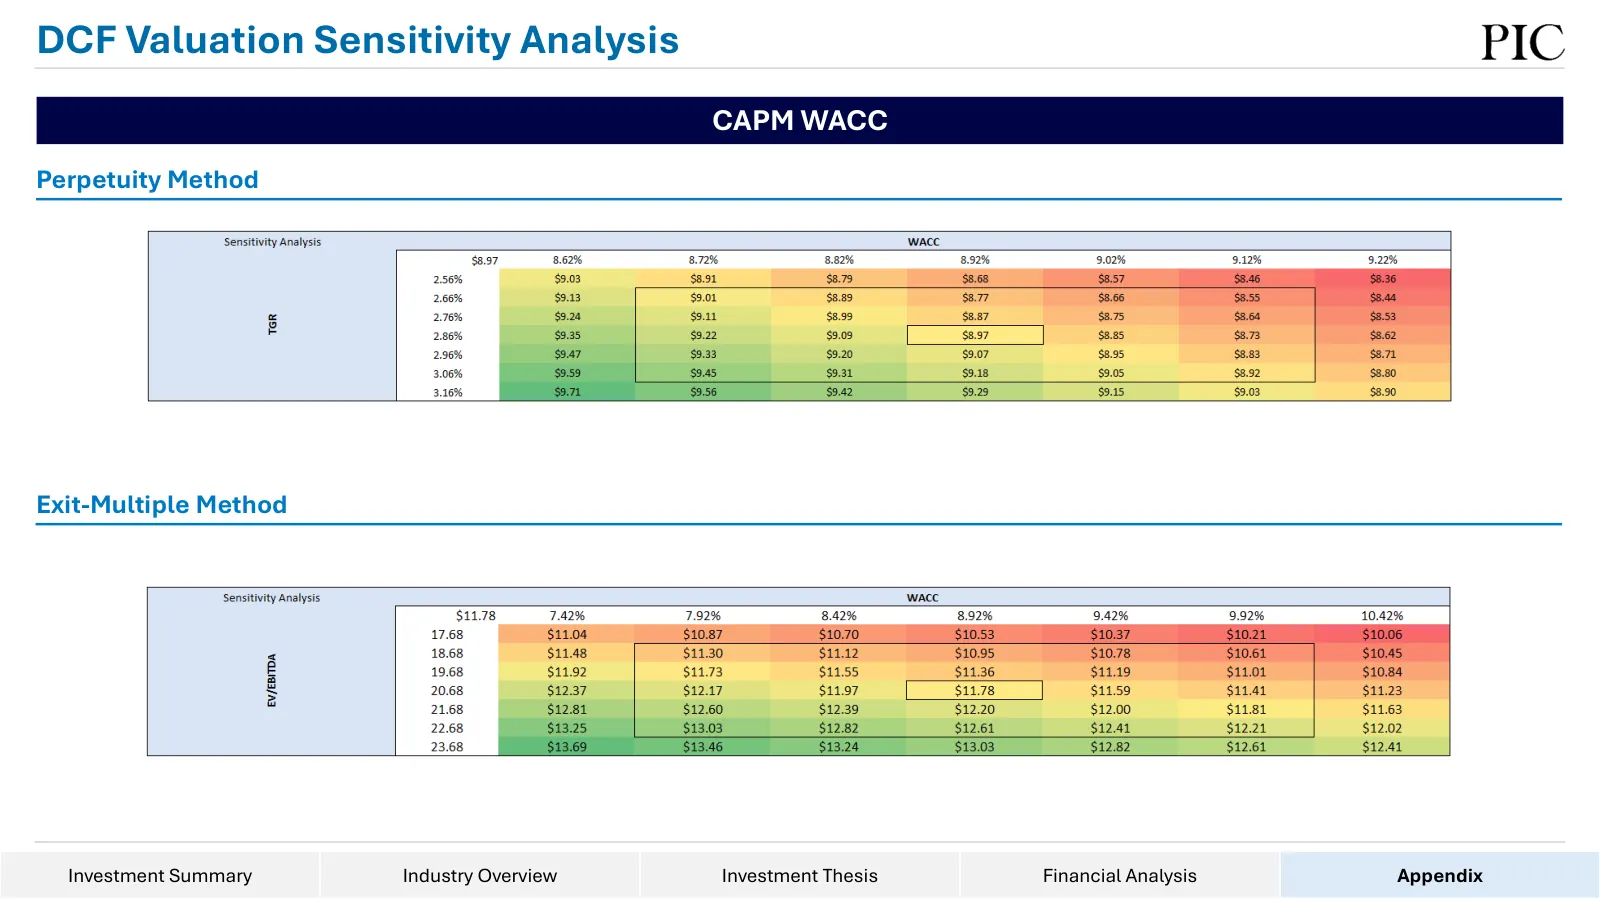
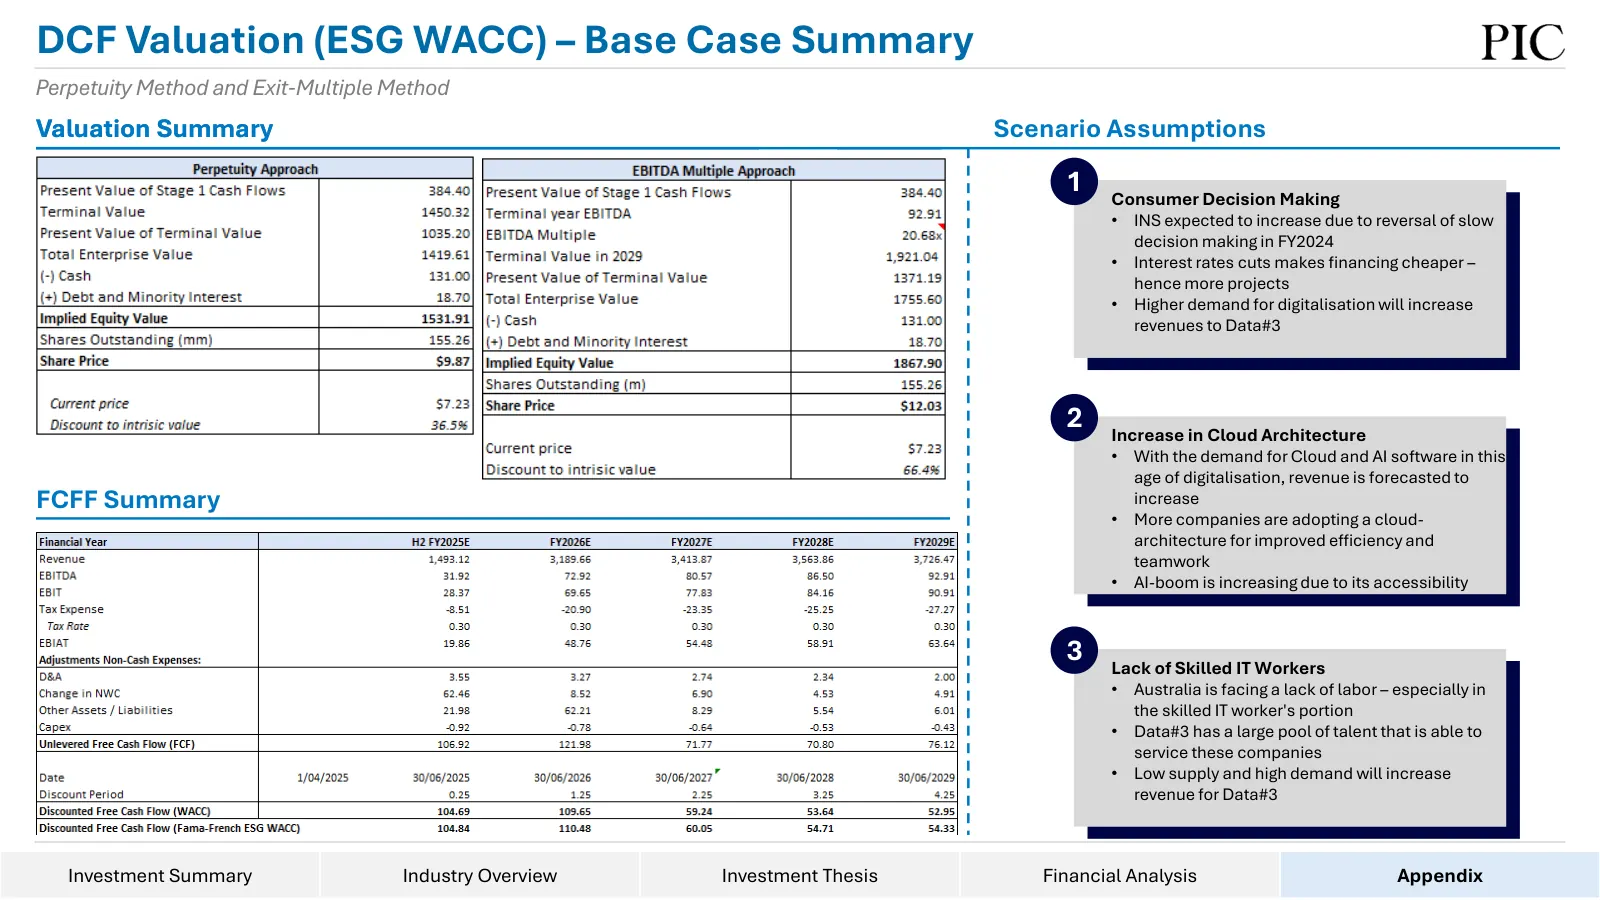
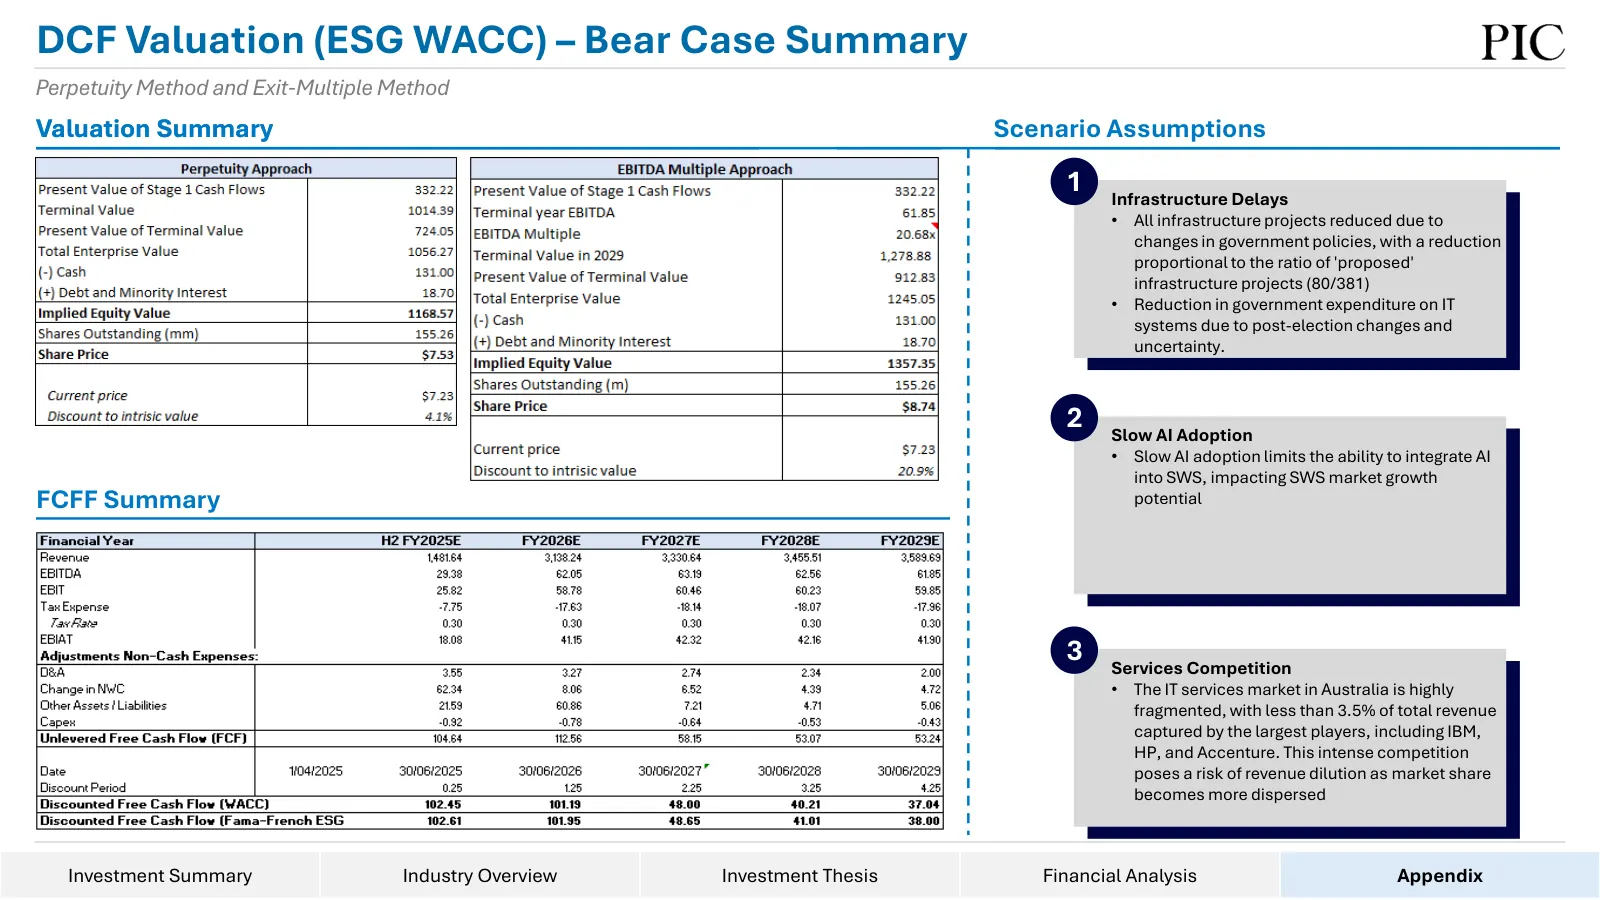
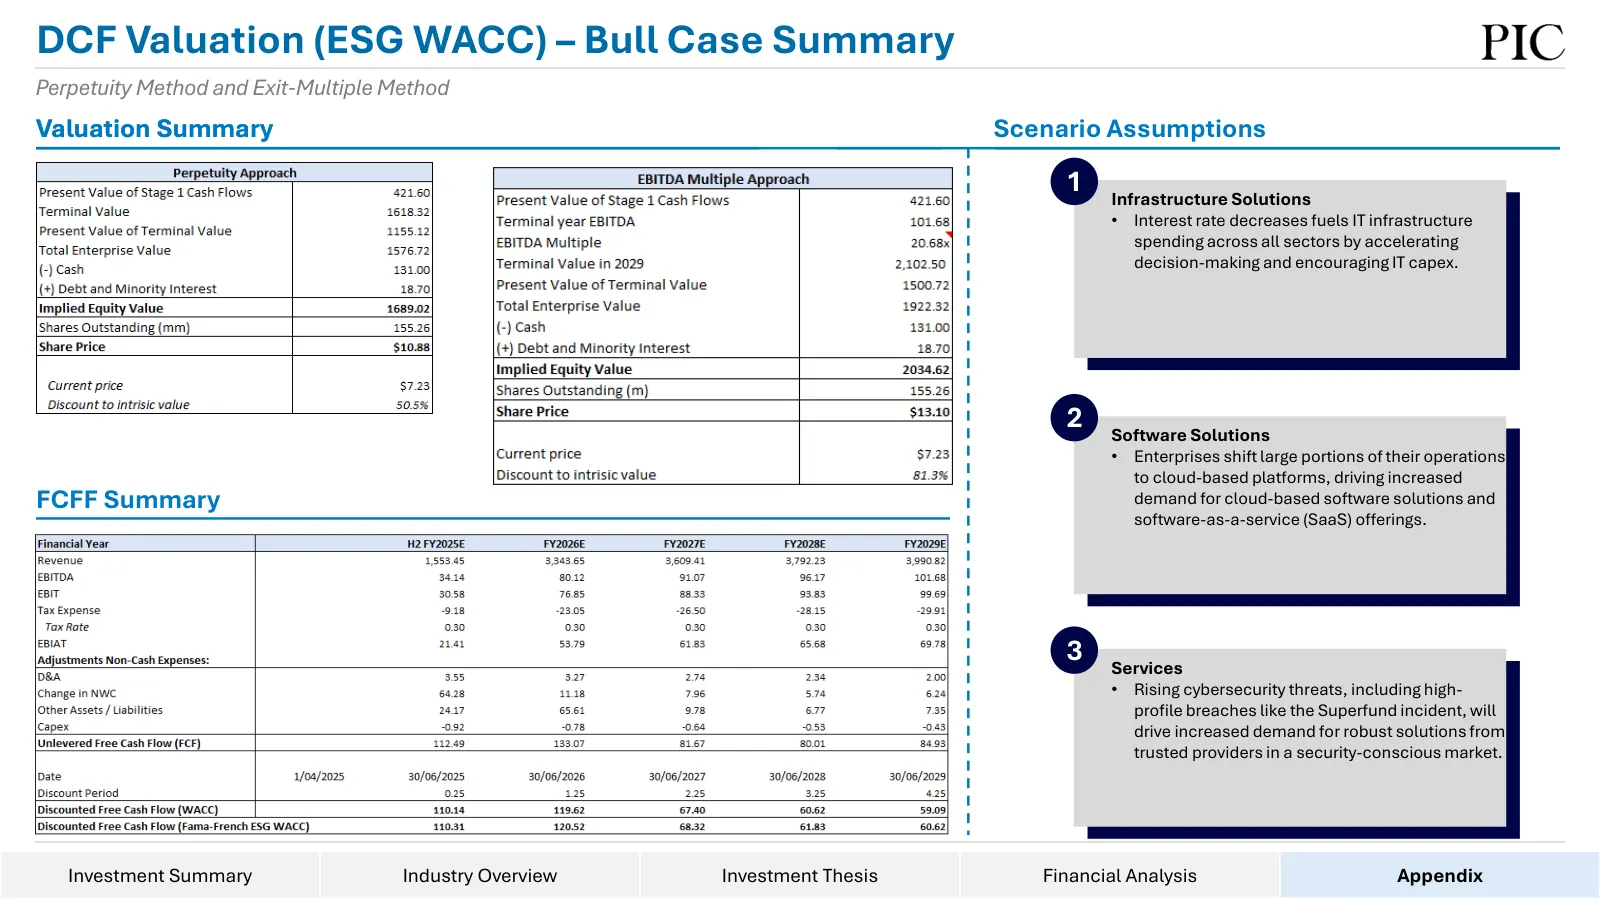
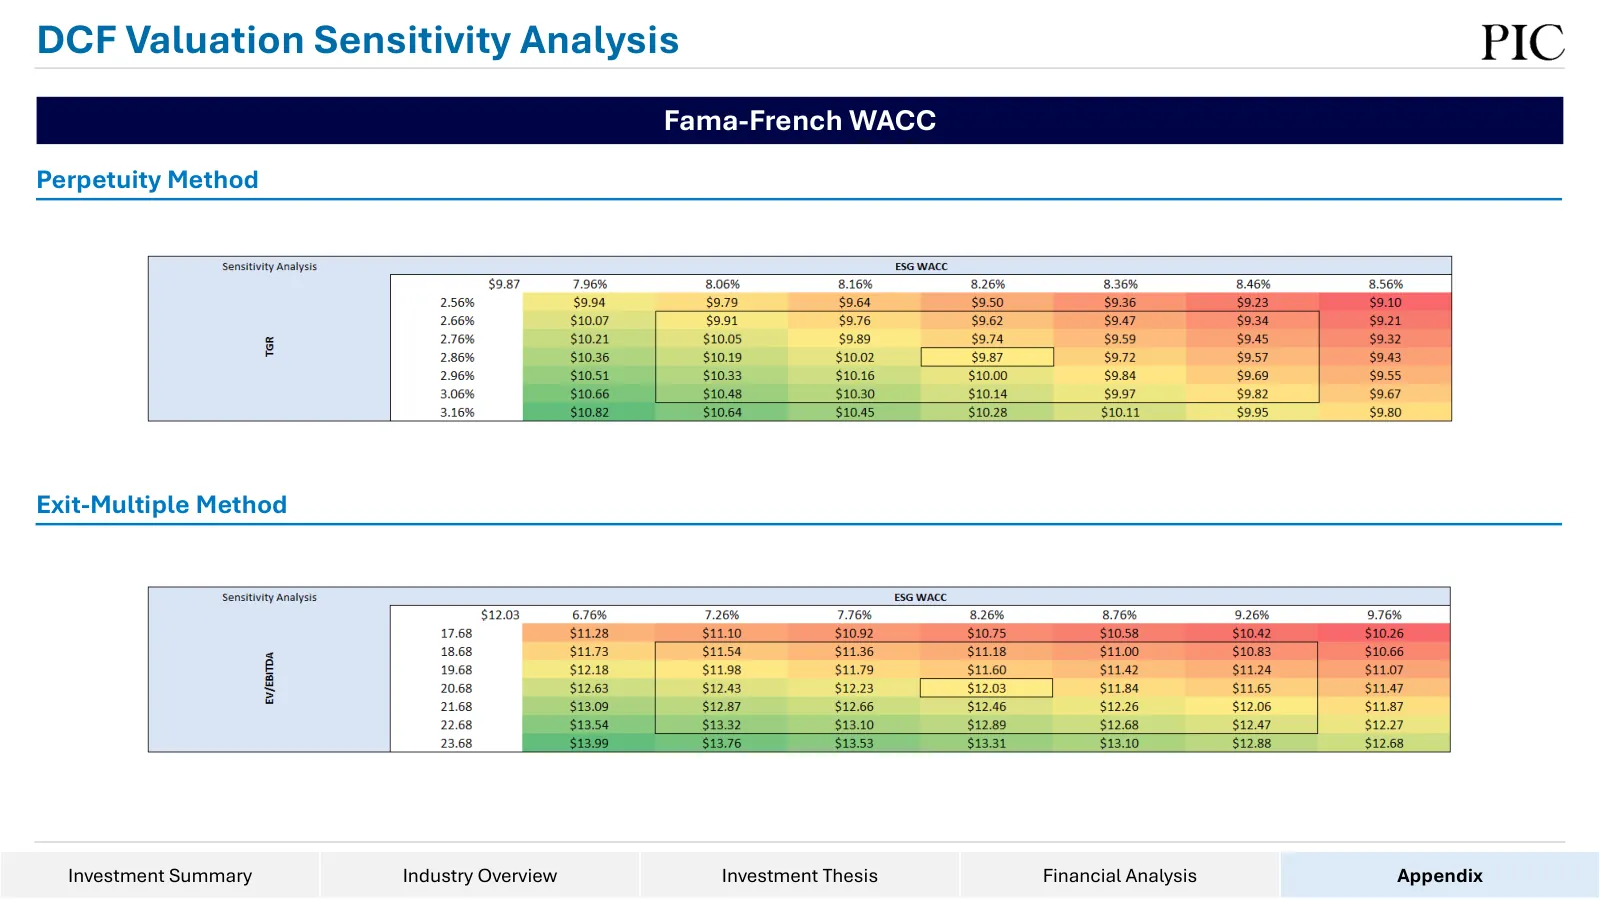
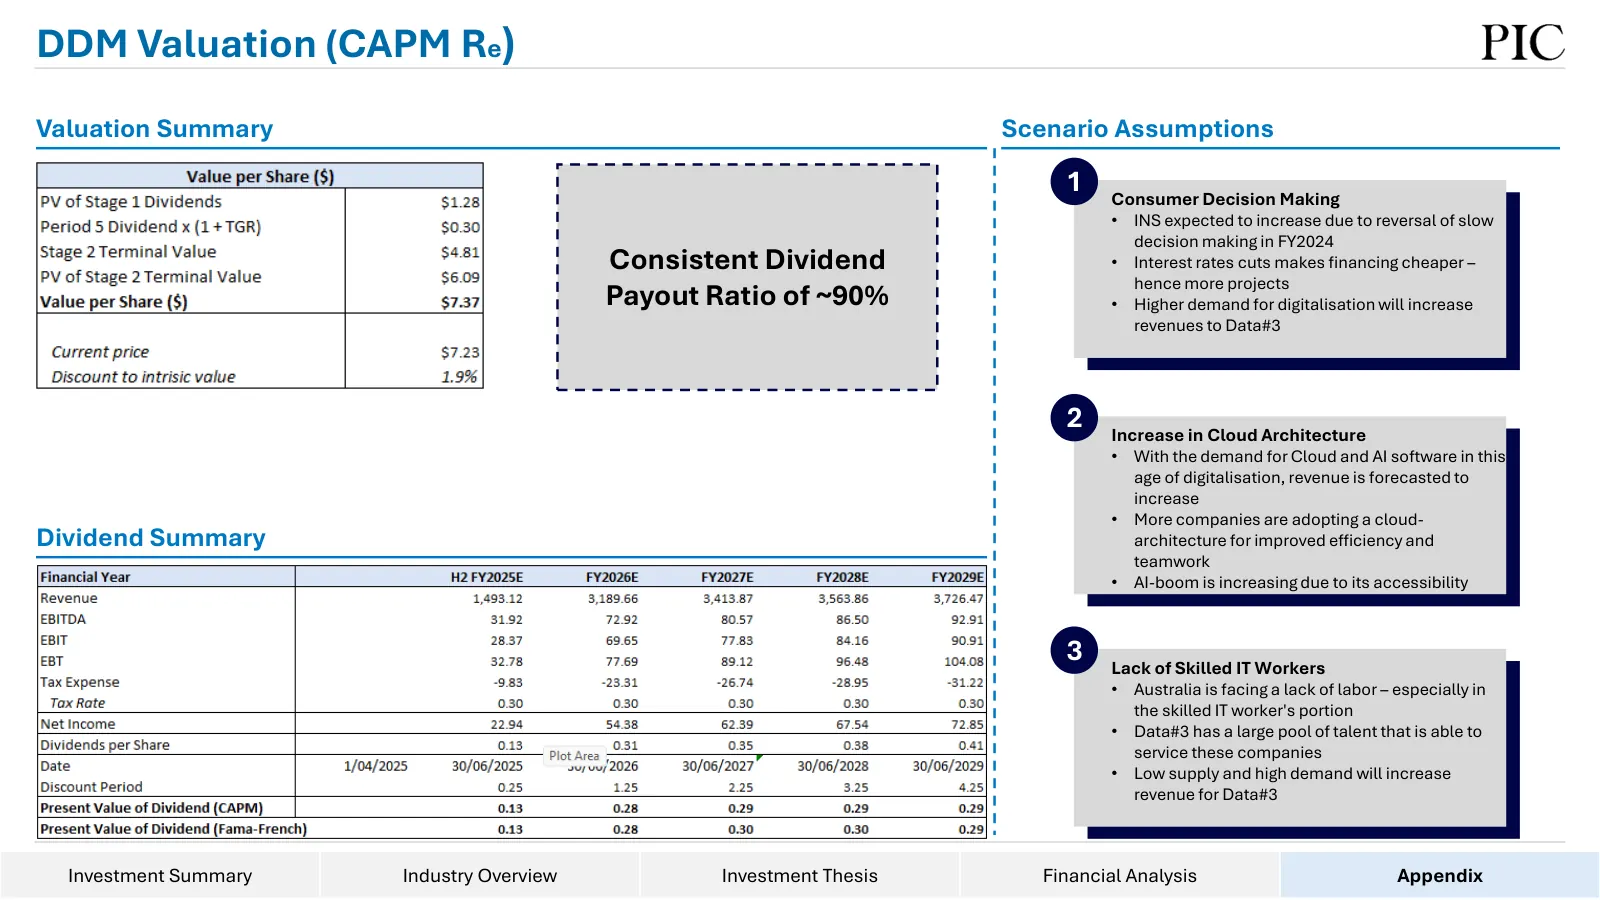
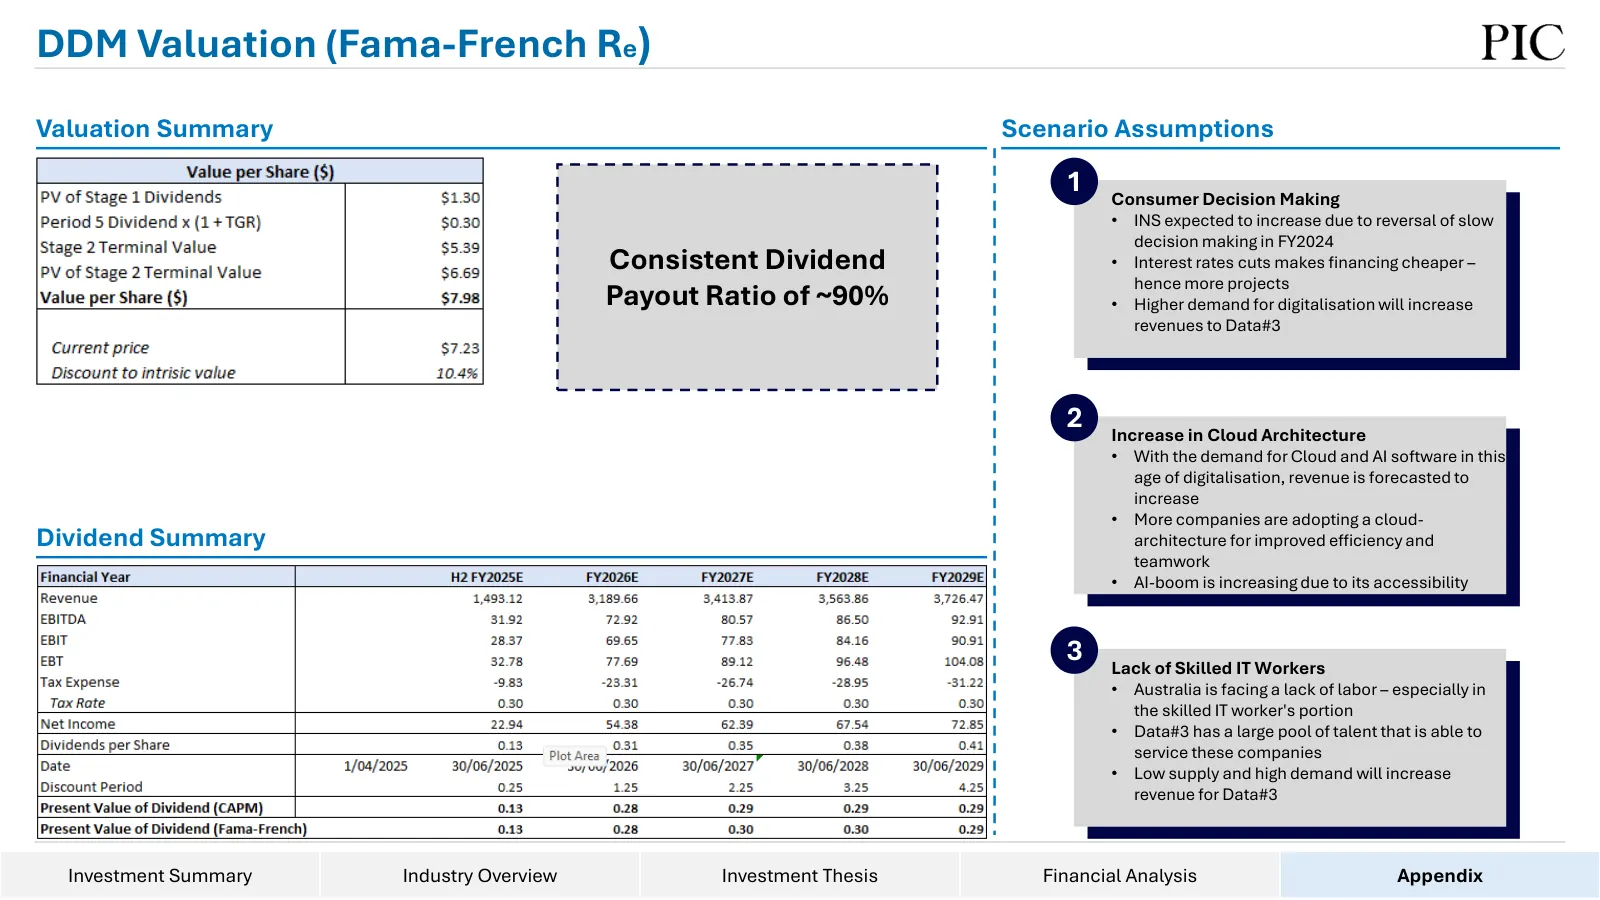
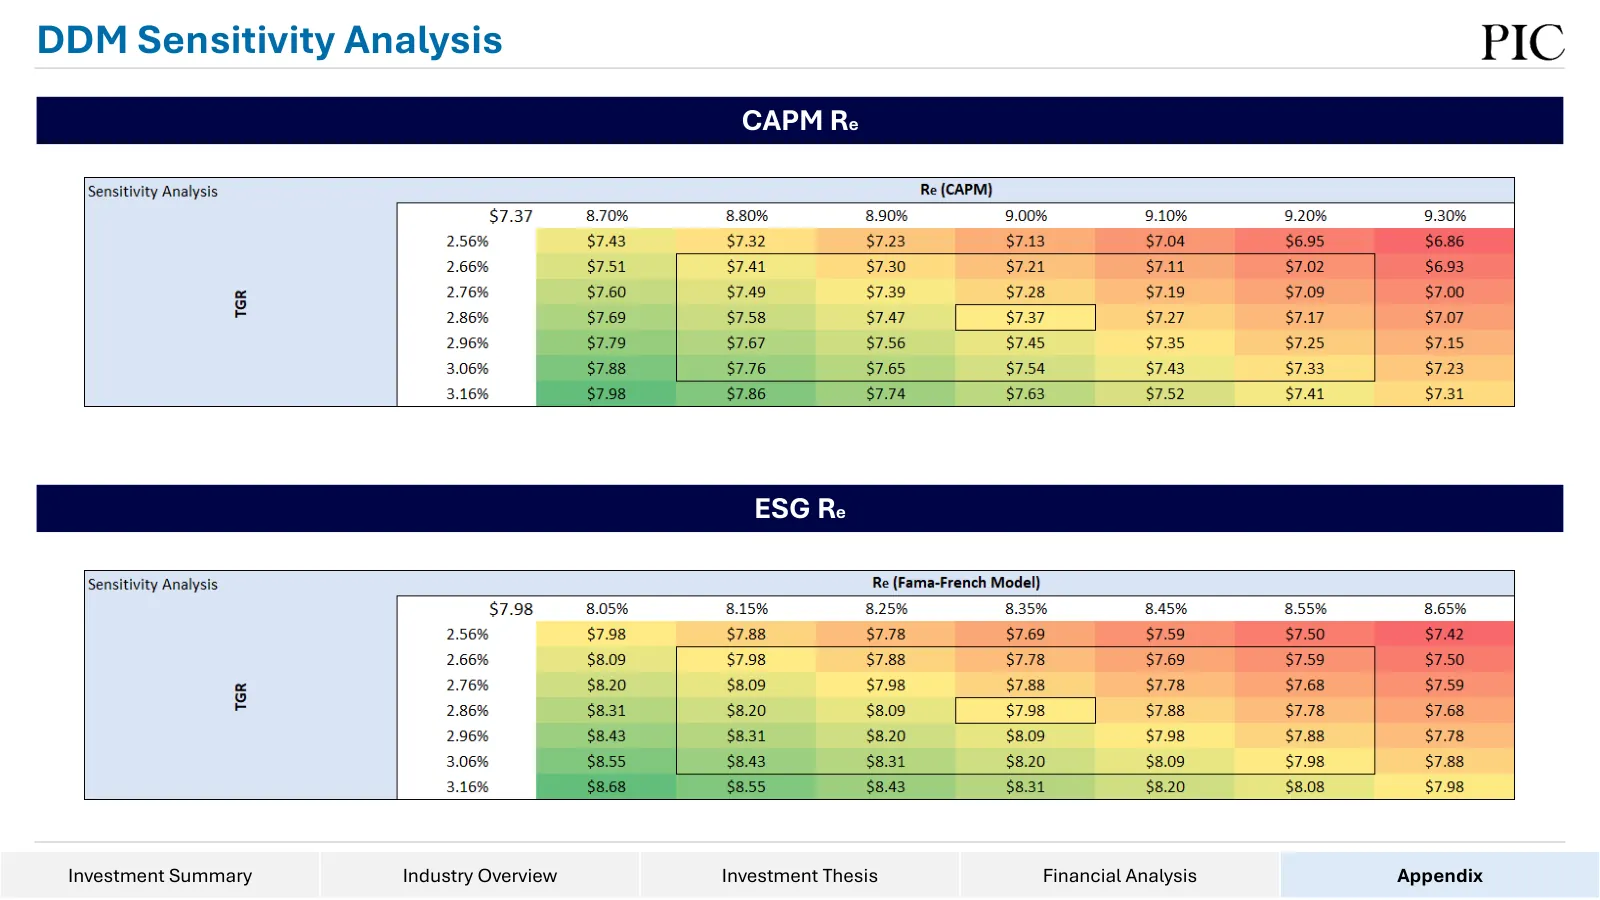
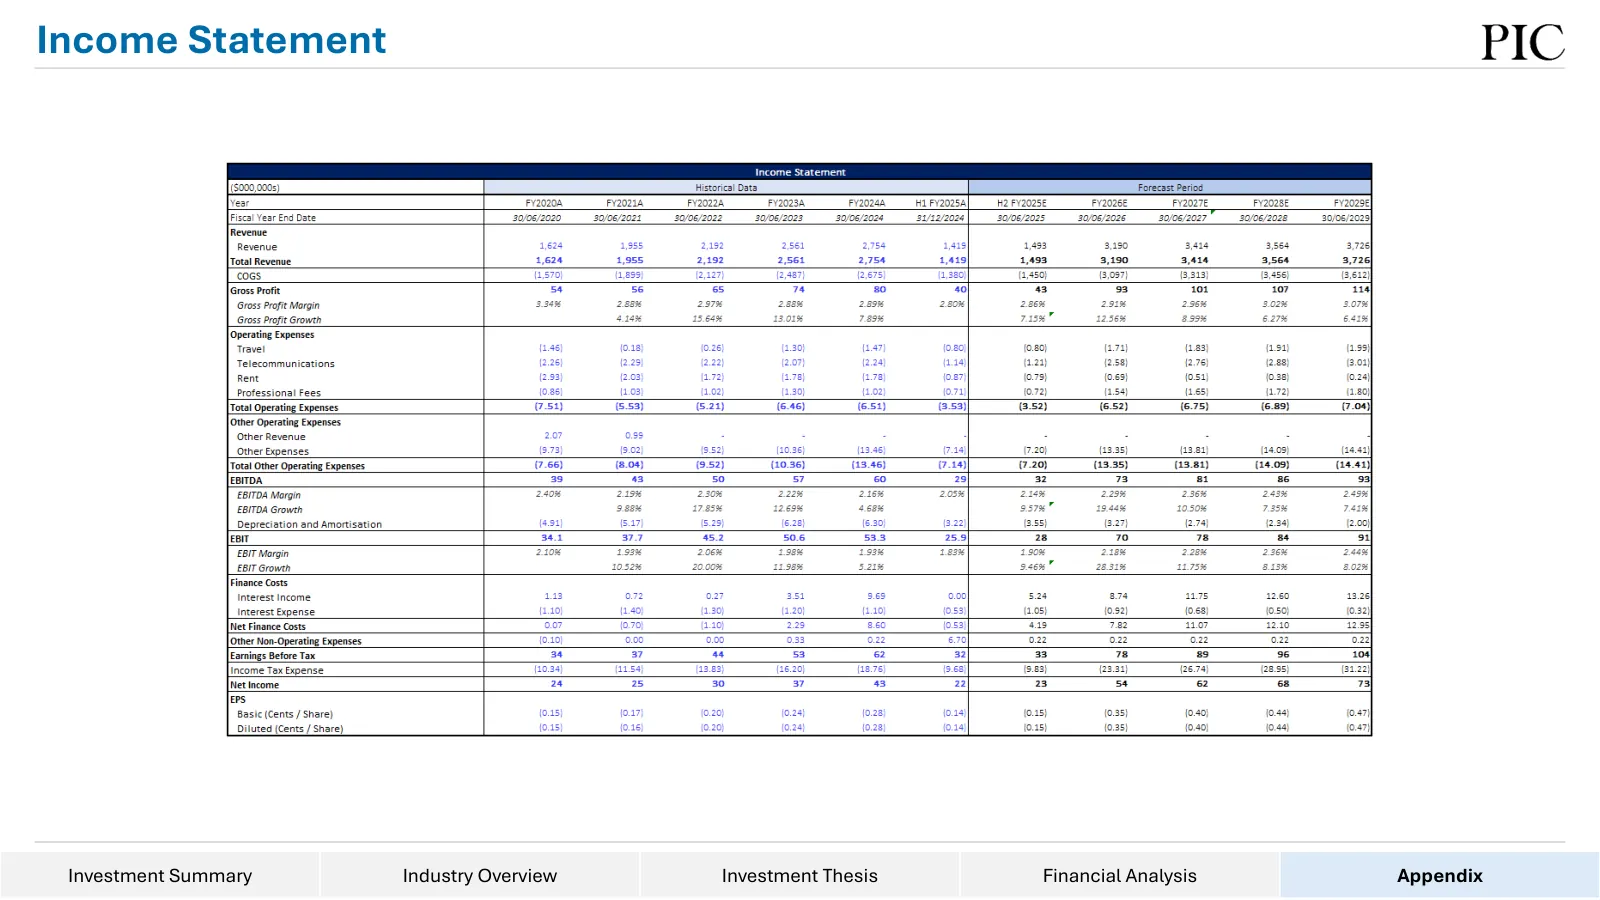
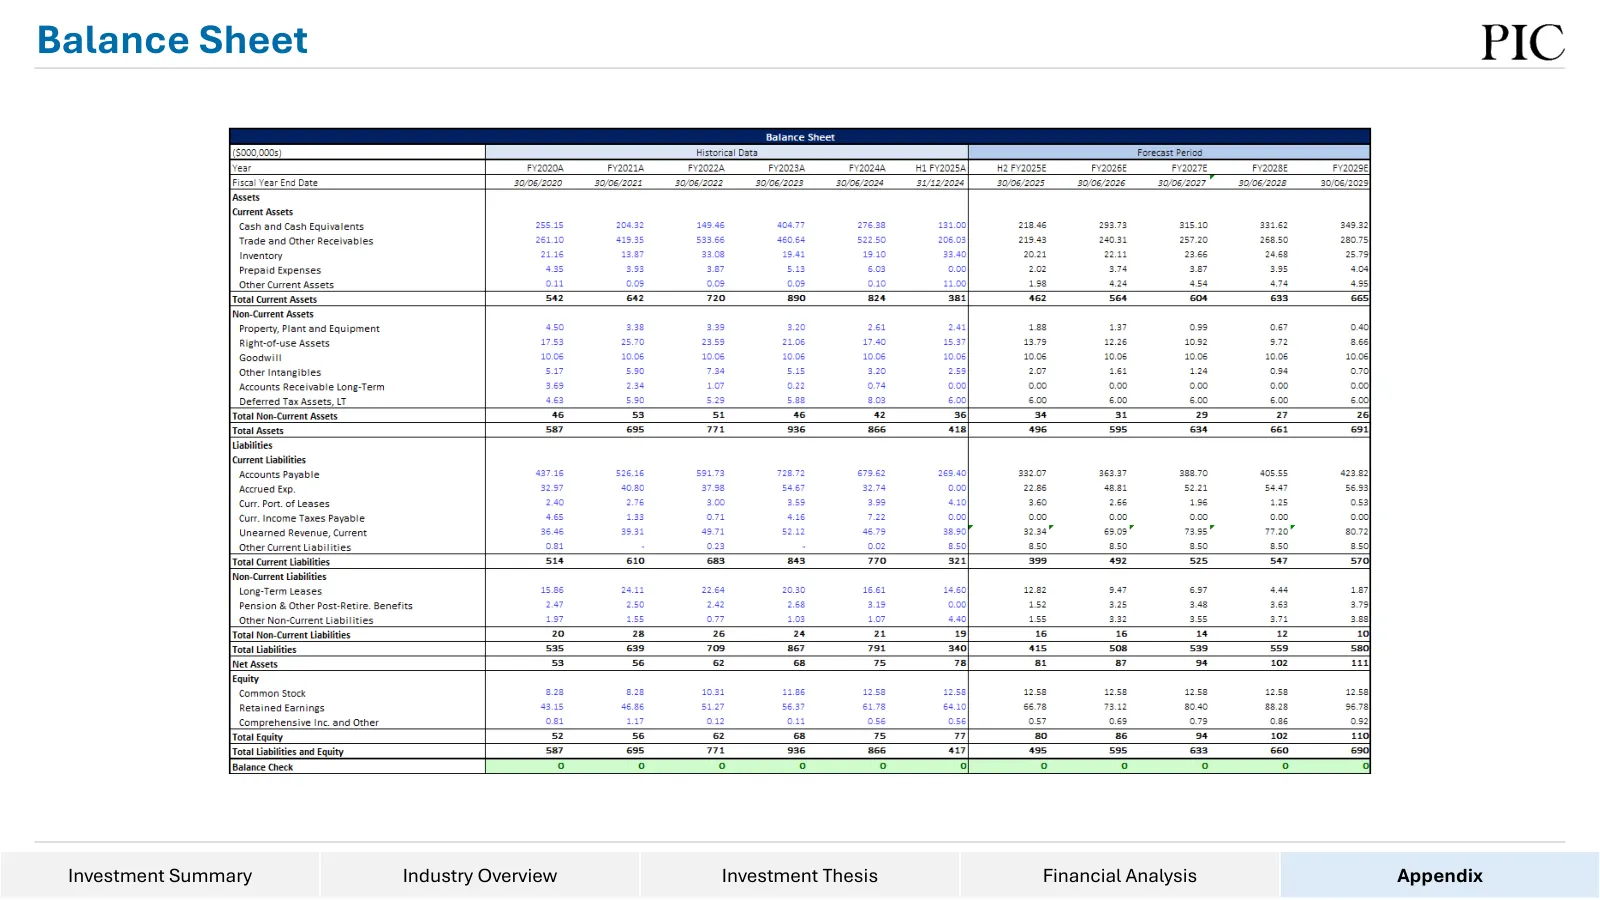
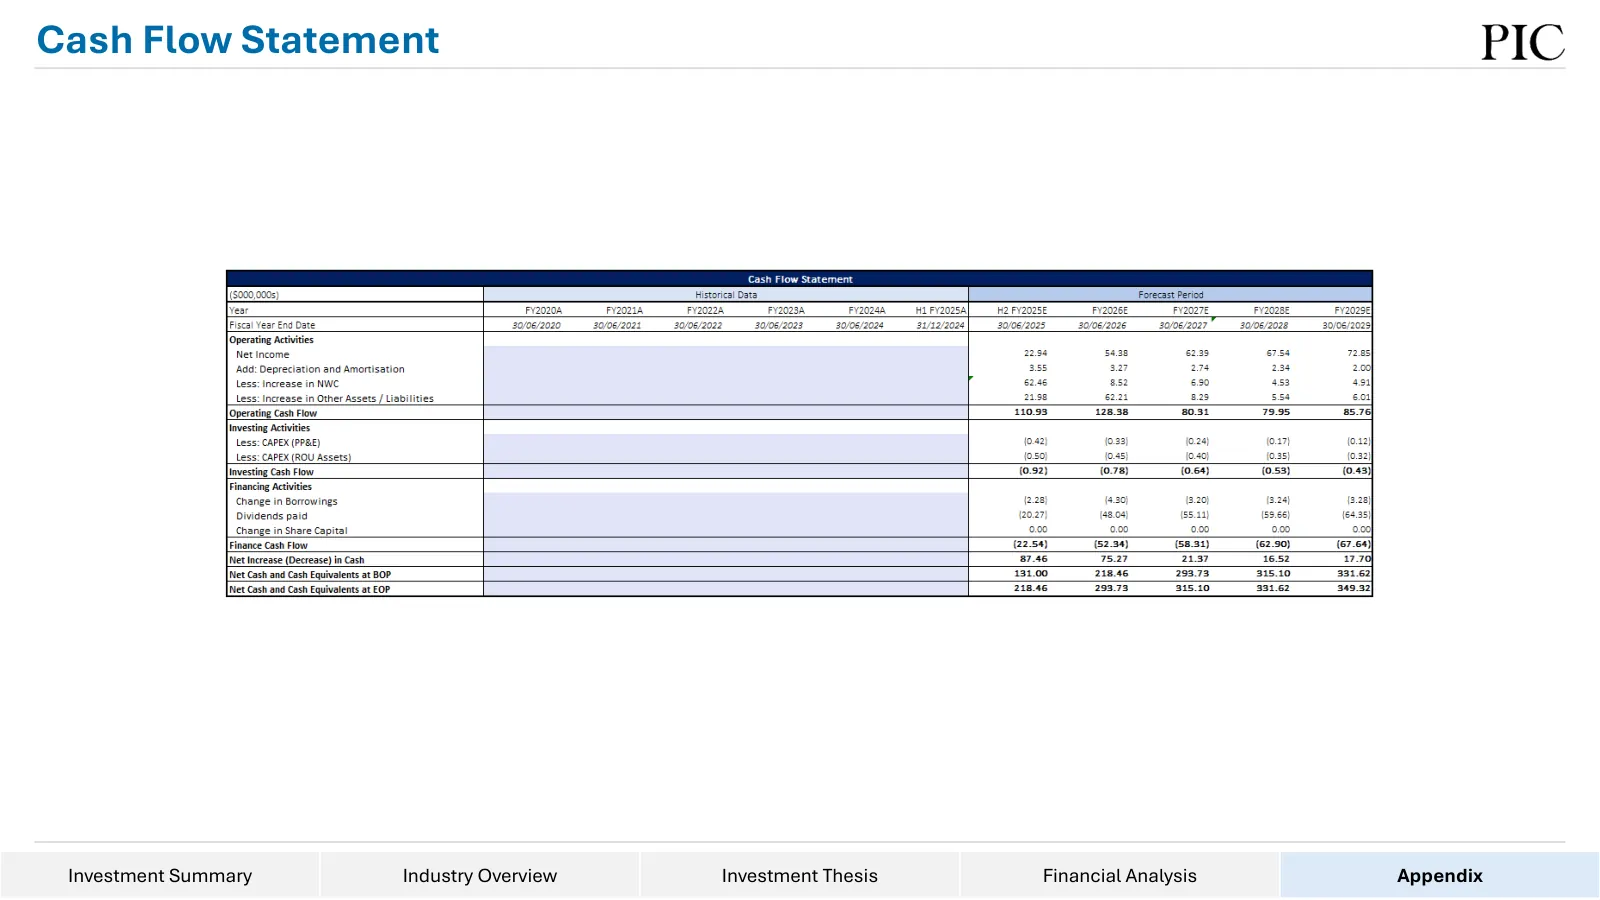
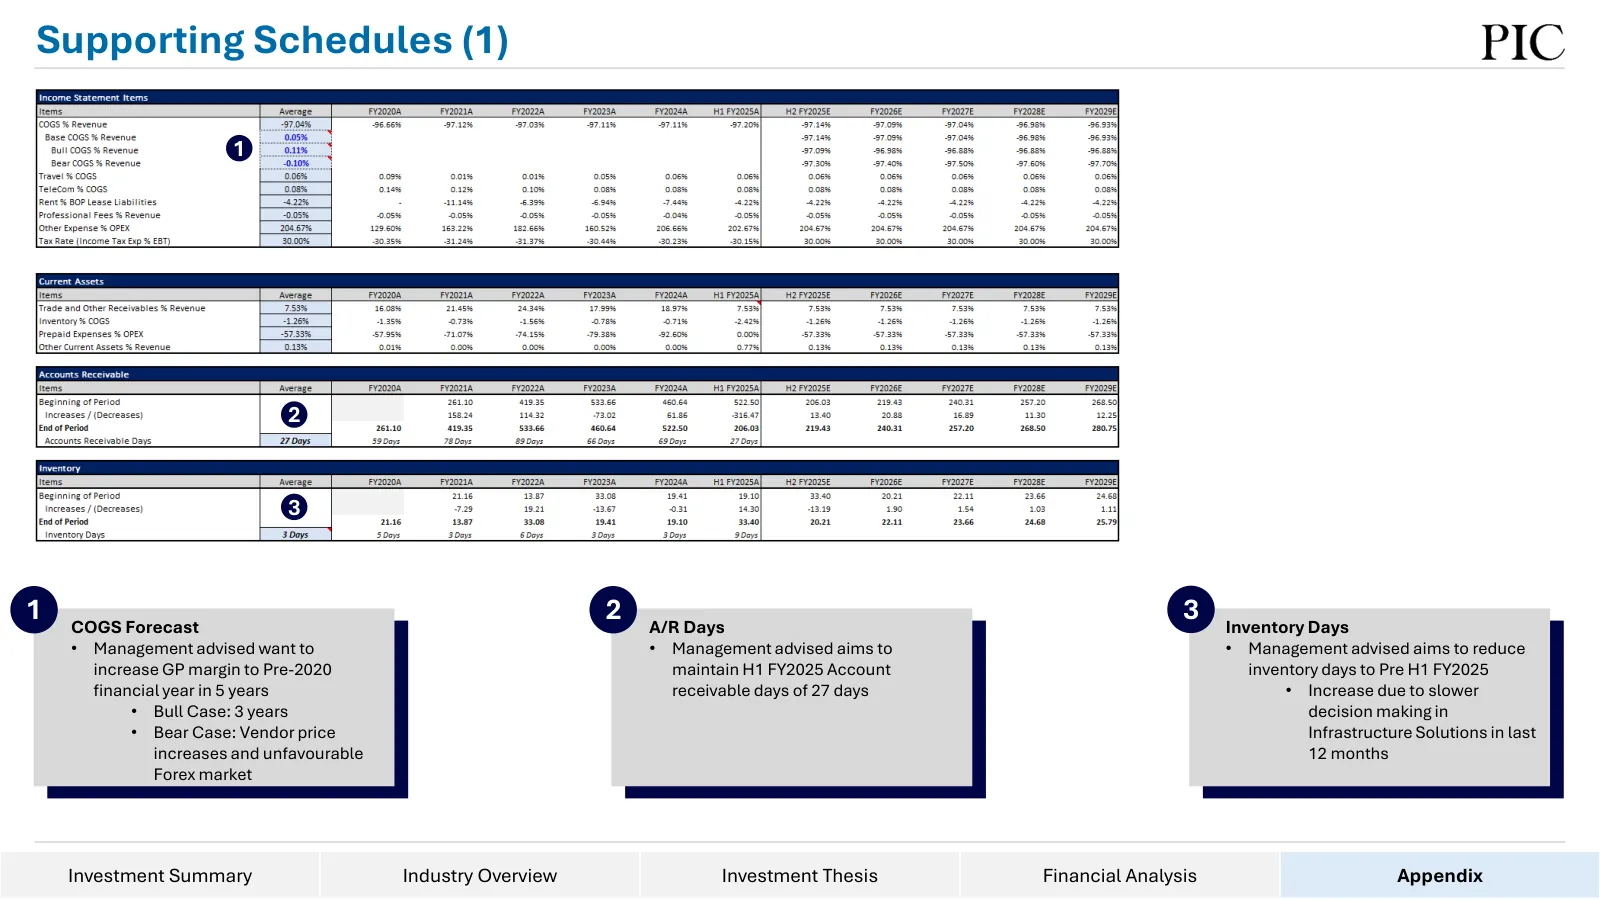
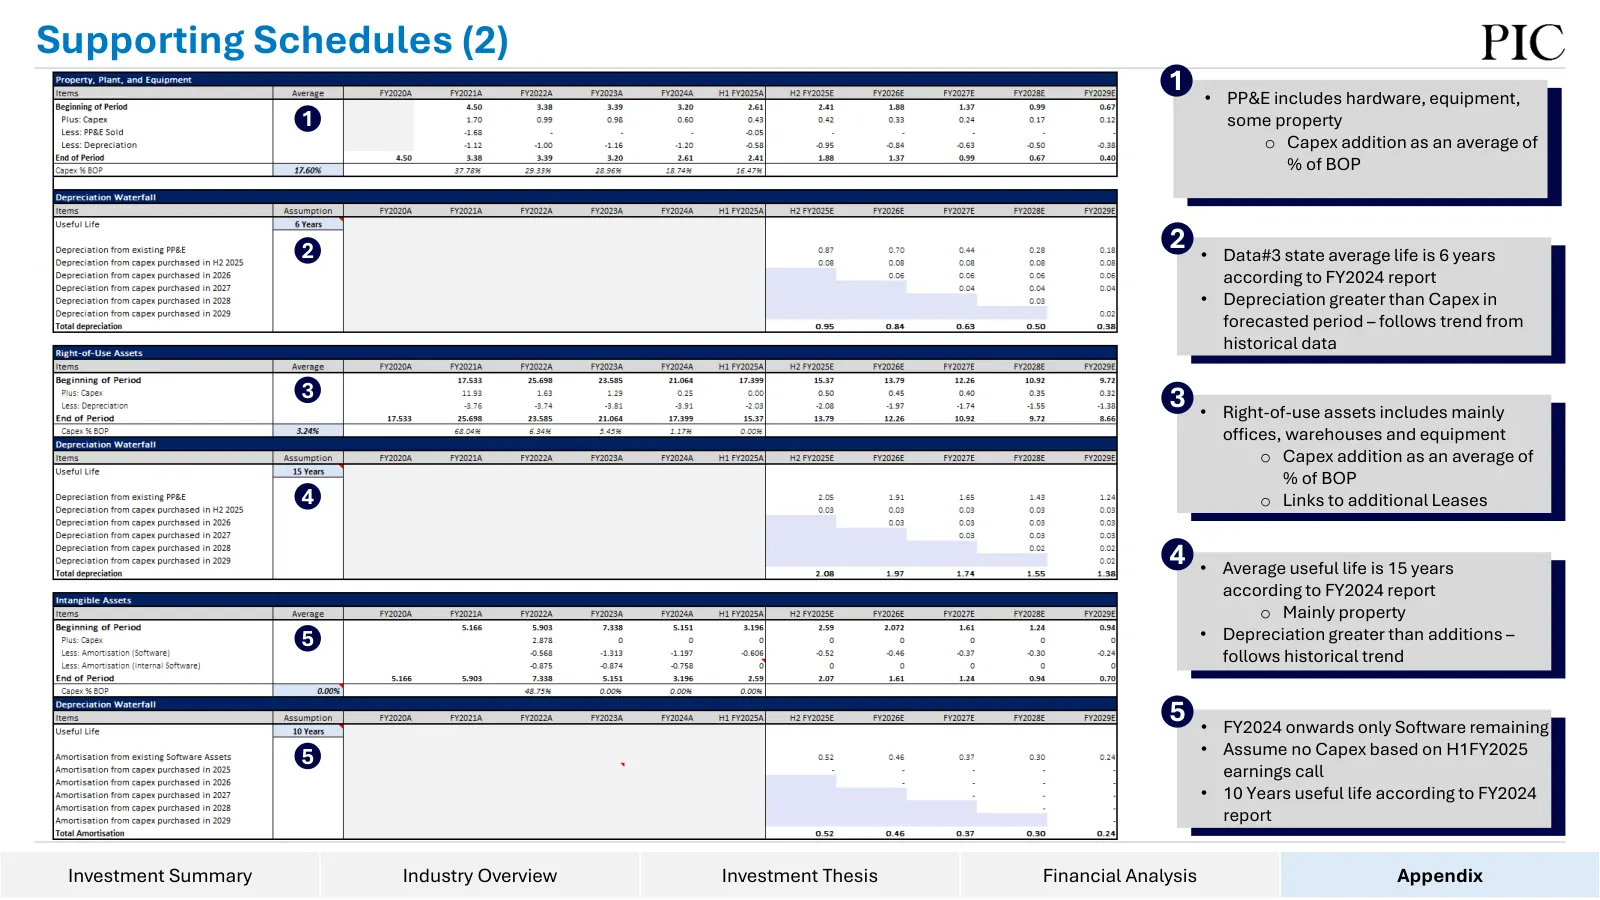
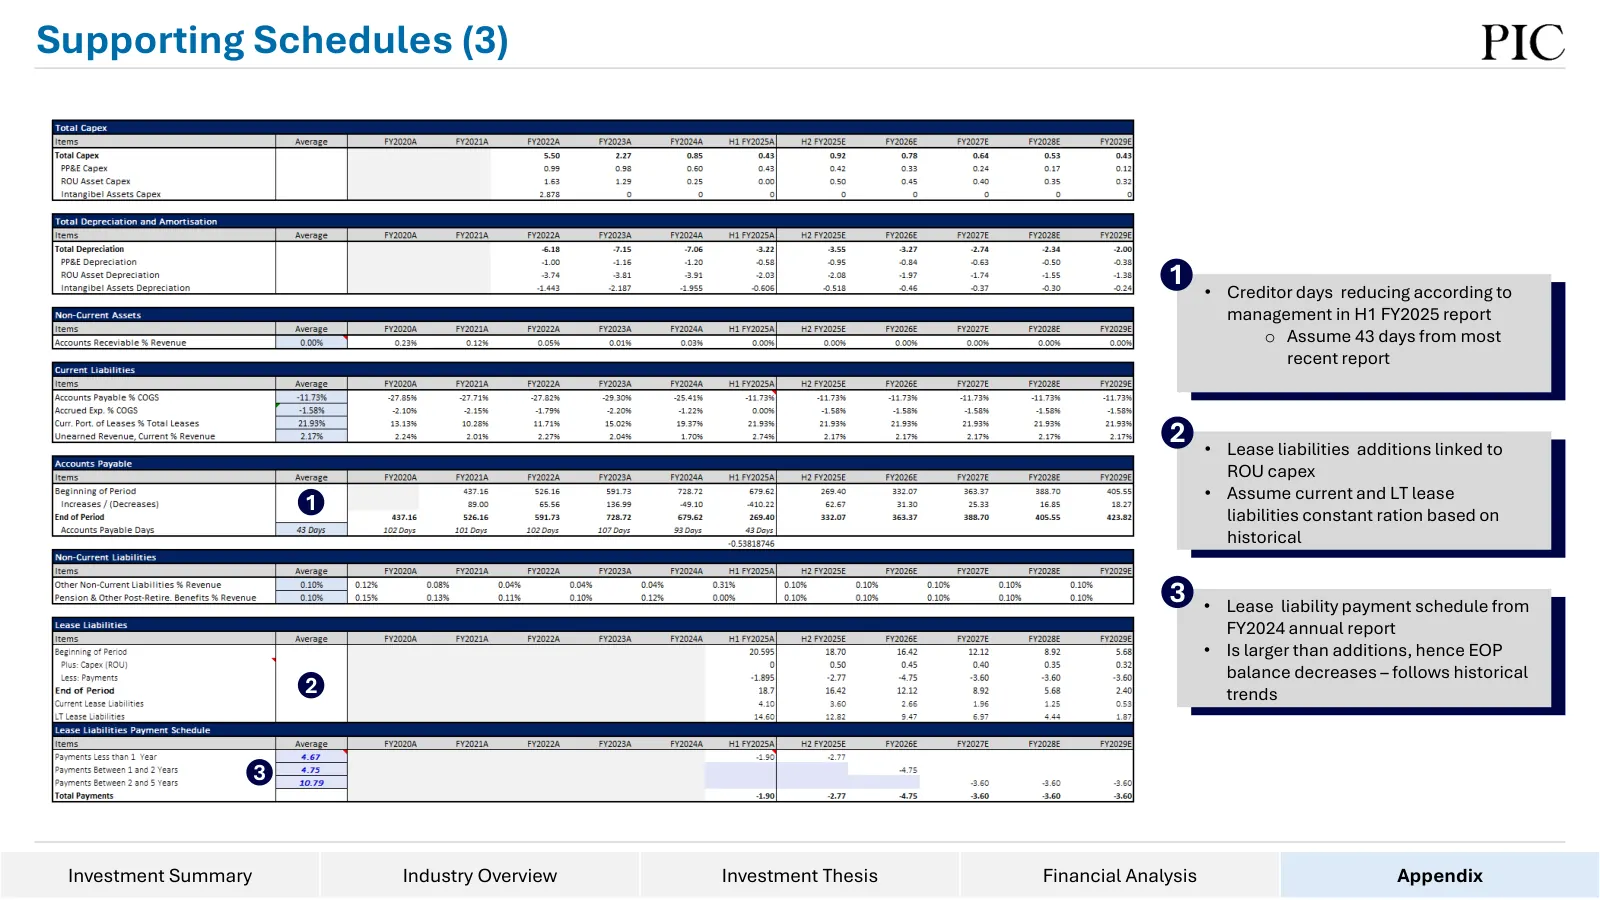
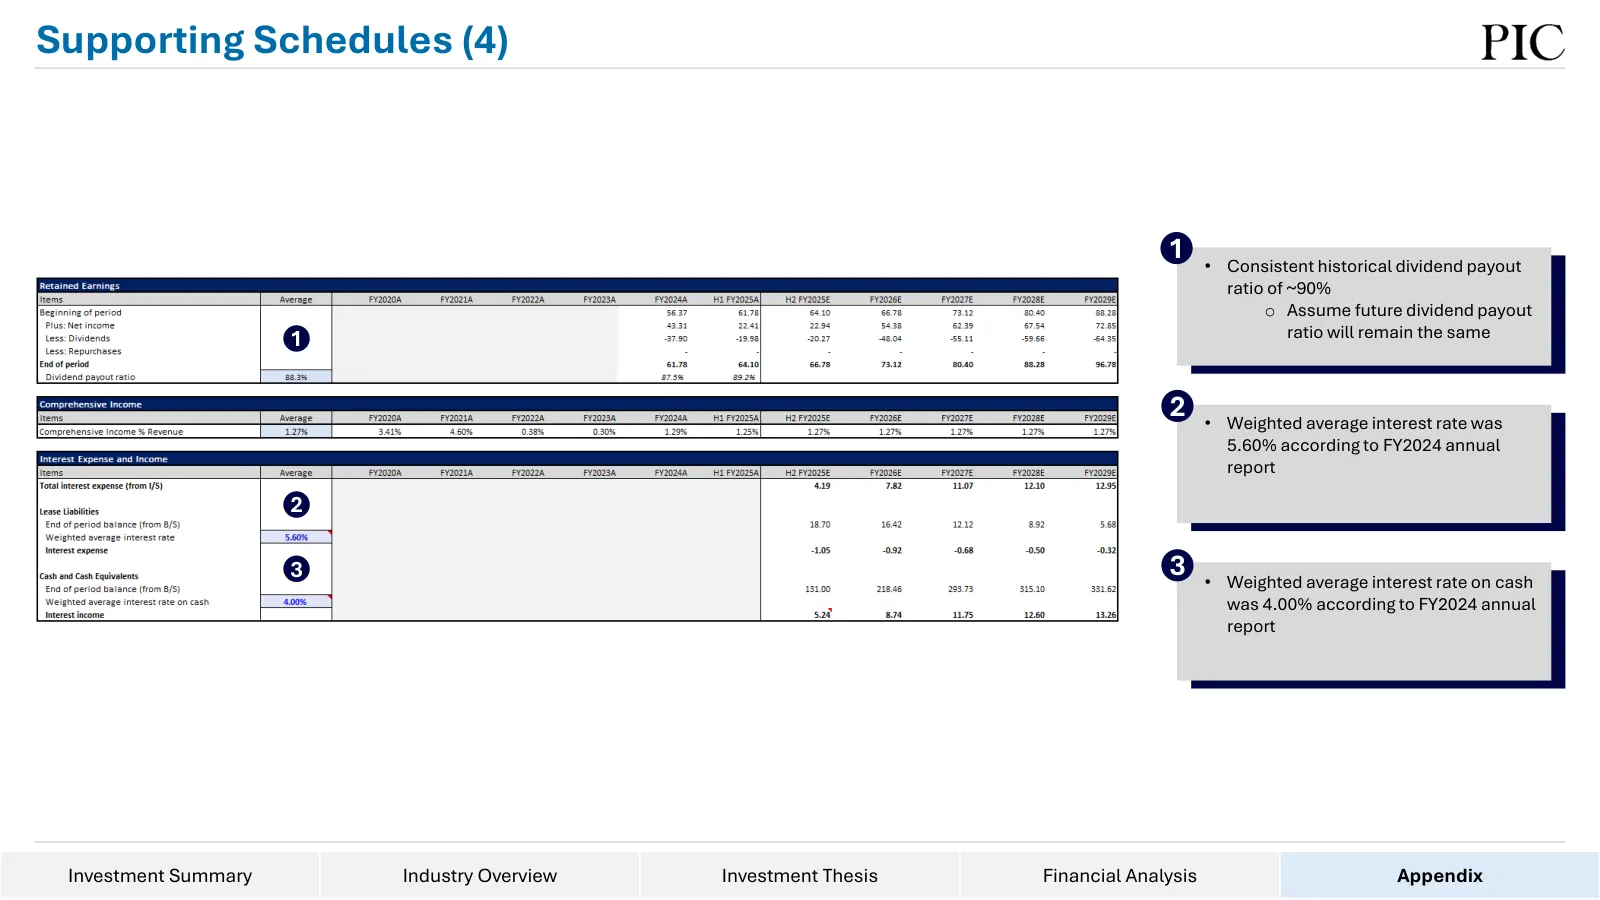
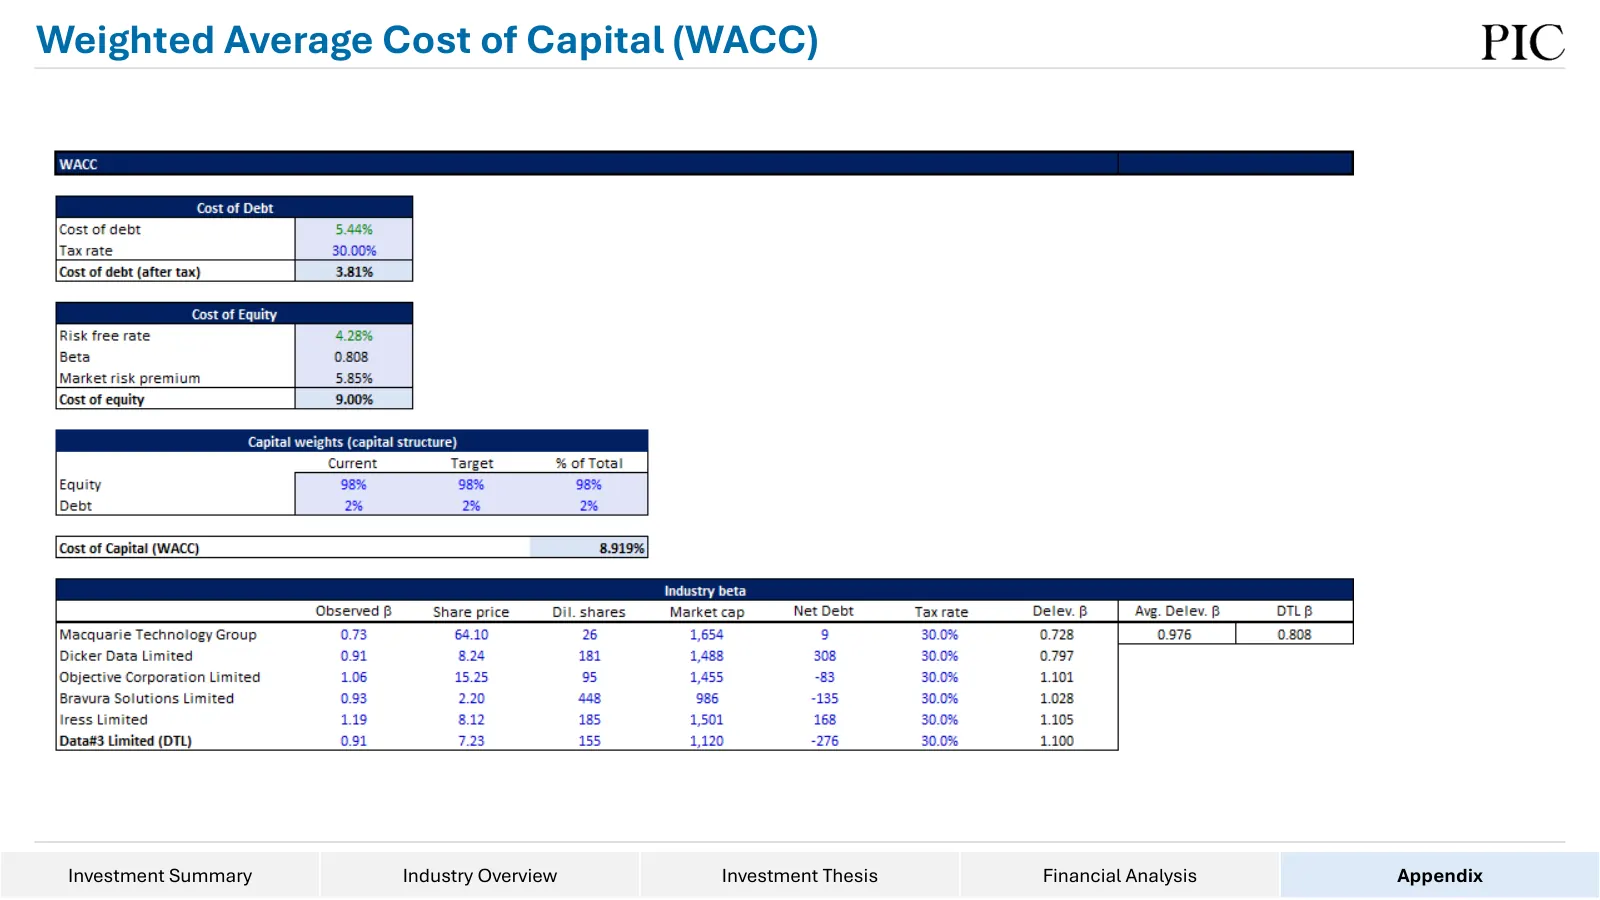
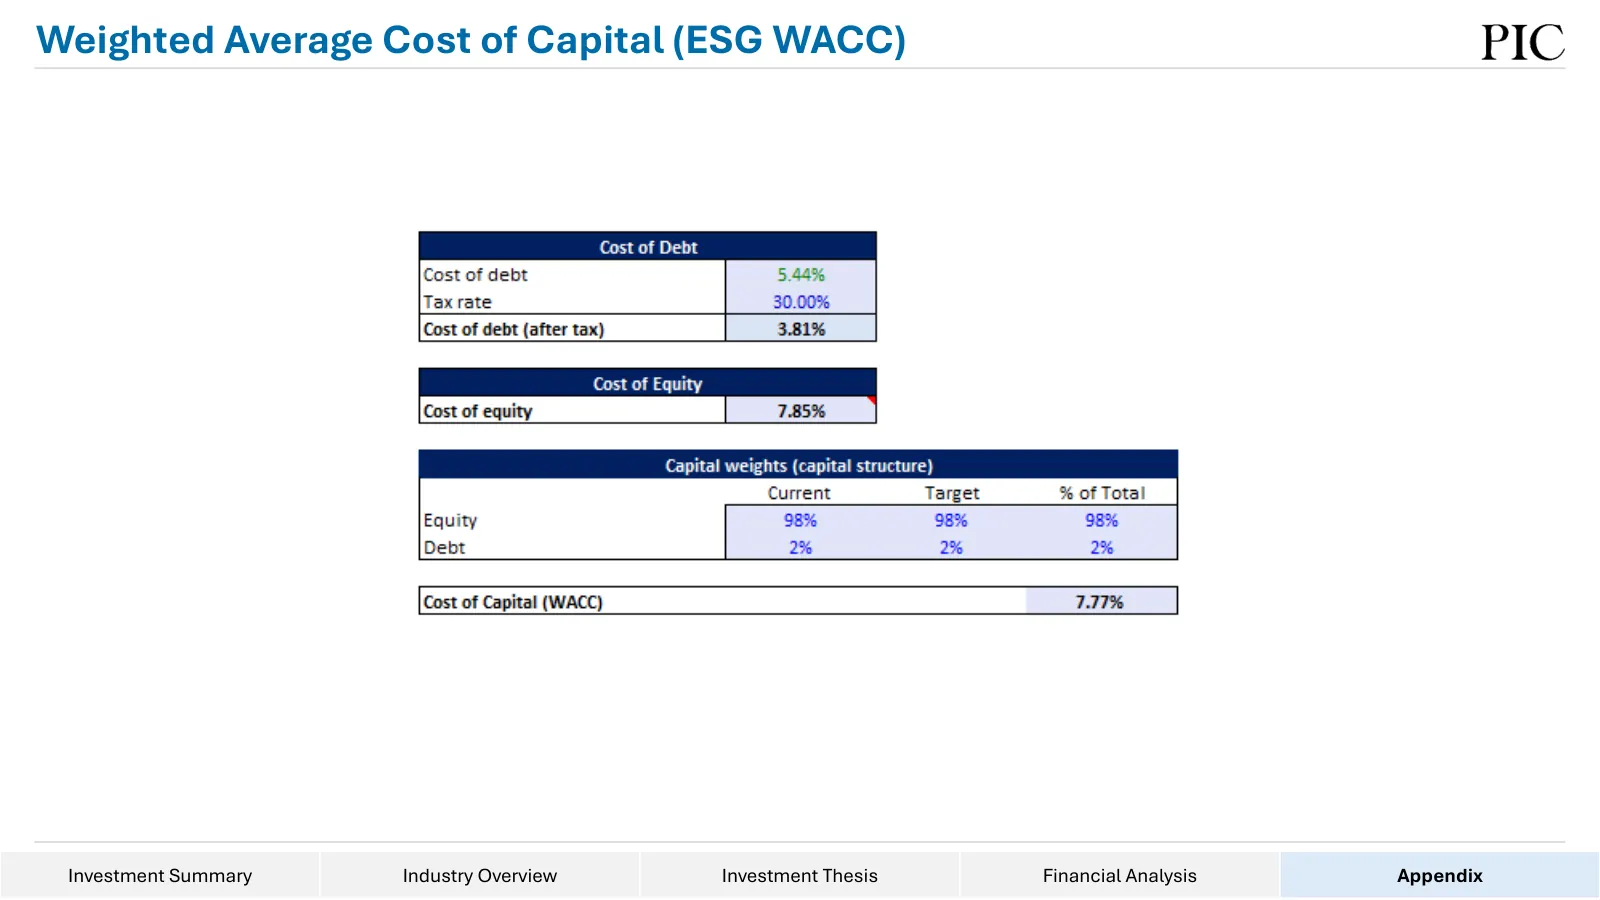
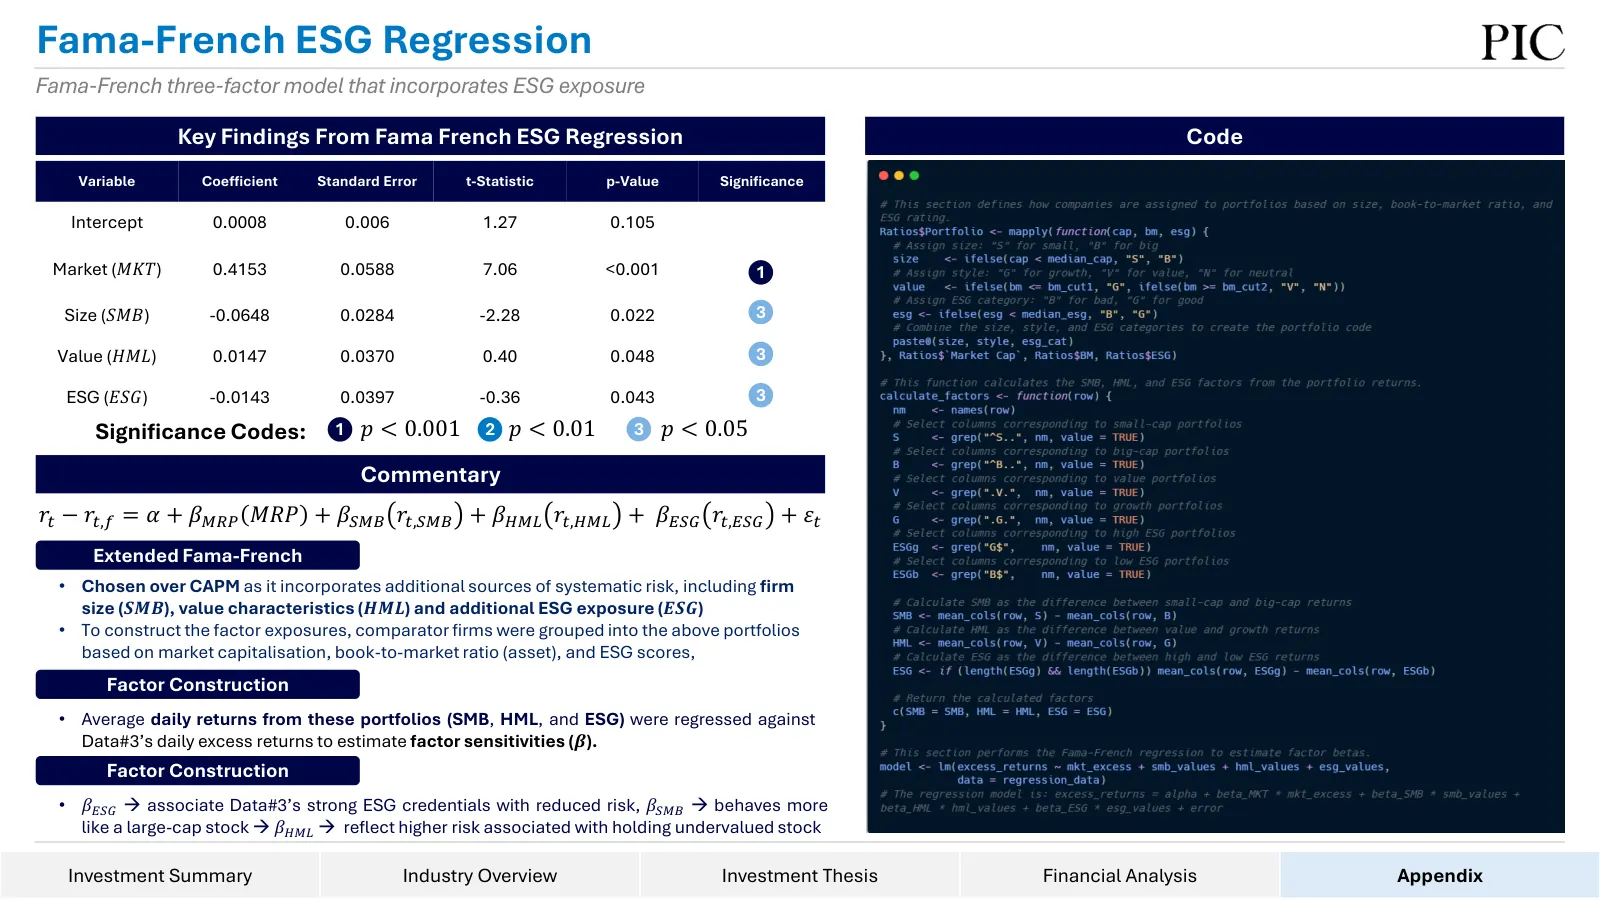
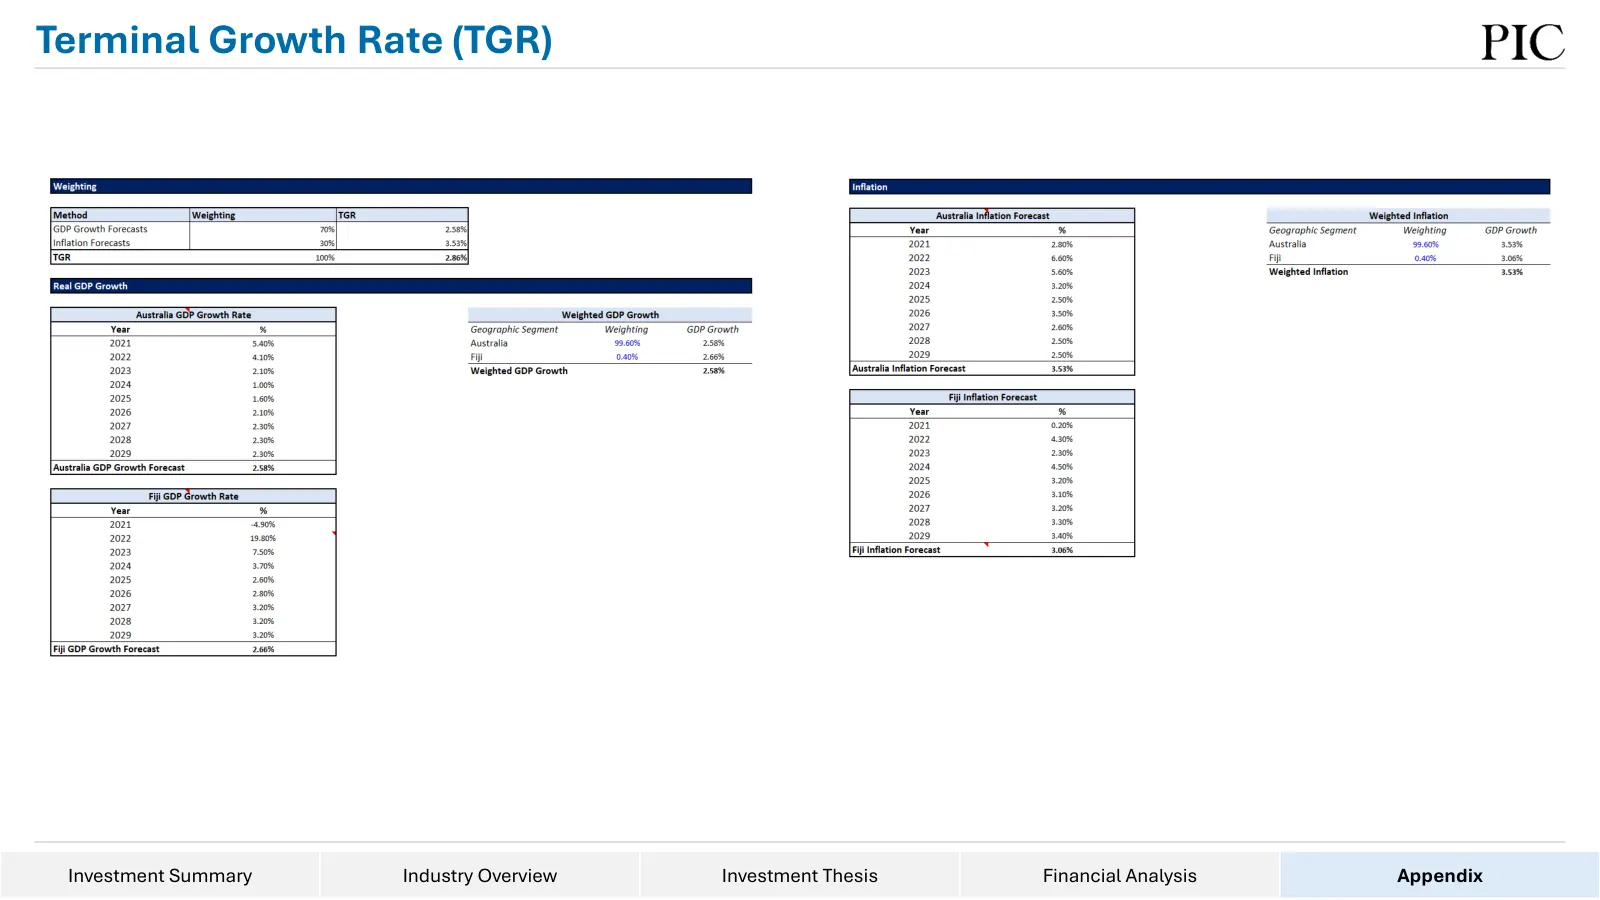
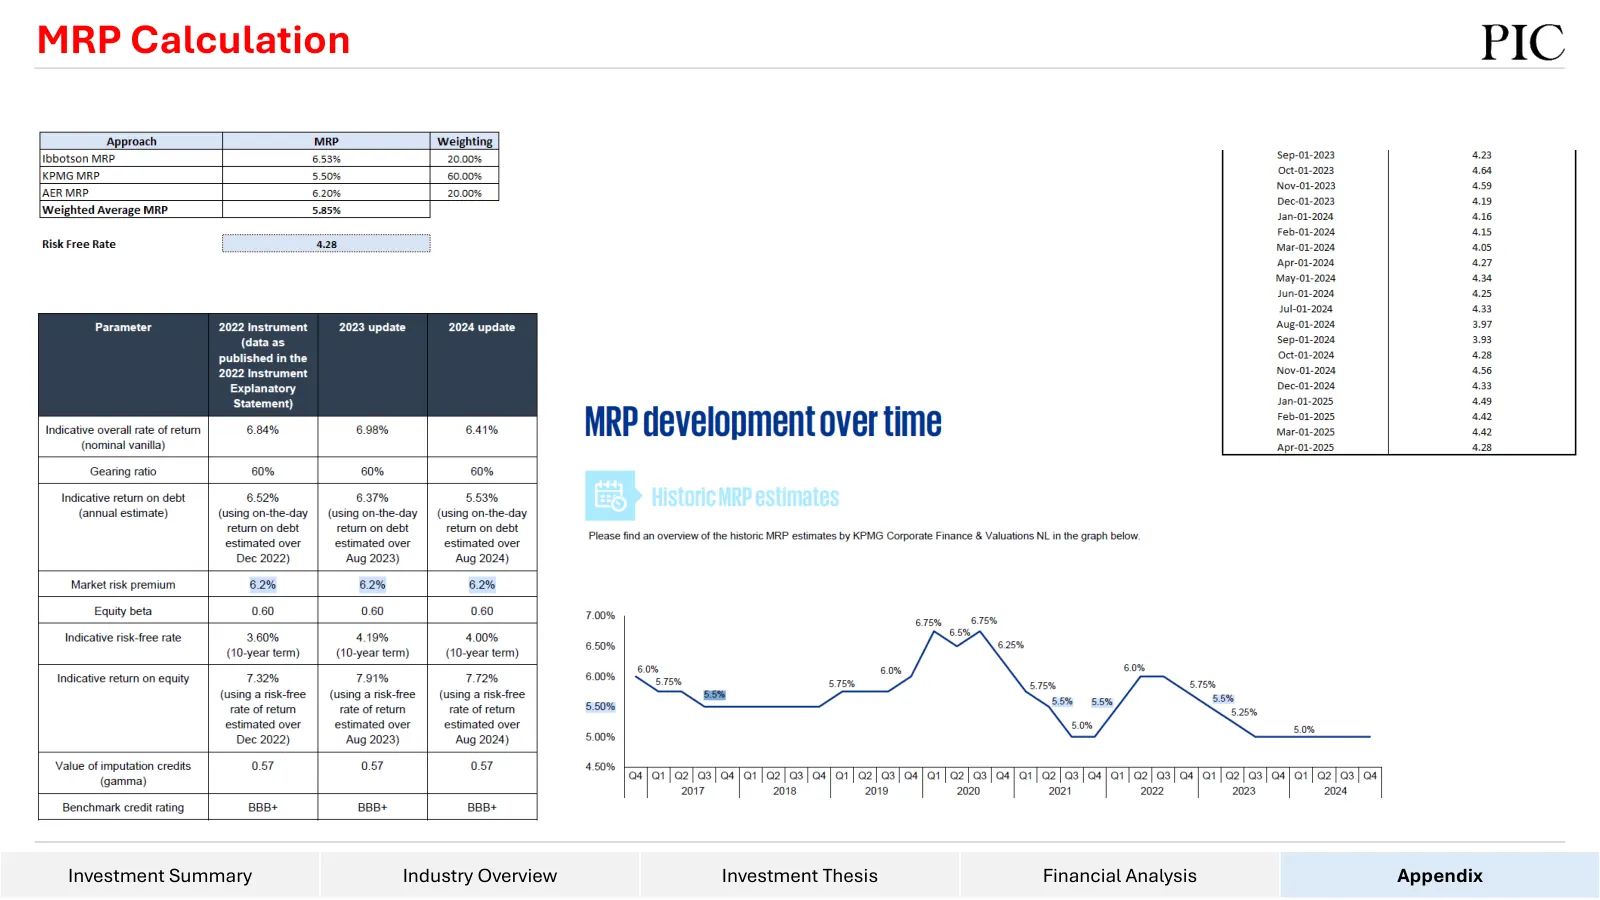
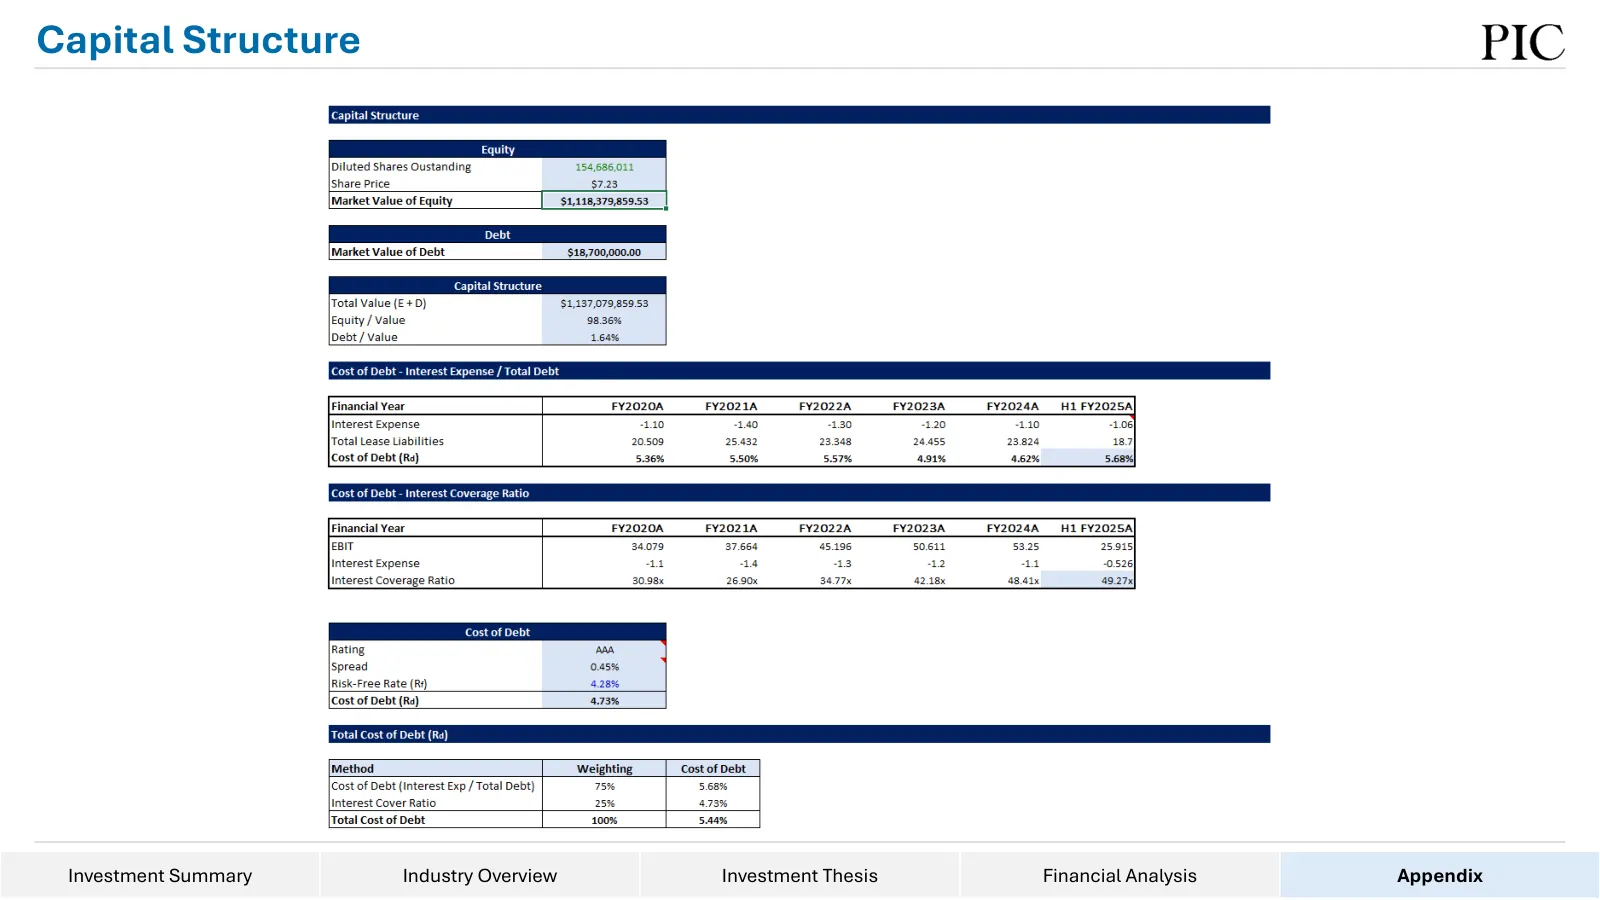
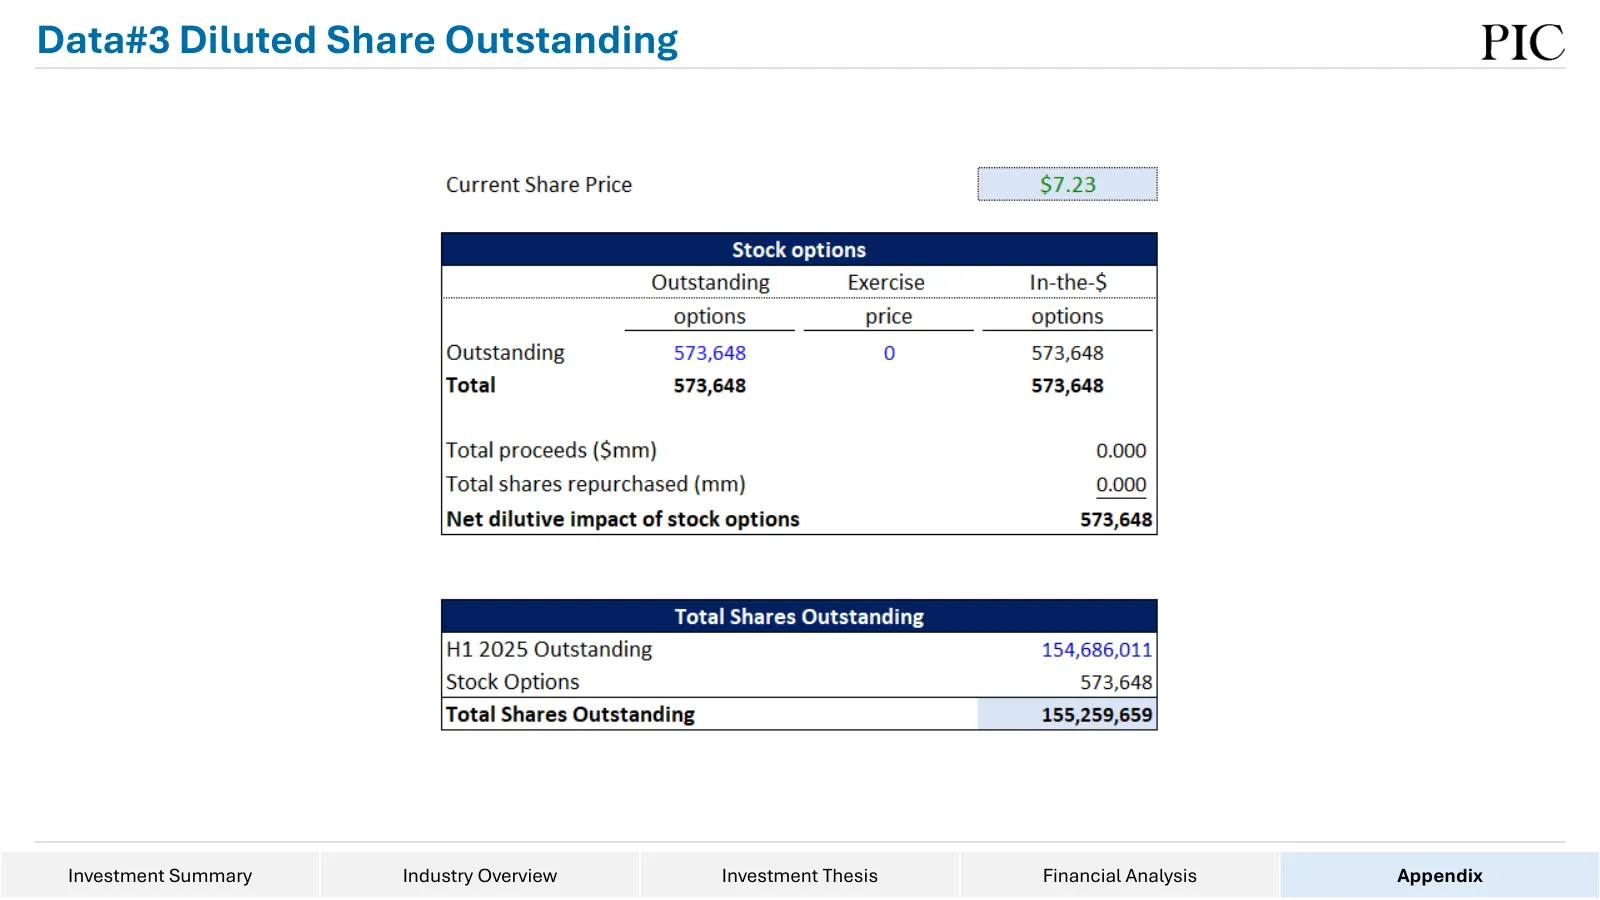
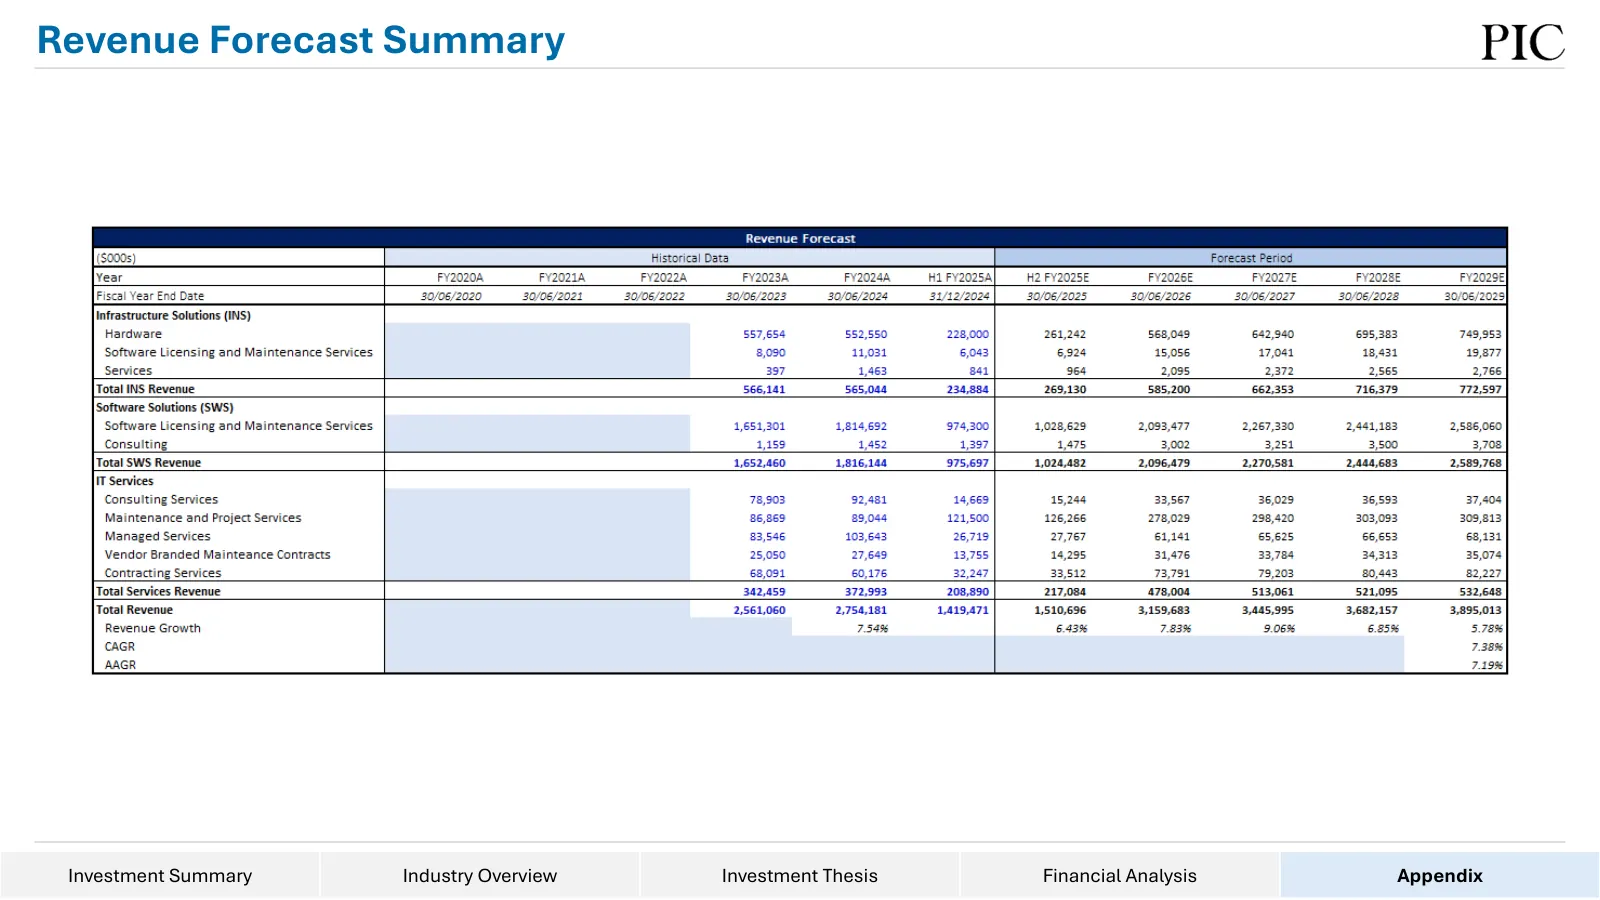
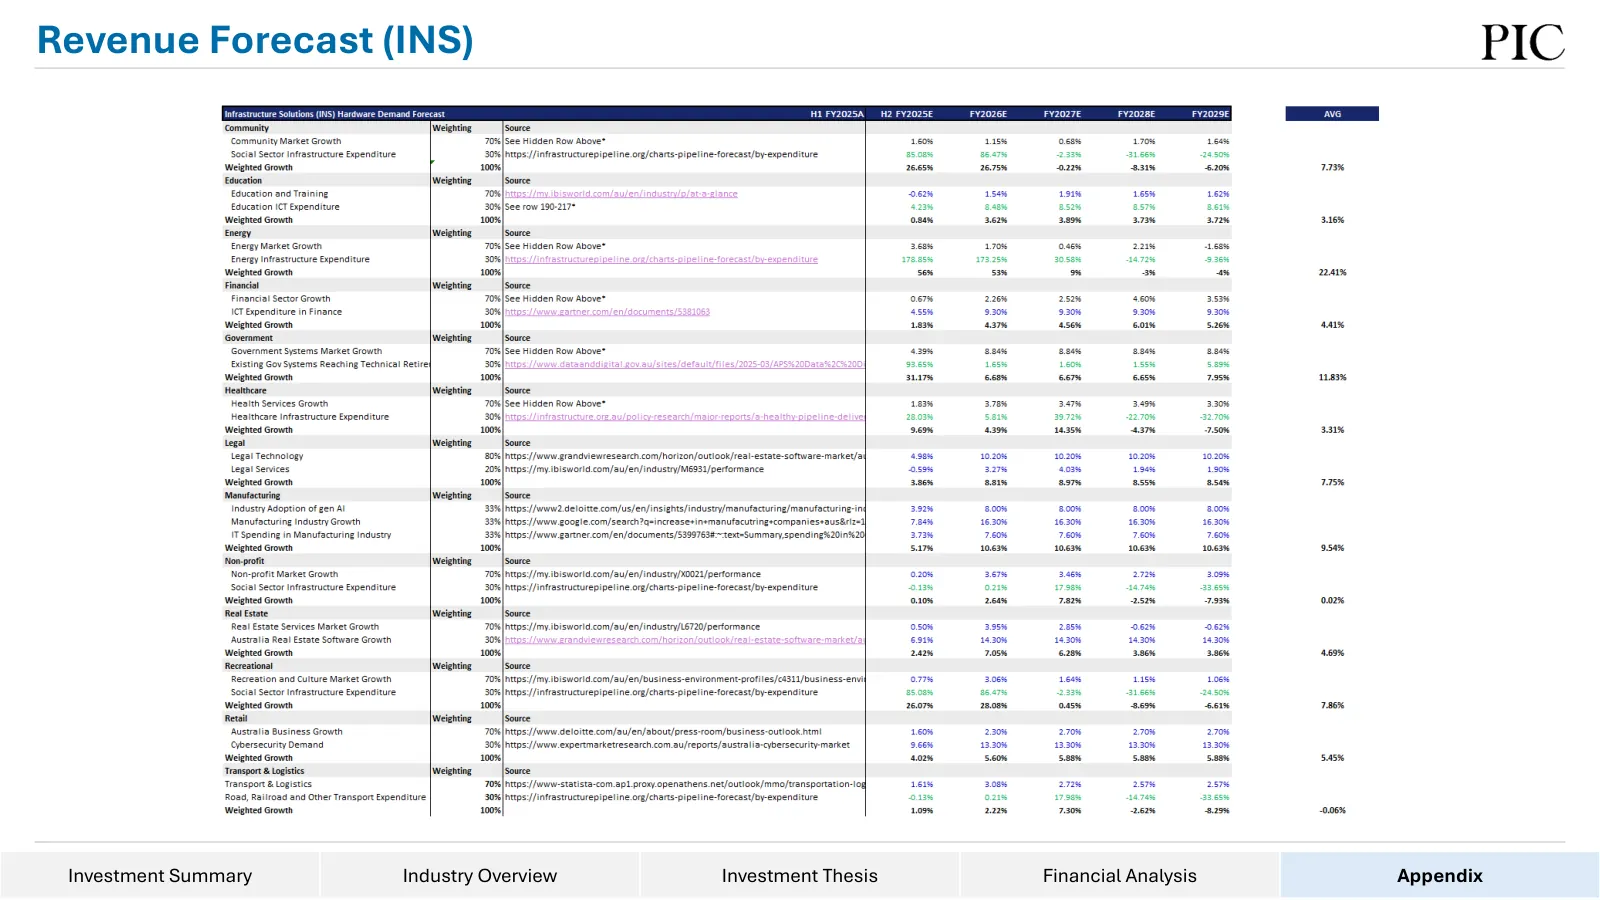
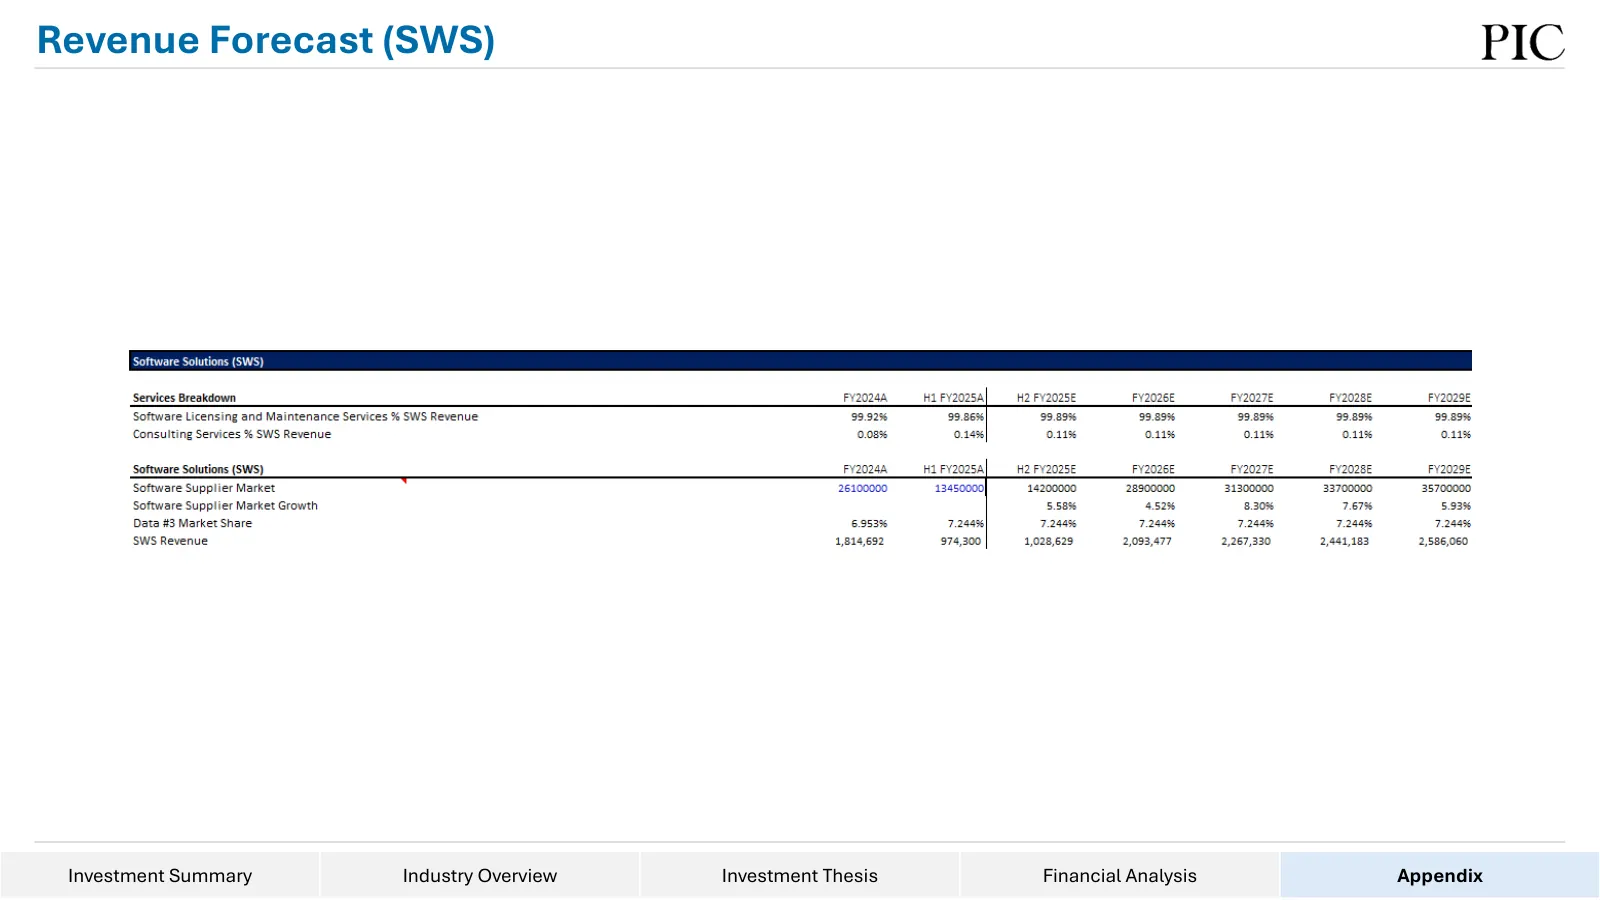
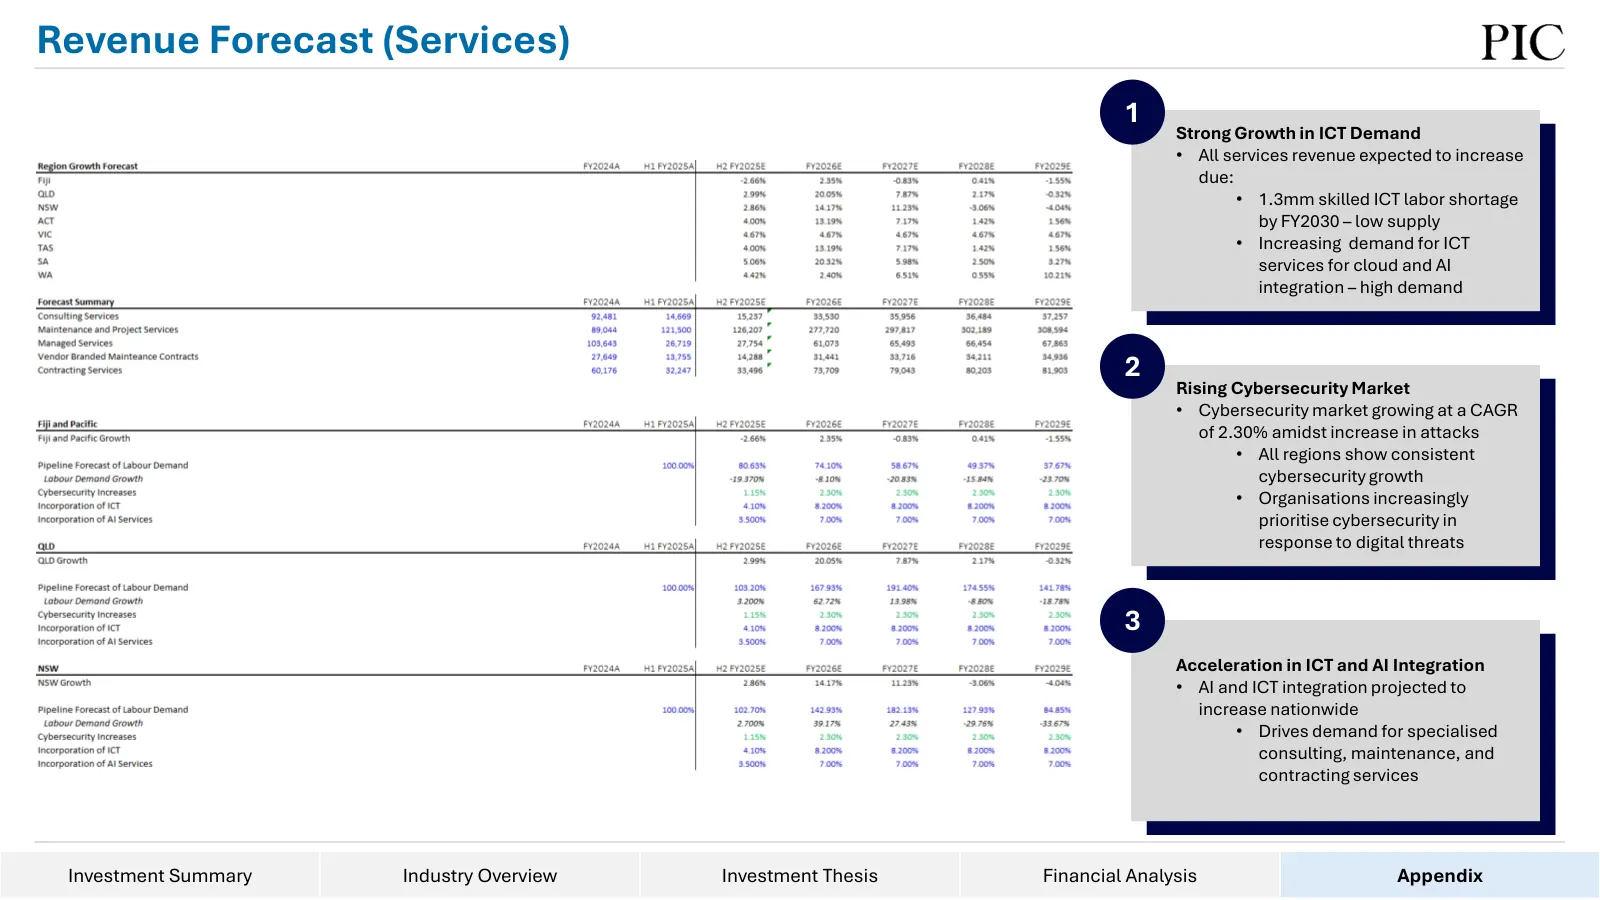
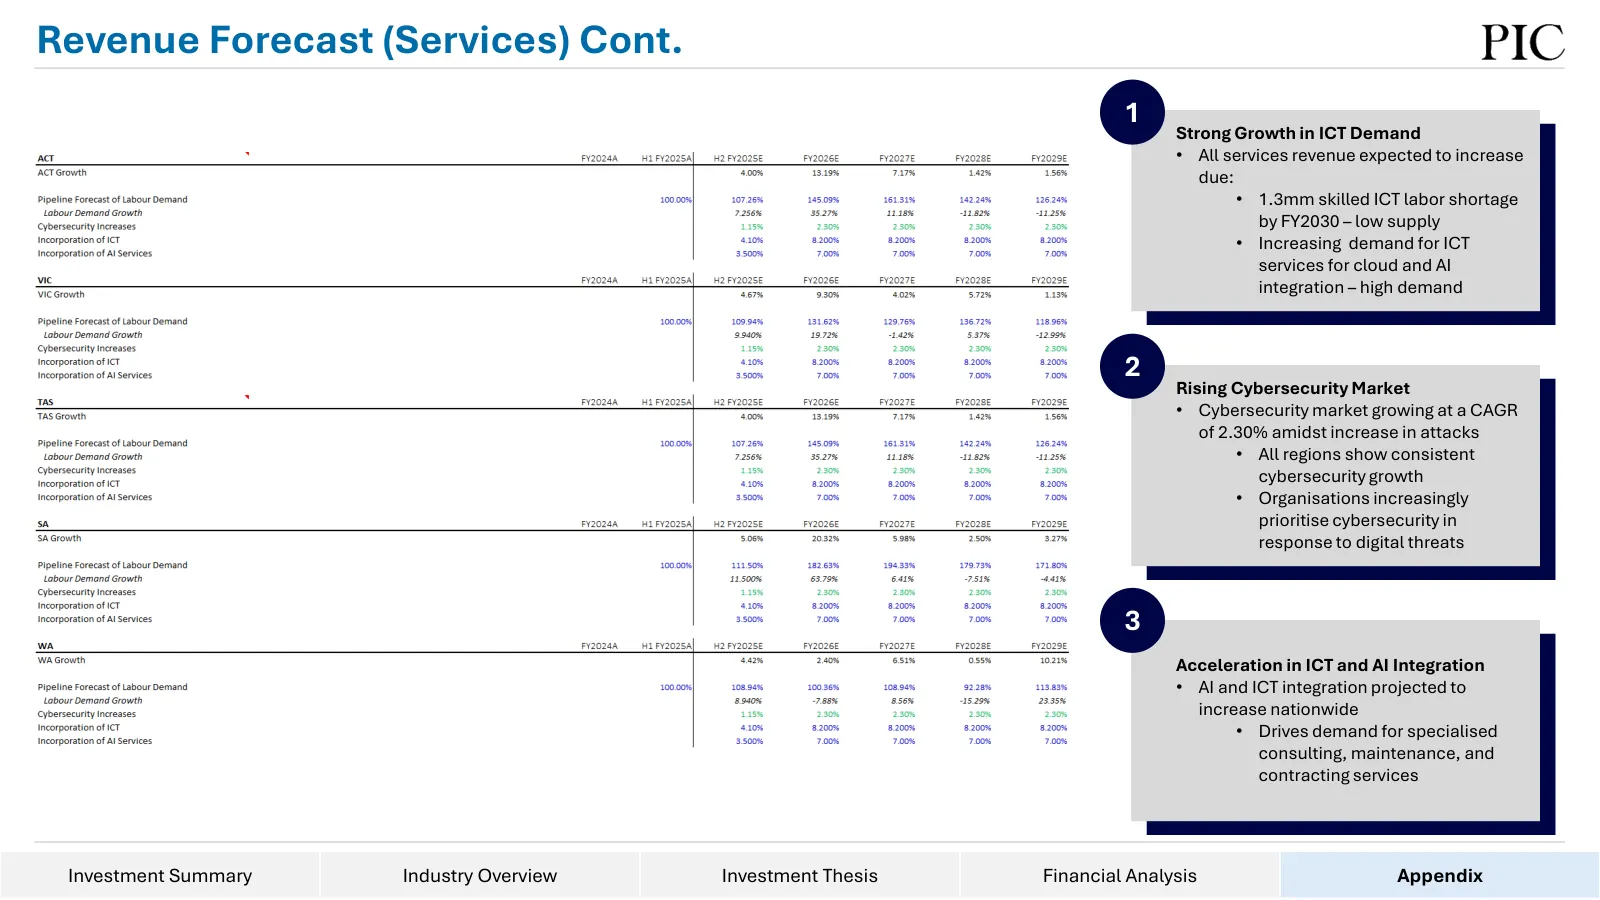
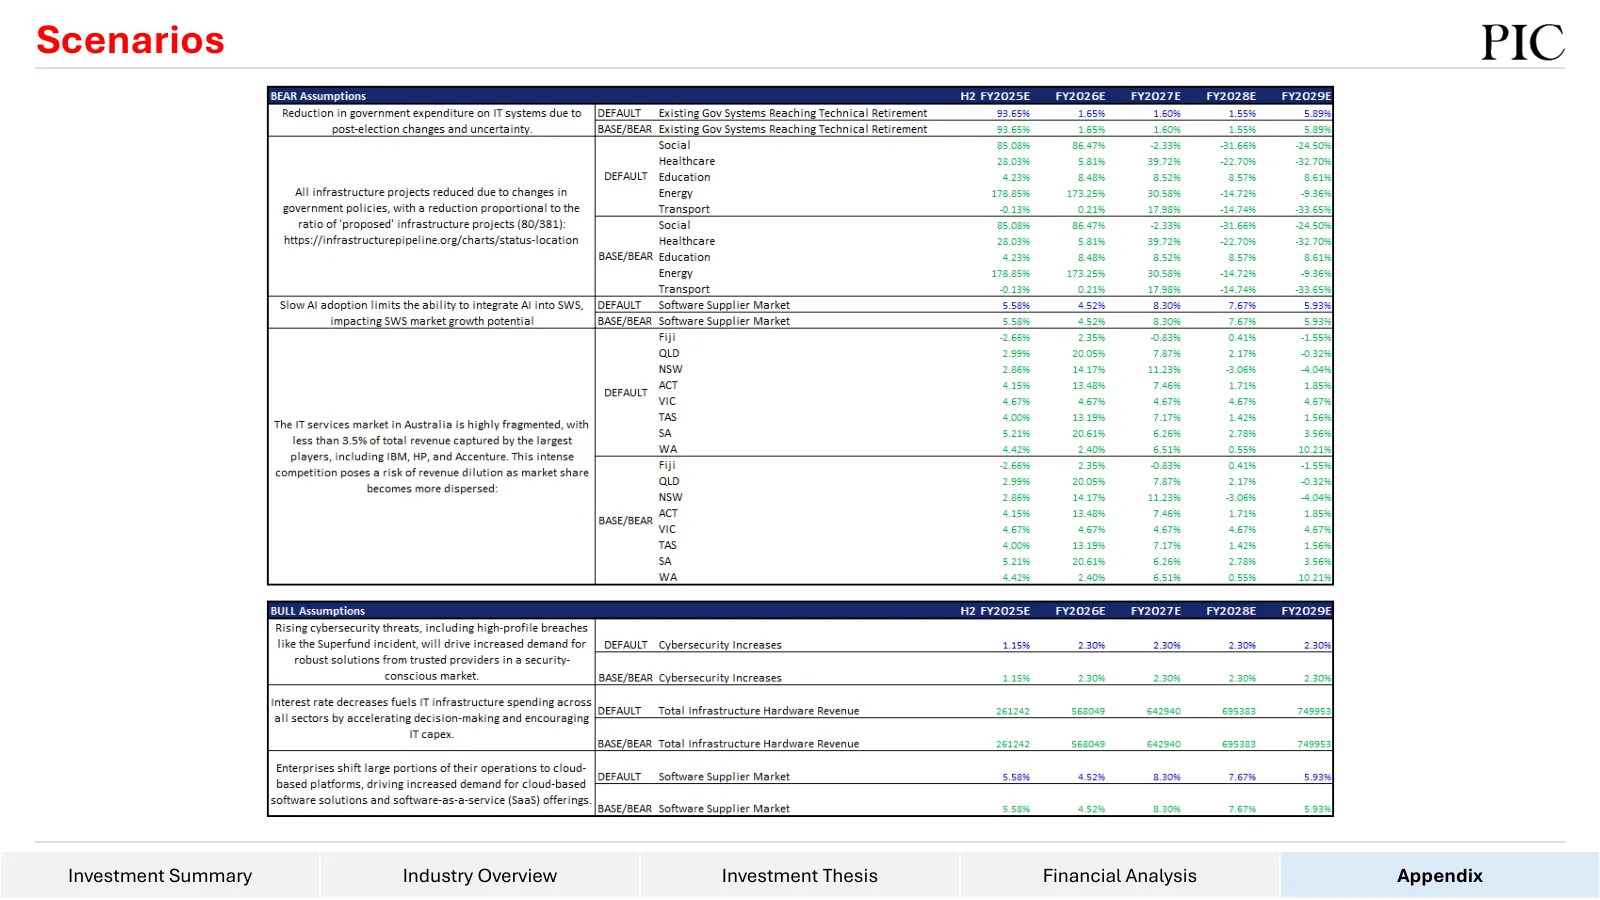
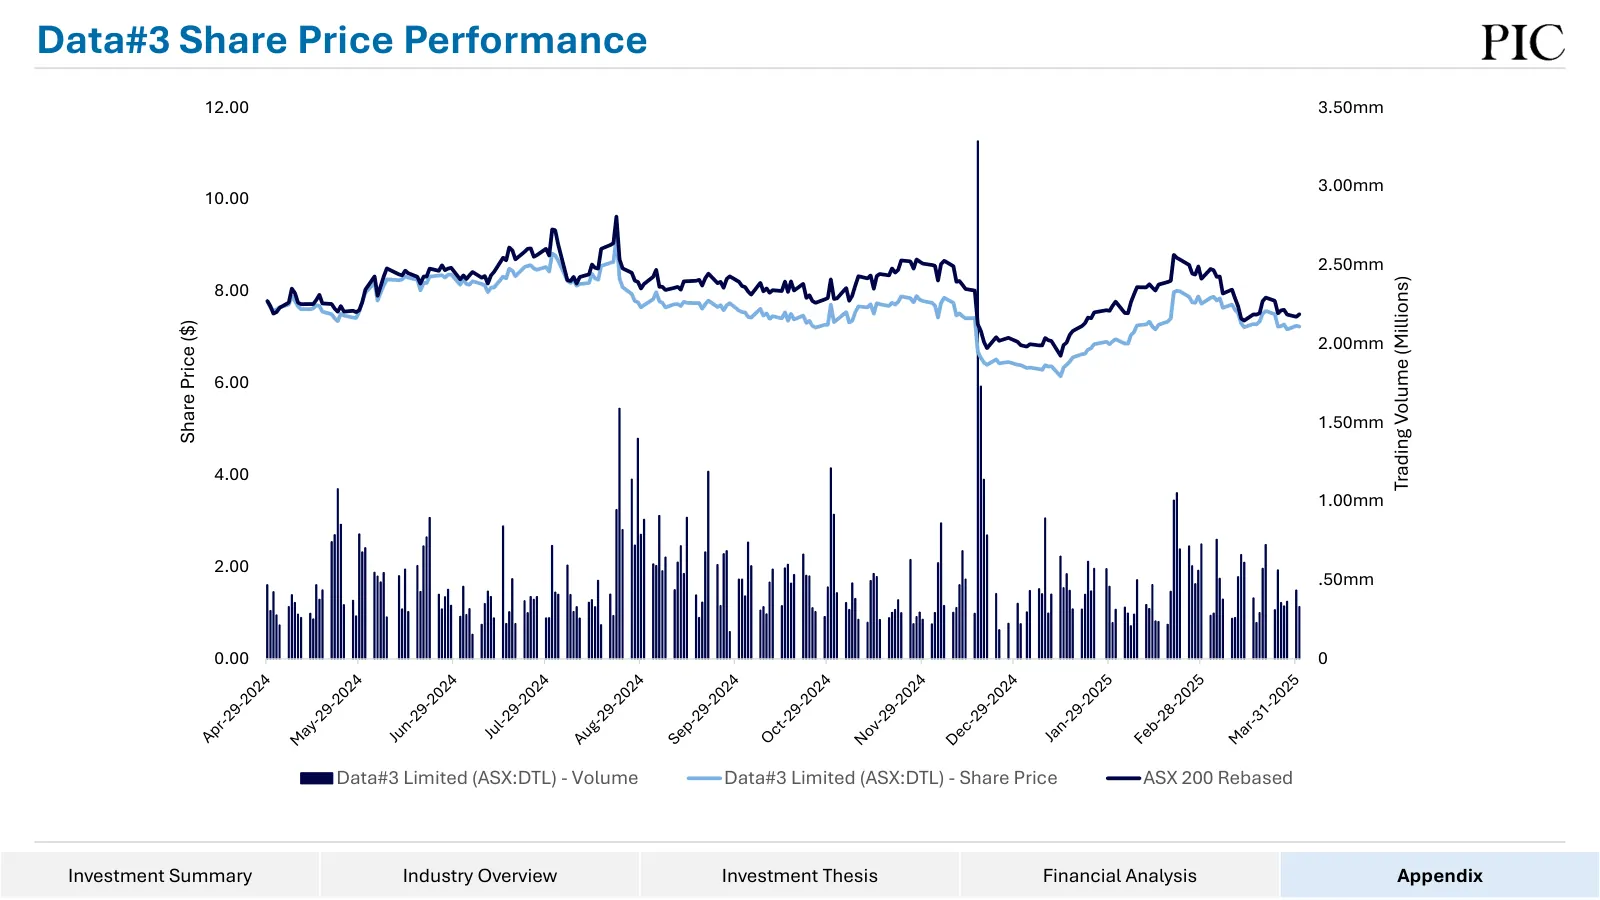
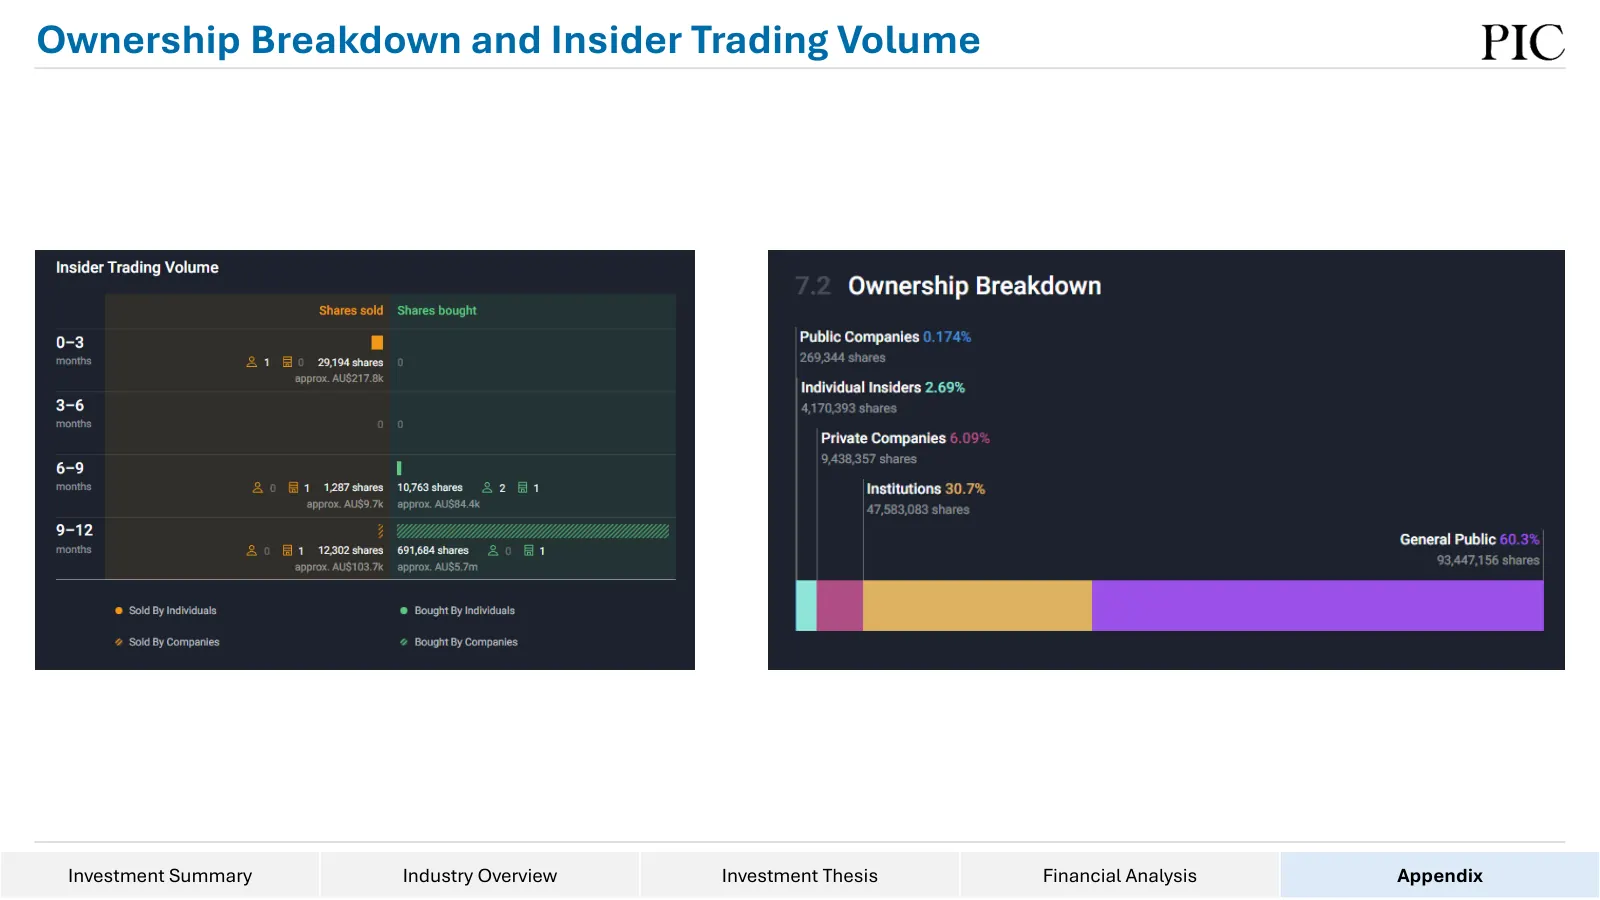
Data#3: overweight at A$7.23, with a A$10.02 target. April 2025, for UQ's student-managed investment fund. The market was pricing in recession fears and missing long-term IT demand and the company's position in cloud, software and AI. Discount rates from both CAPM and a Fama-French model with an ESG factor, with the risk modelling in Python and R. Team of six, as PIC Capital. Finalist.
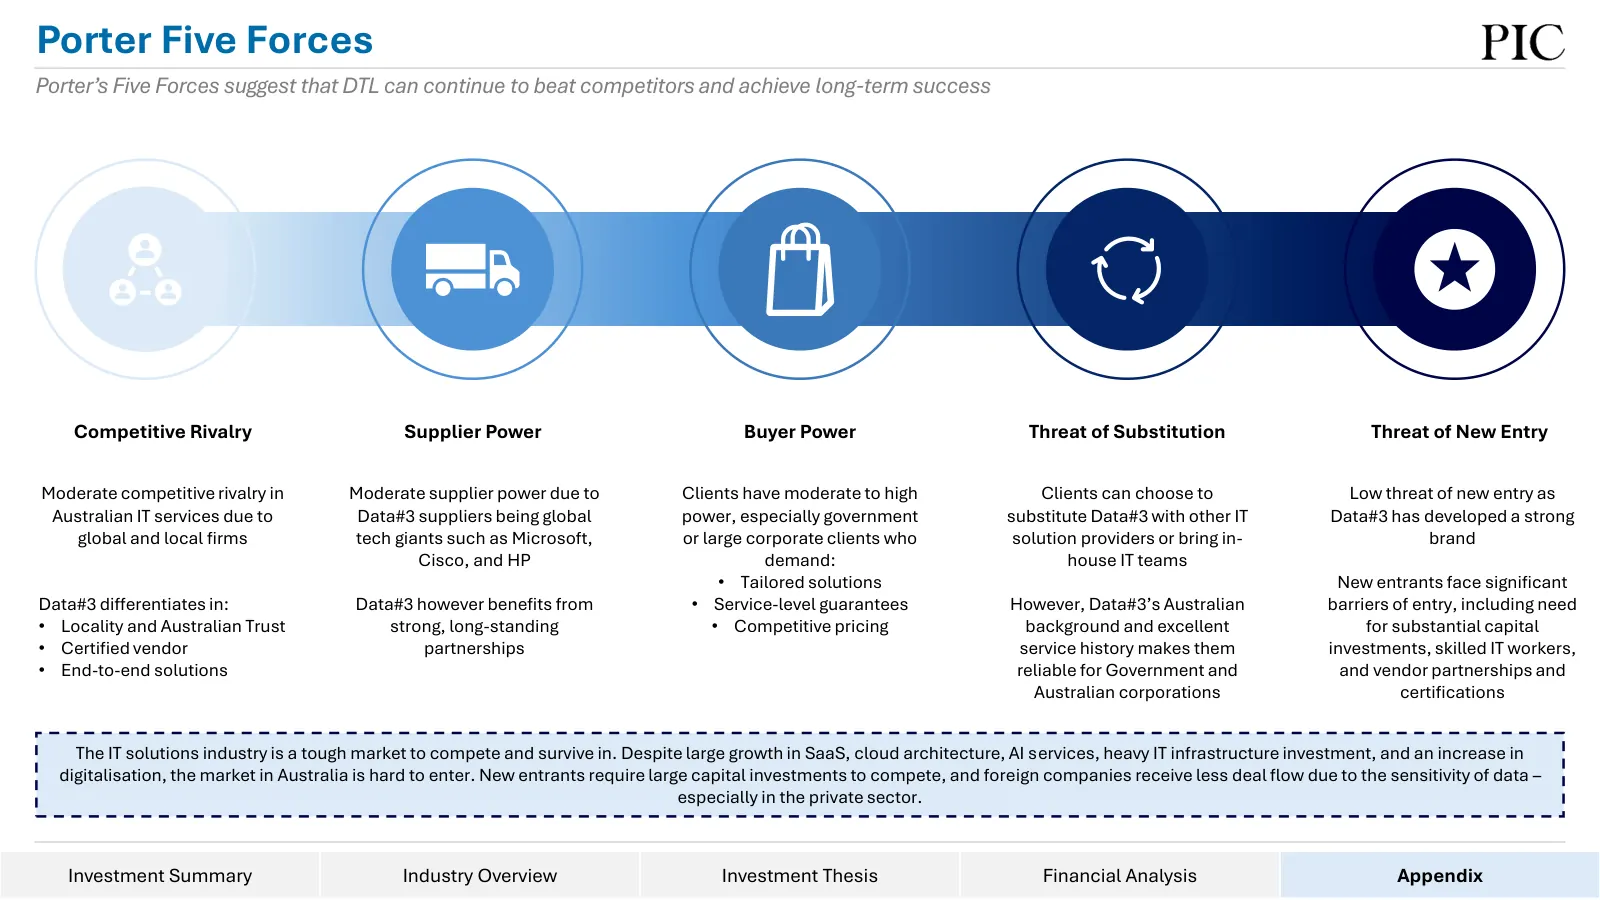
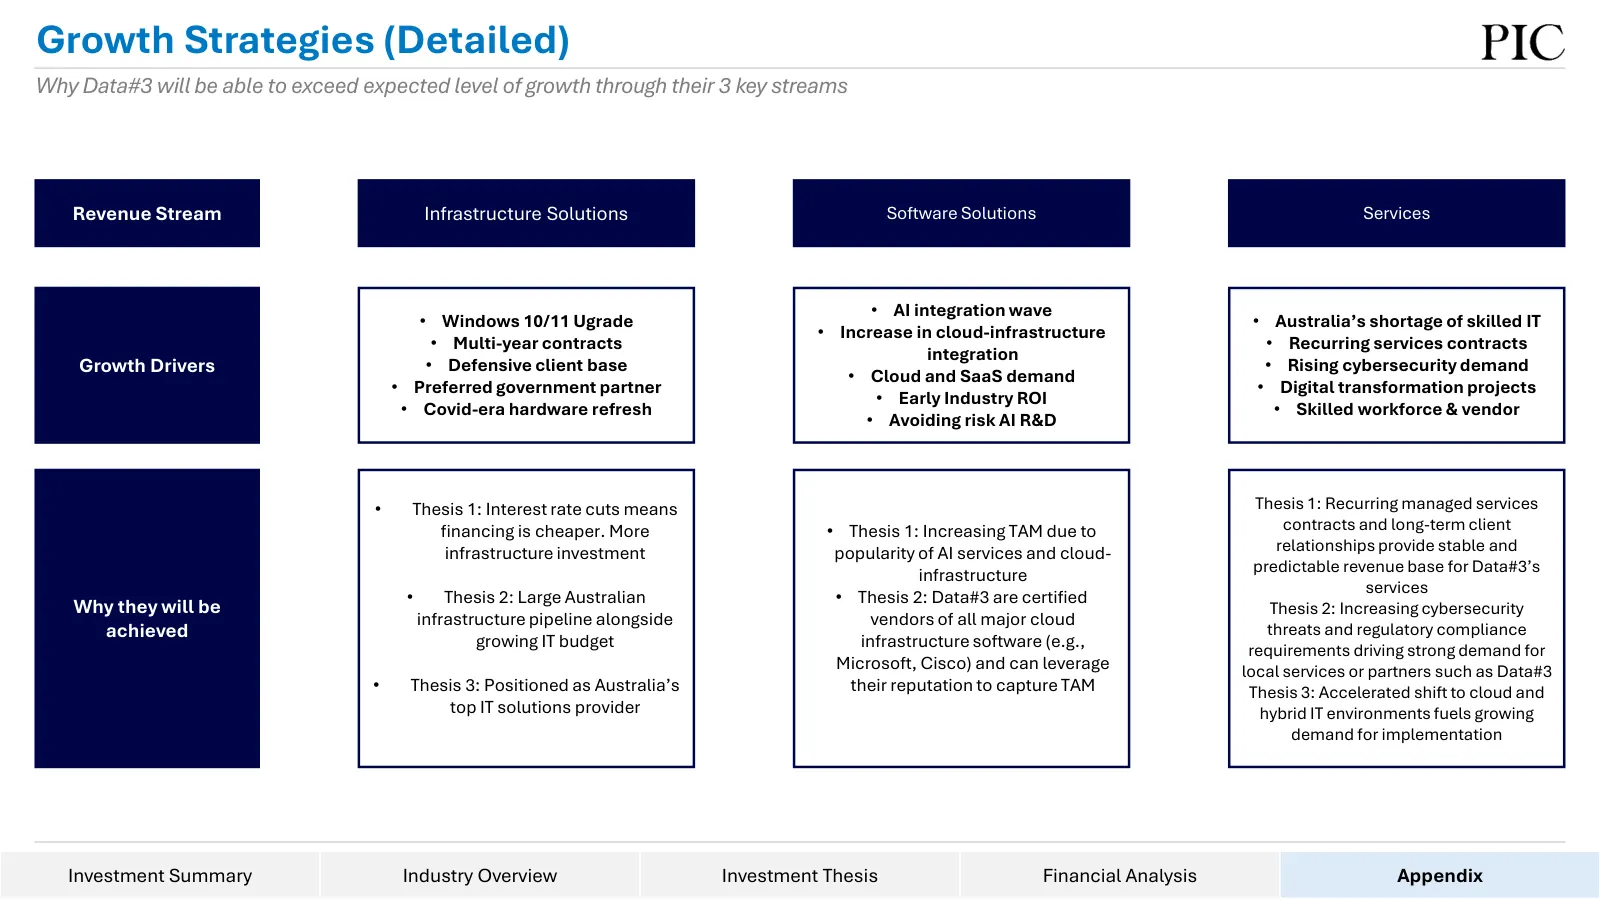
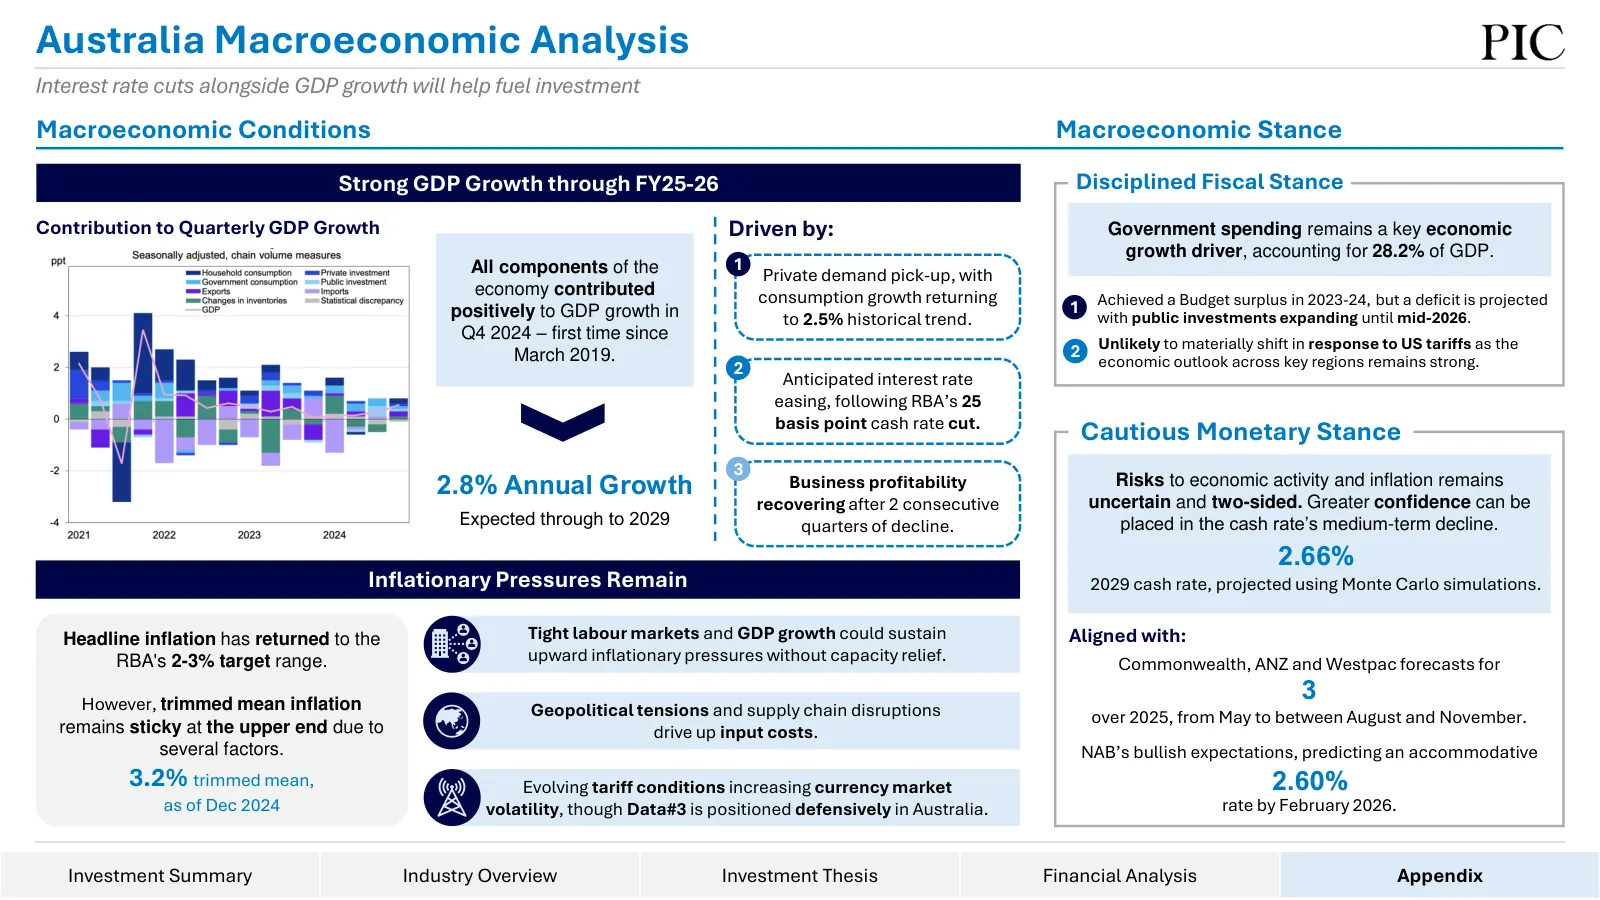
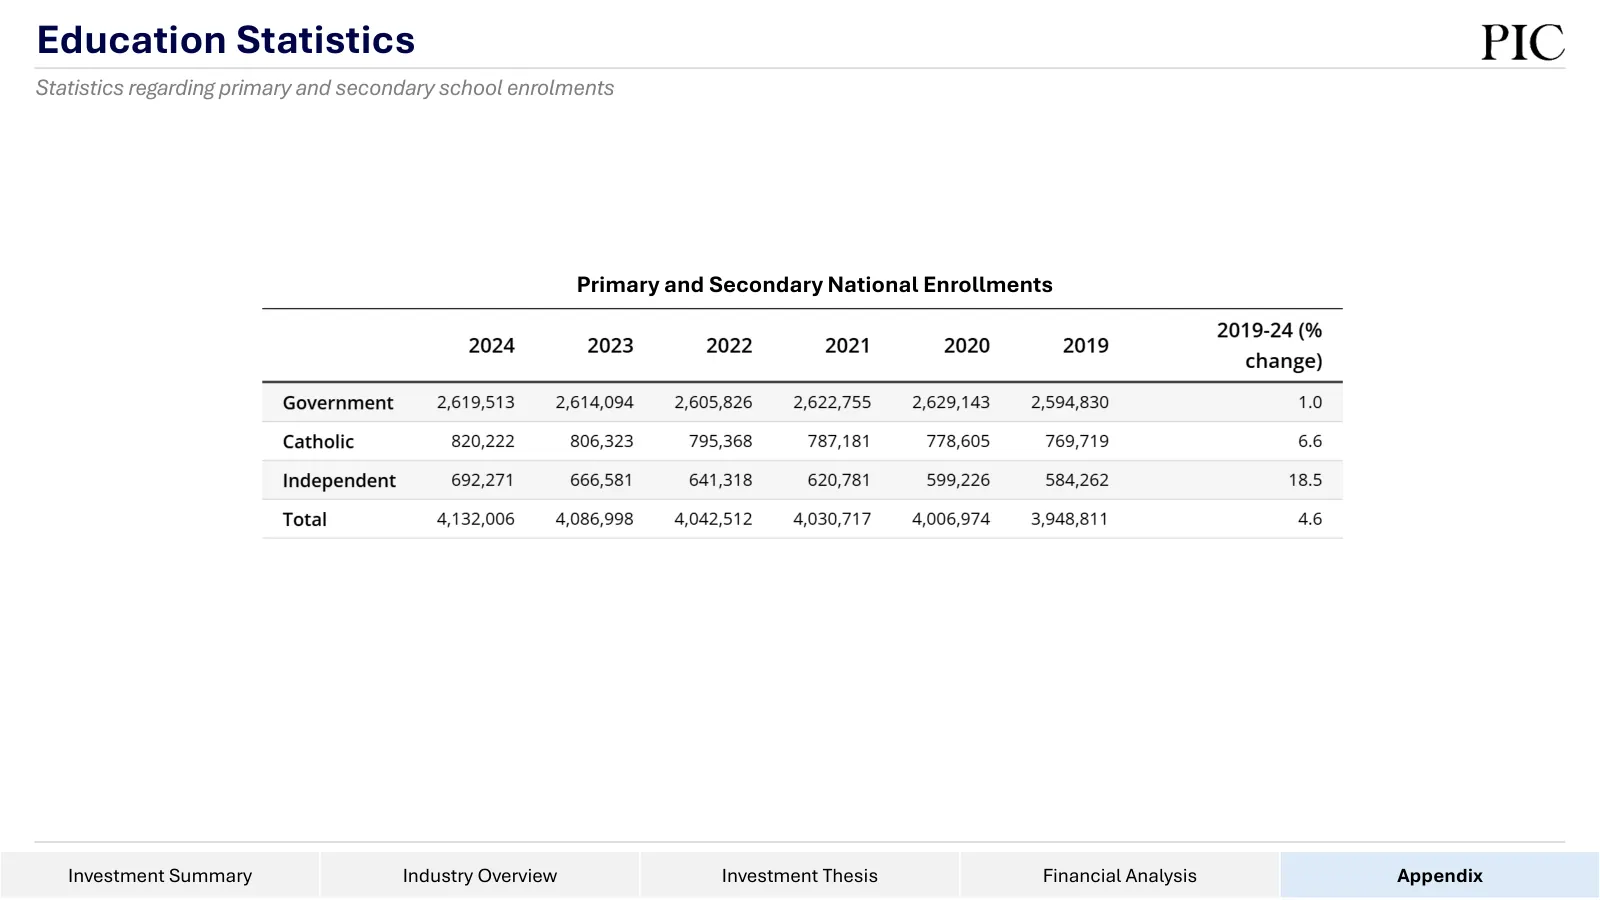
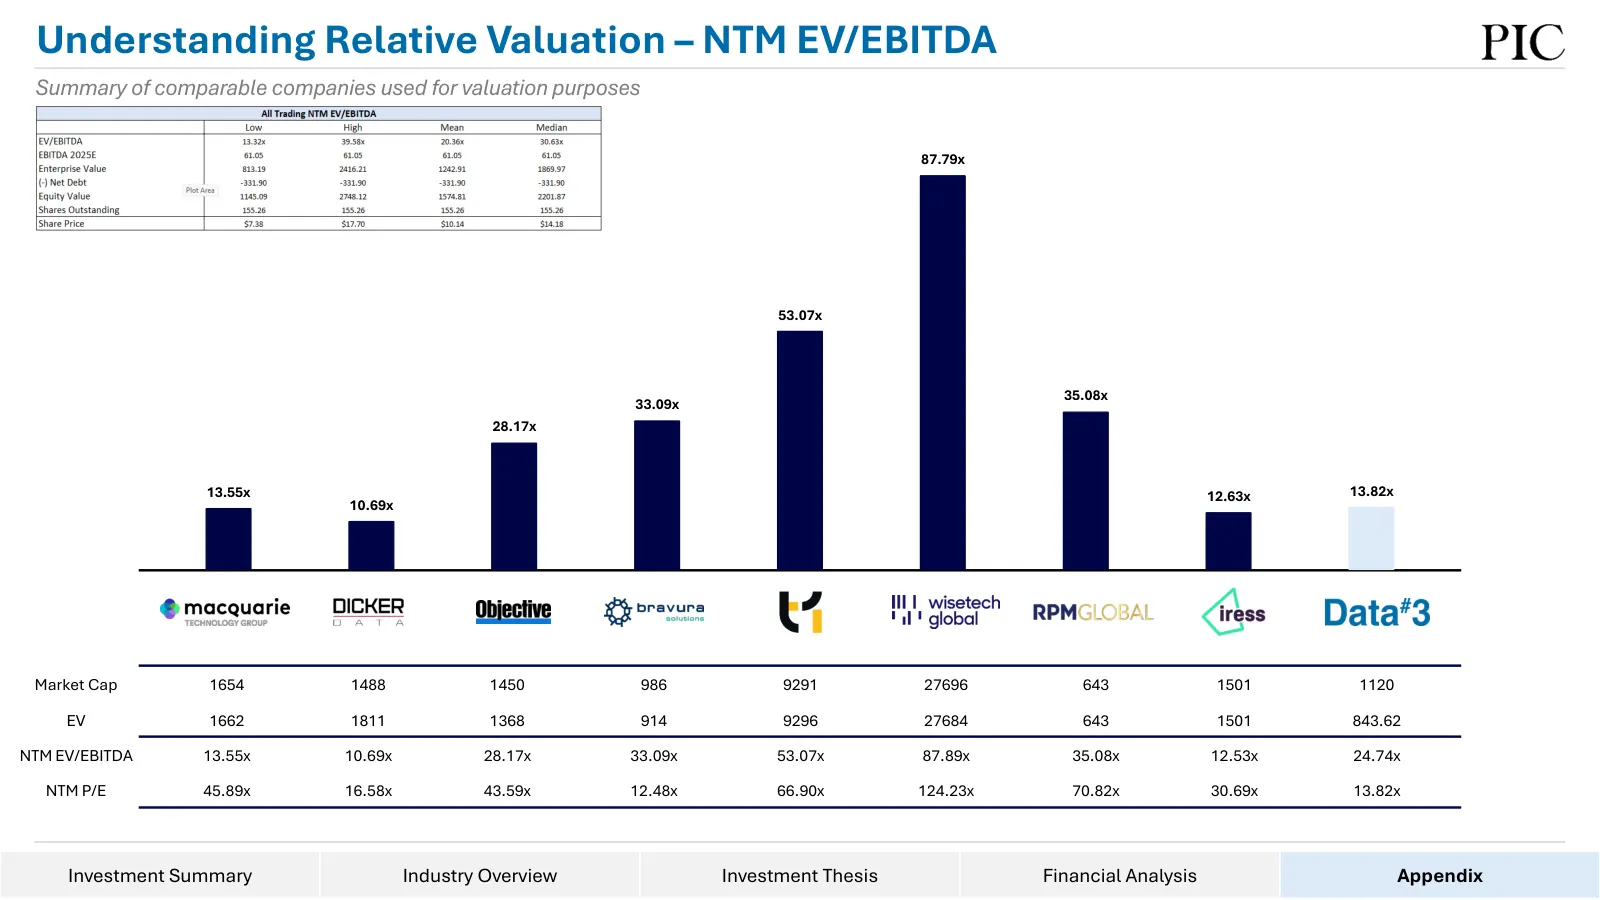
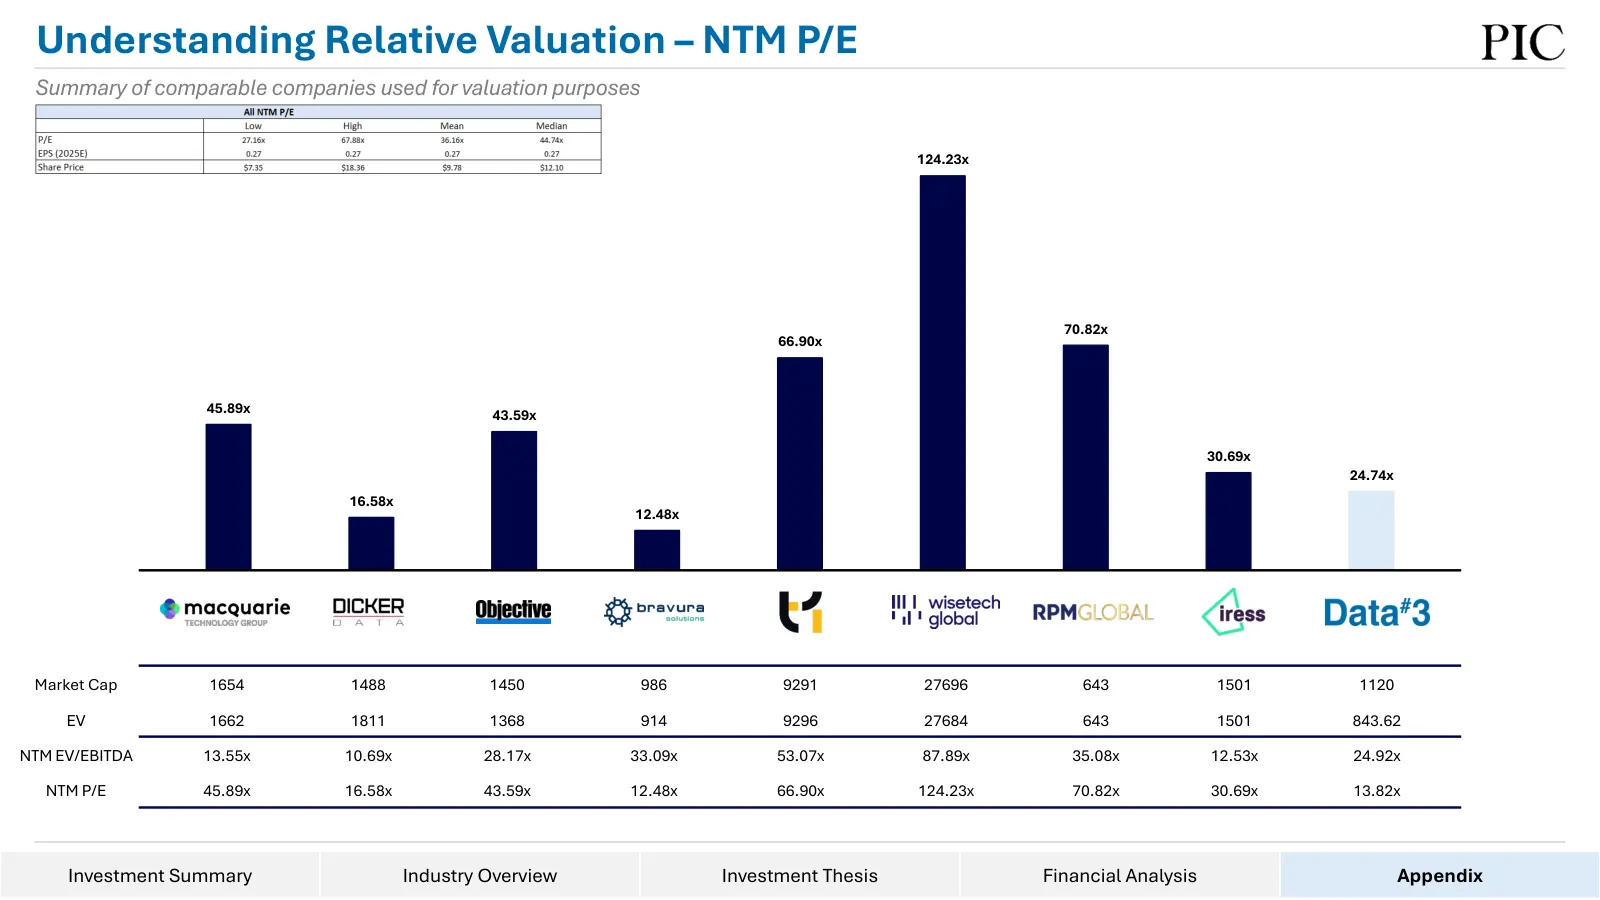
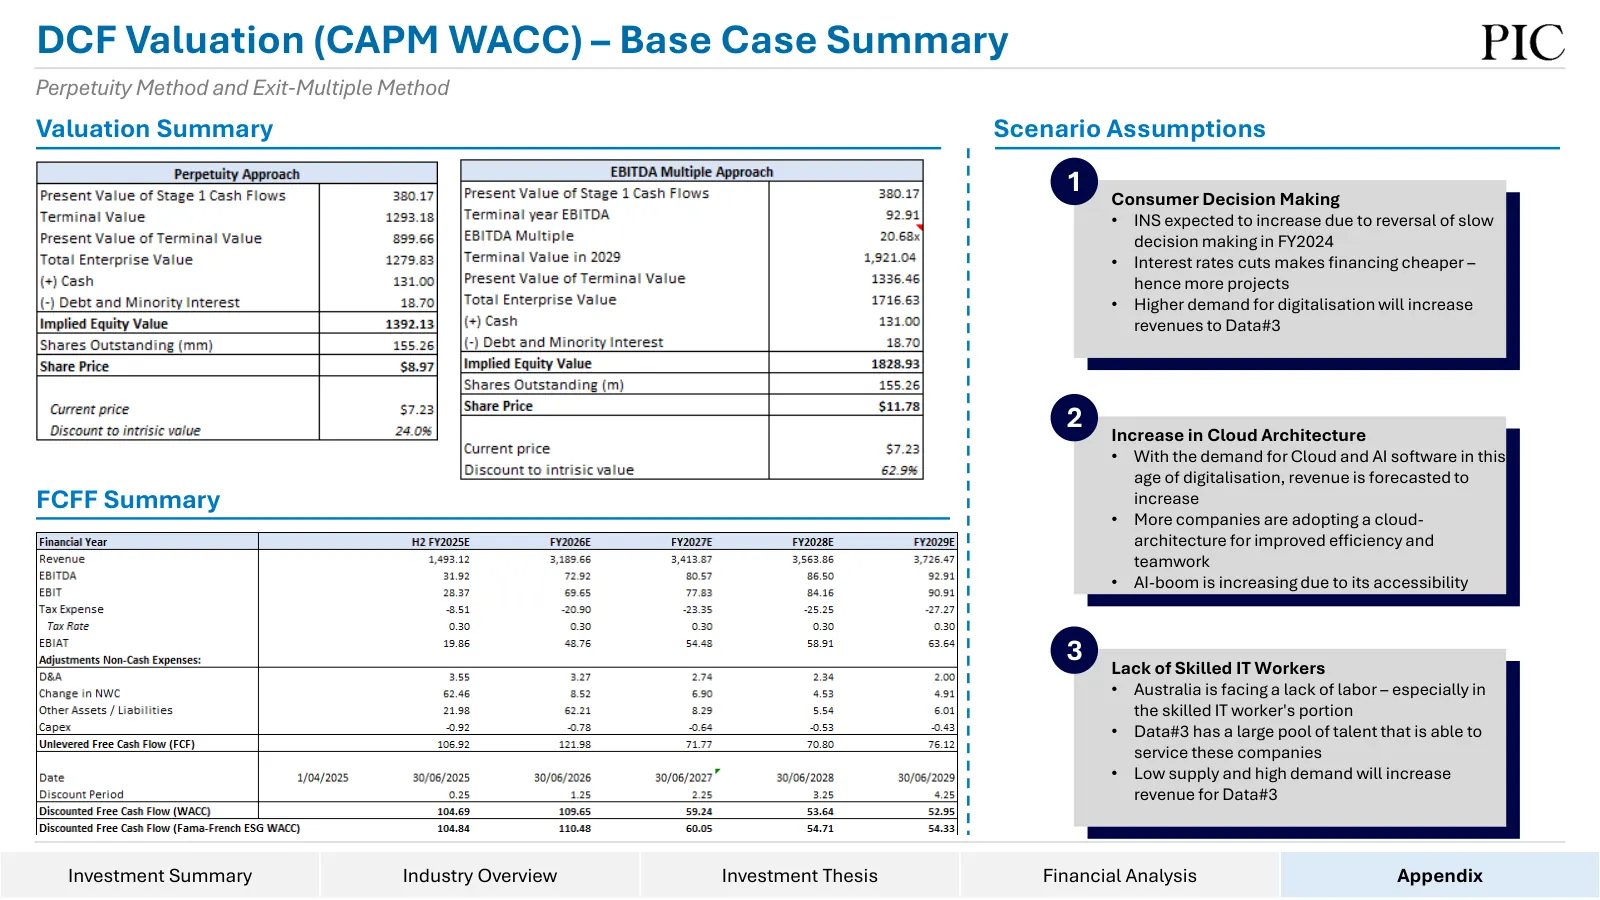
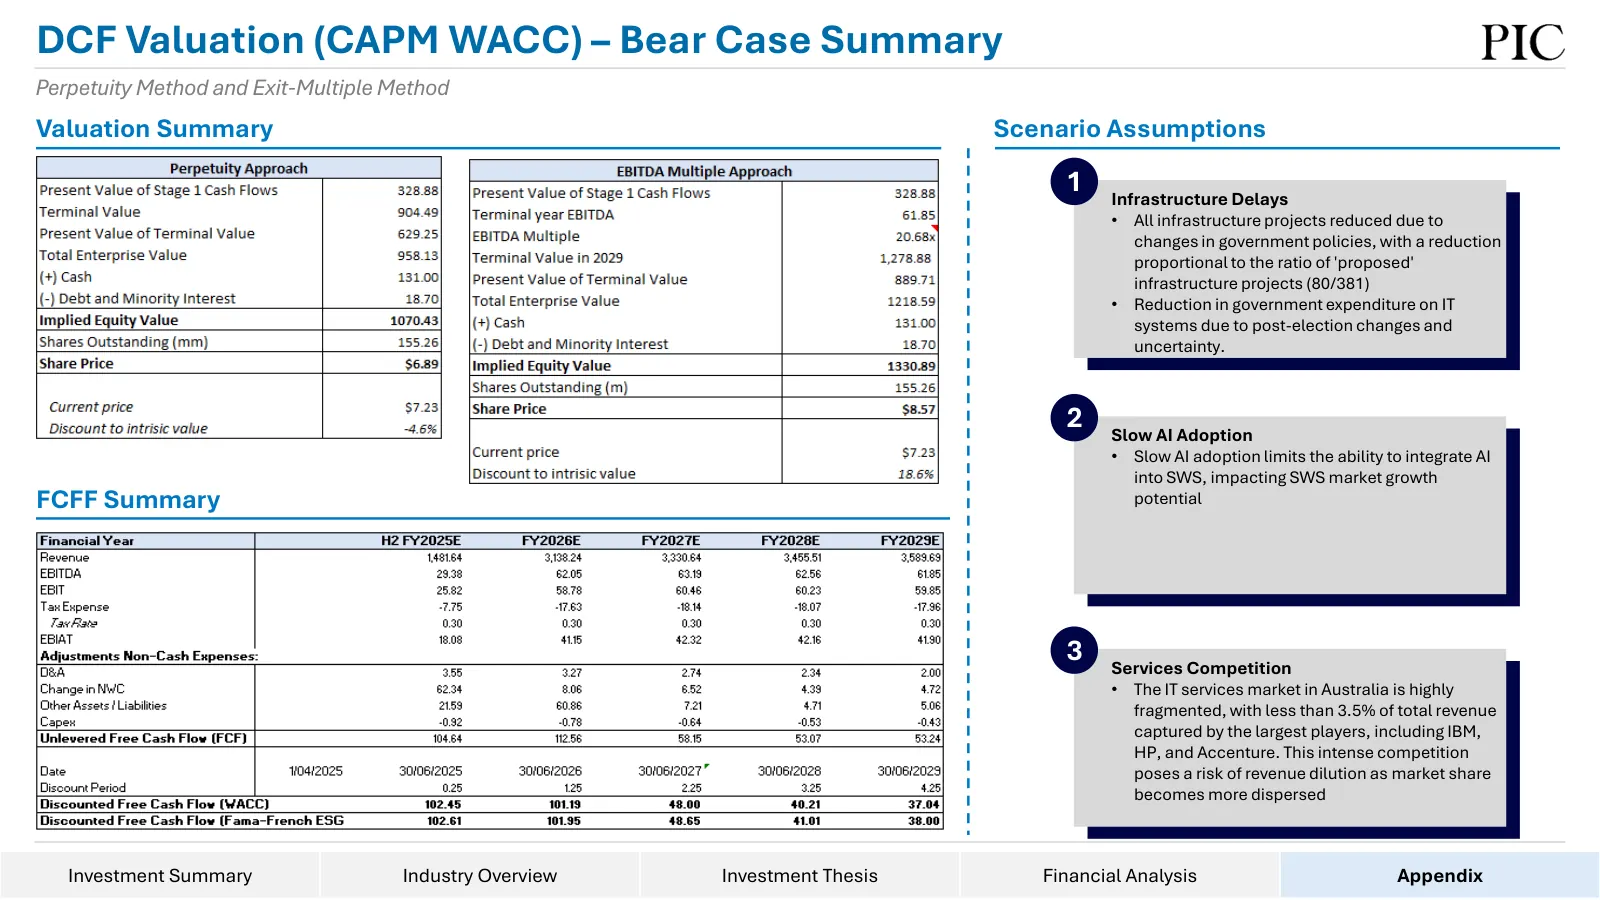
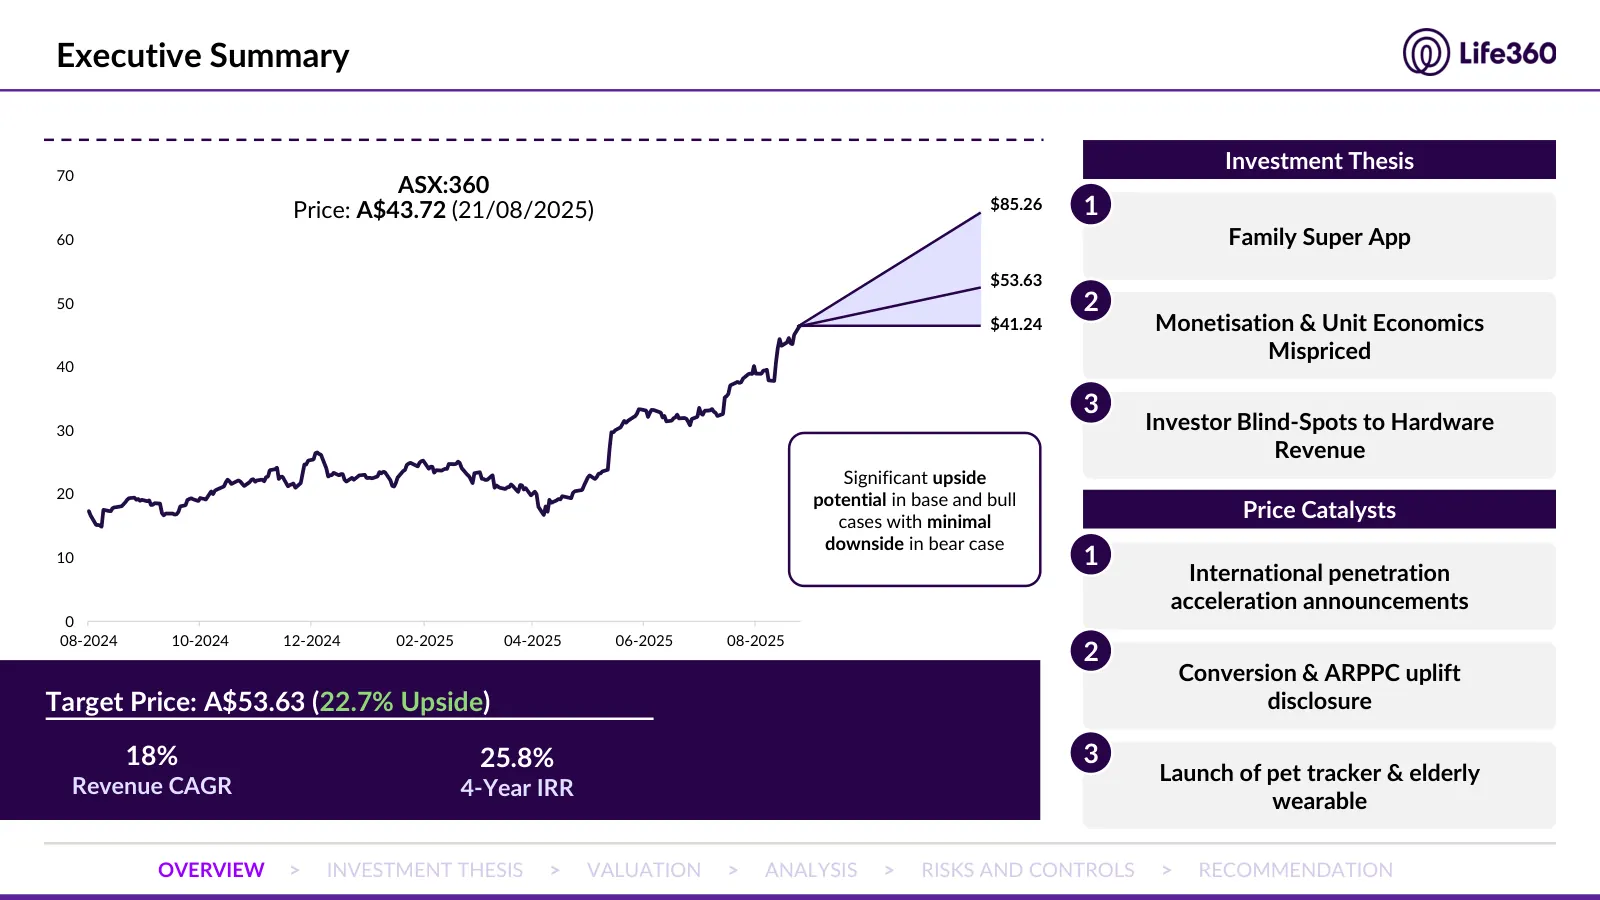
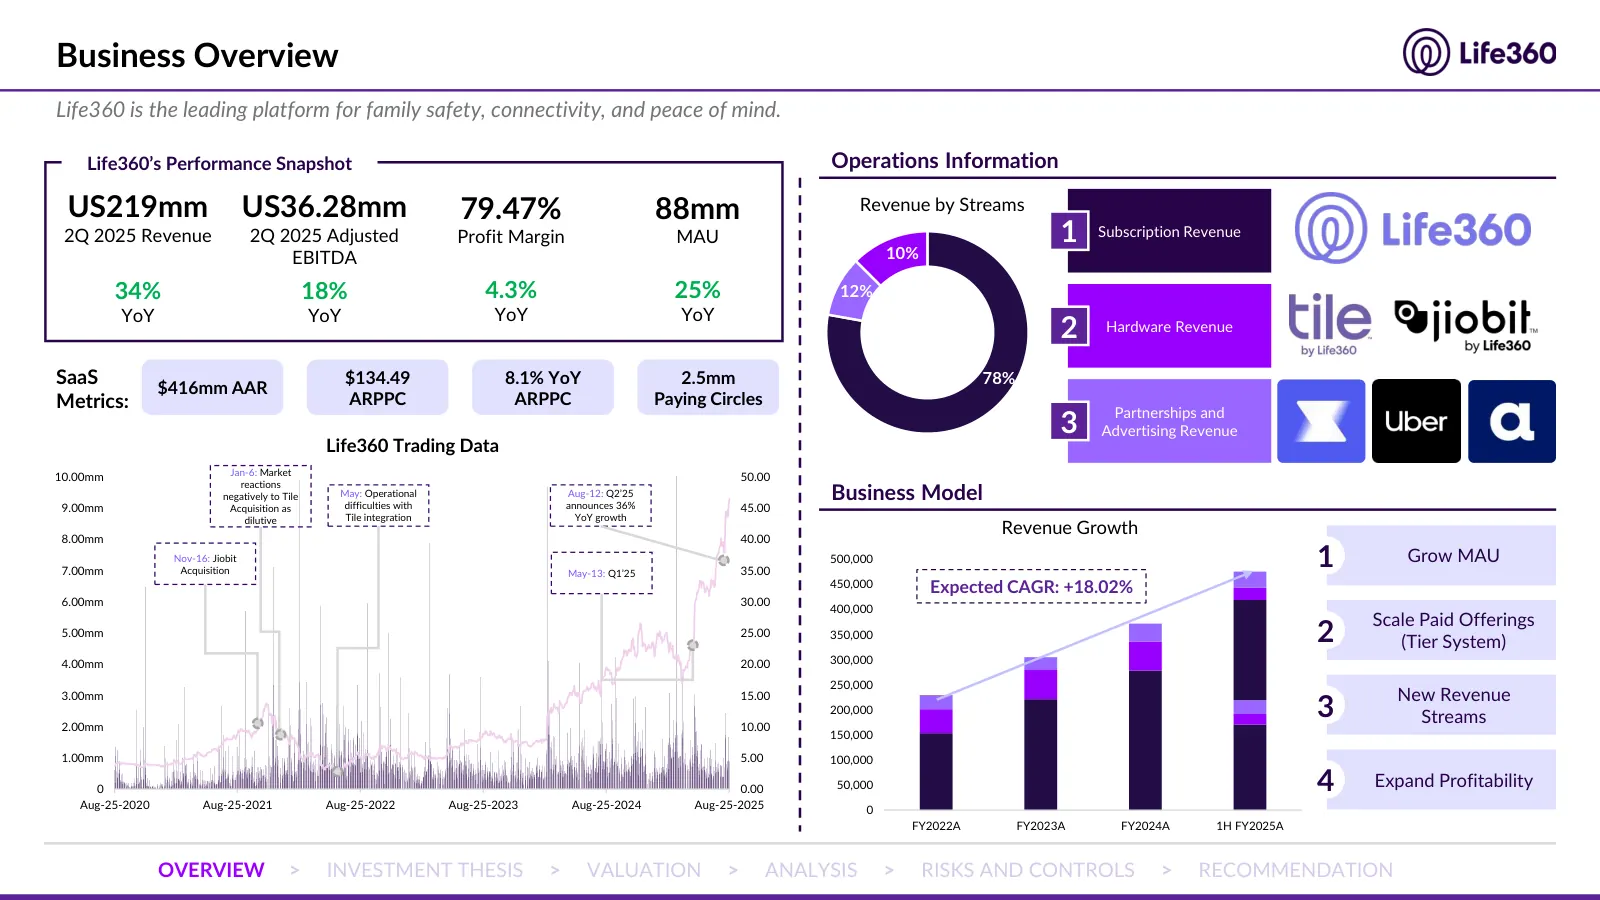
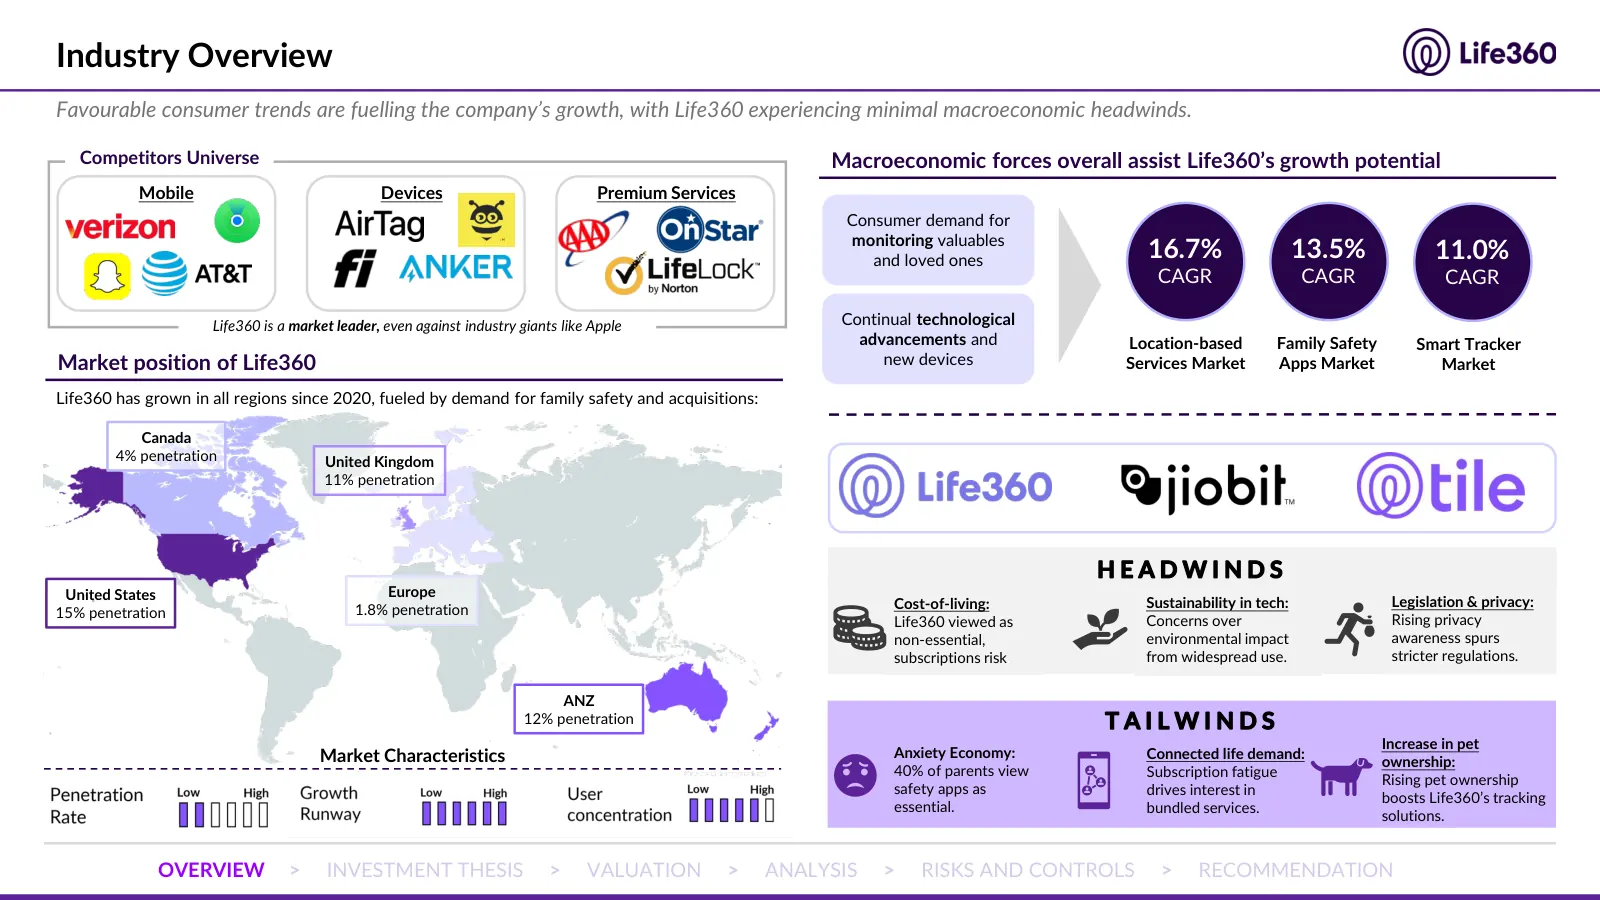
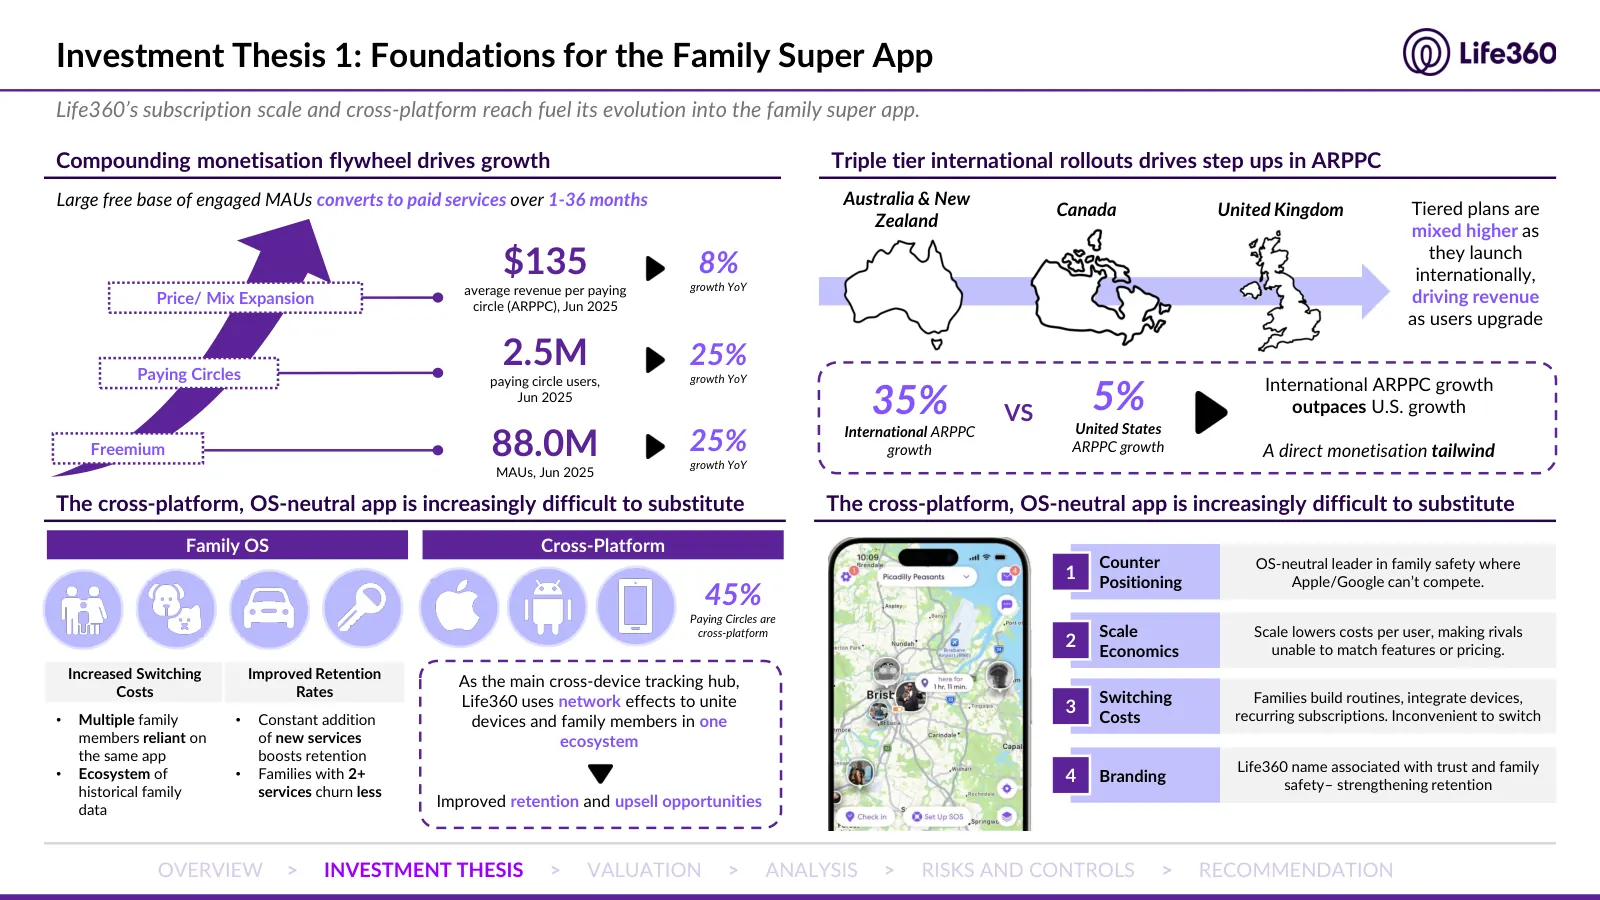
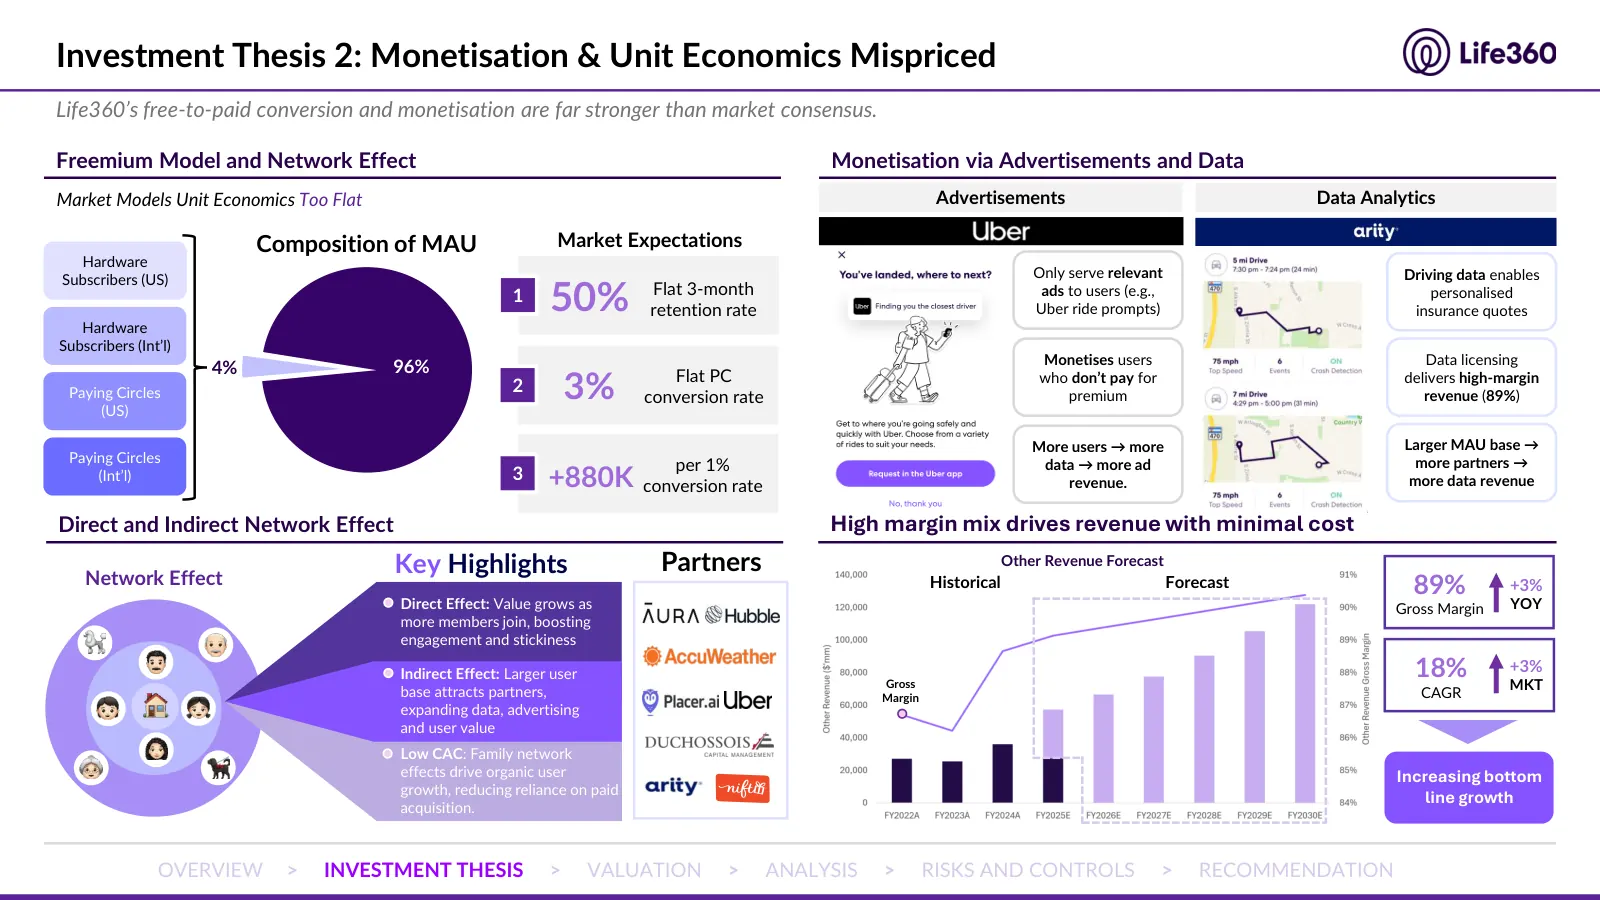
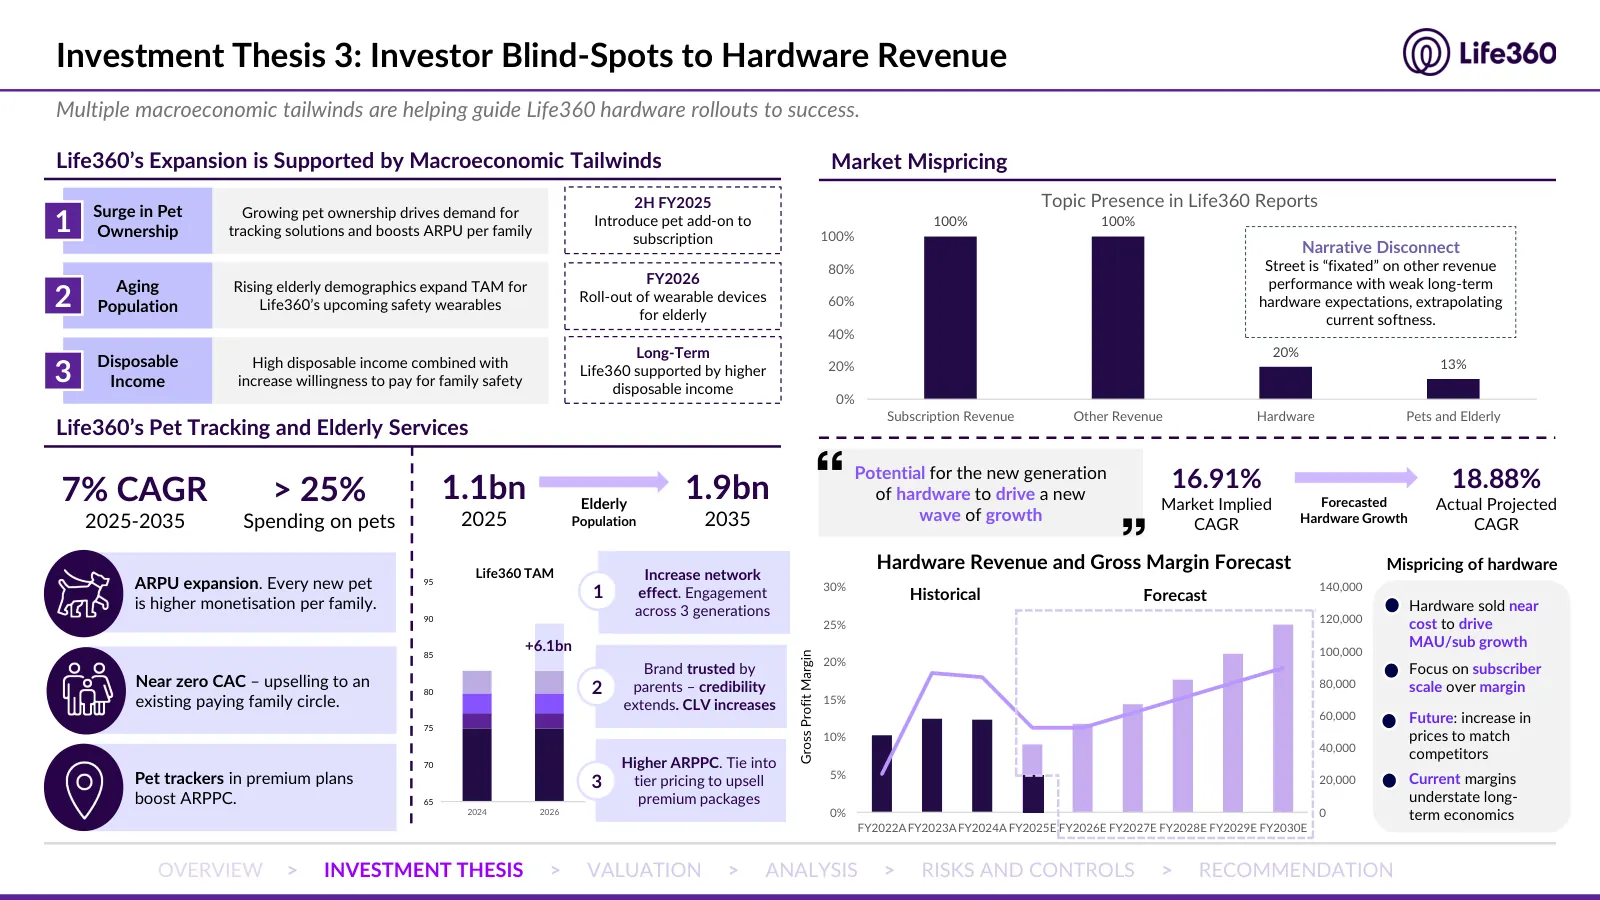
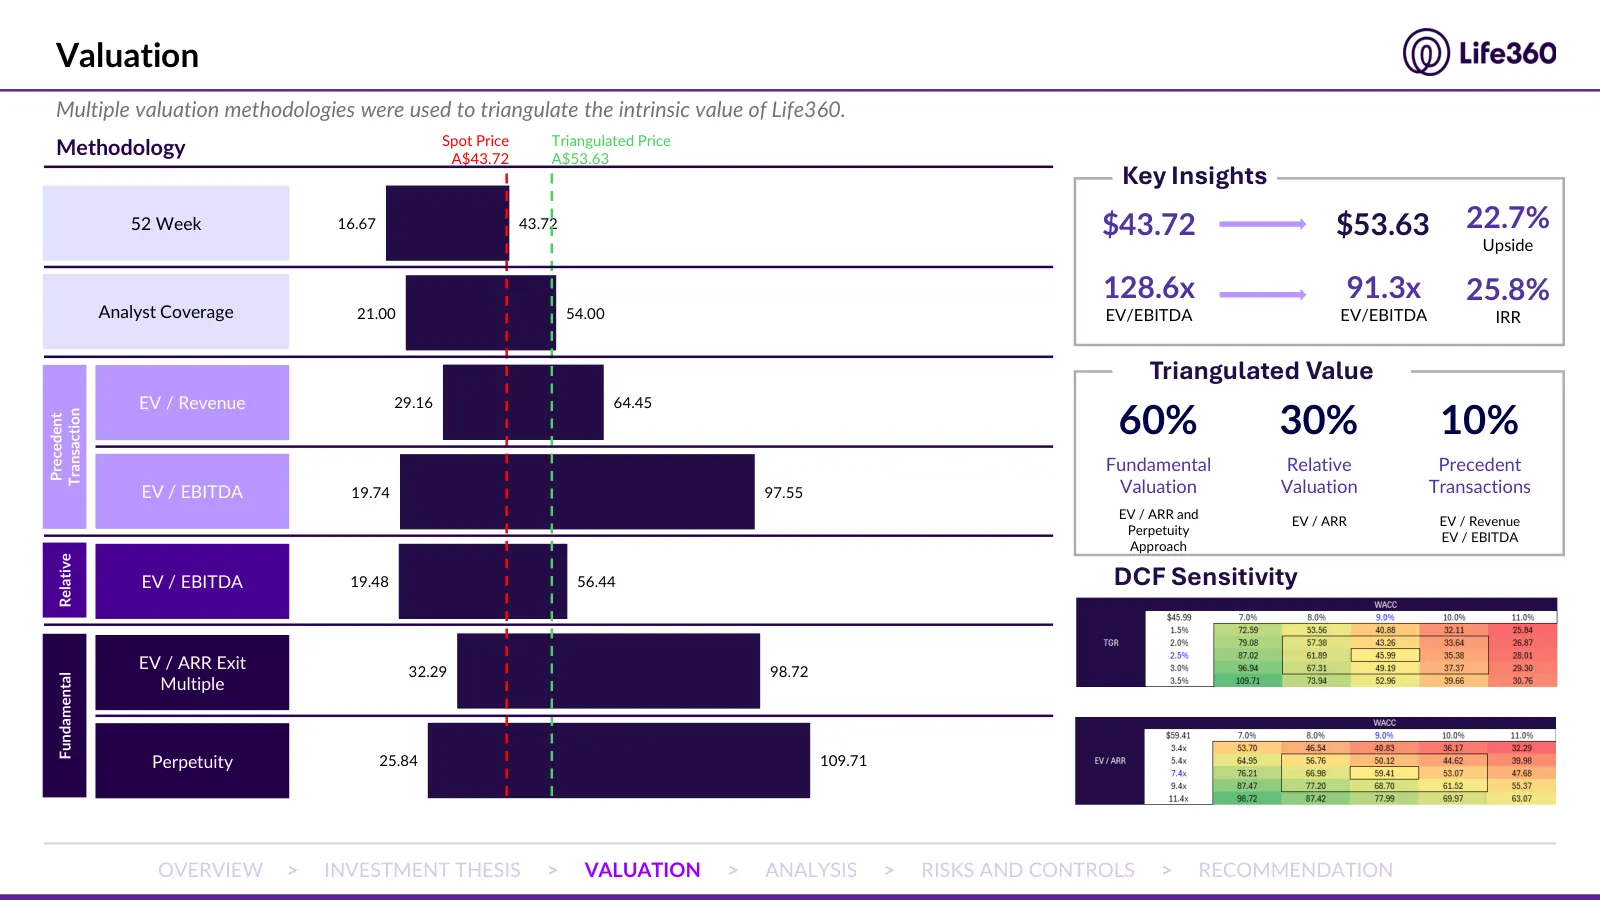
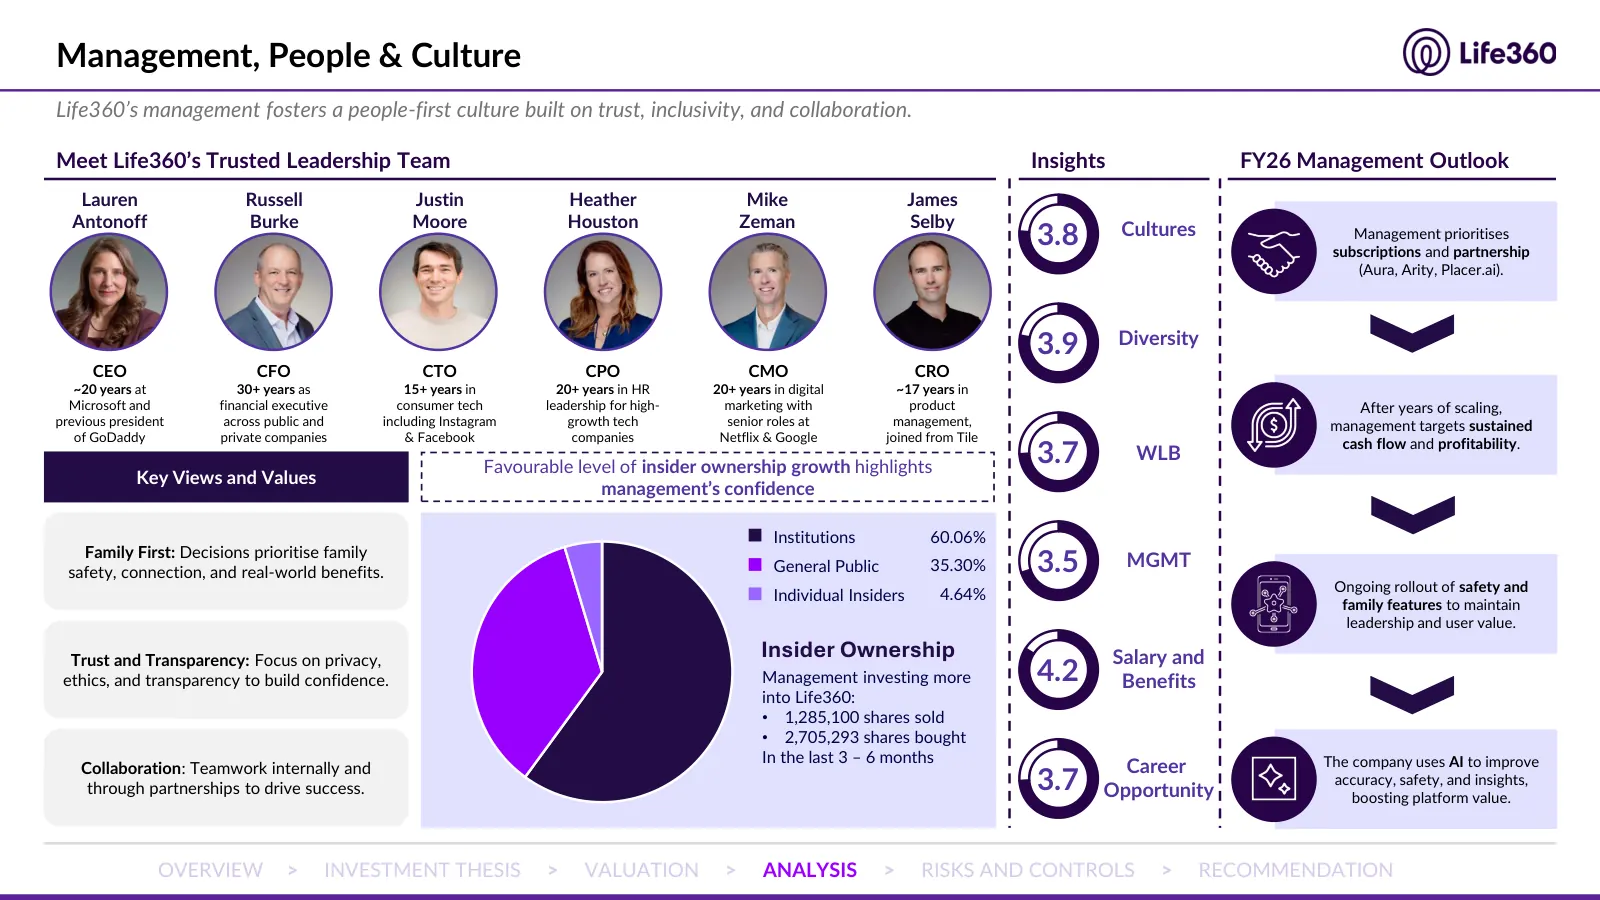
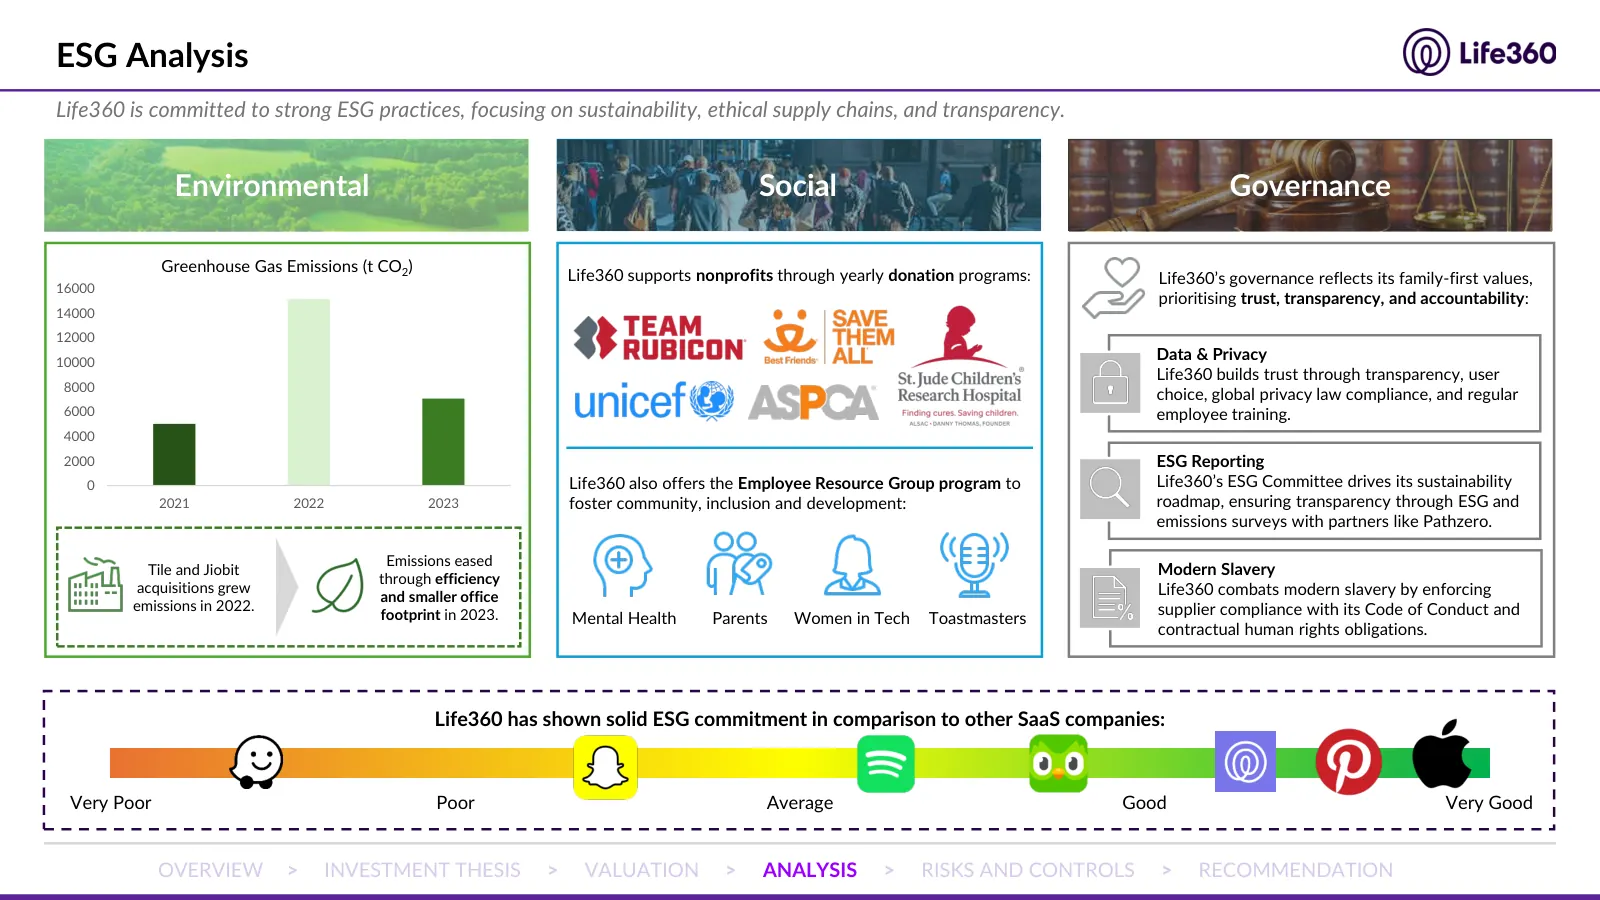
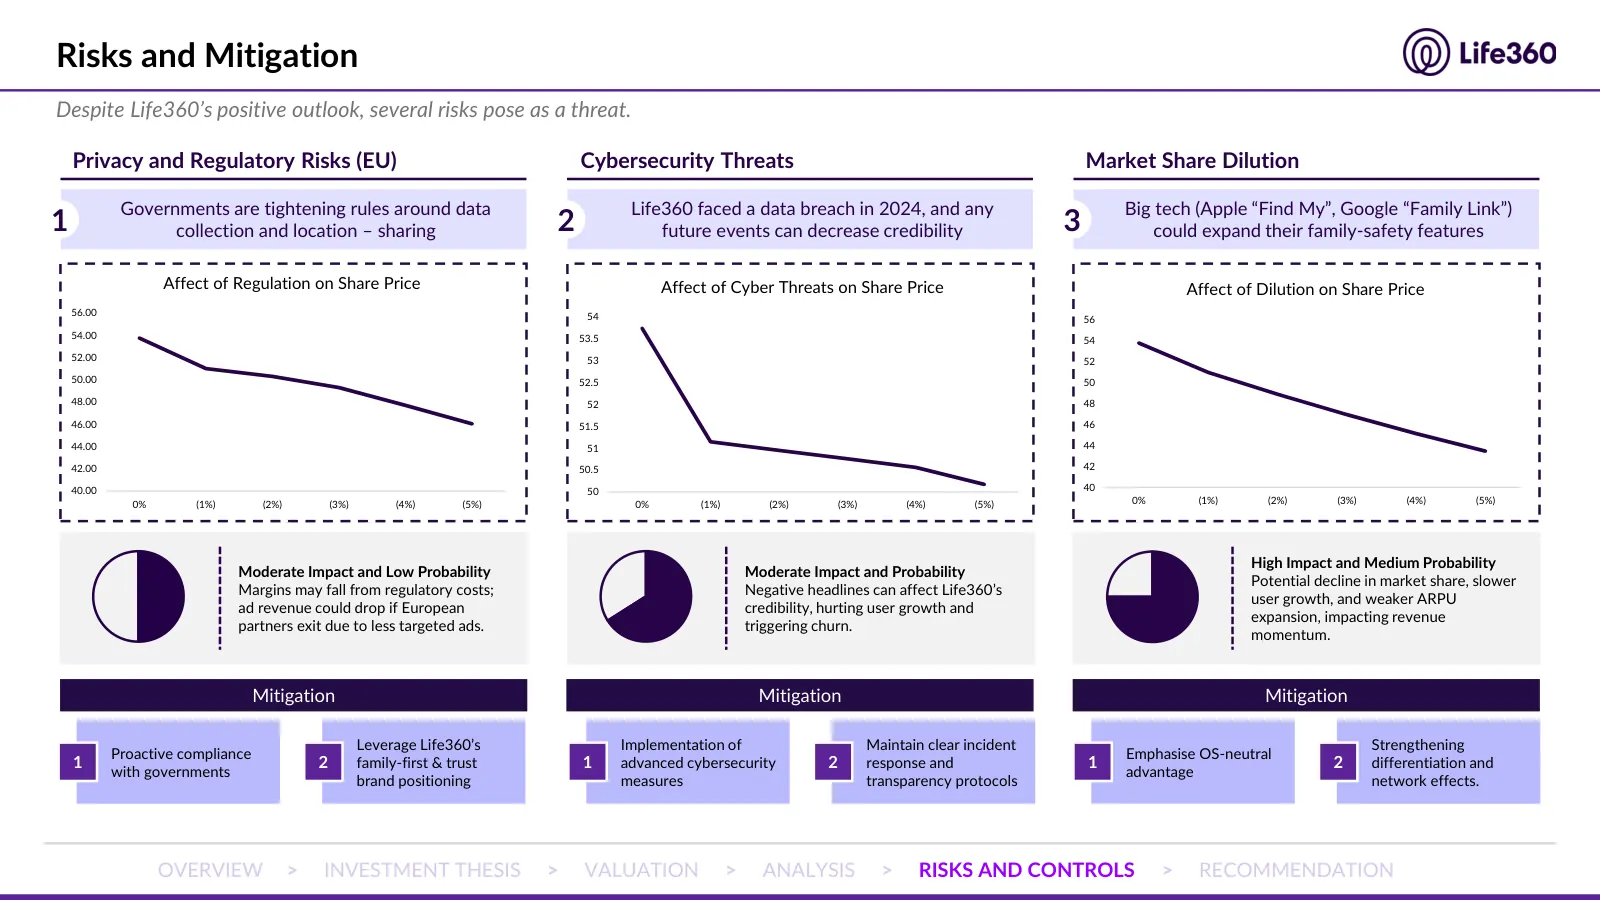
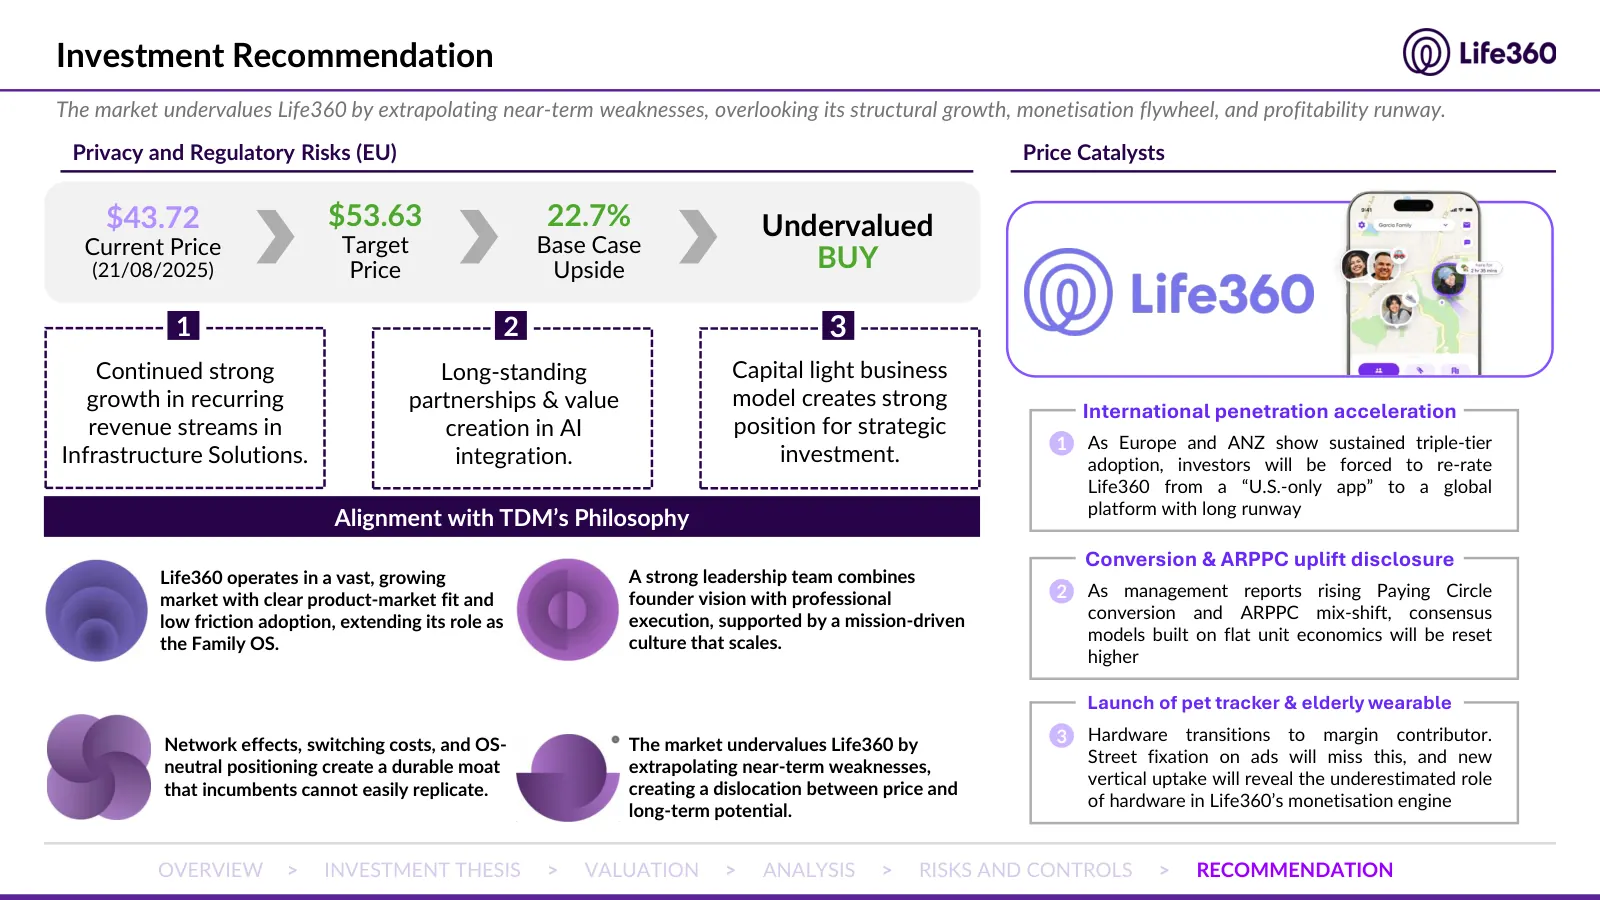
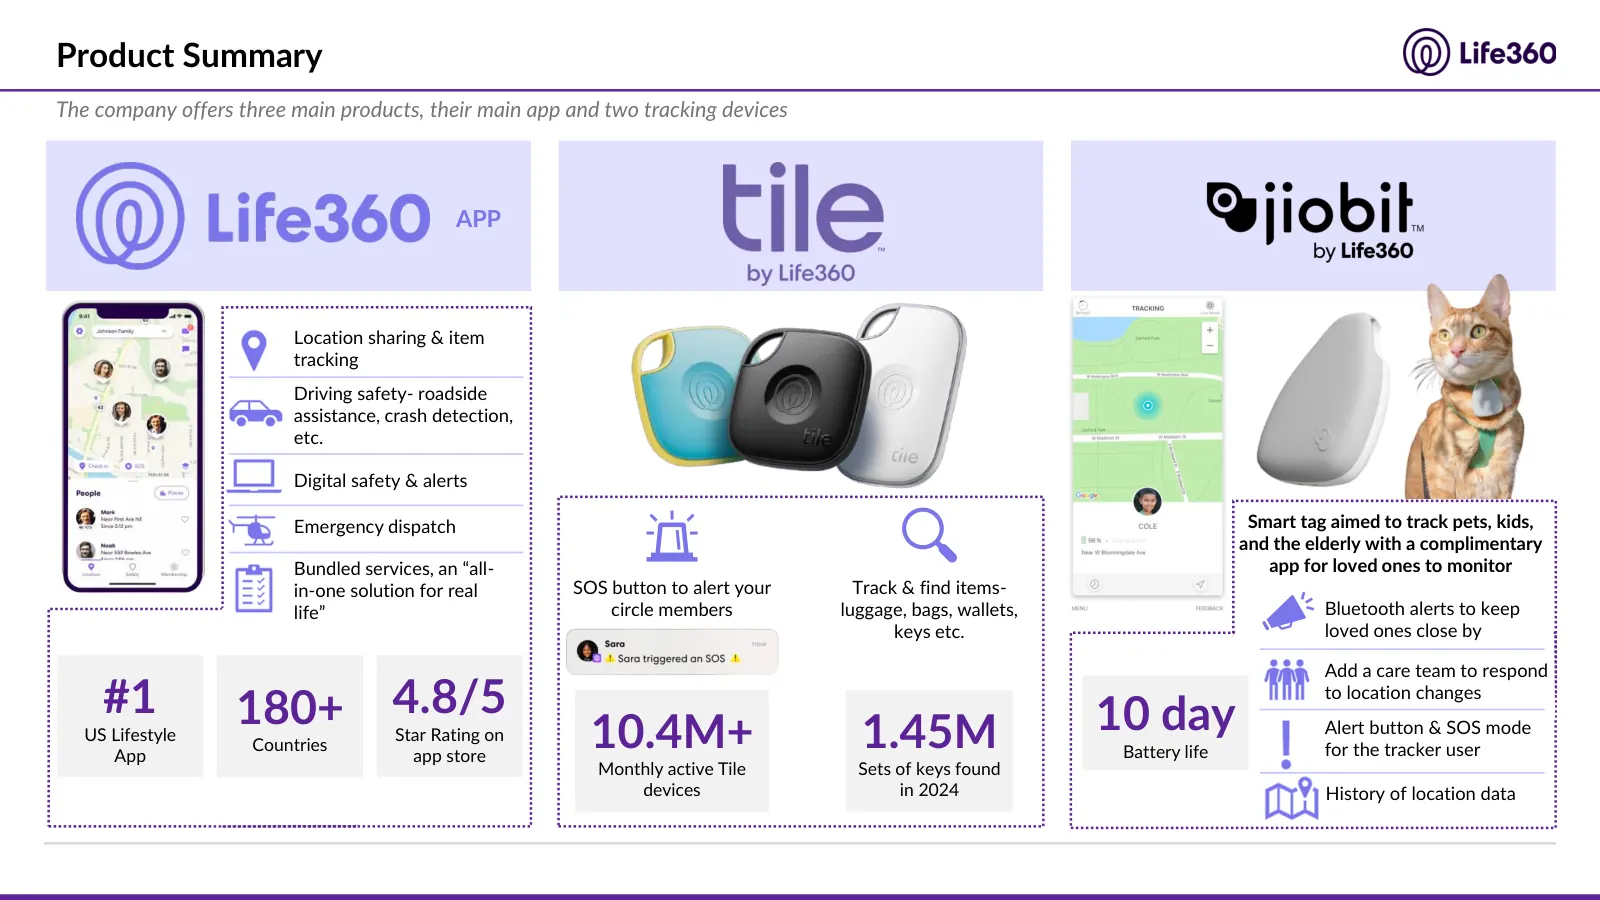
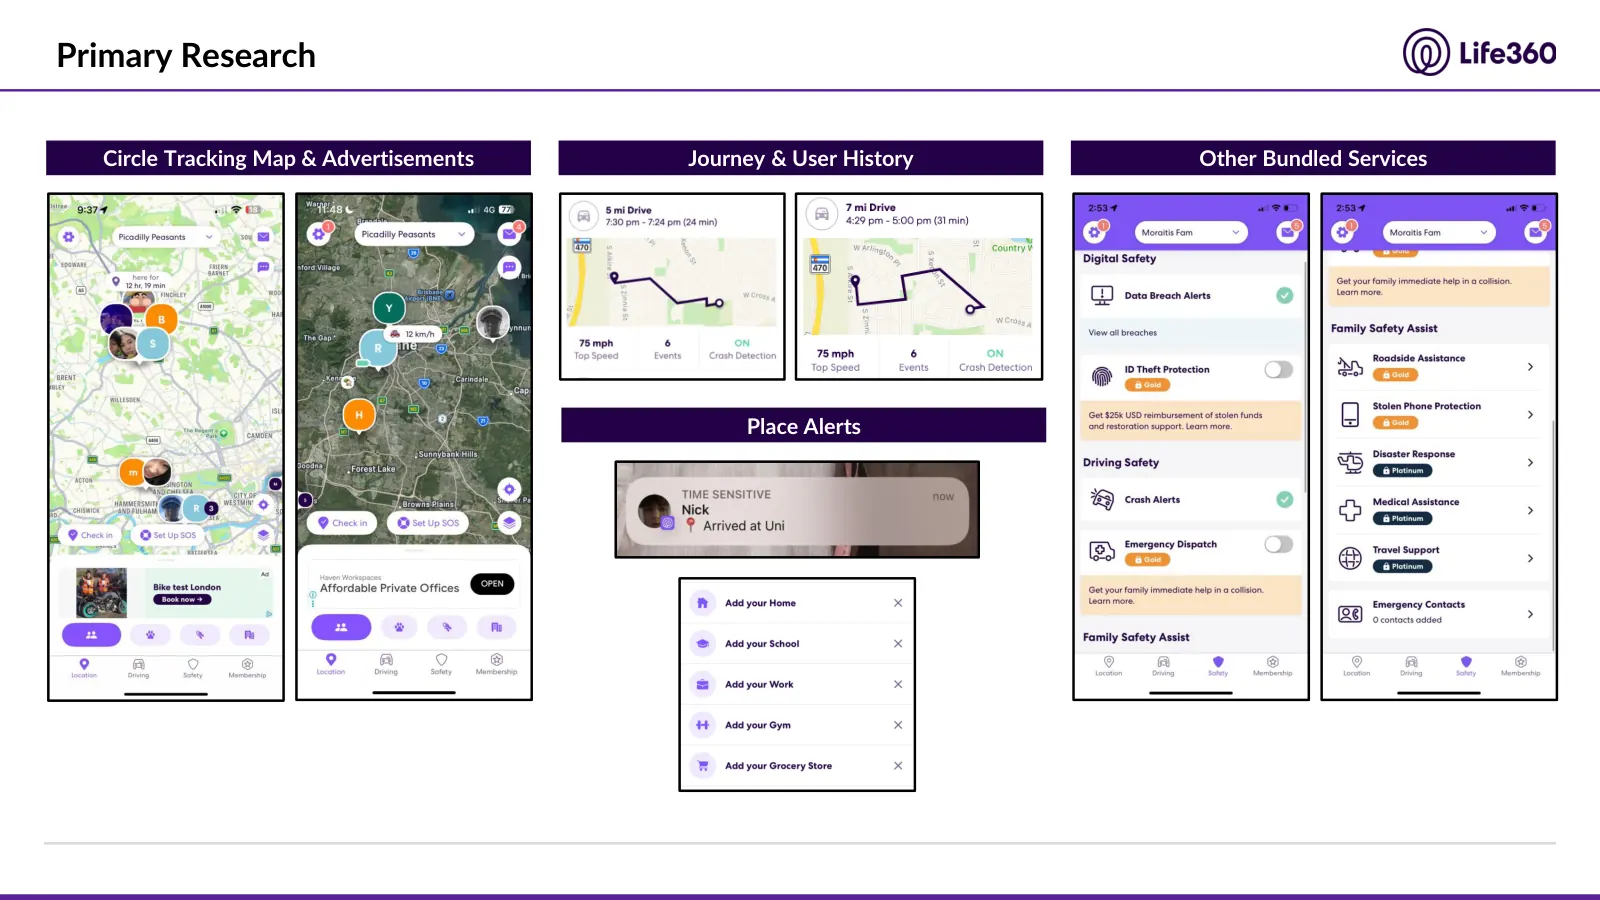
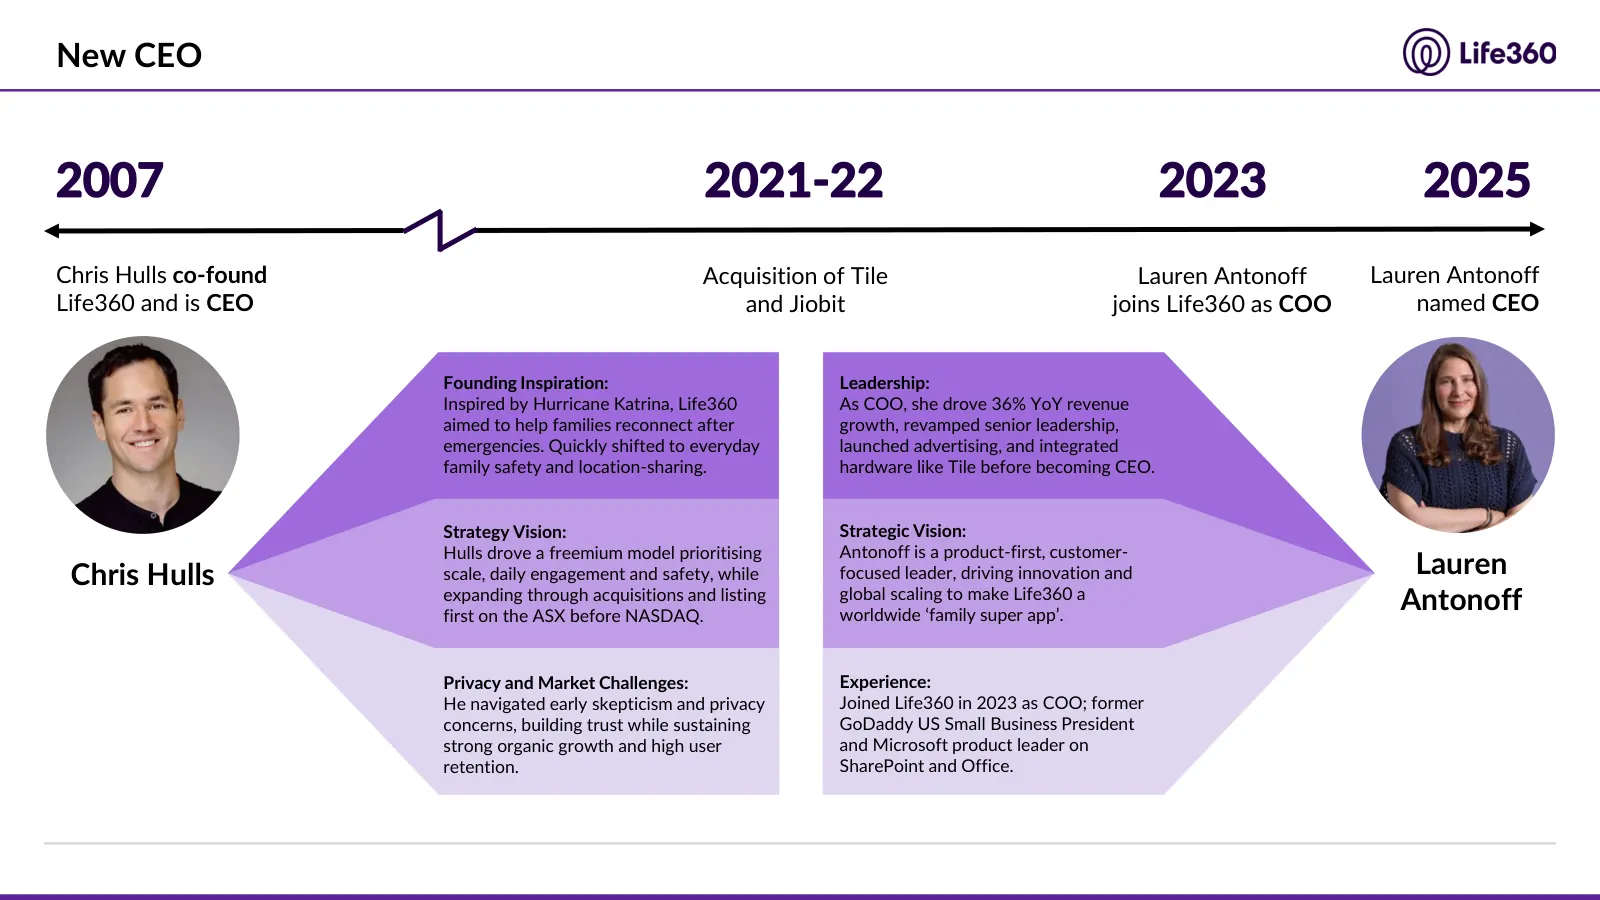
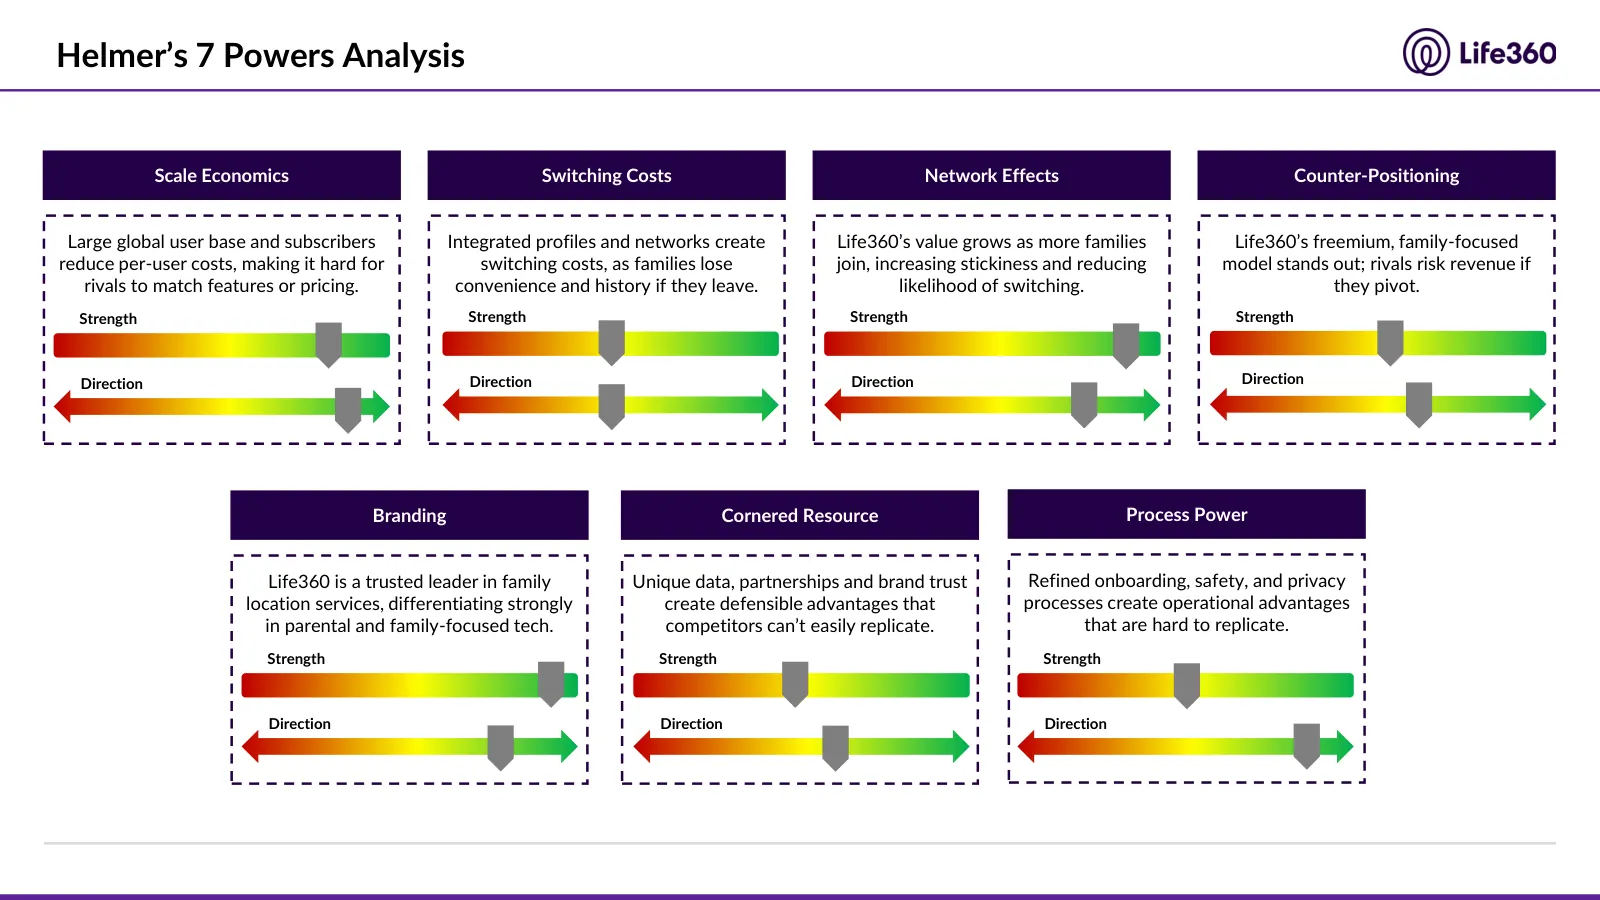
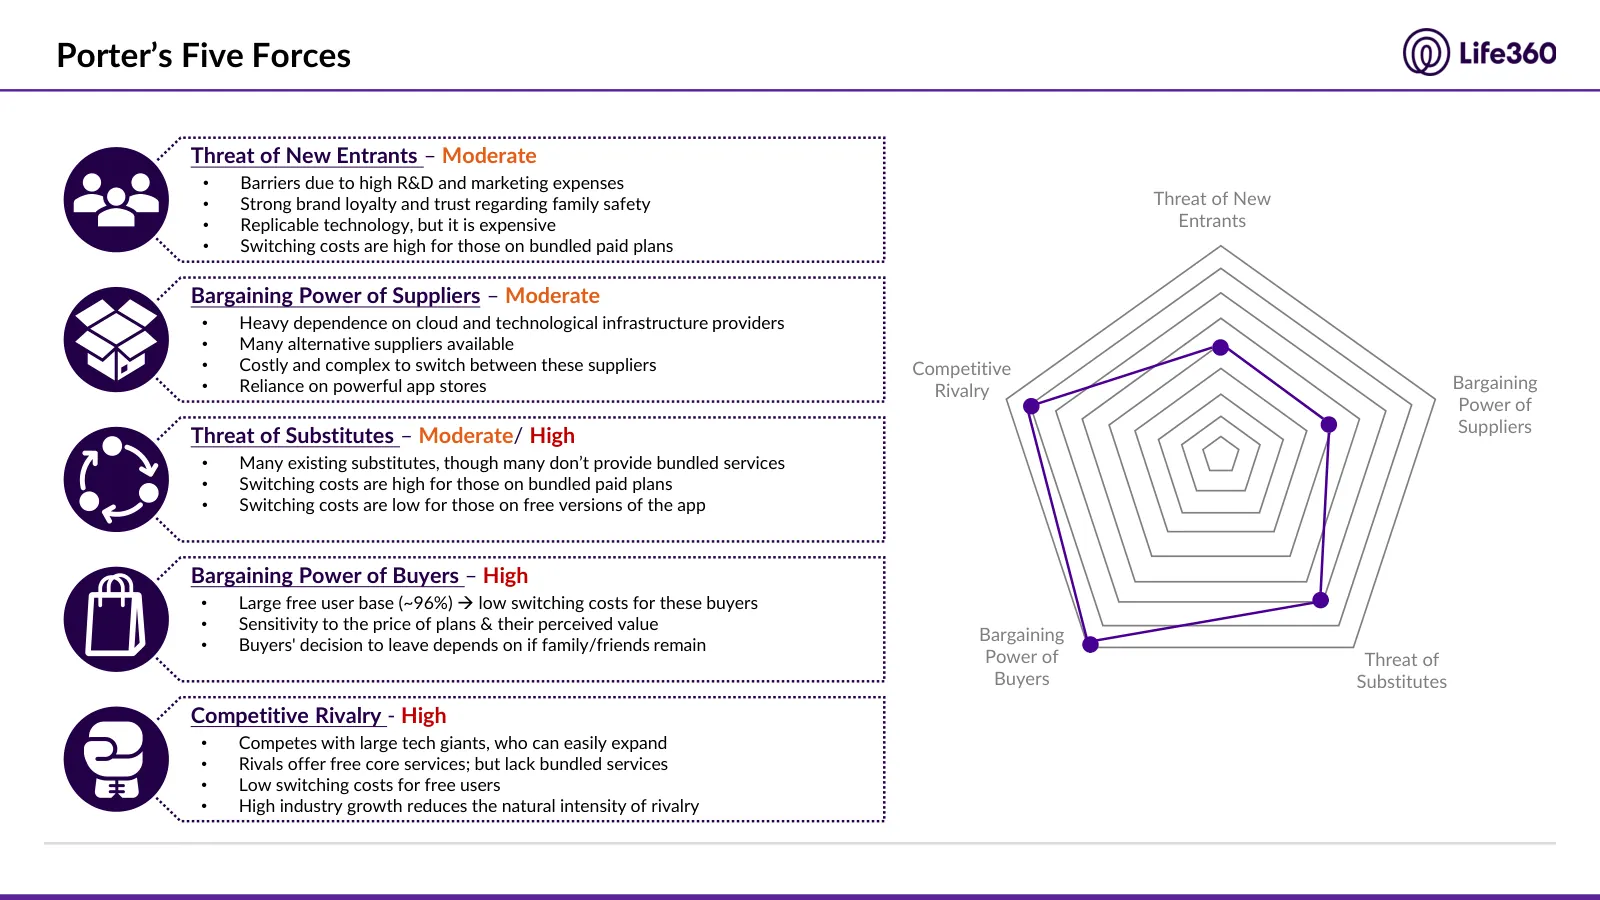
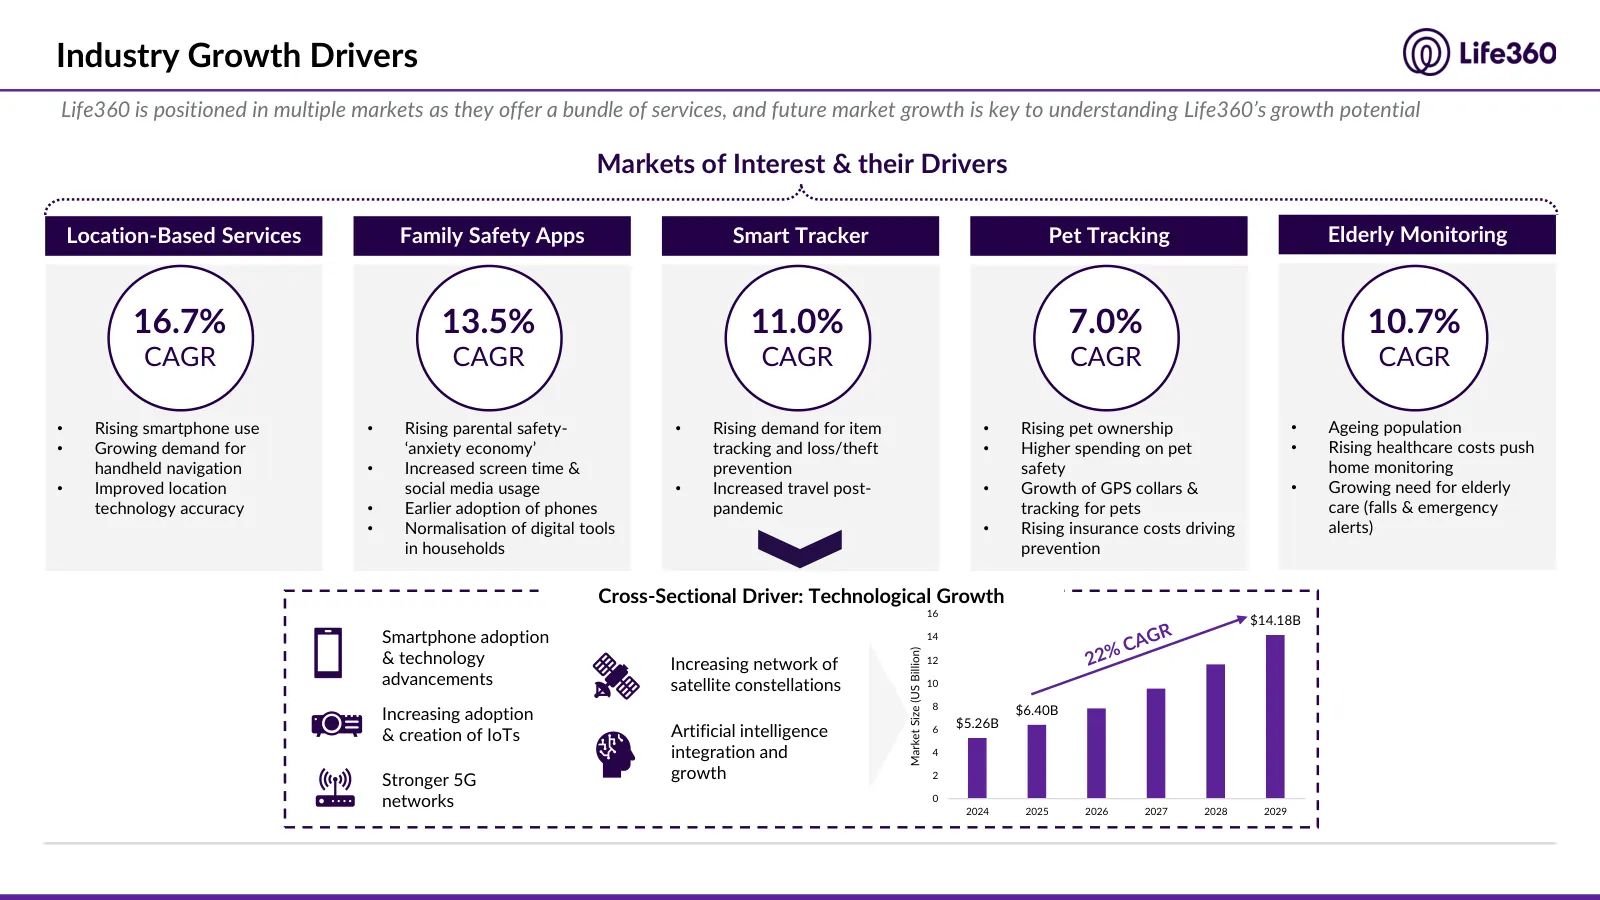
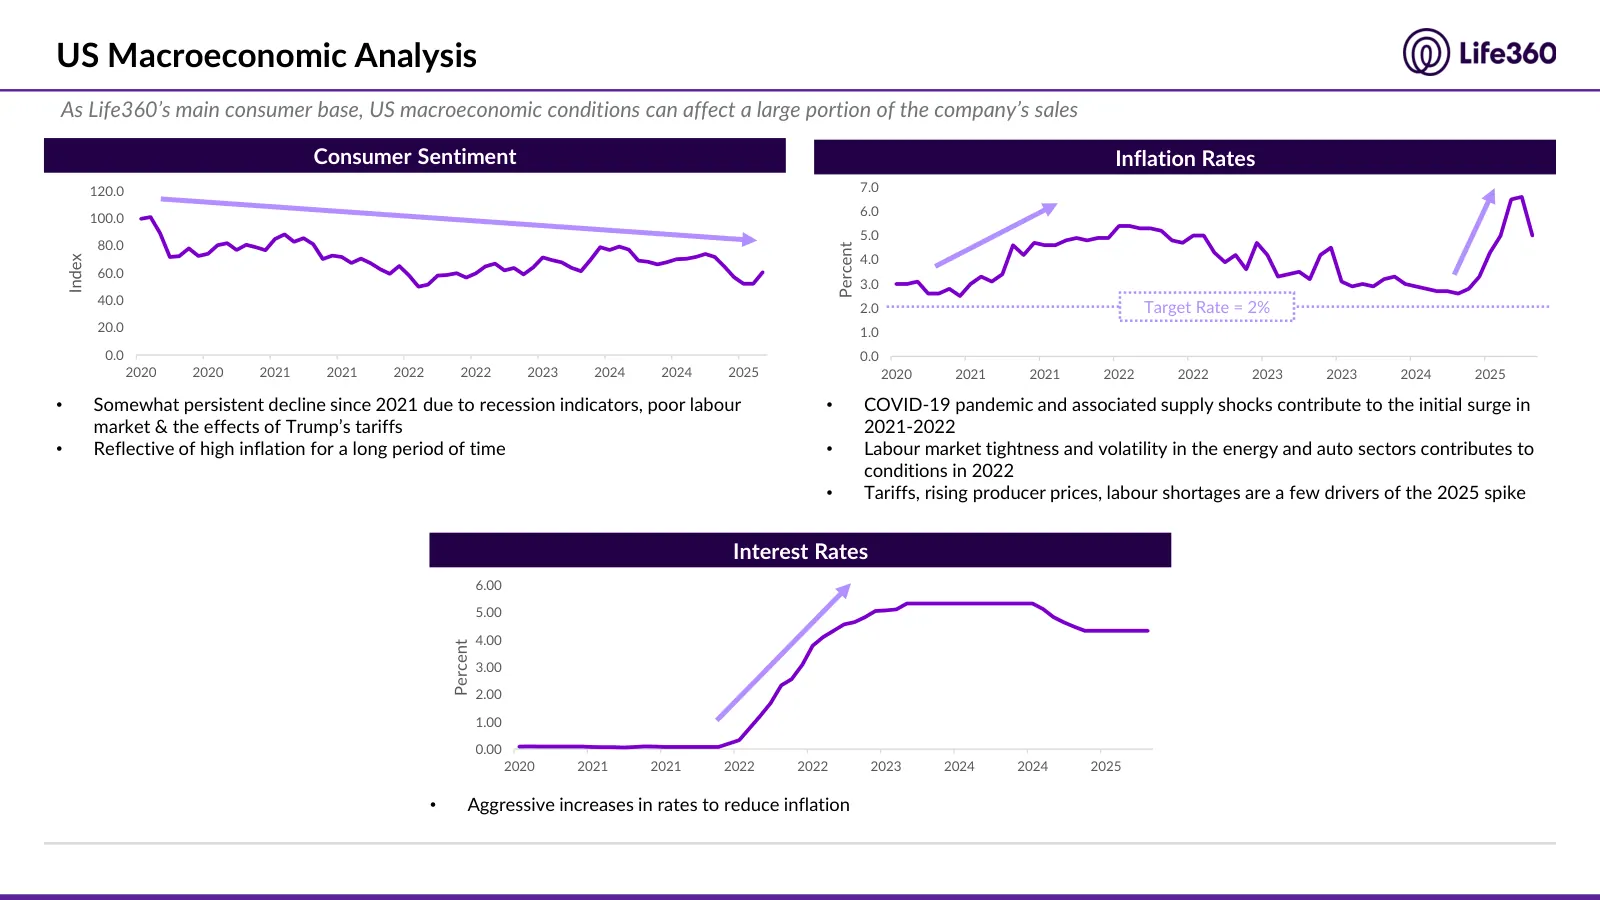
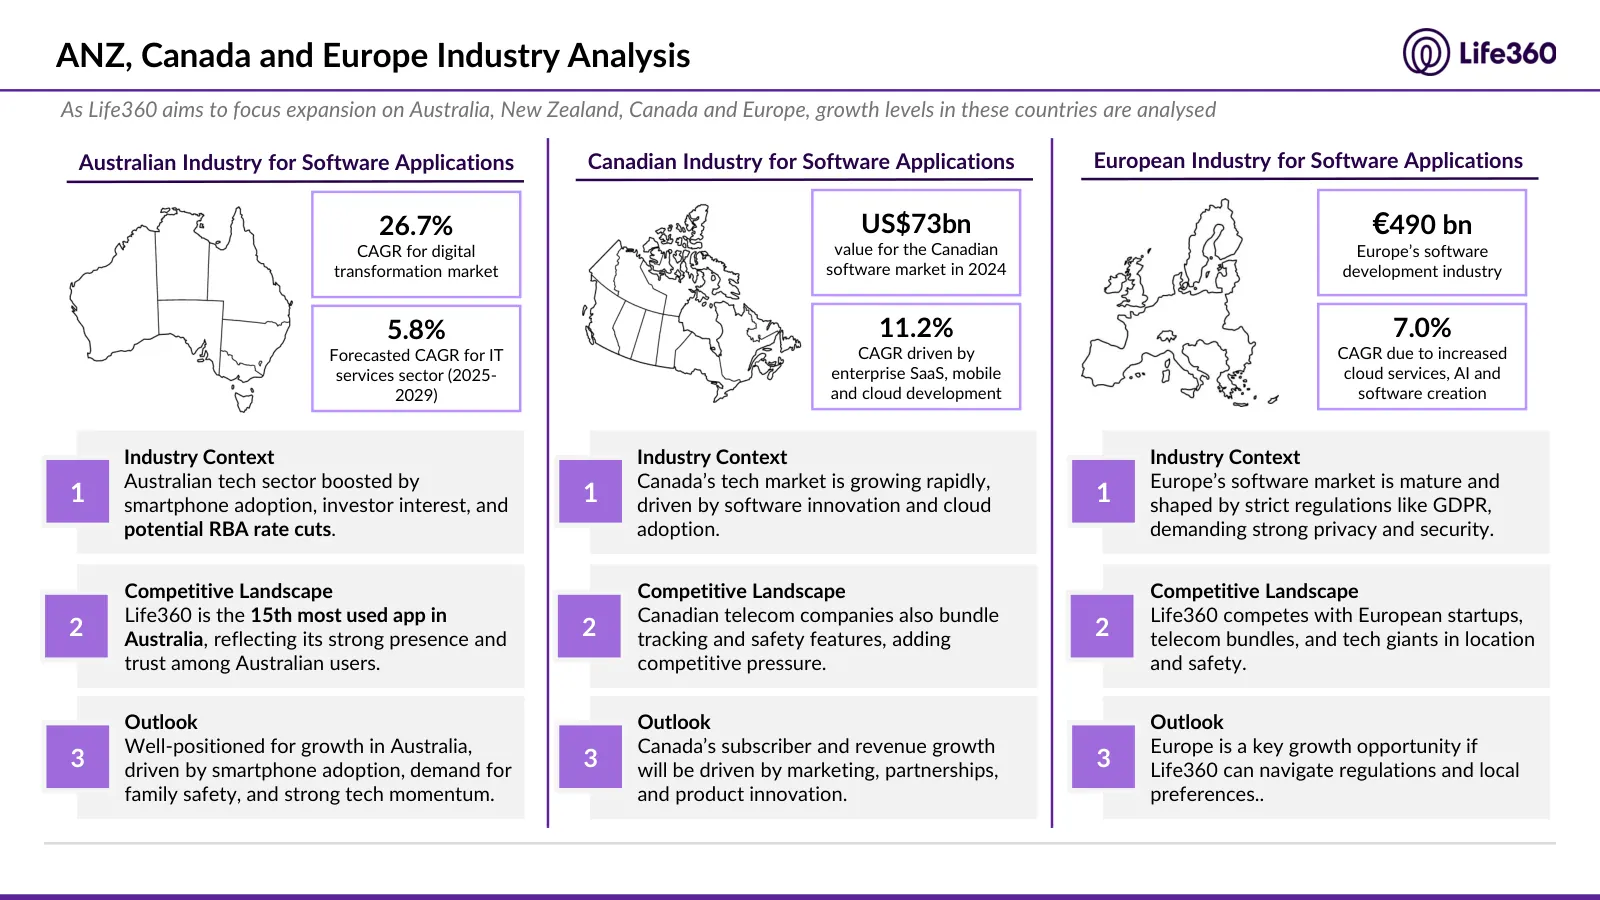
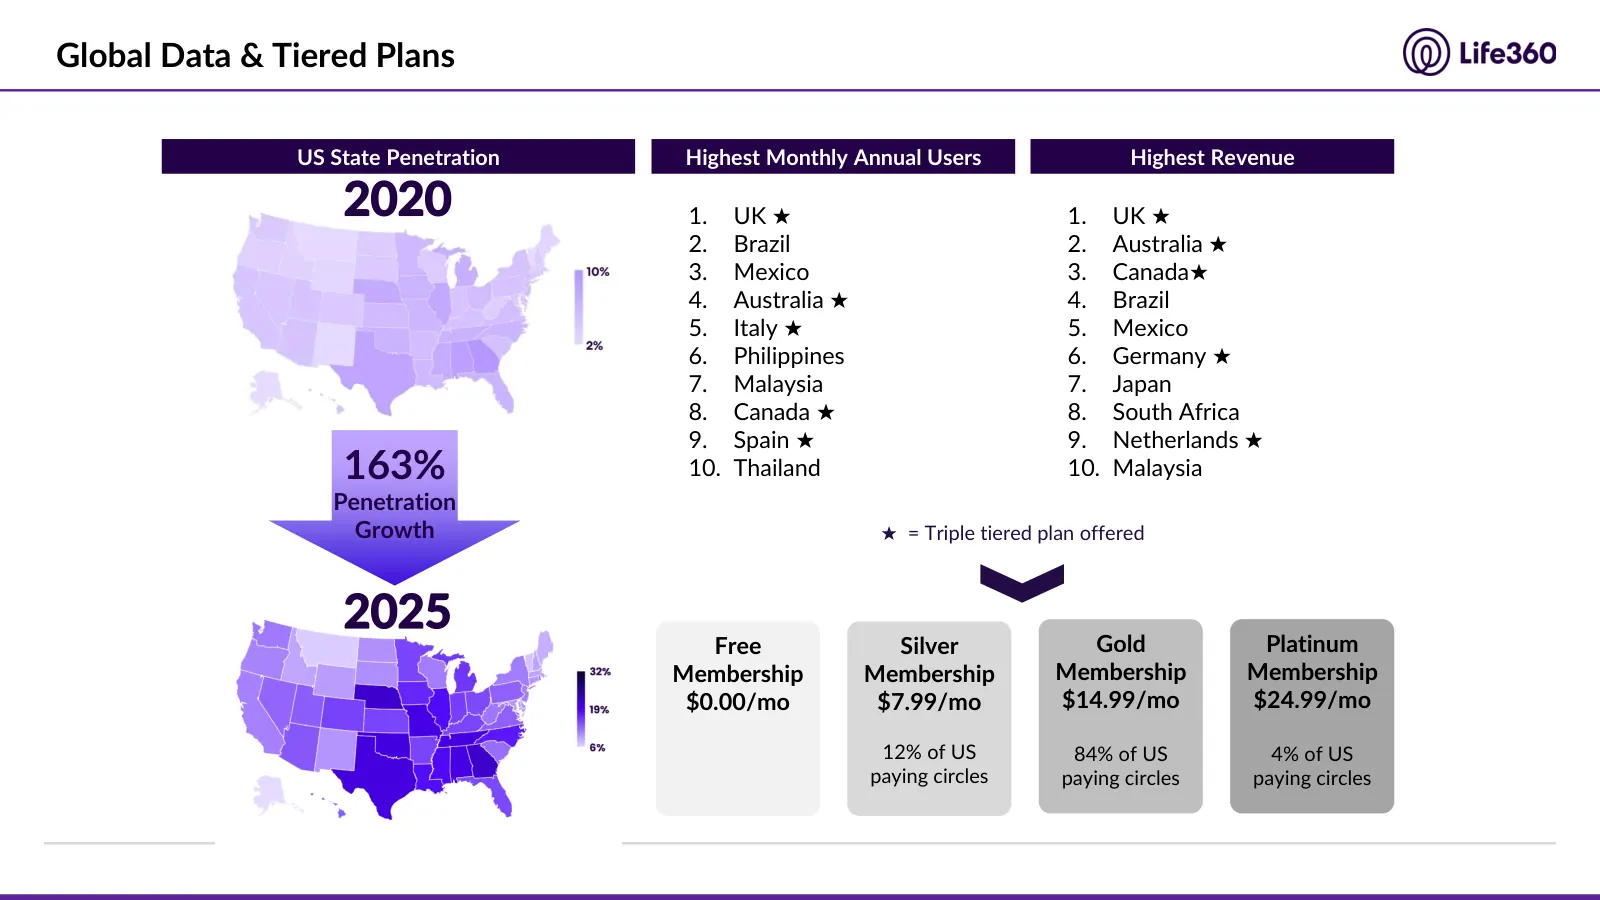
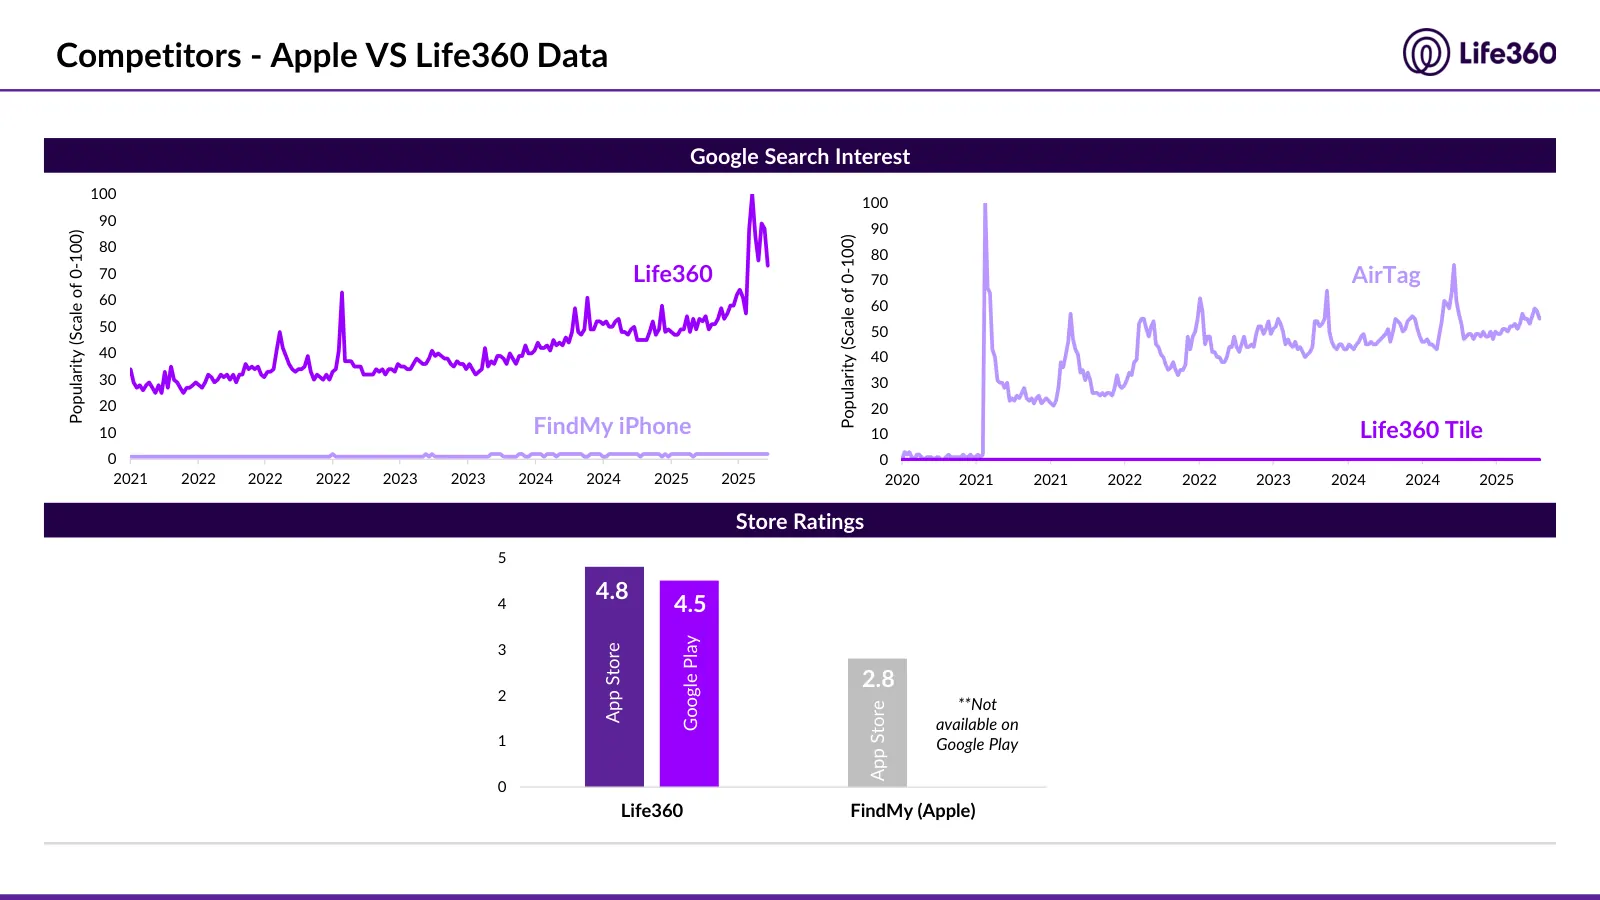
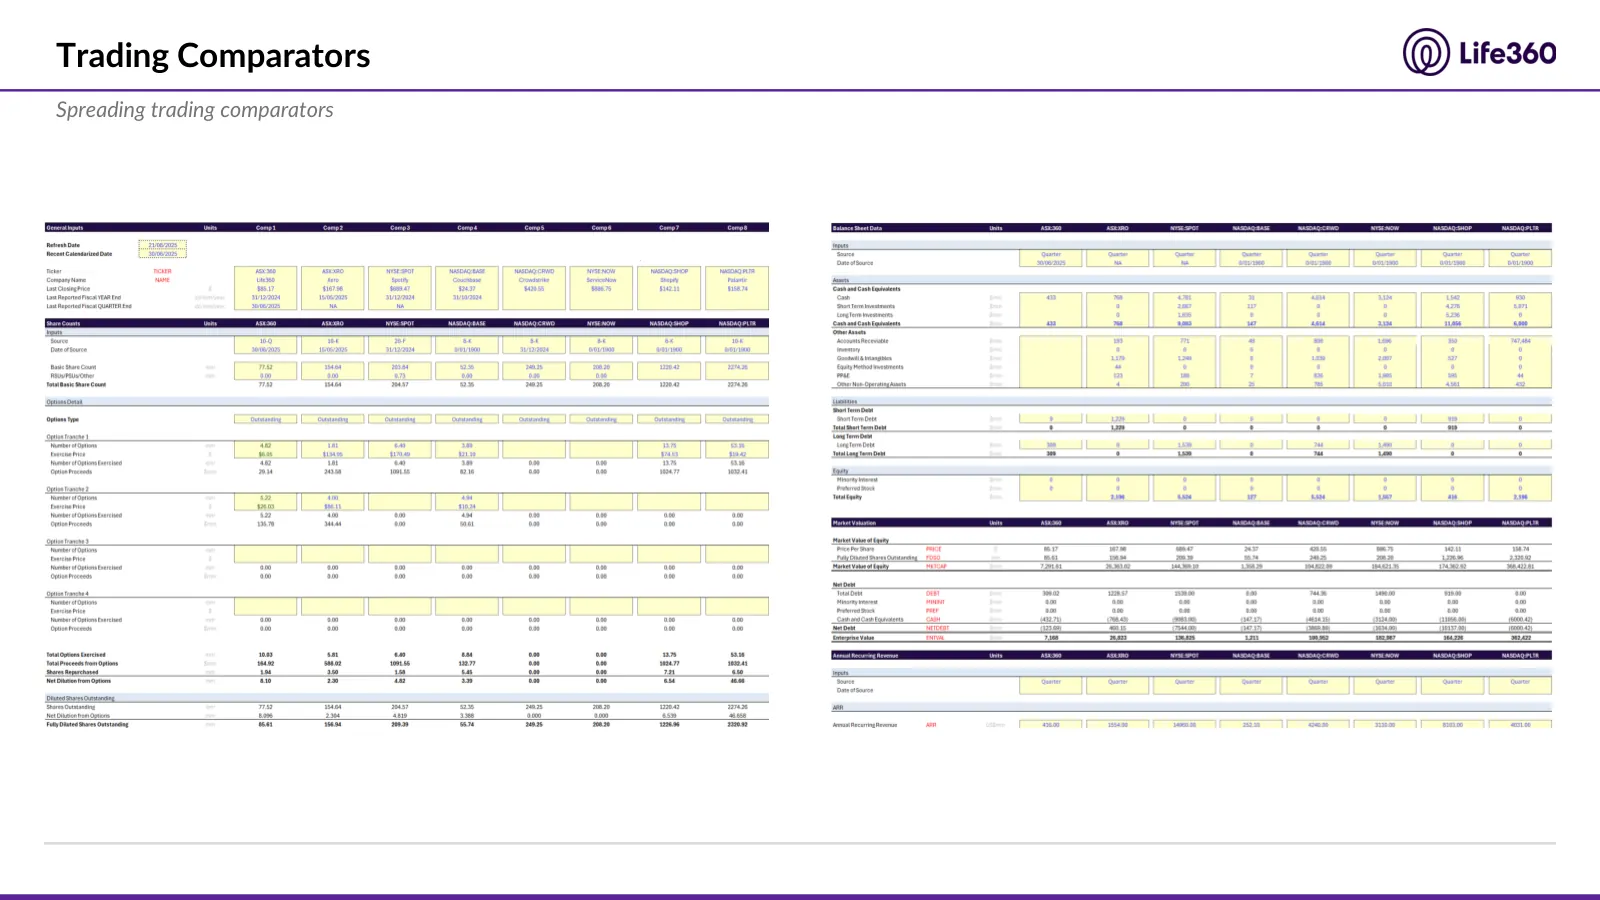
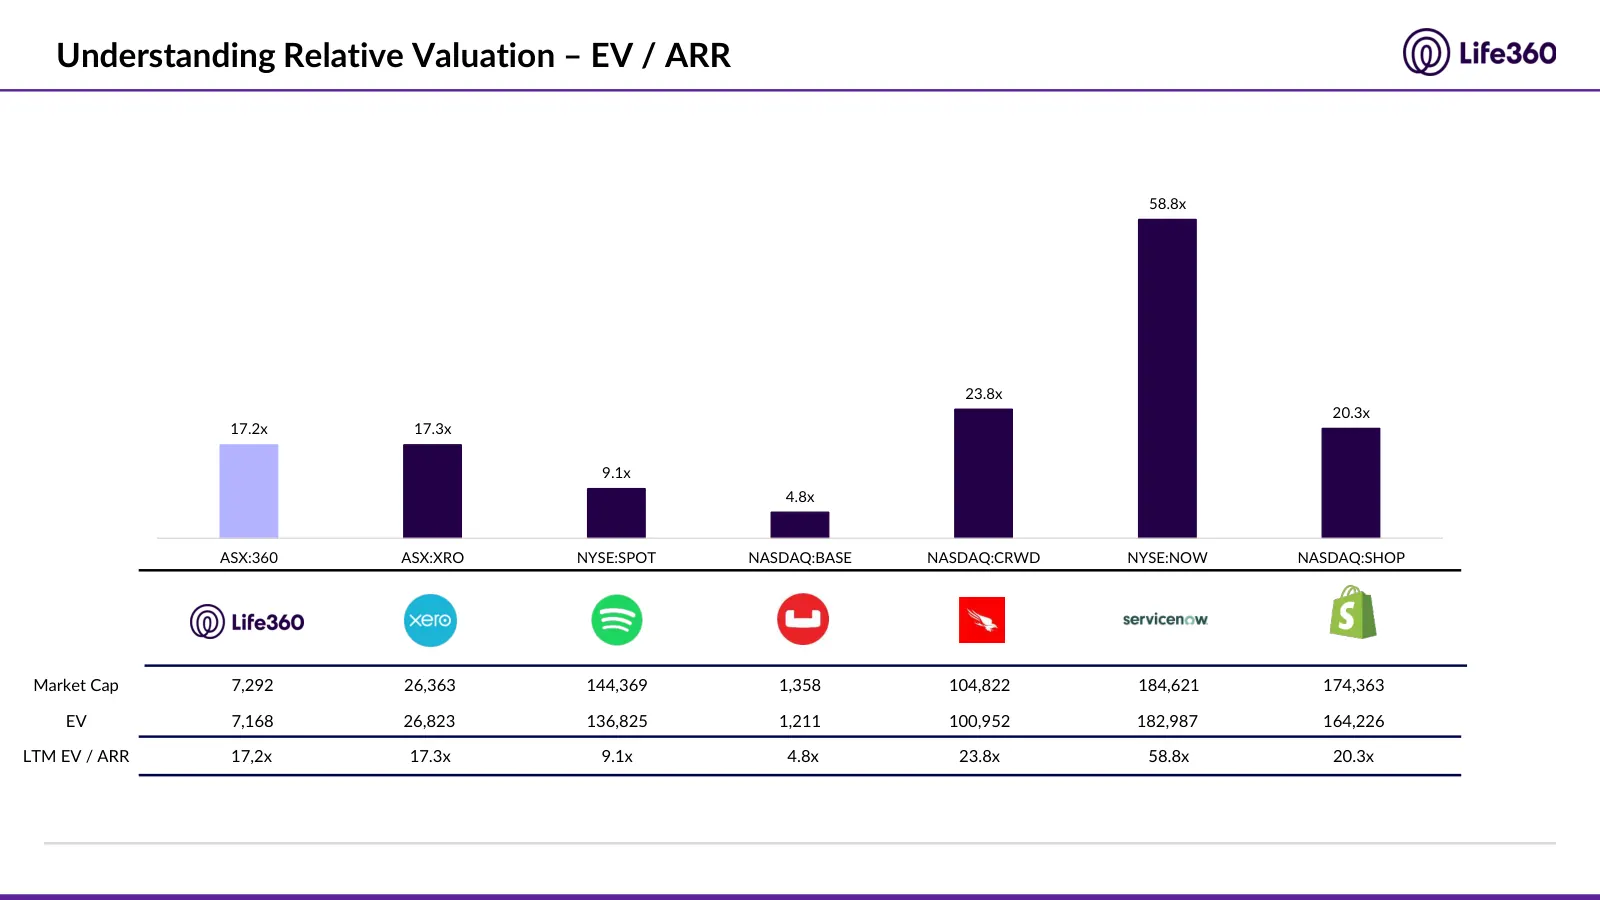
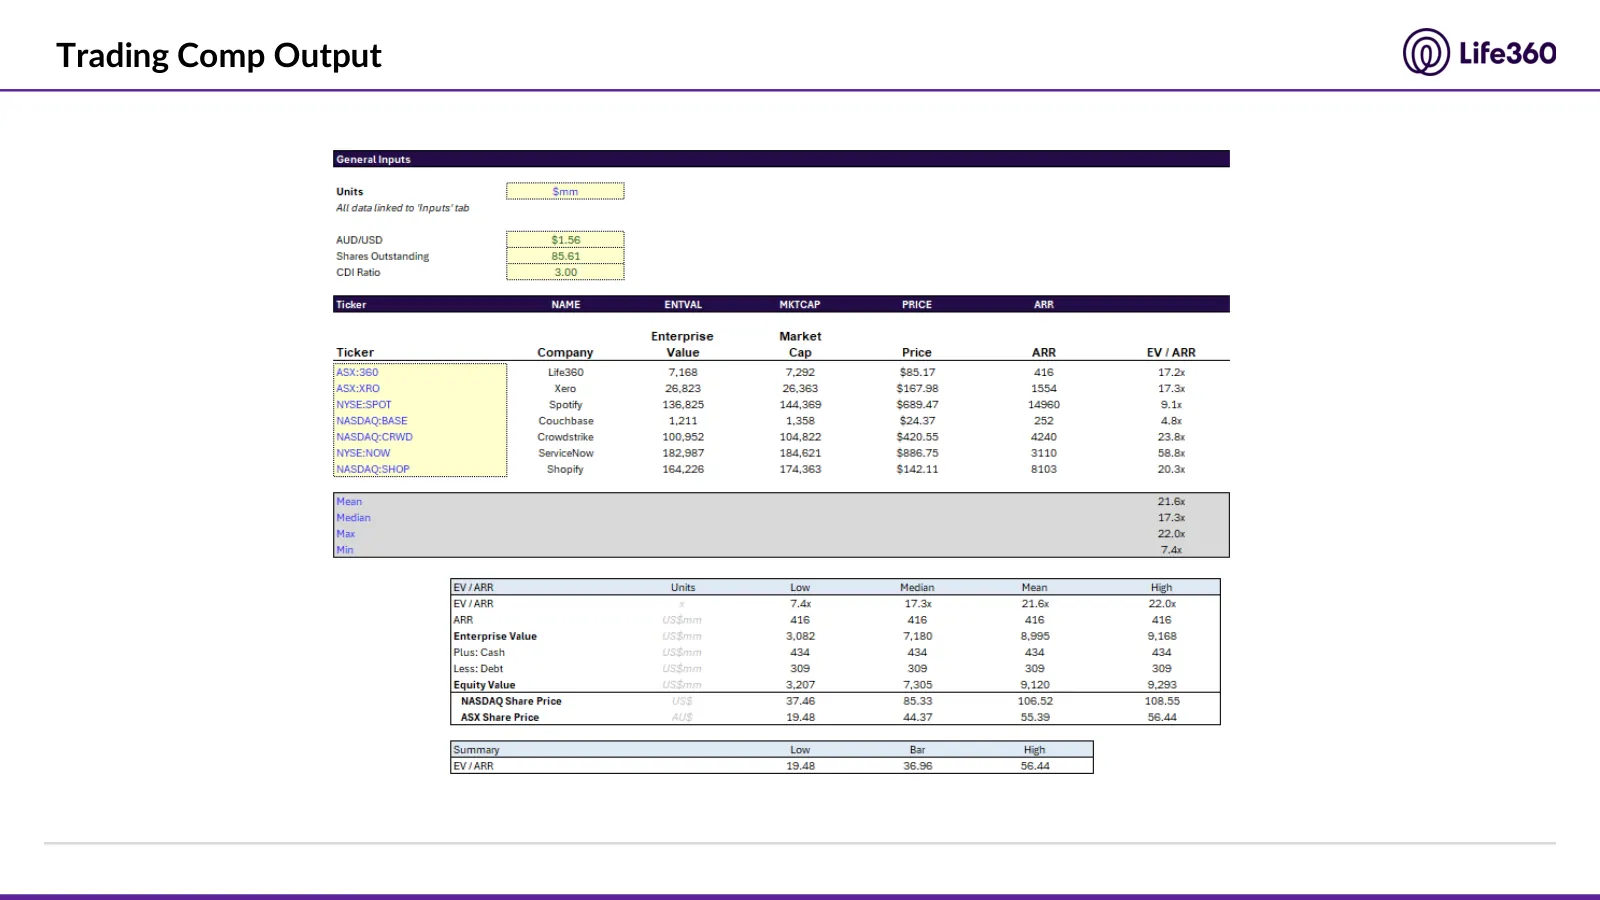
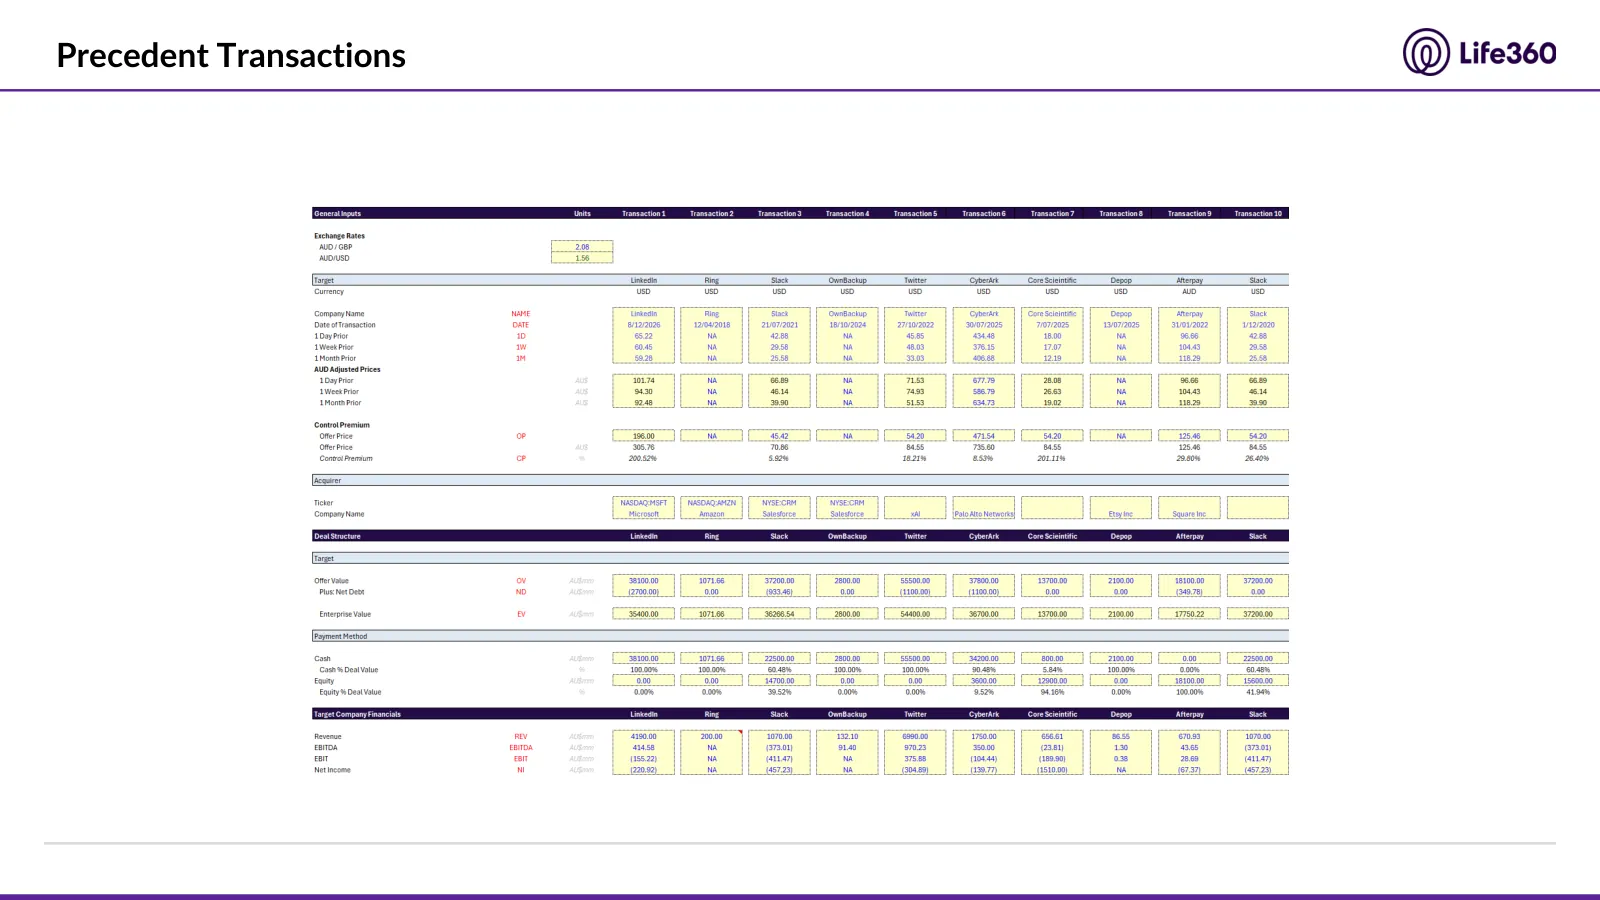
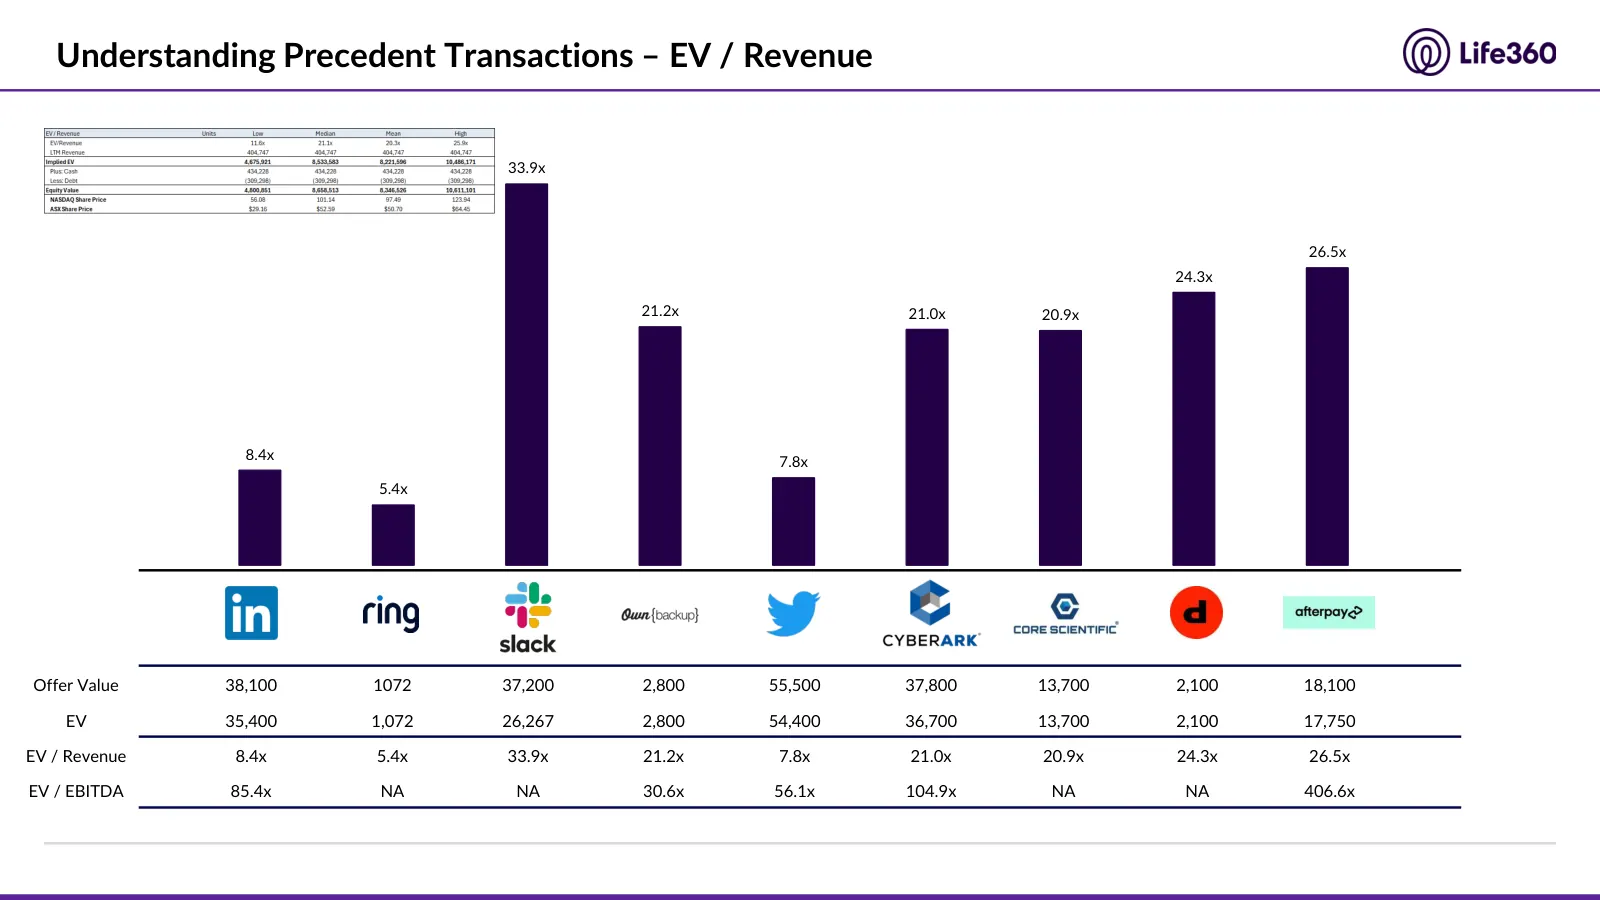
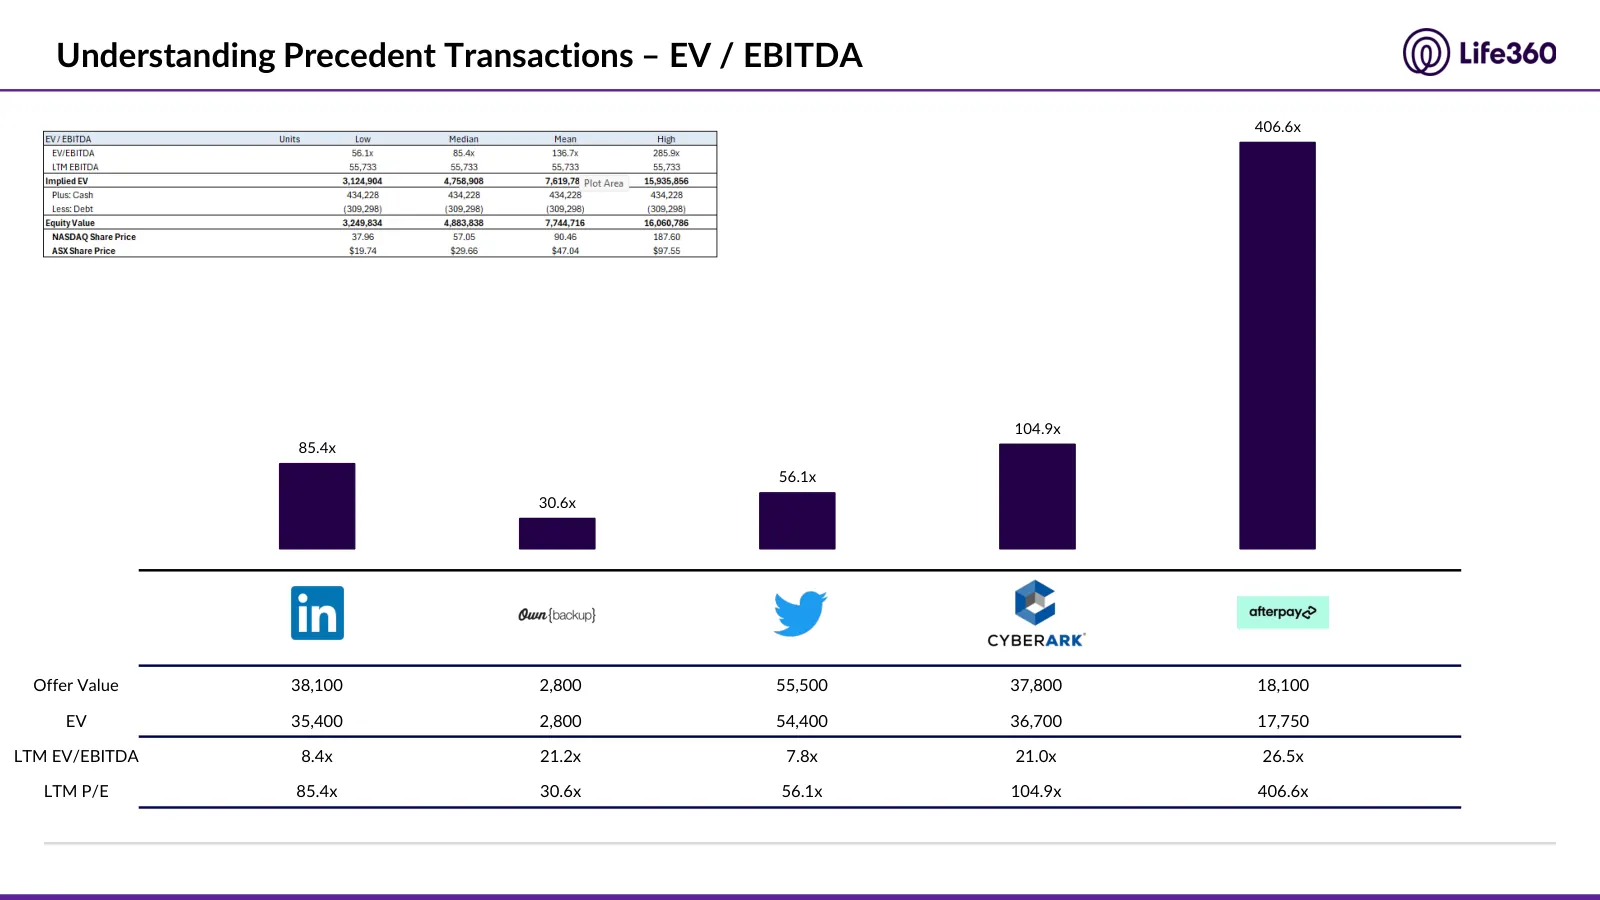
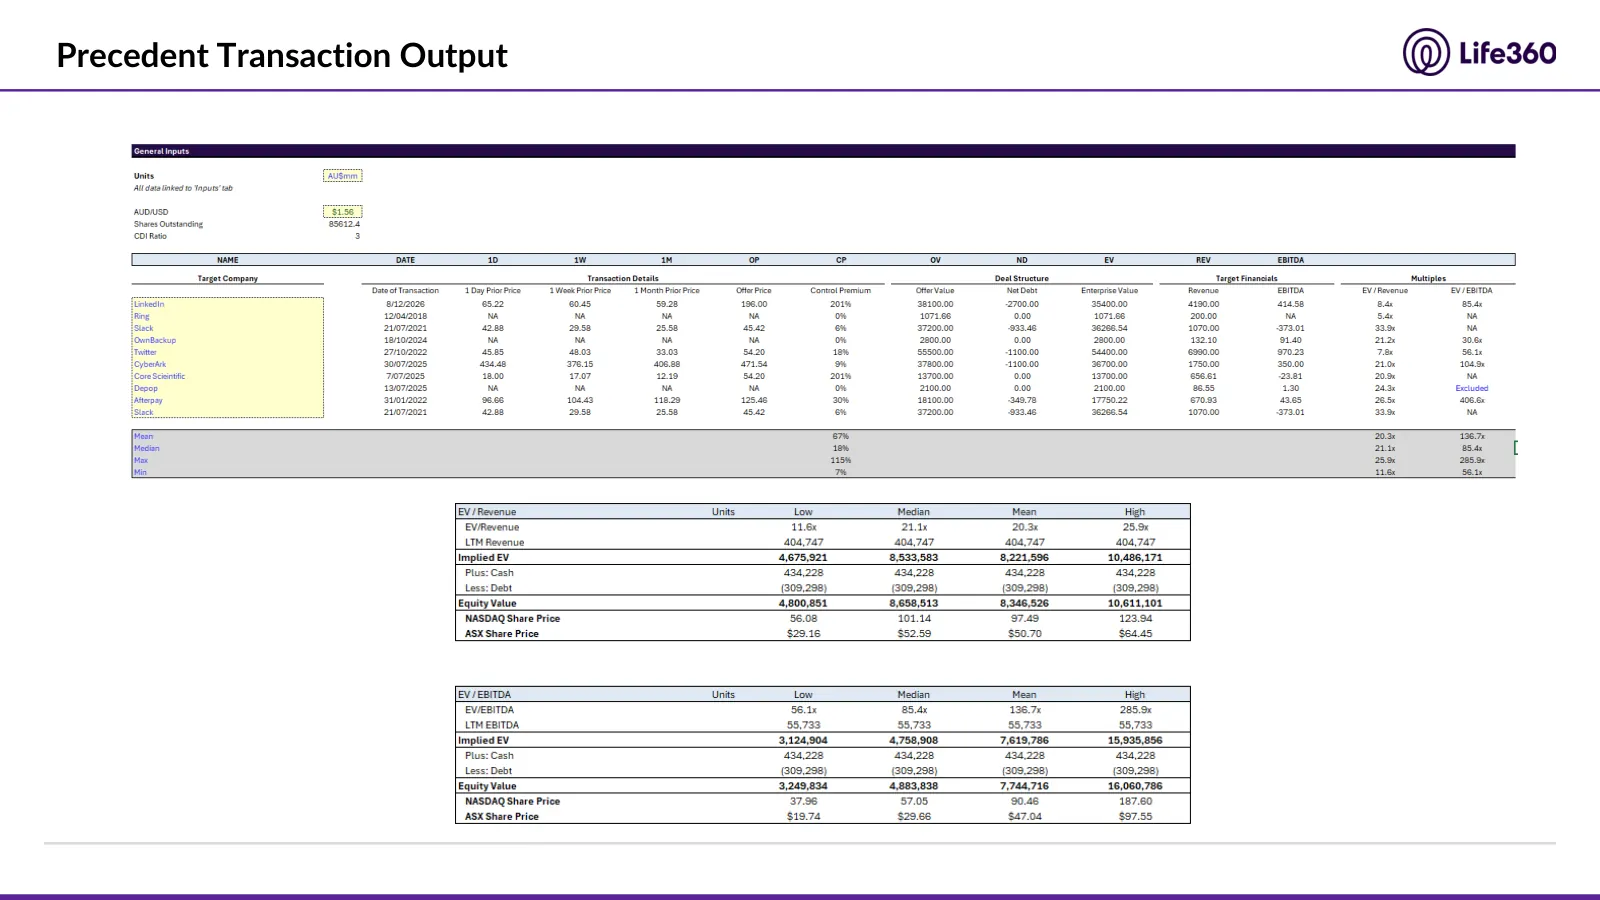
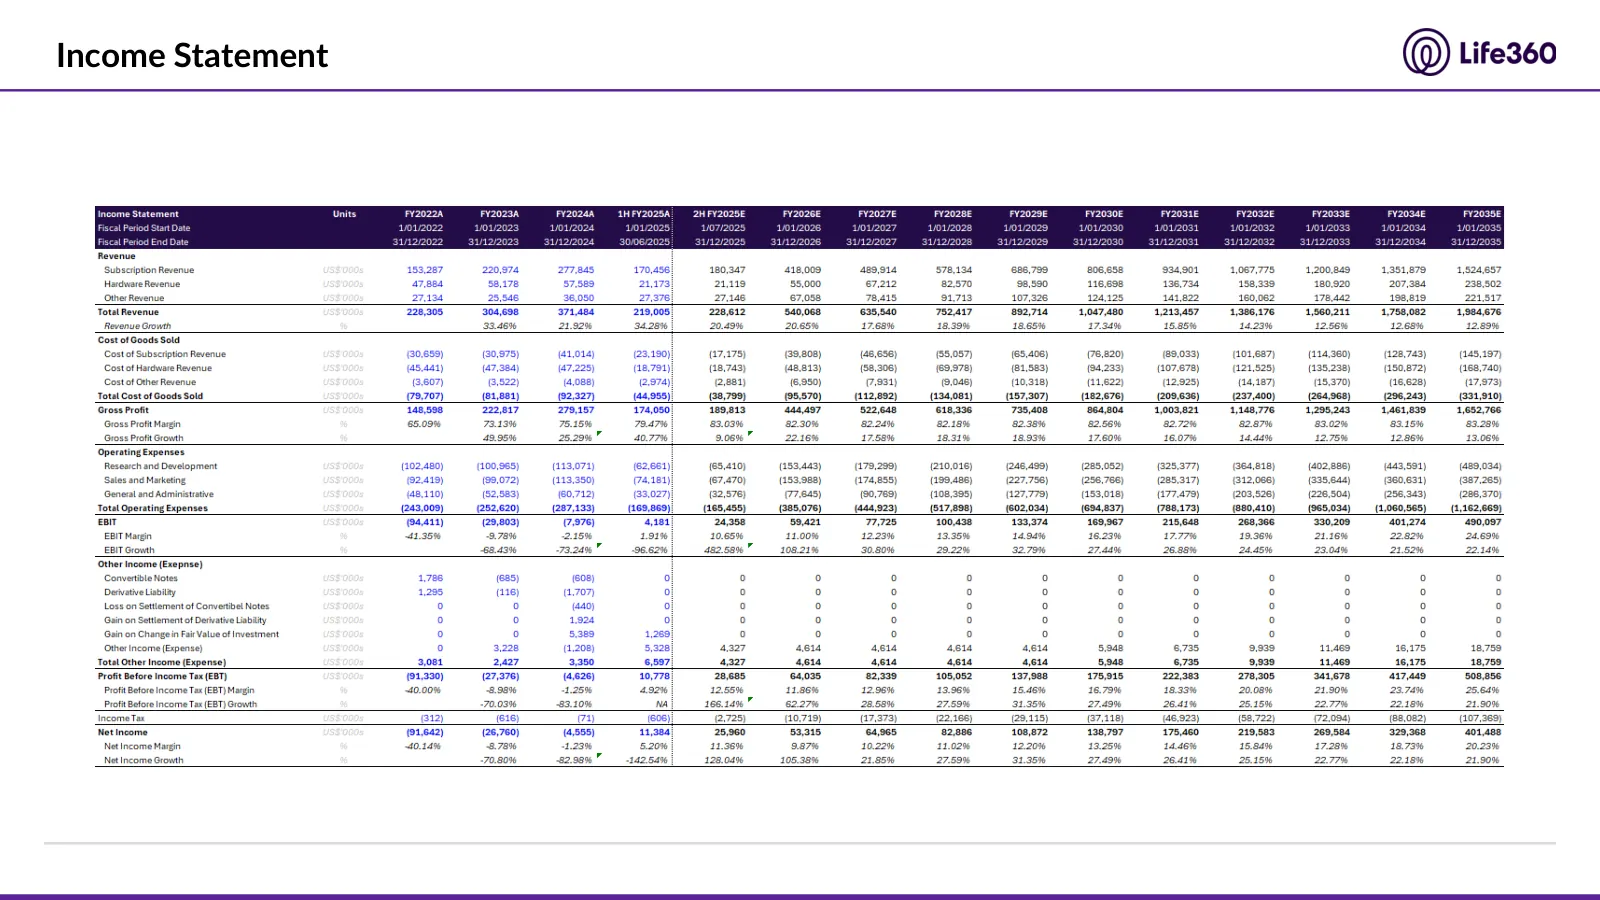
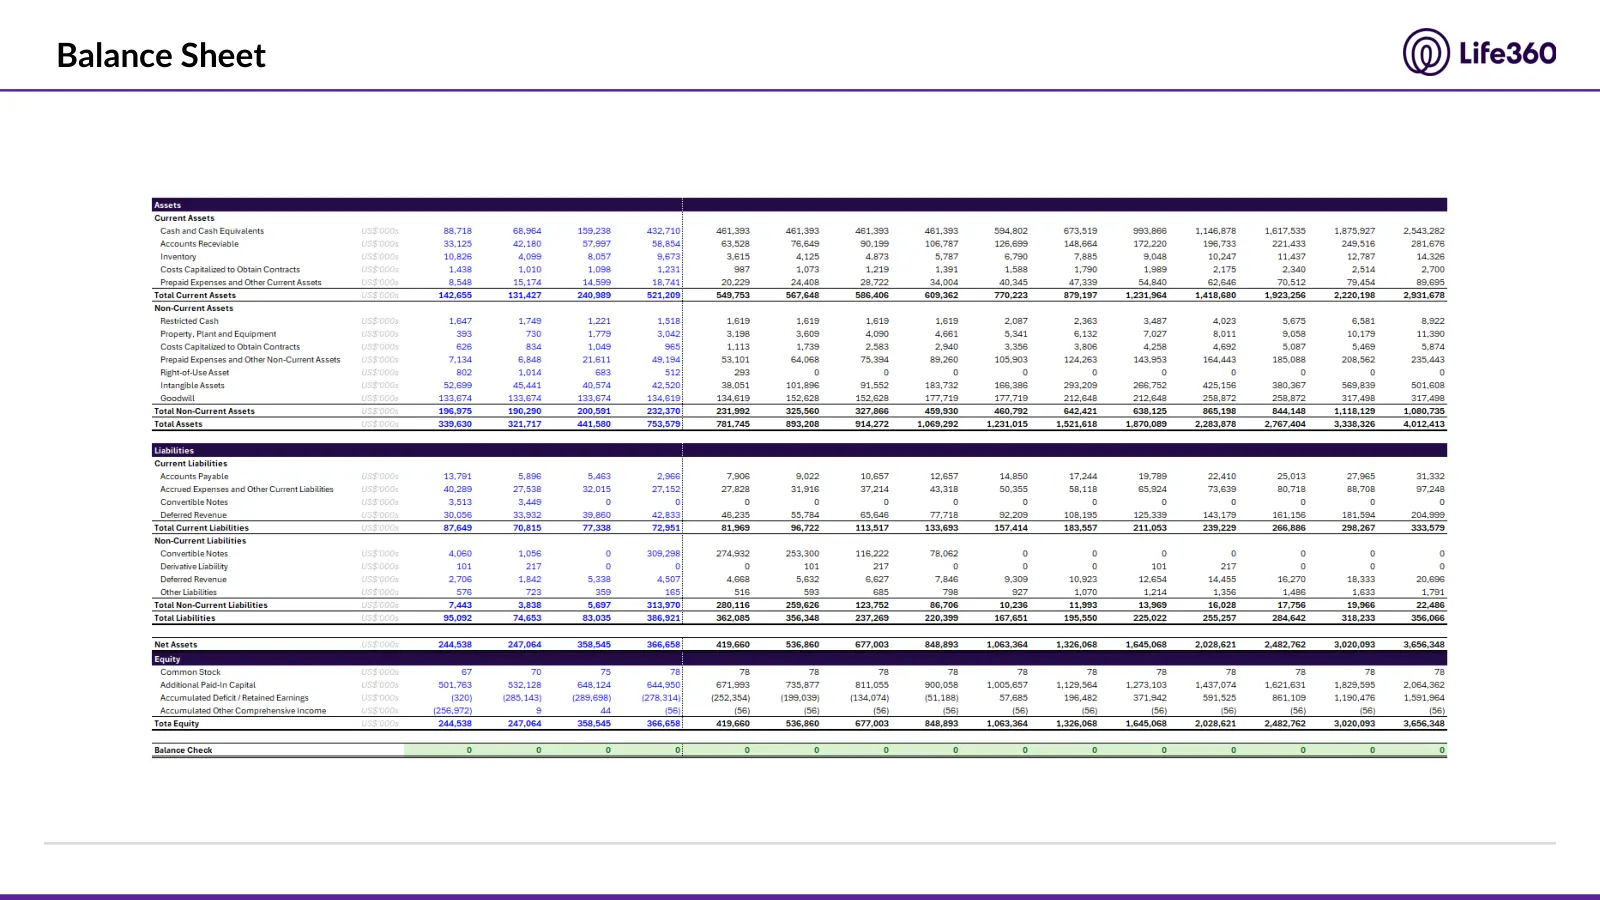
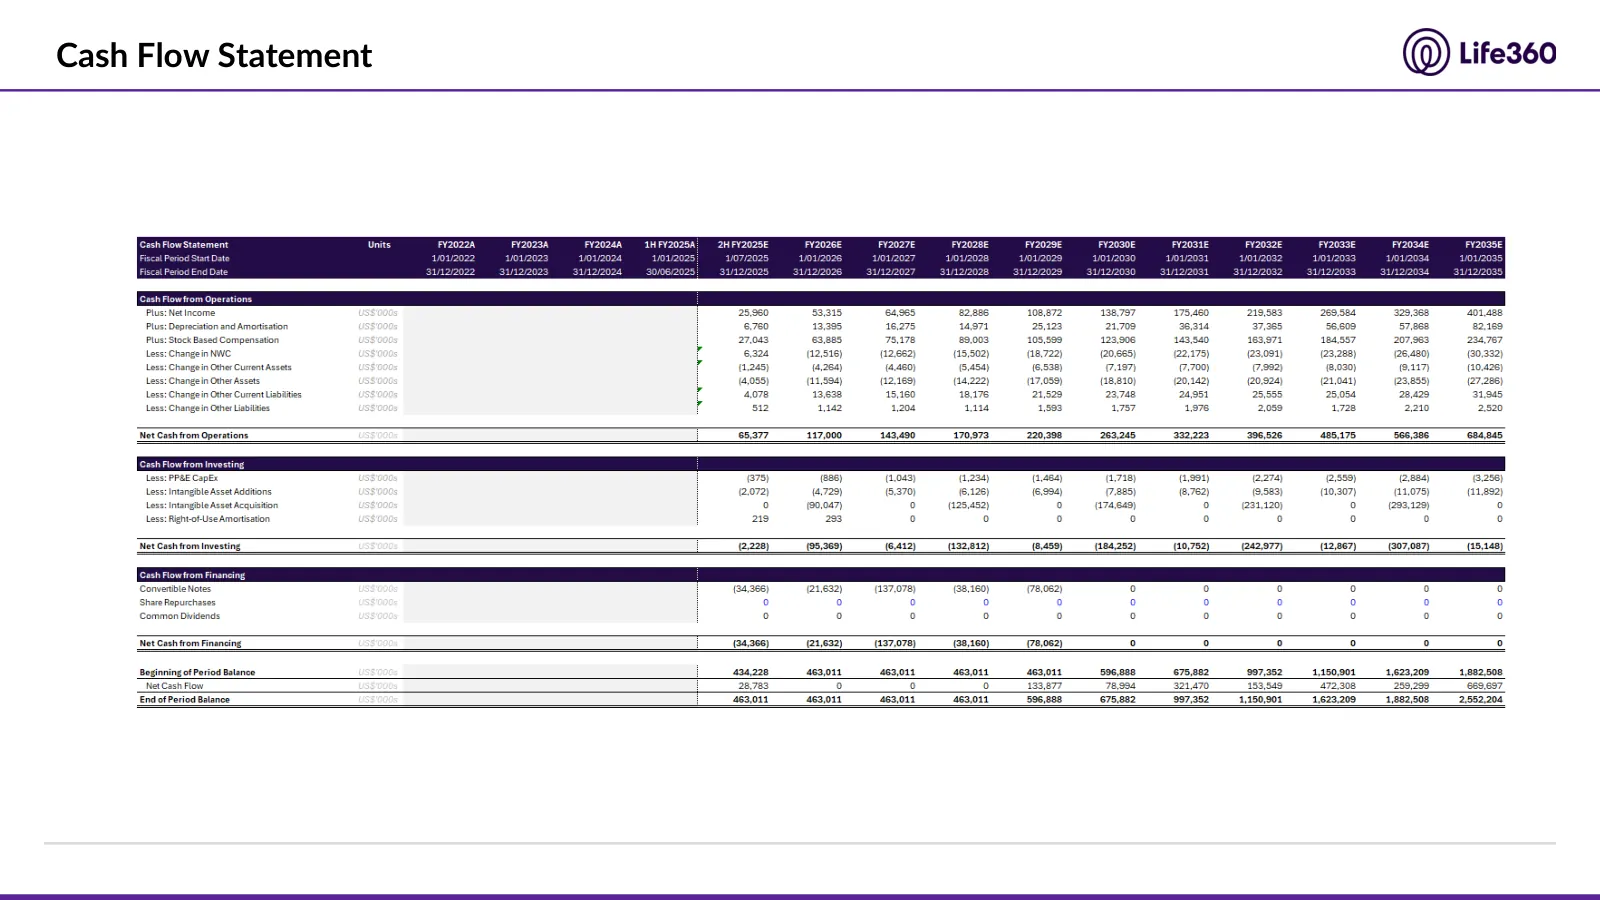
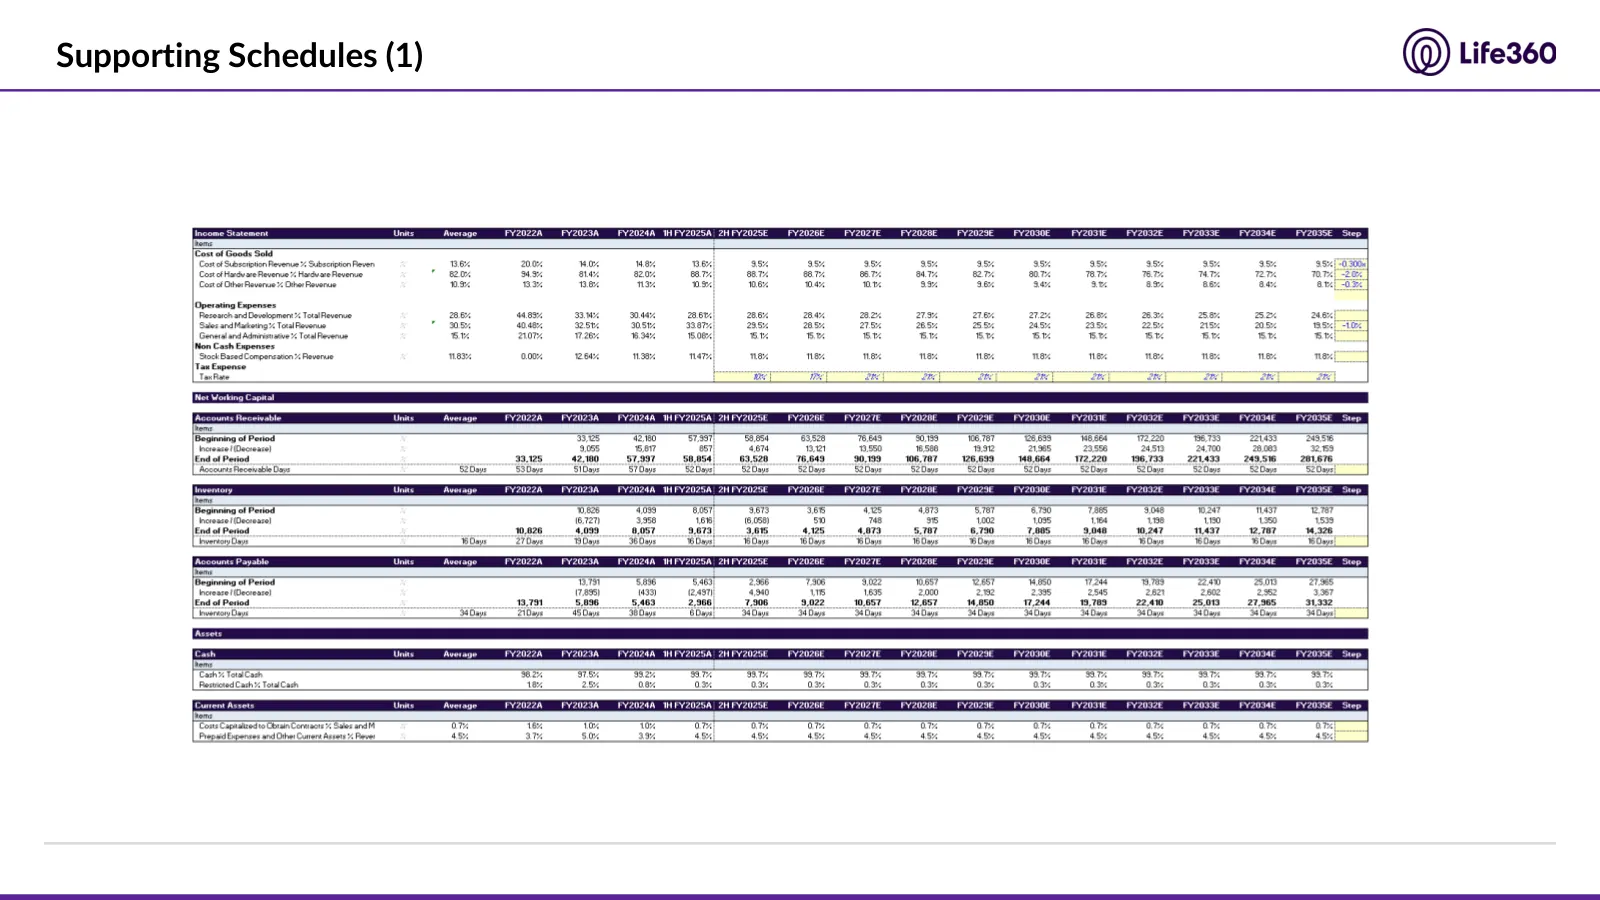
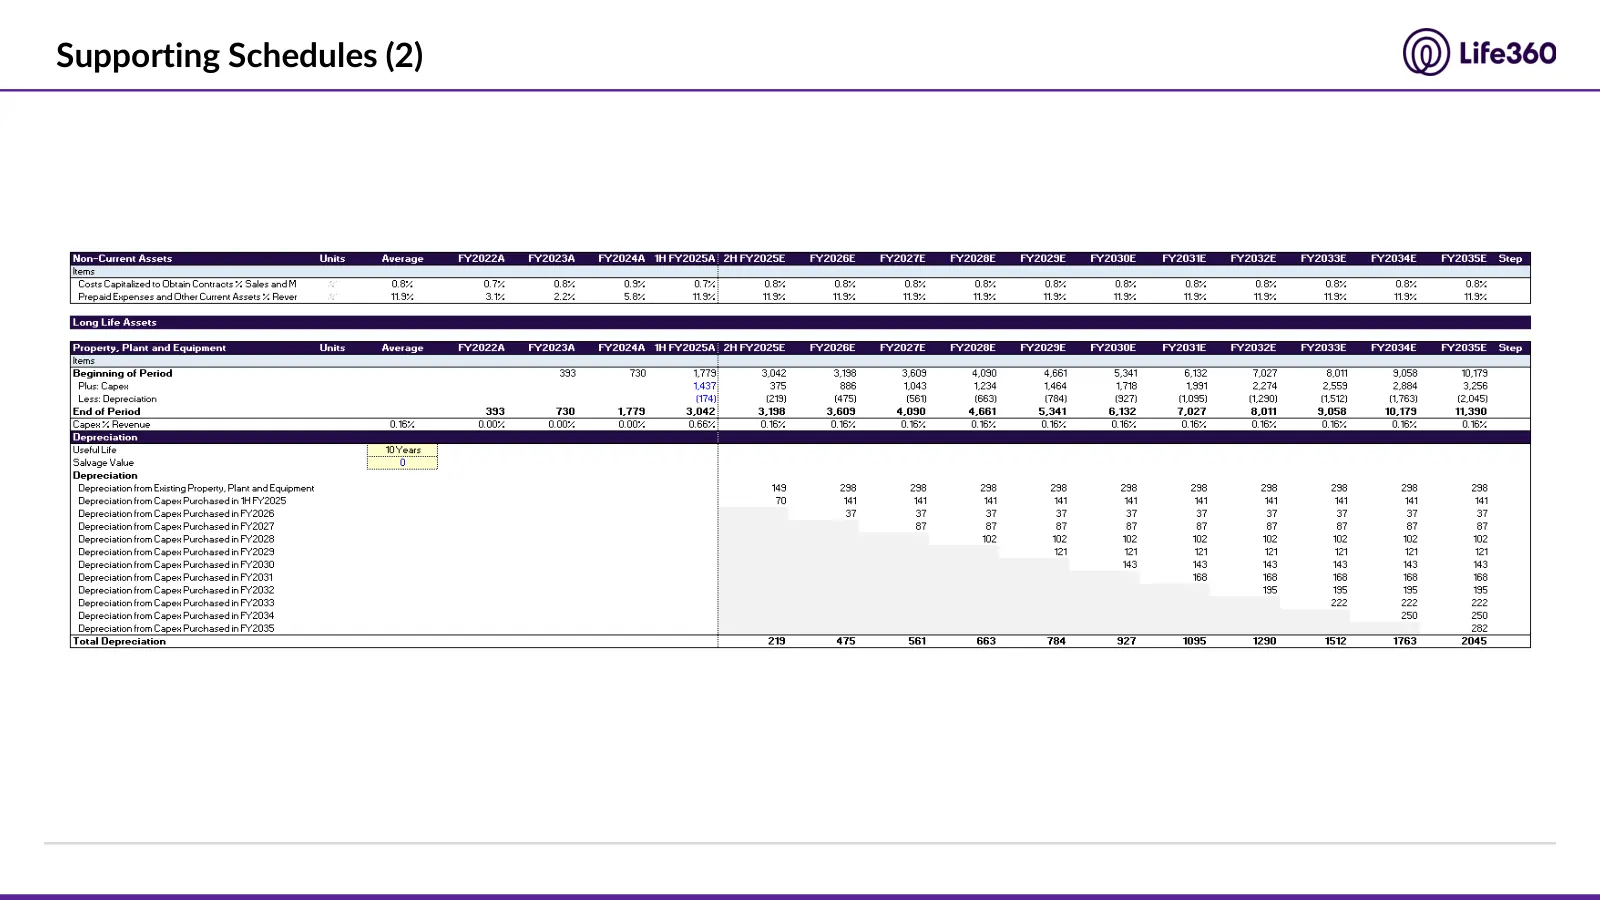
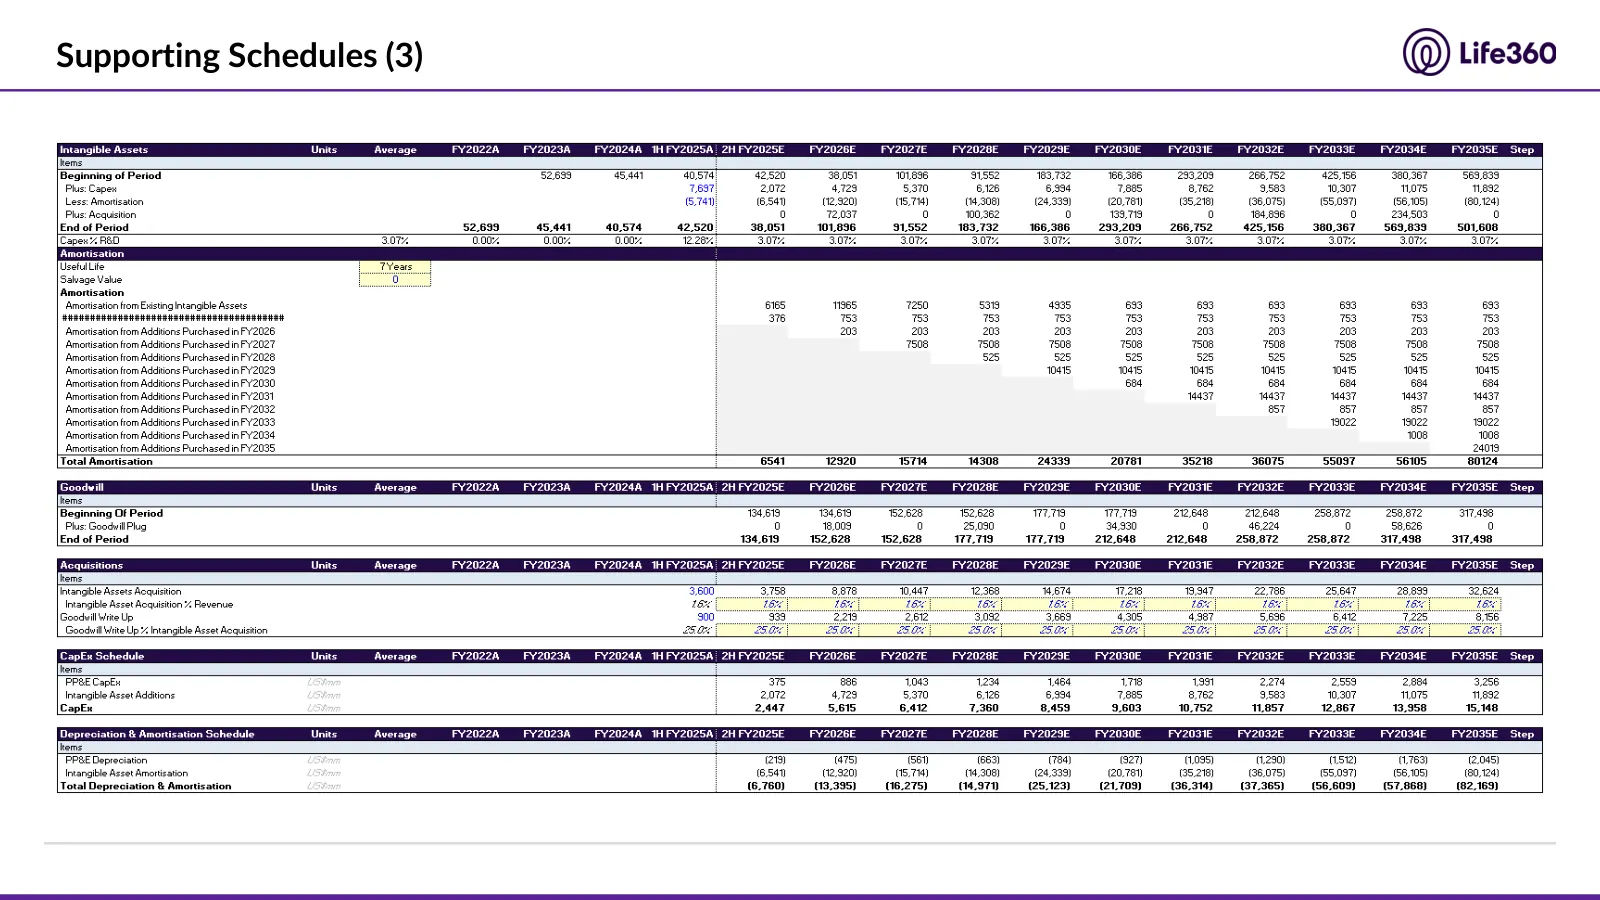
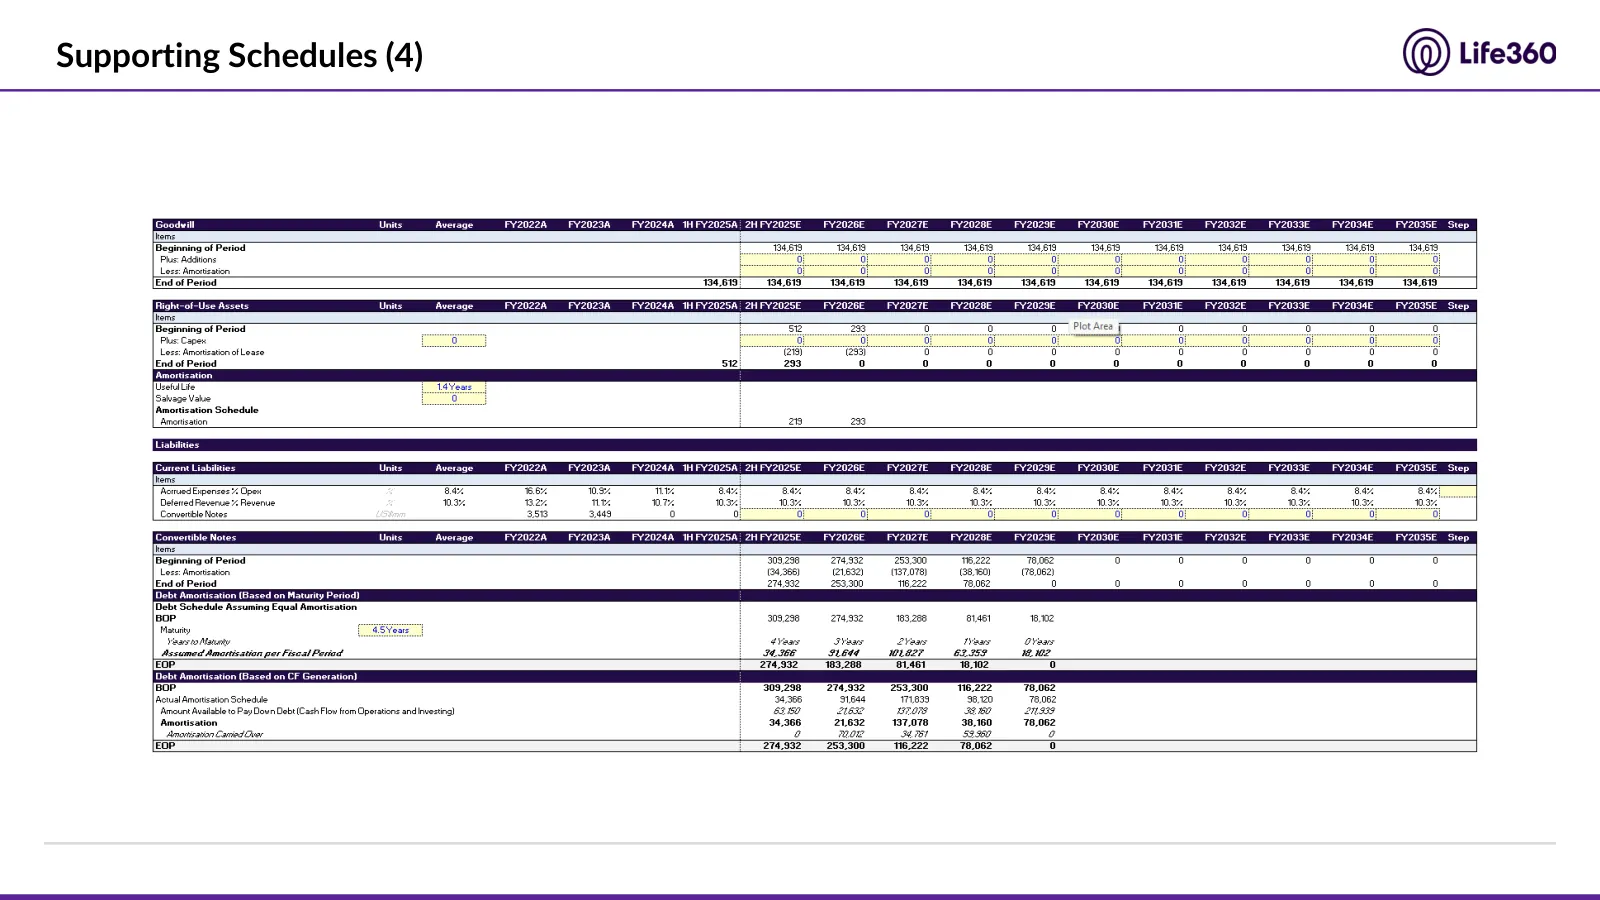
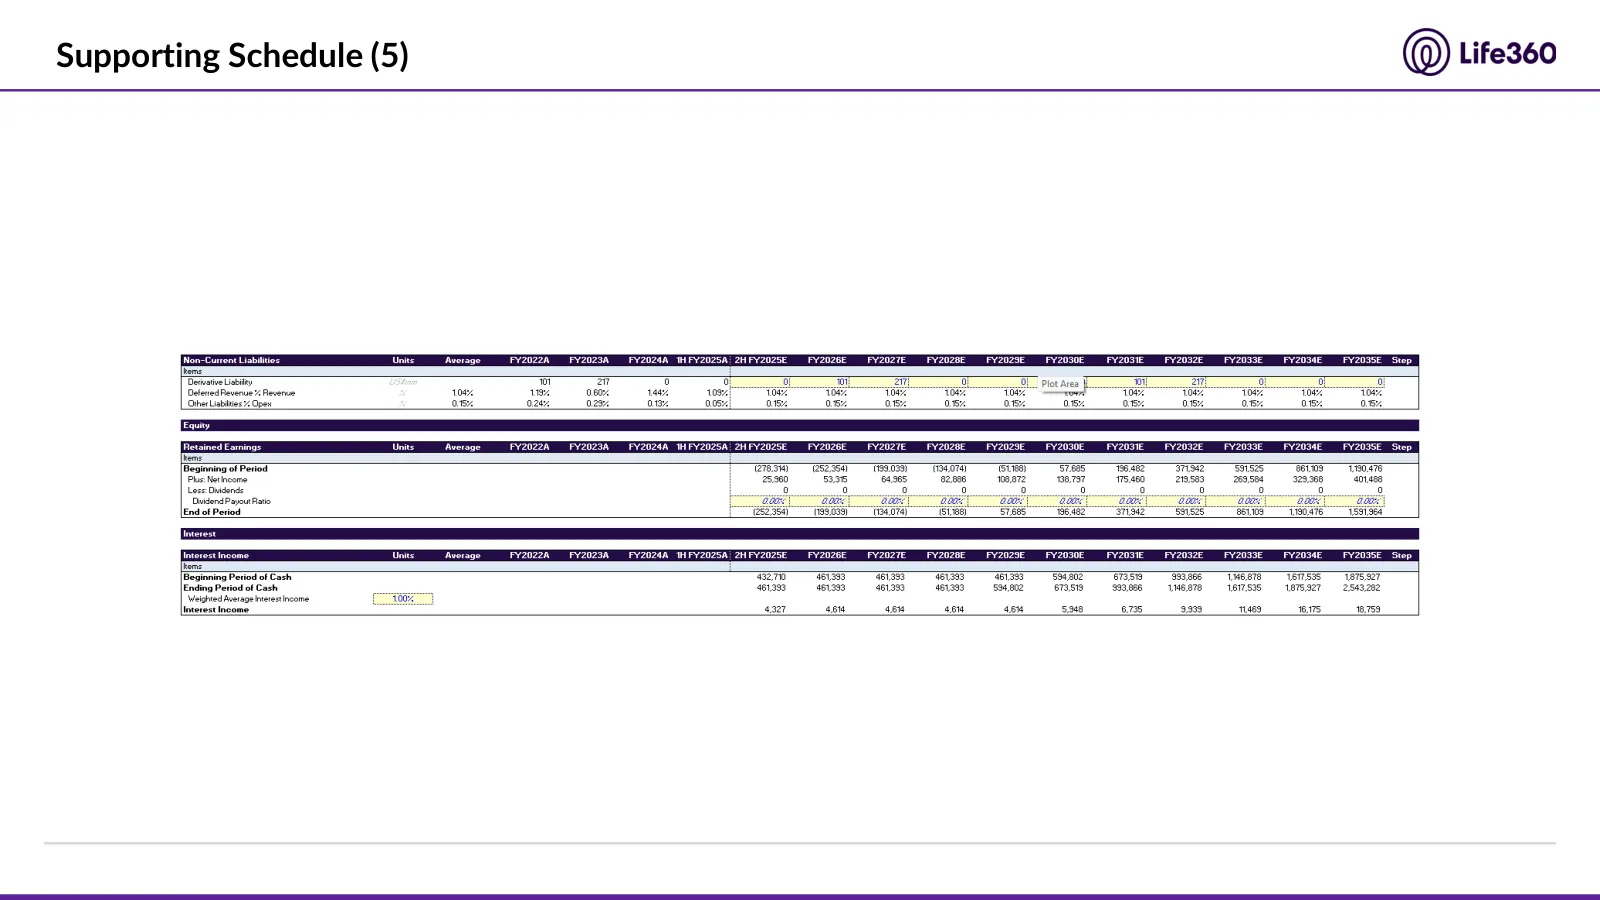
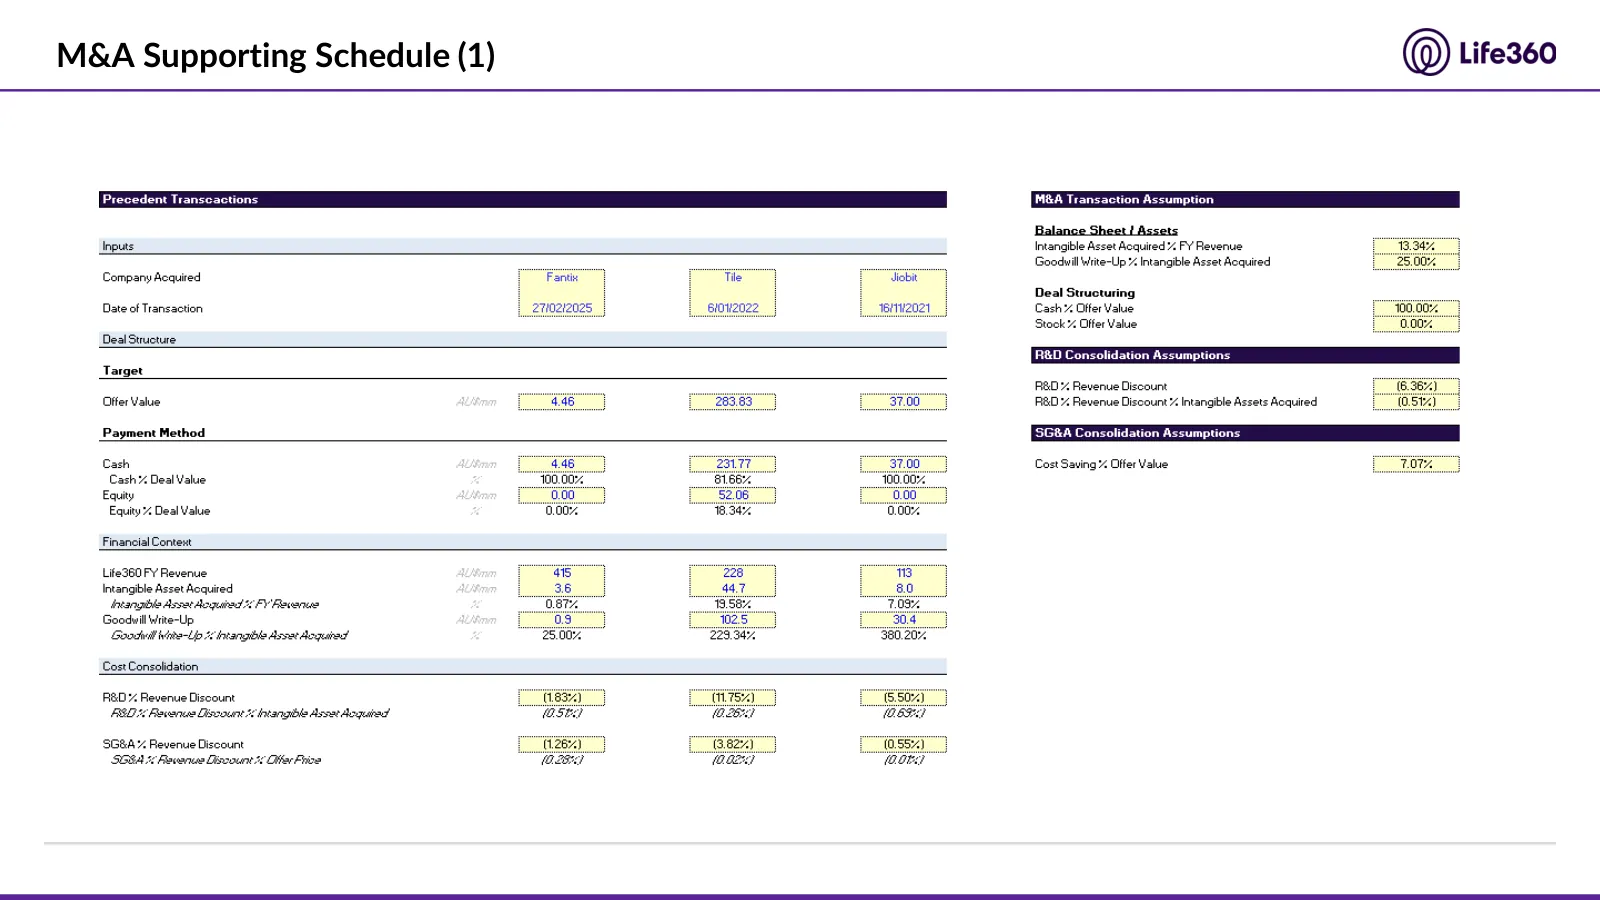
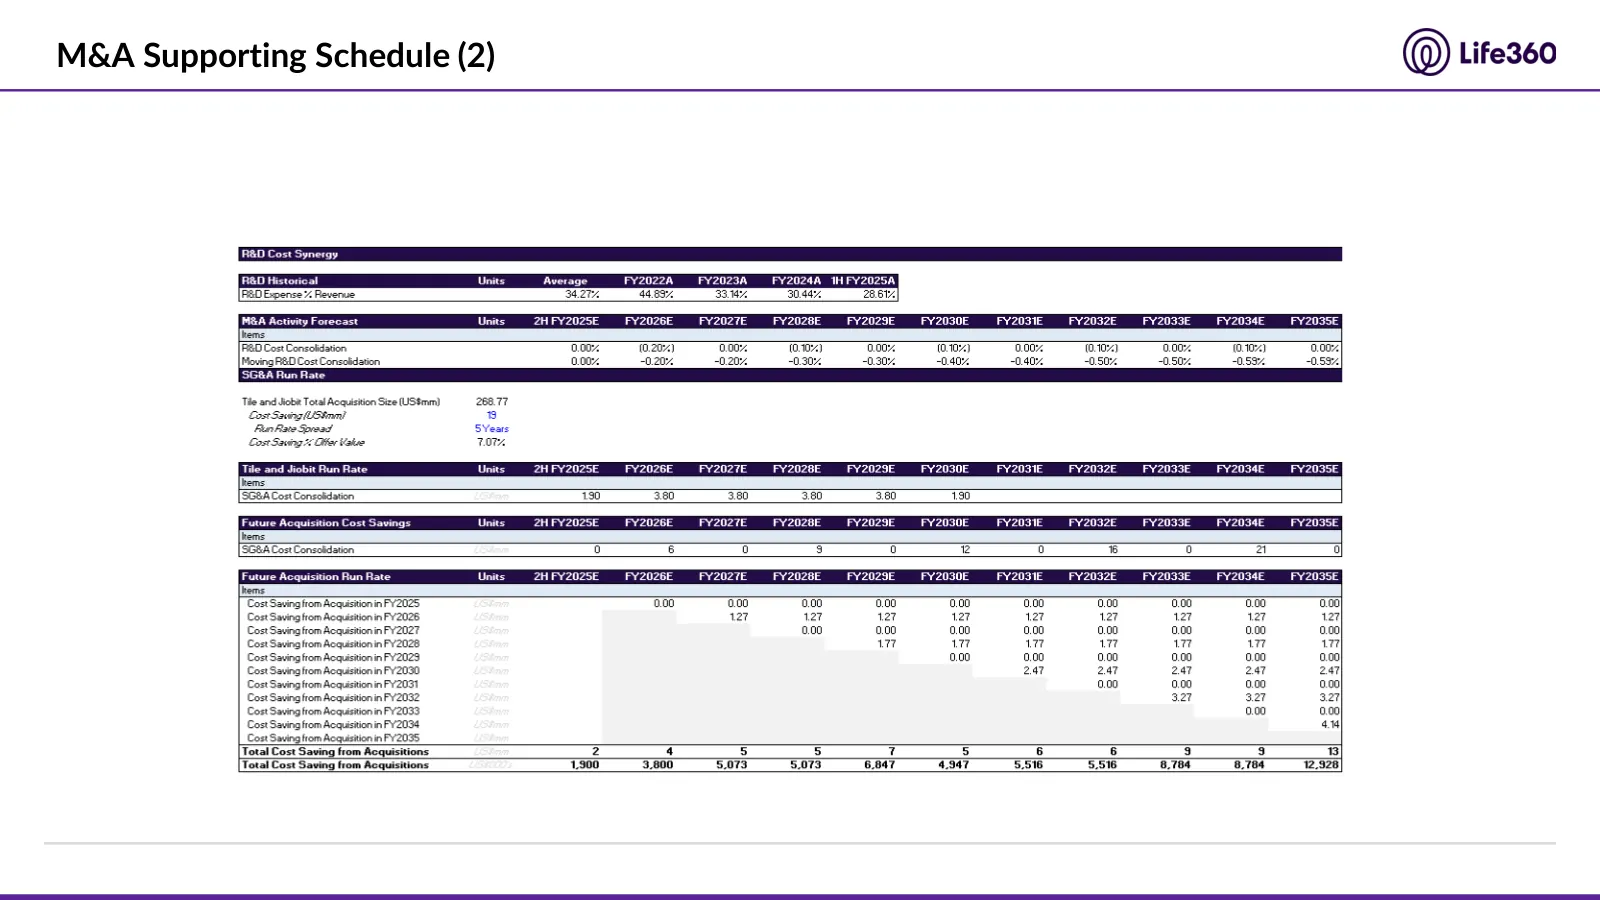
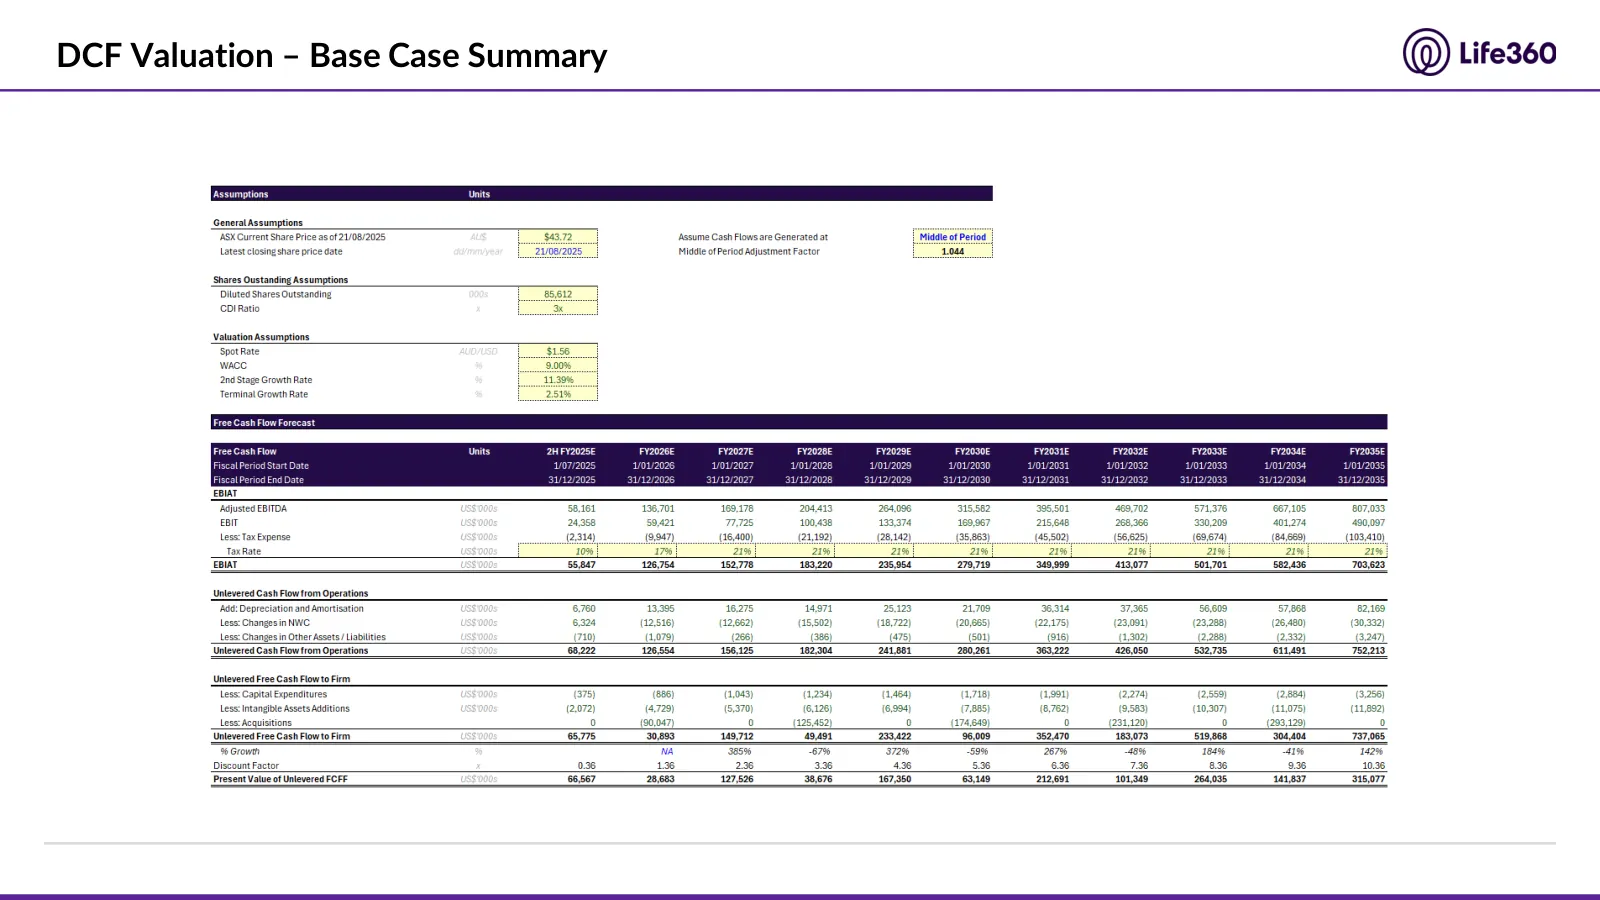
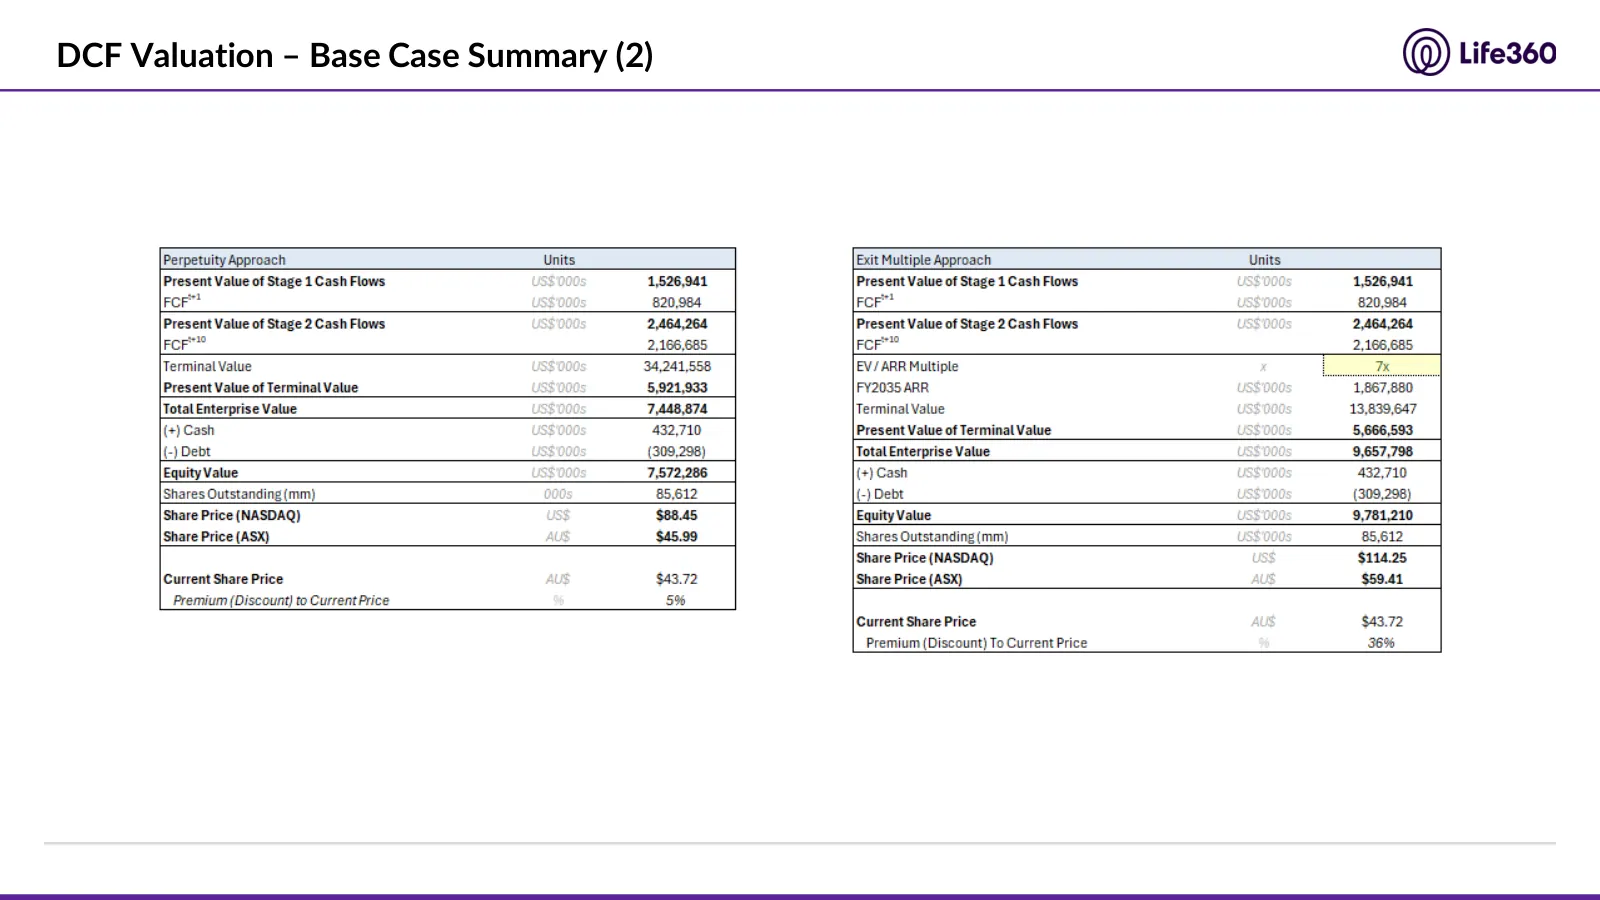
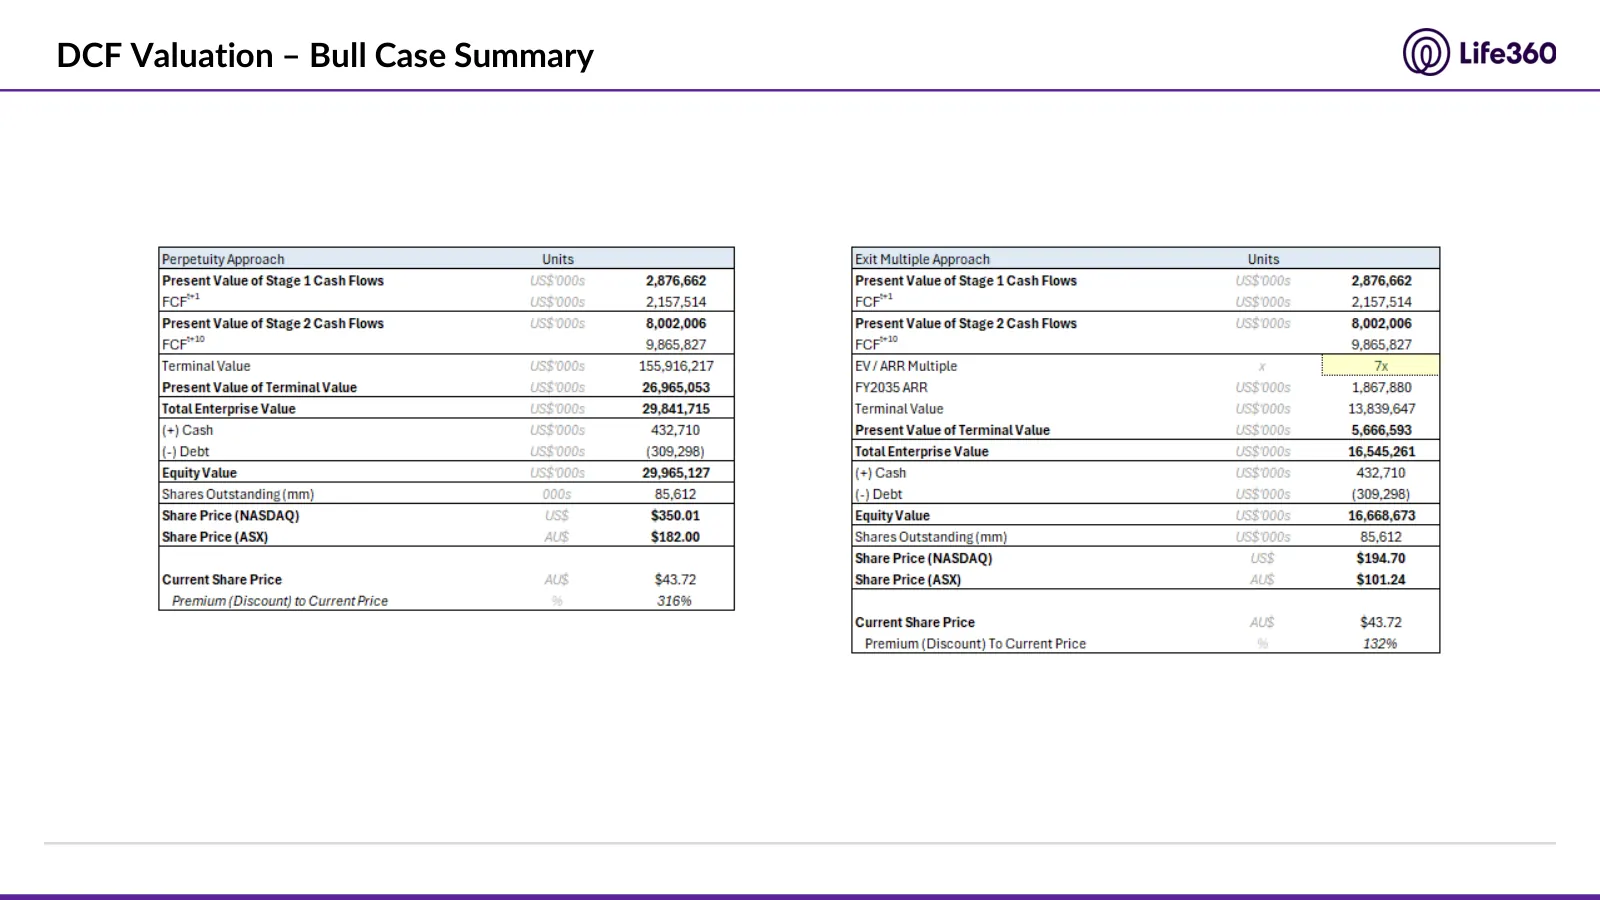
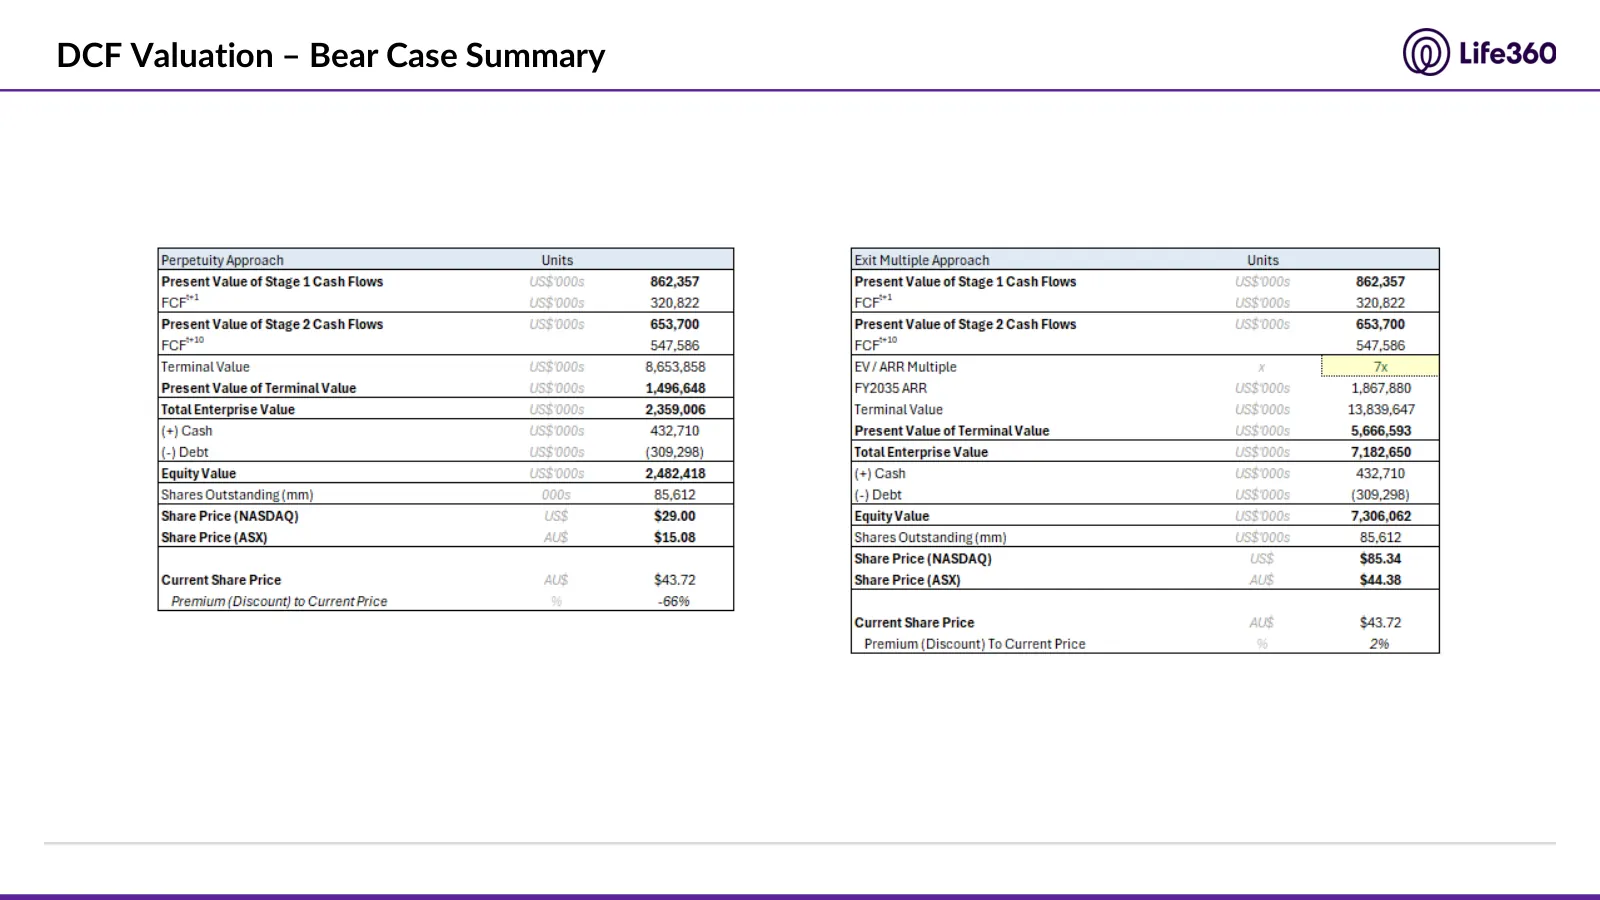
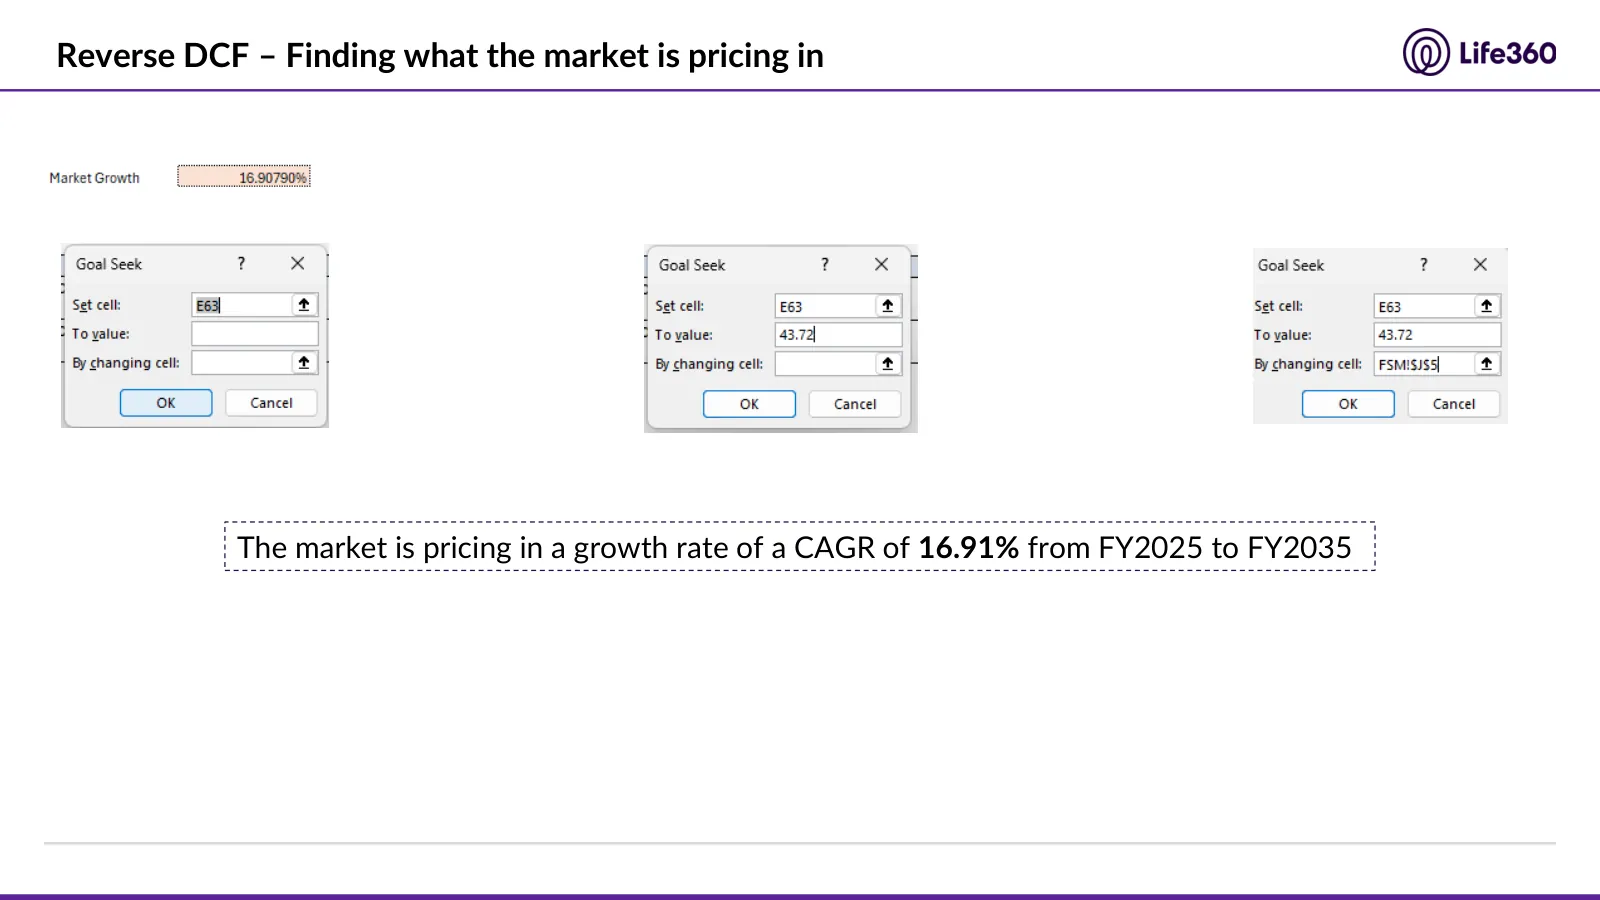
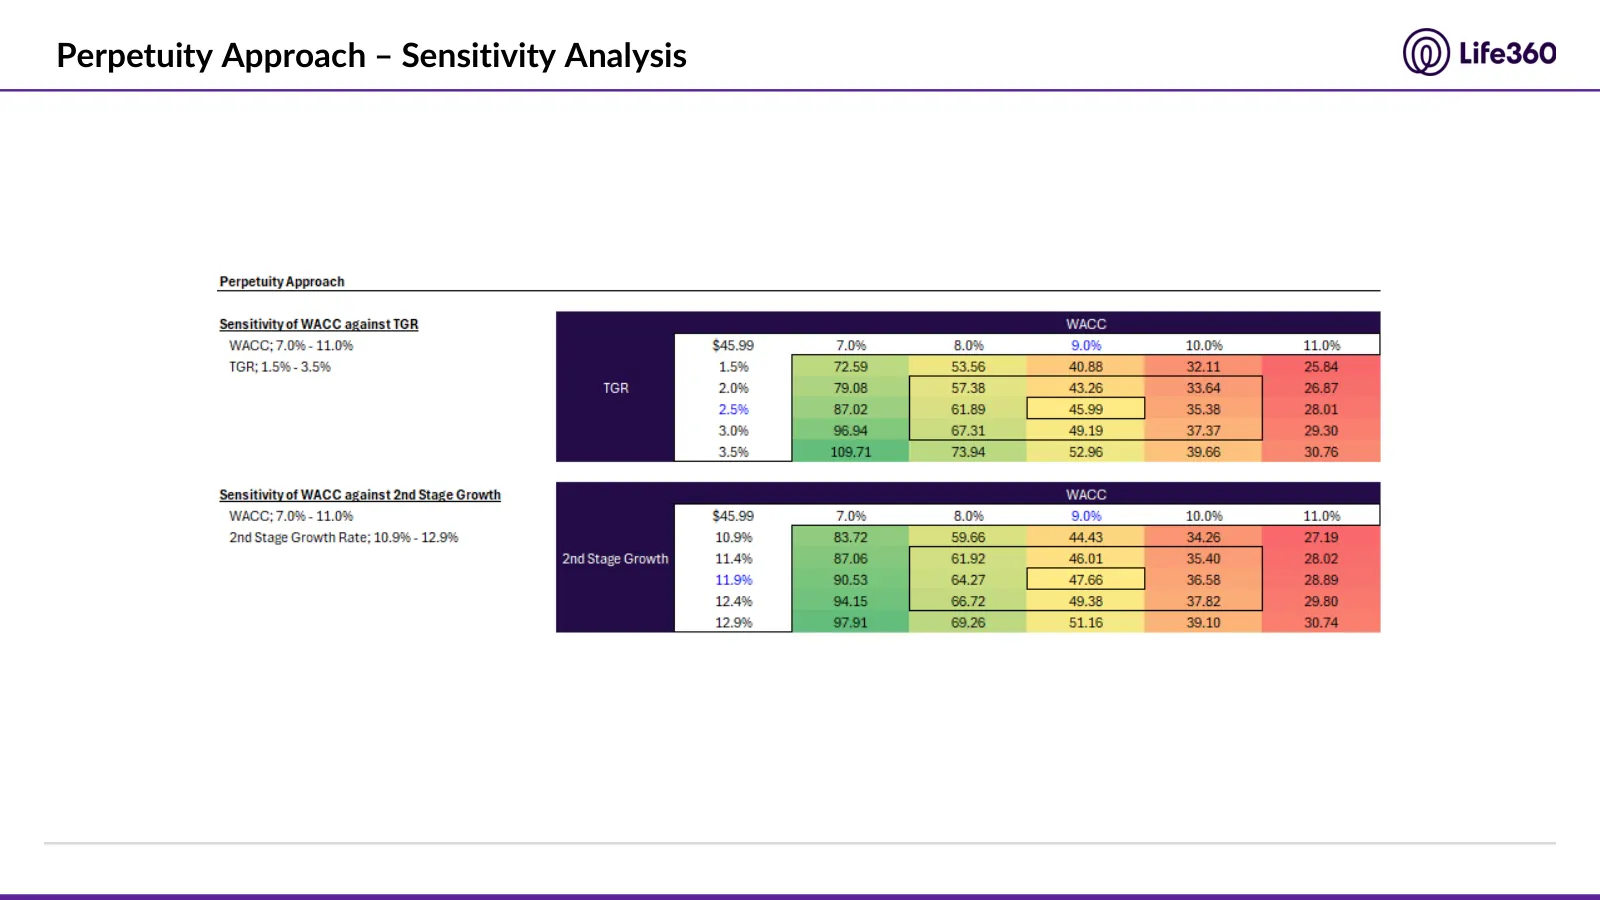
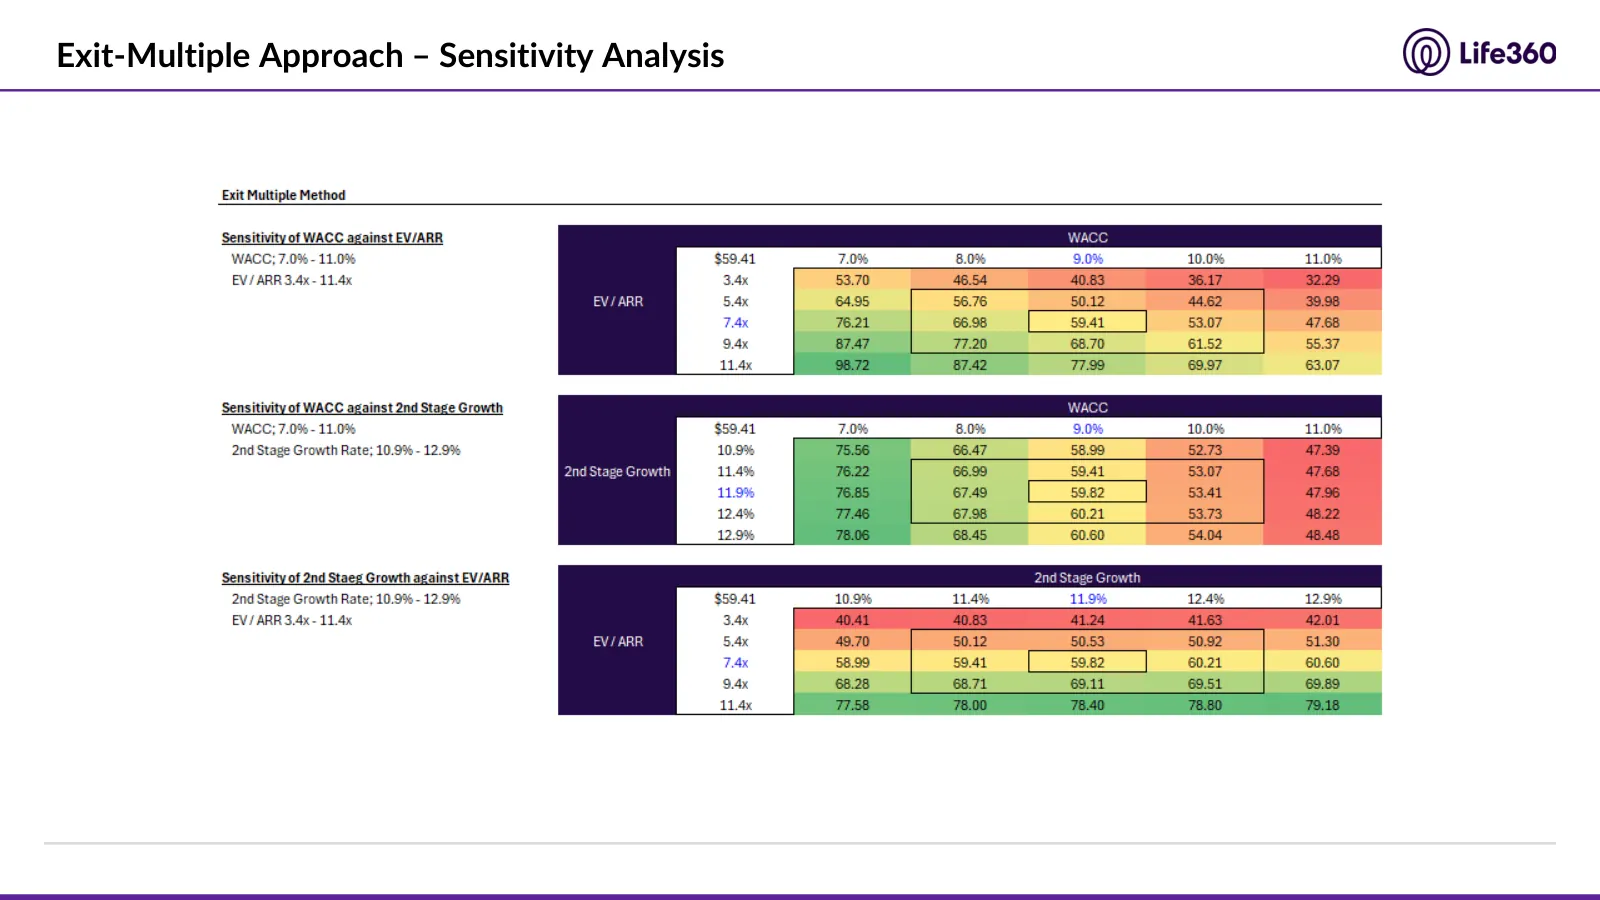
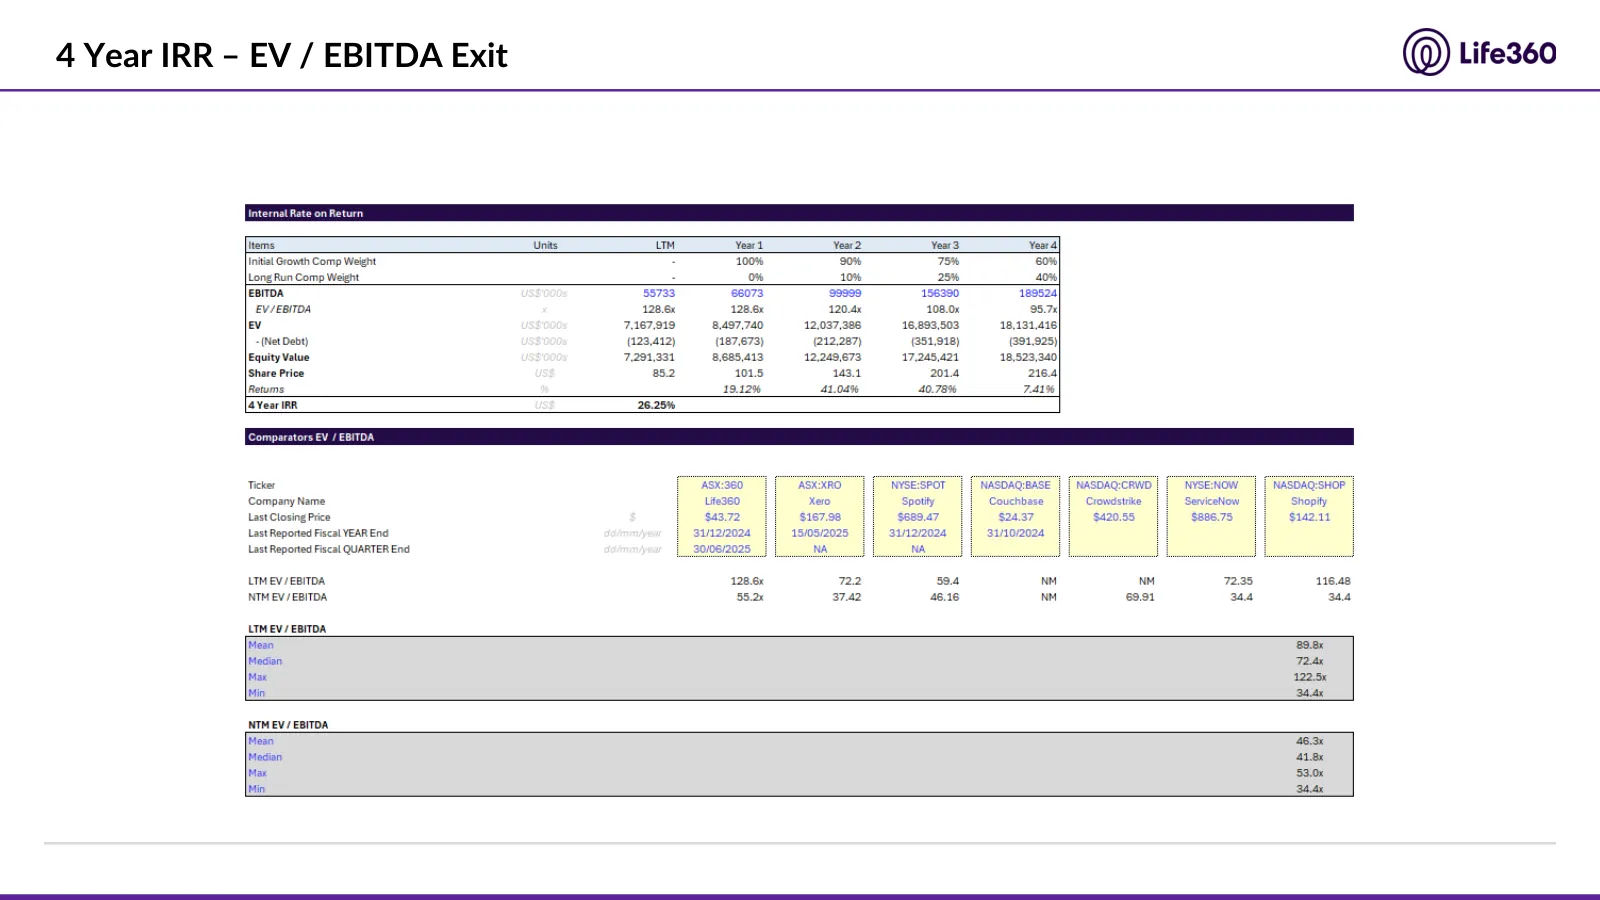
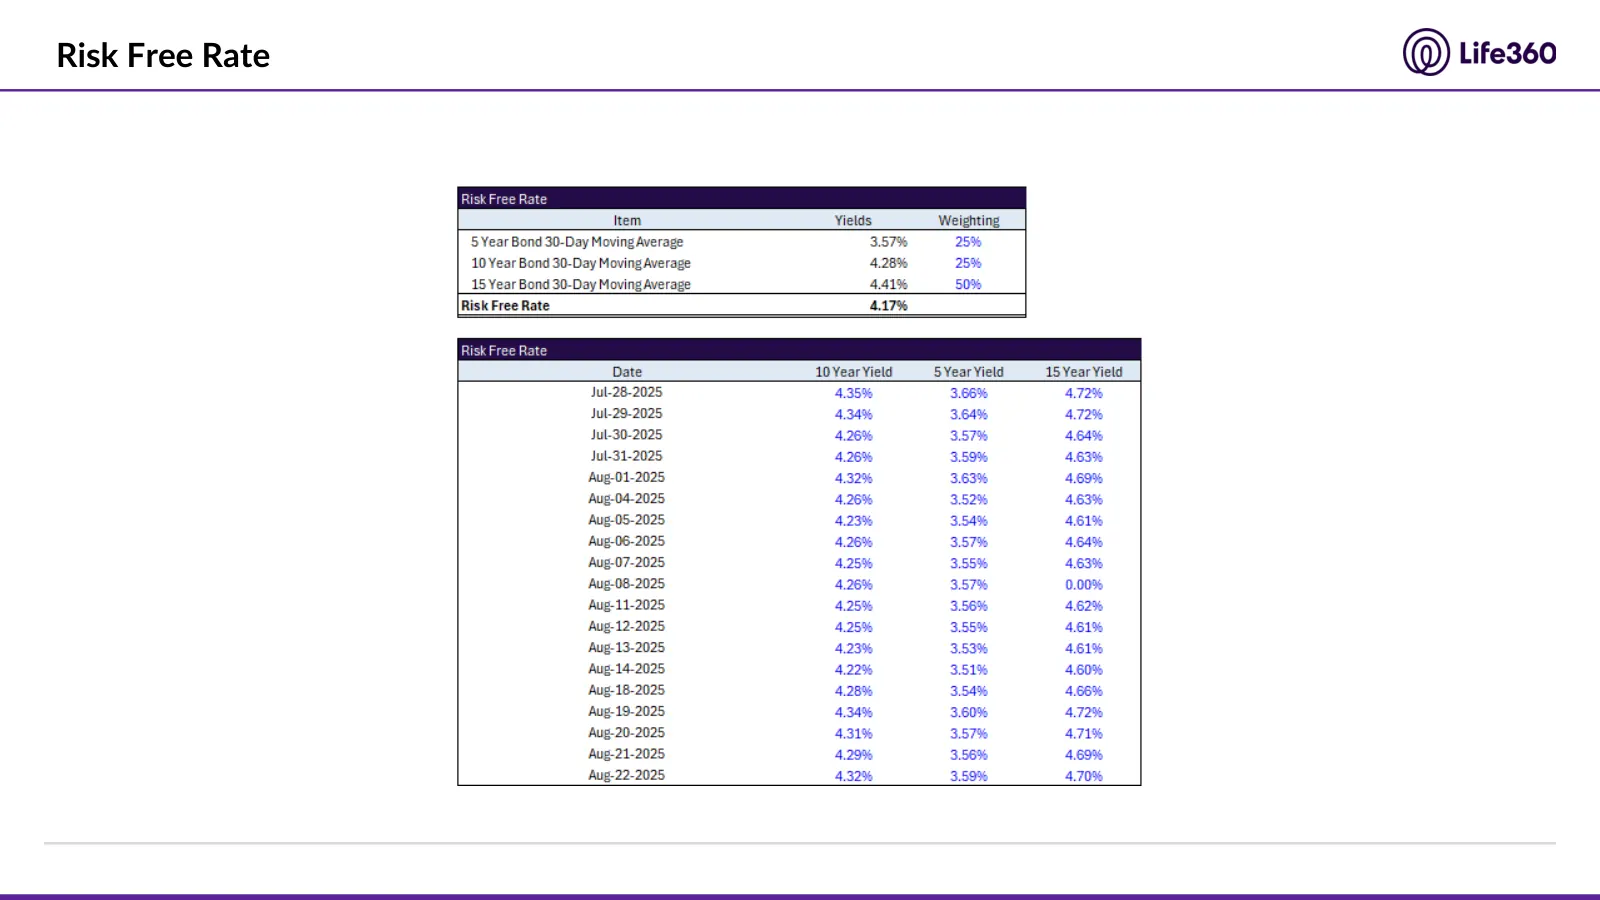
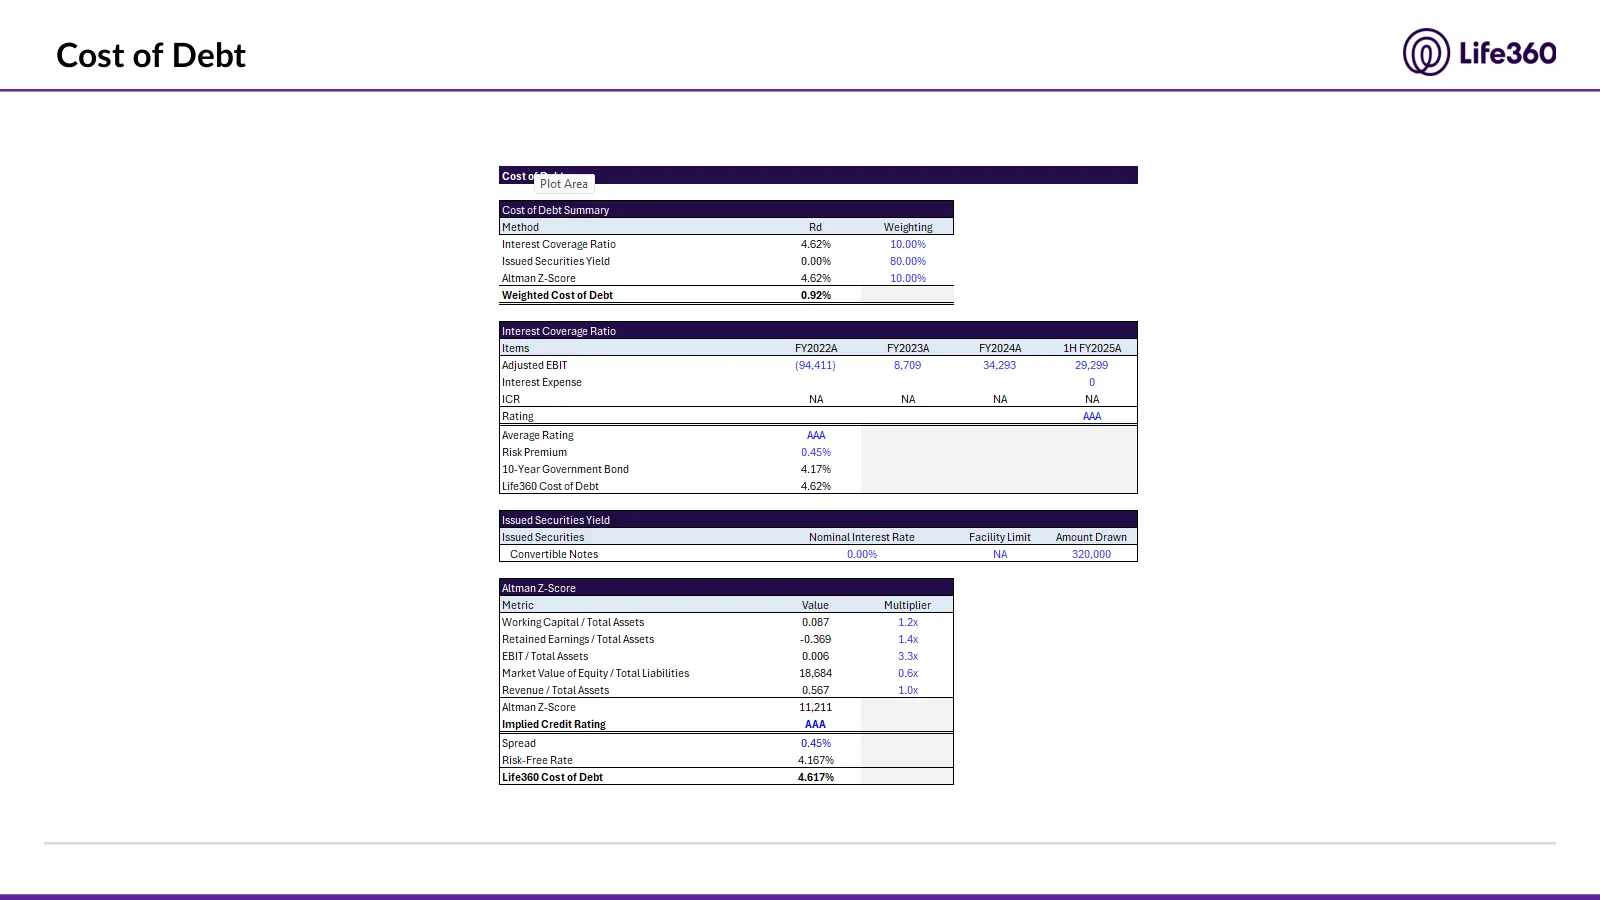
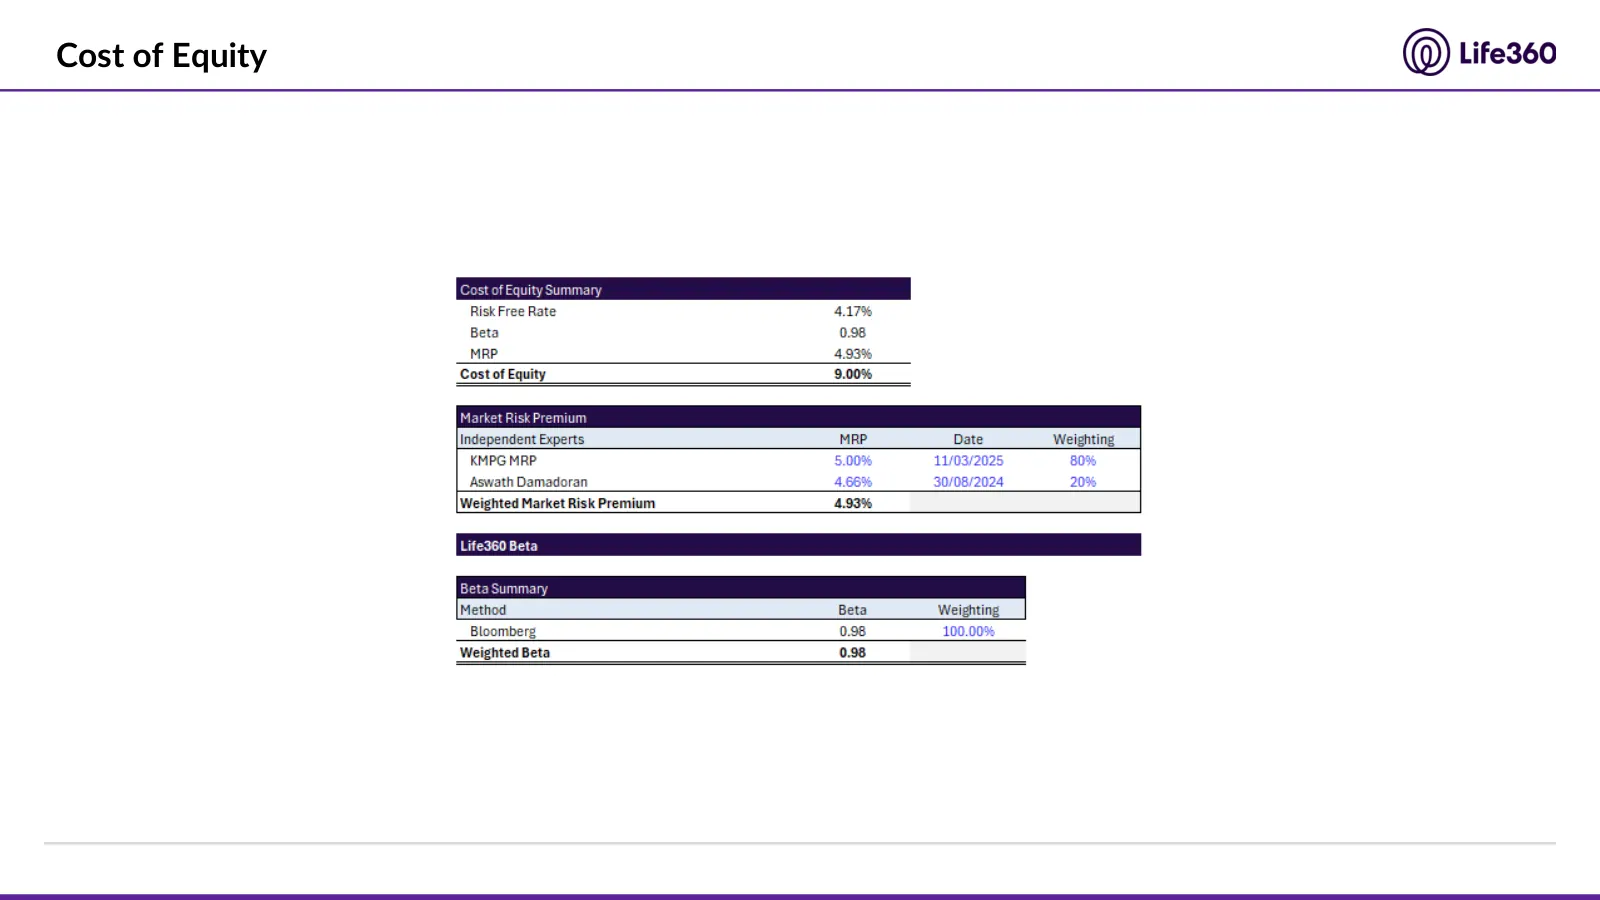
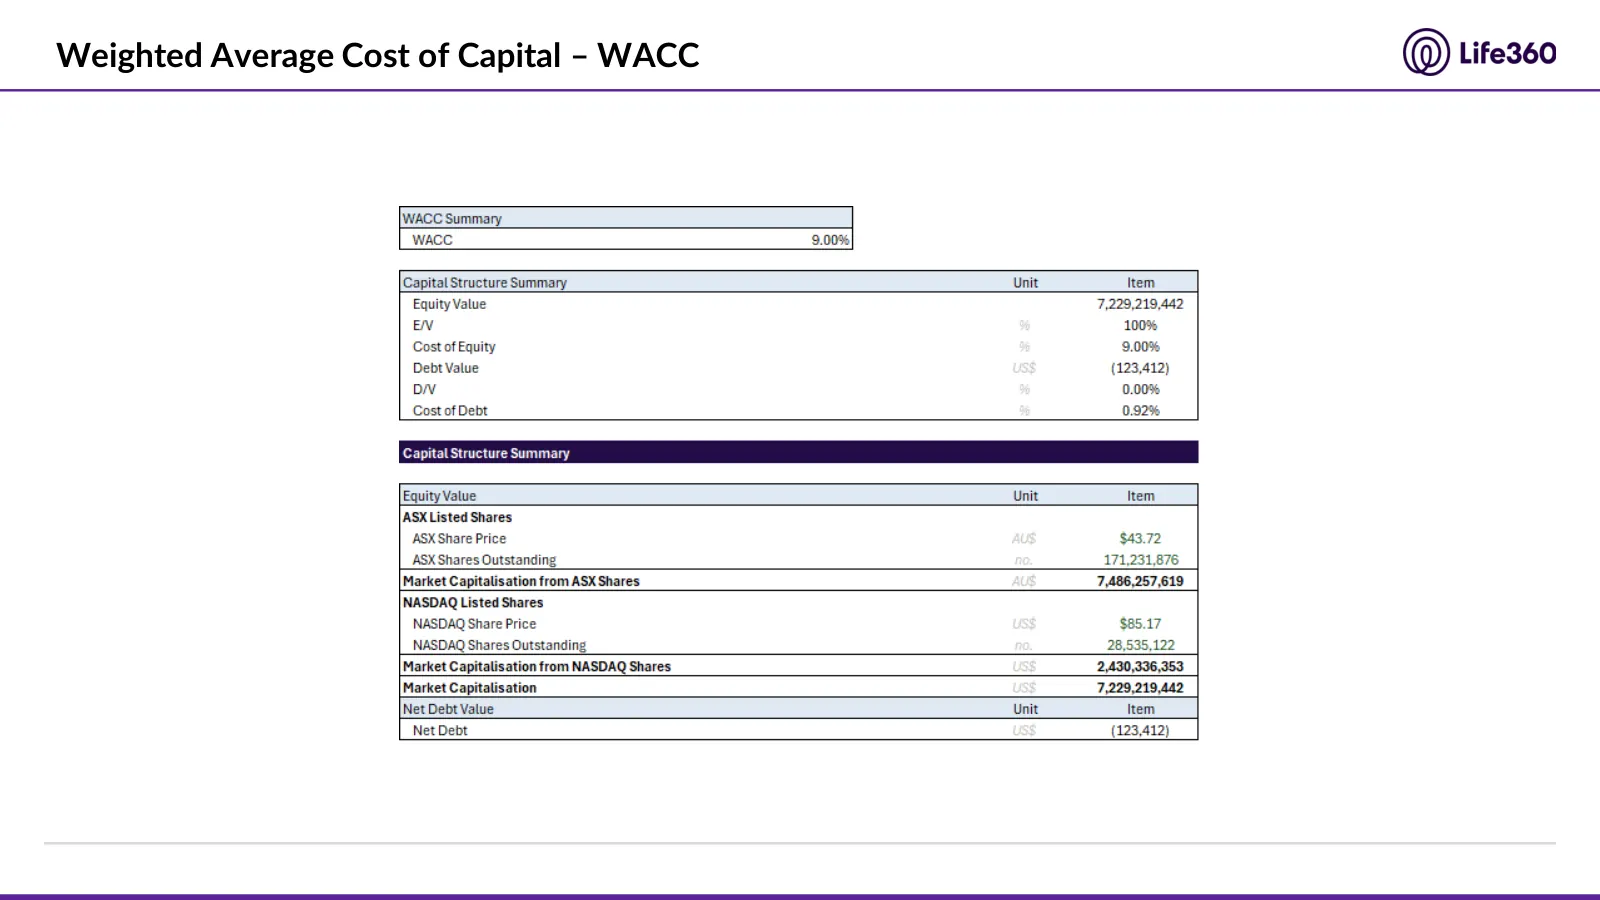
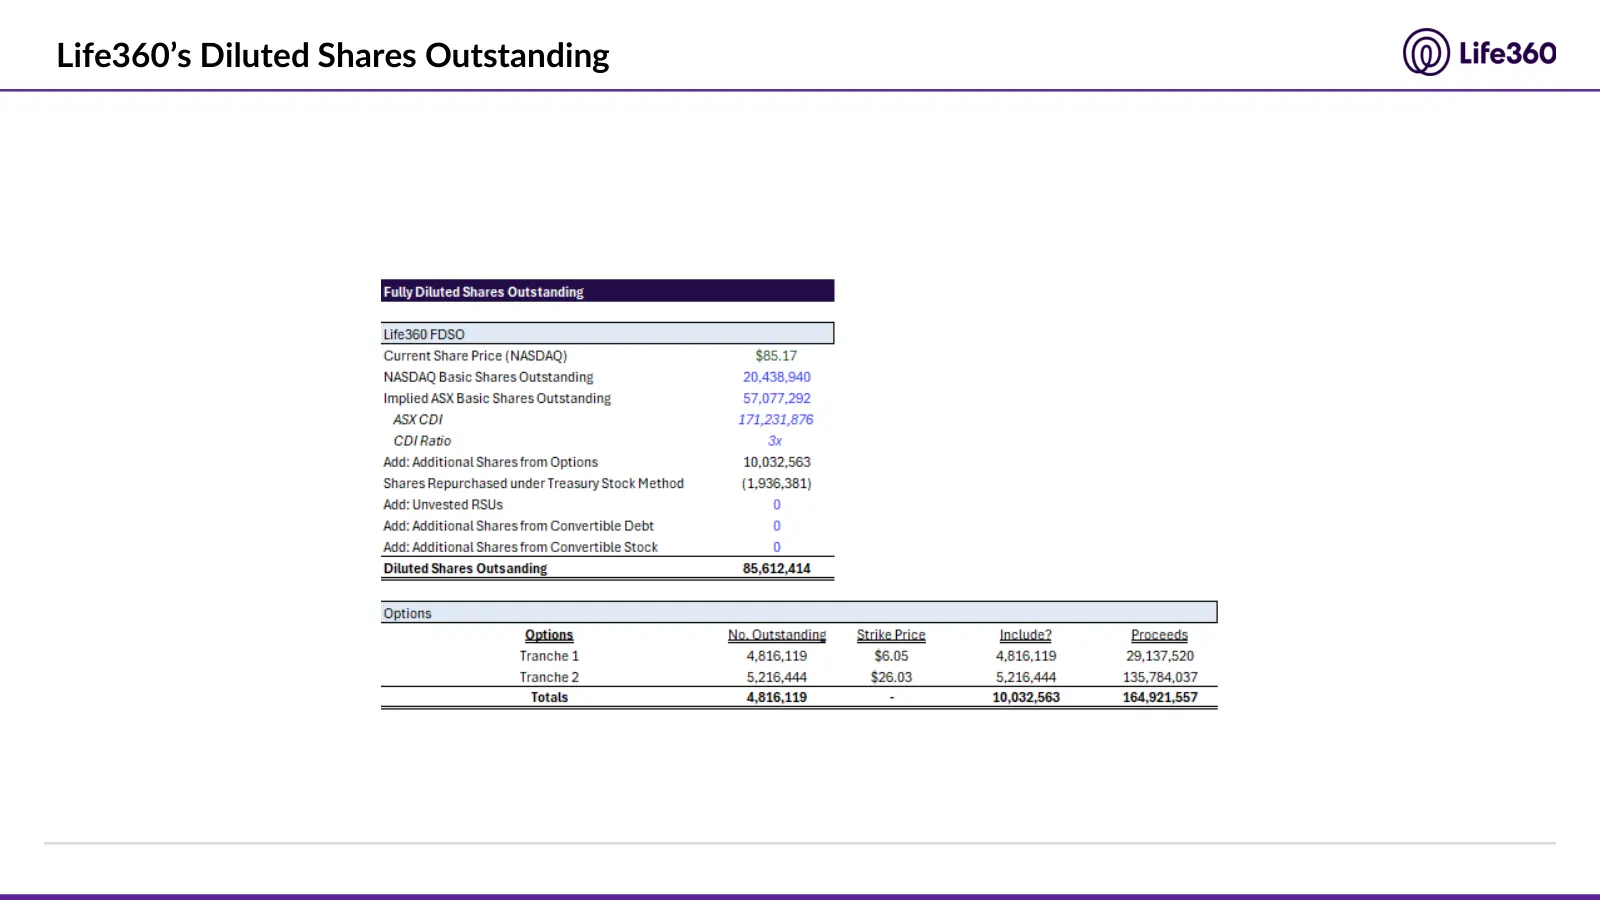
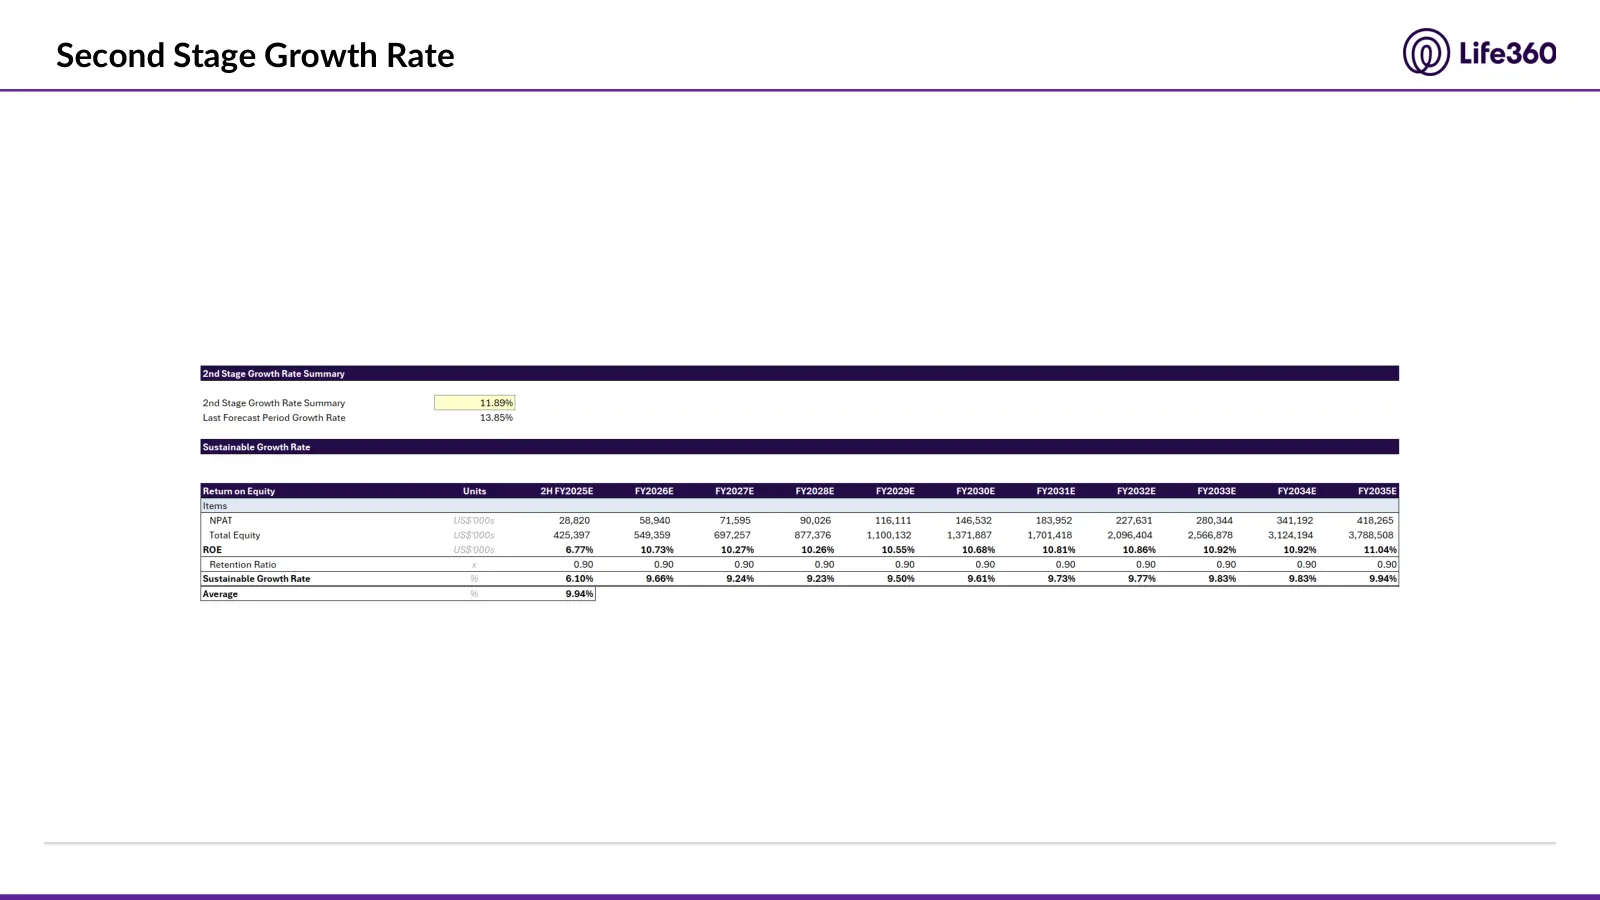
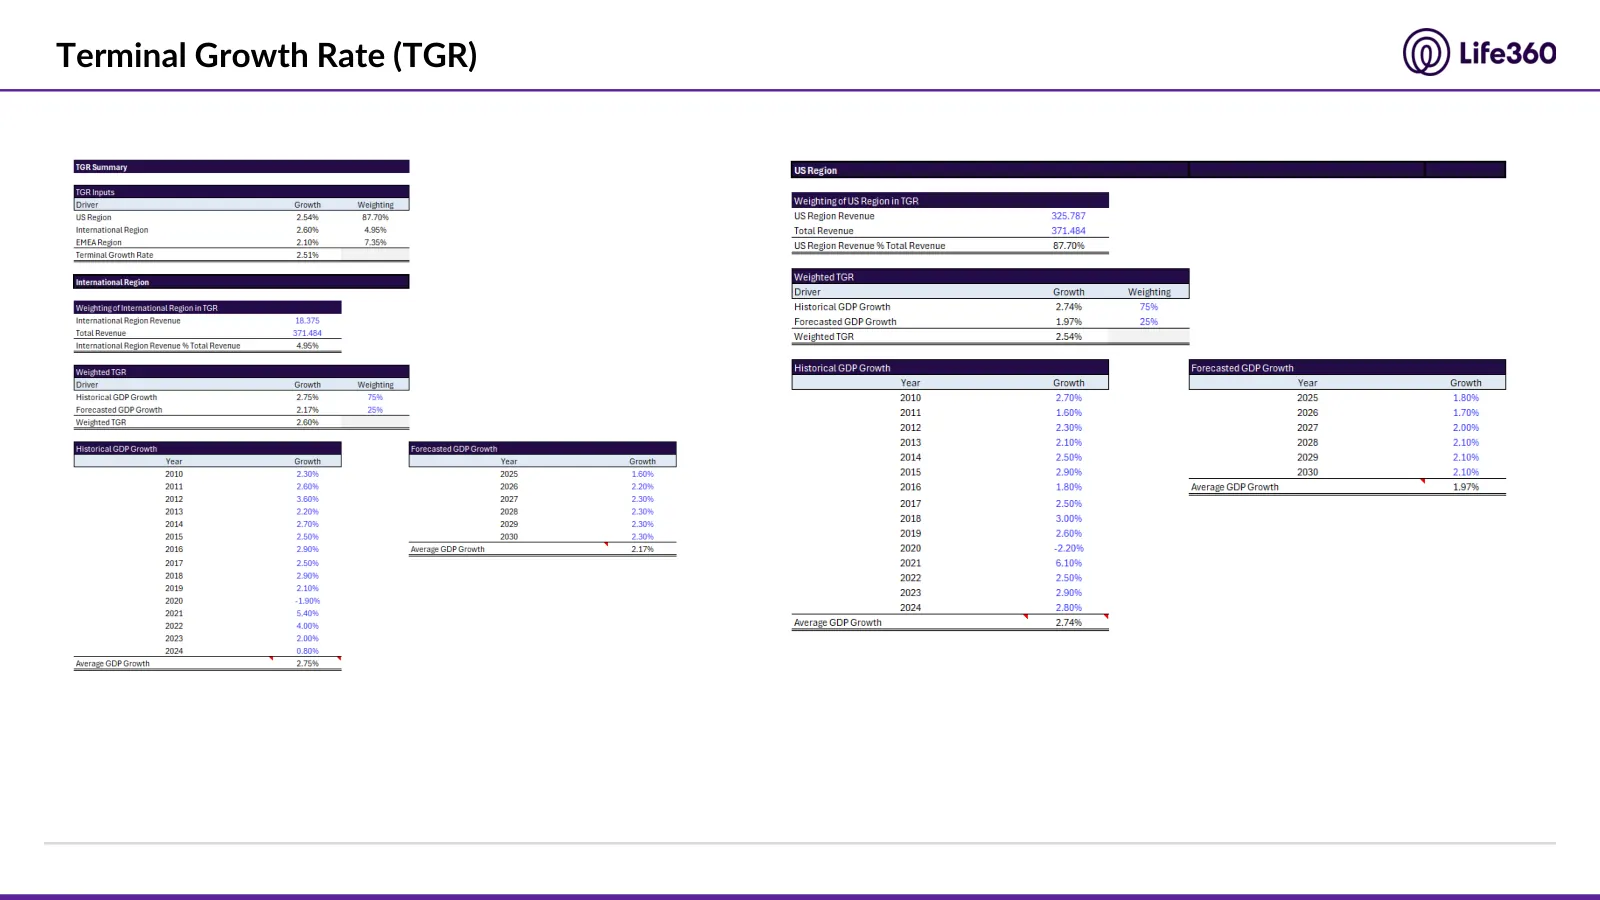
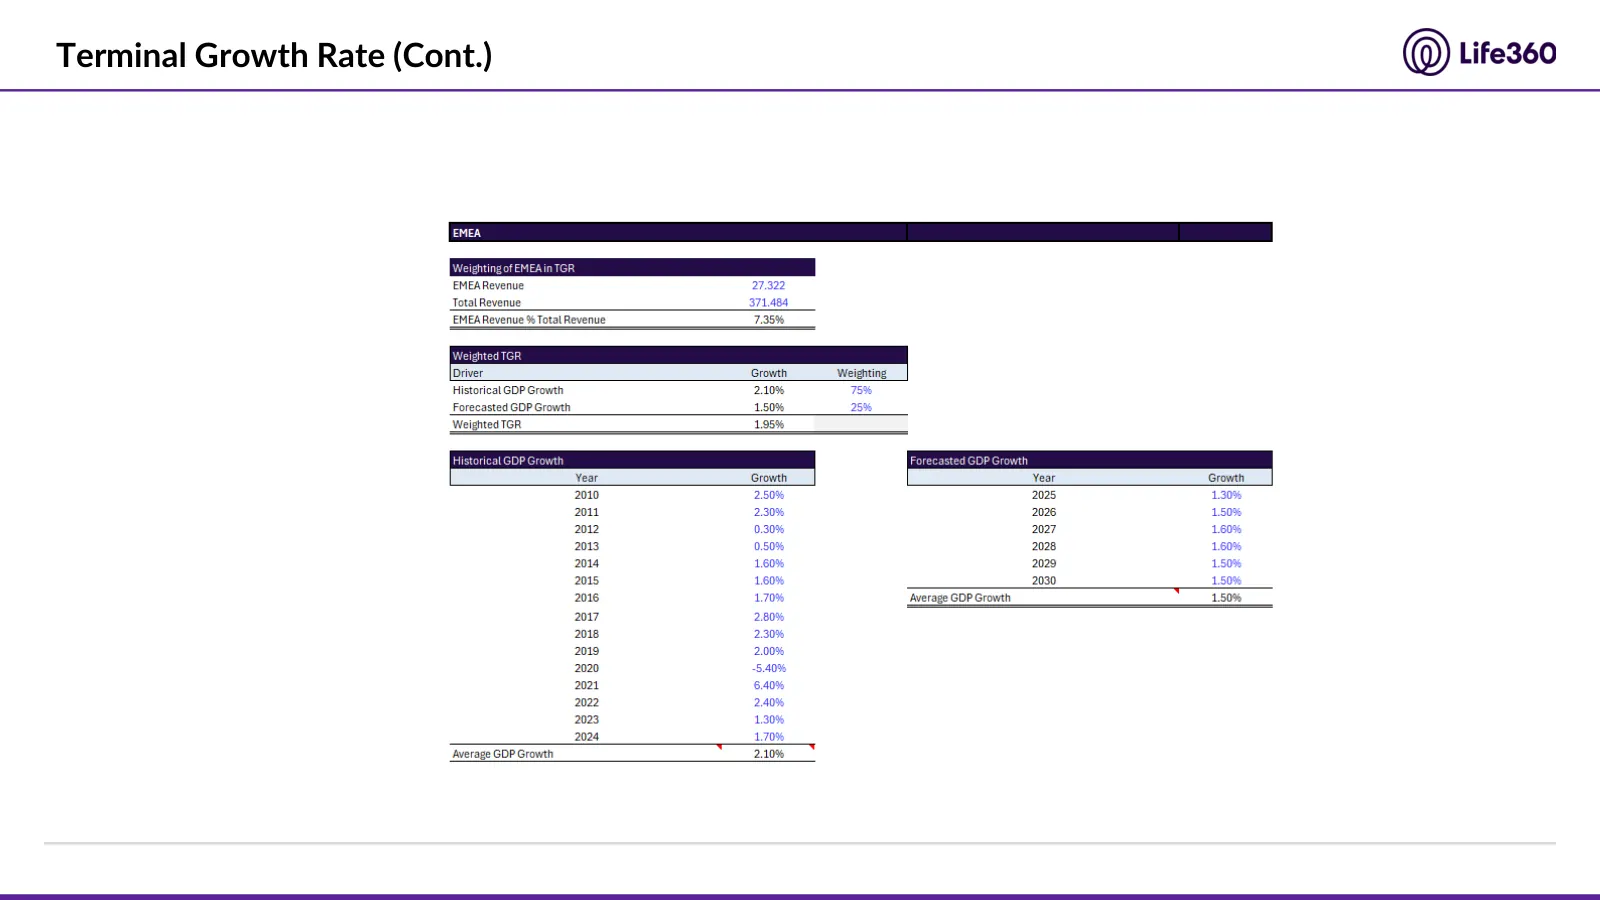
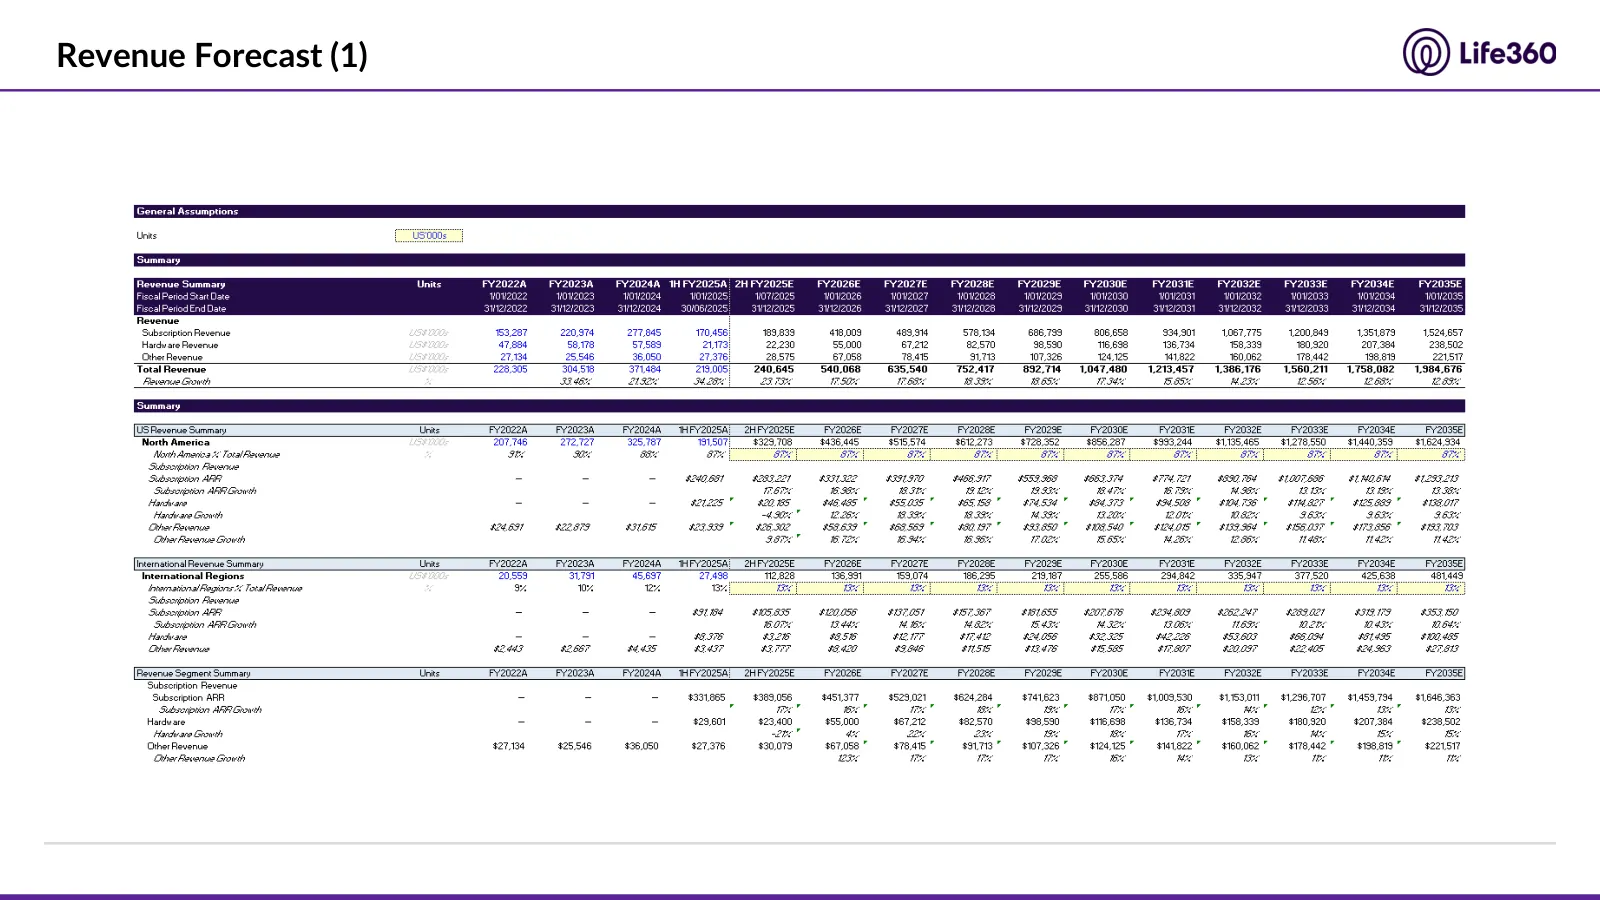
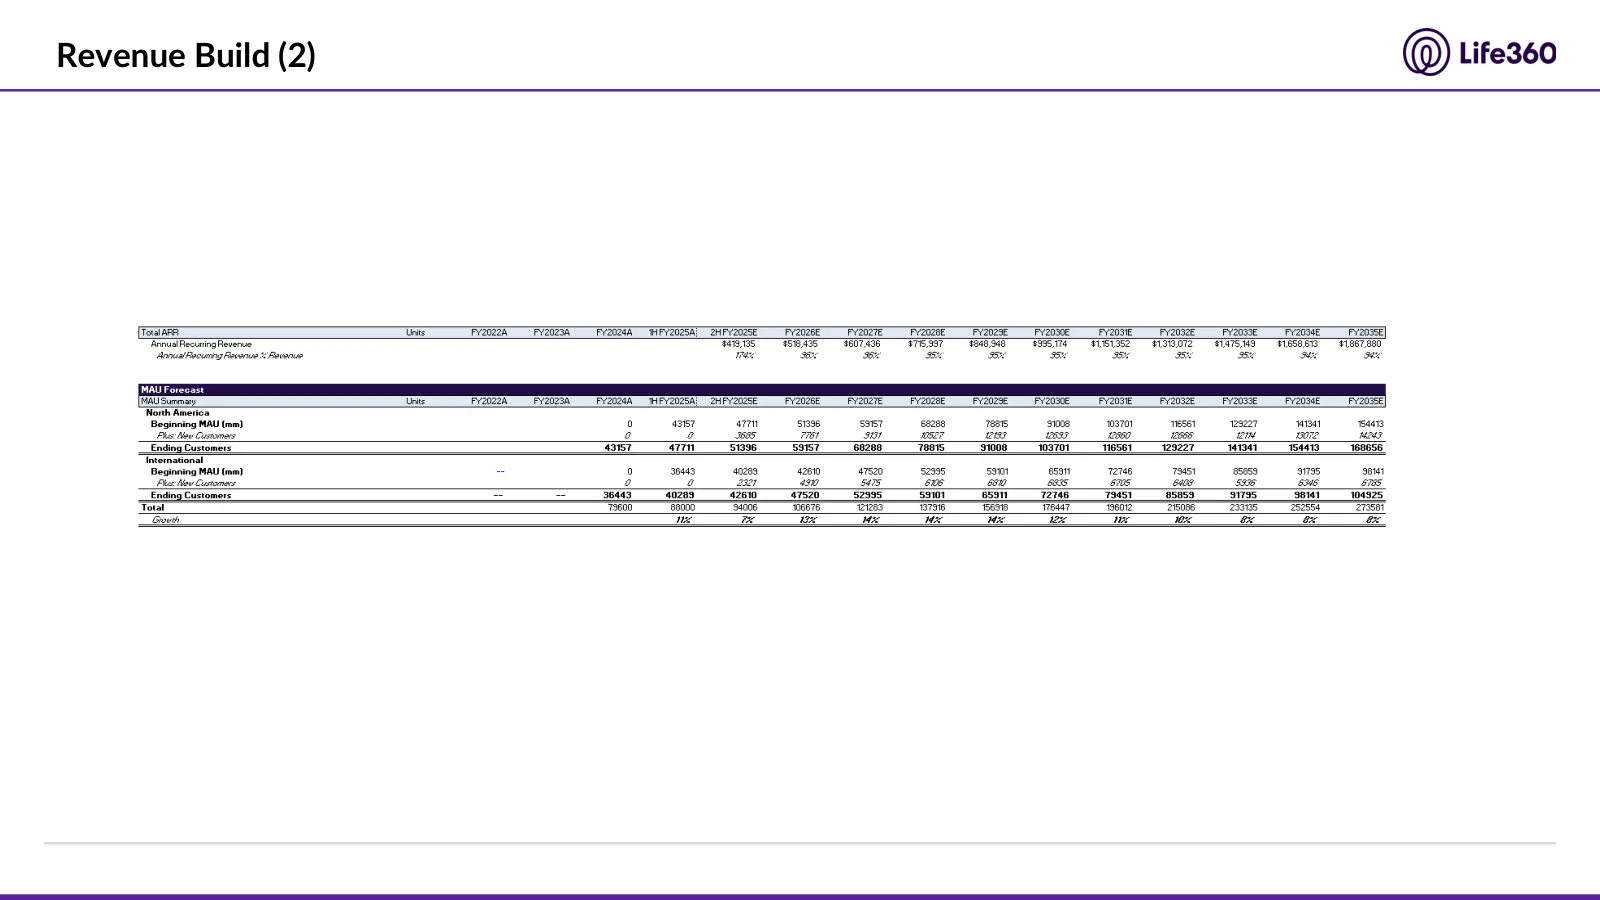
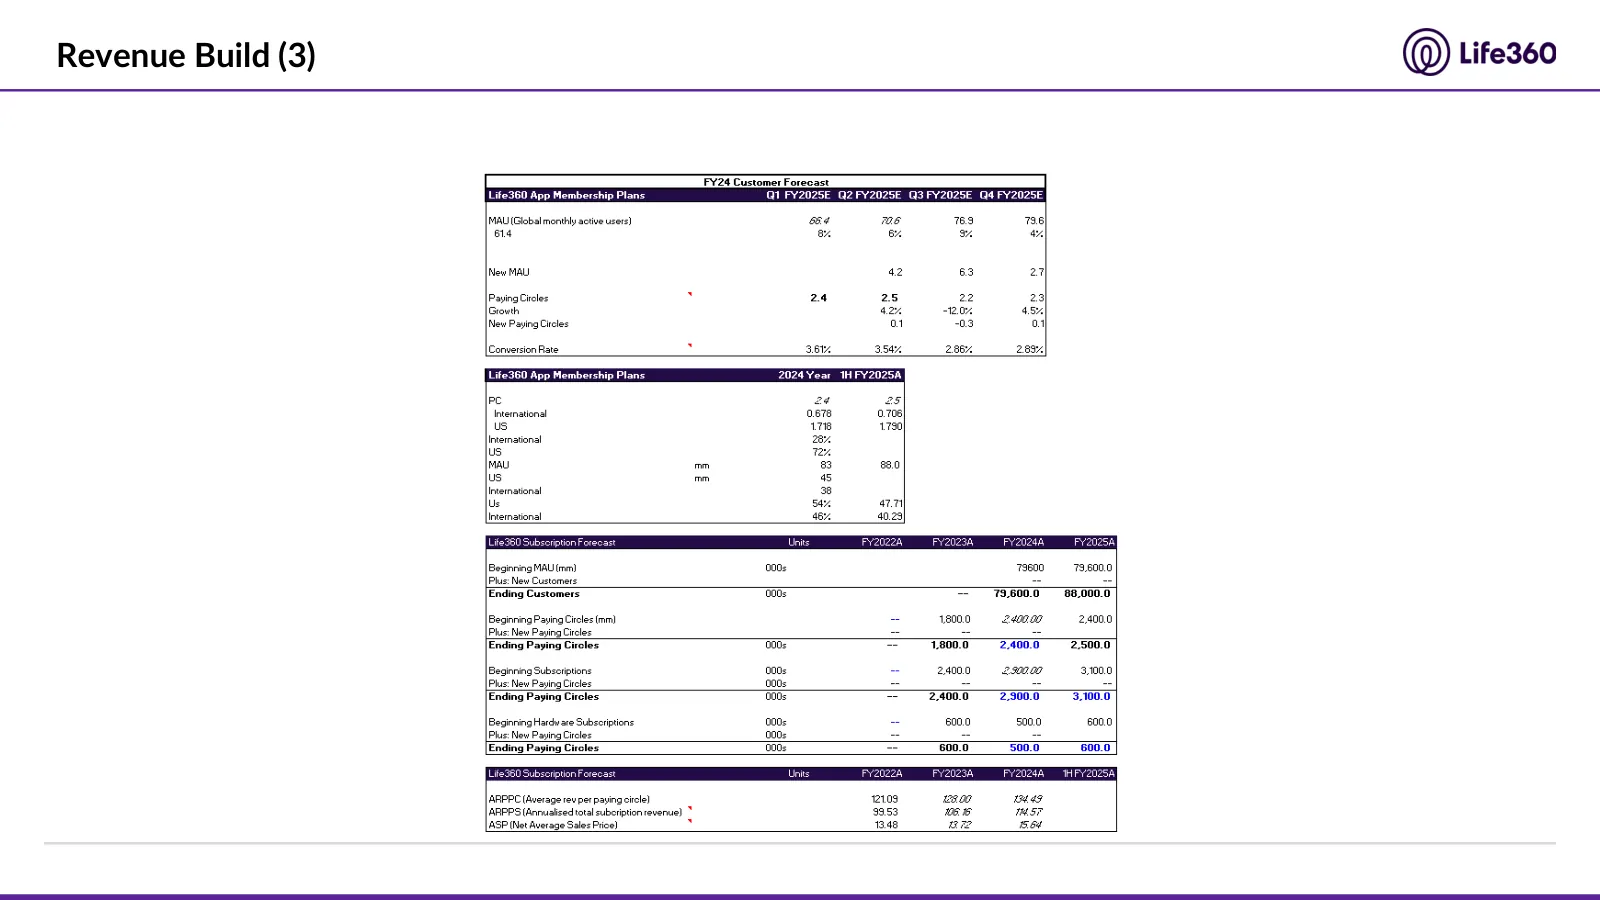
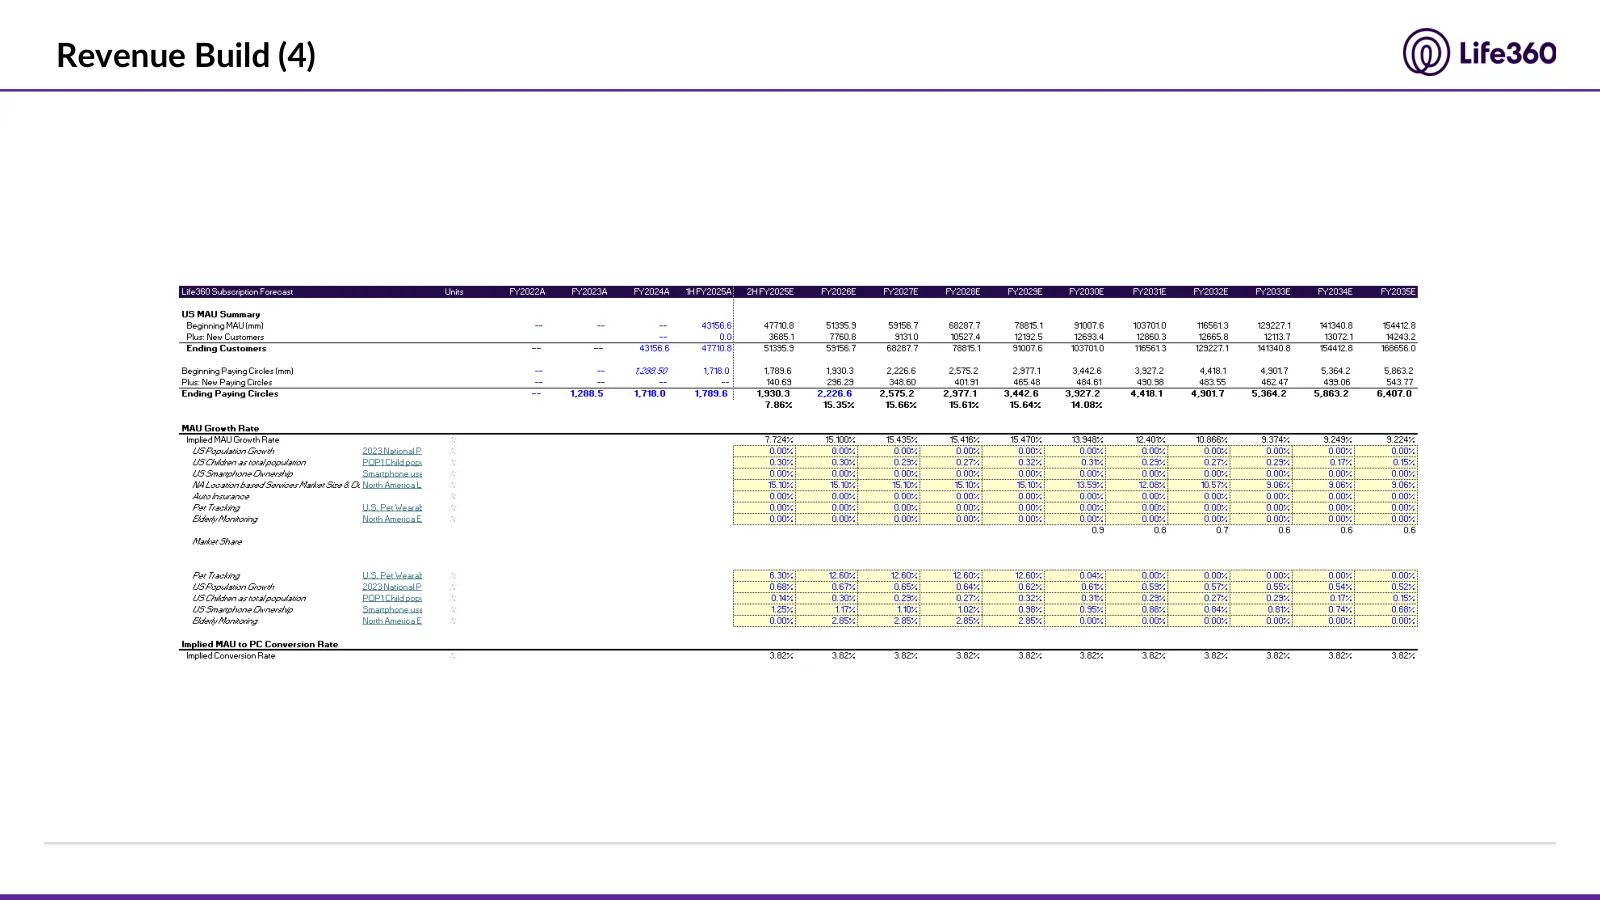
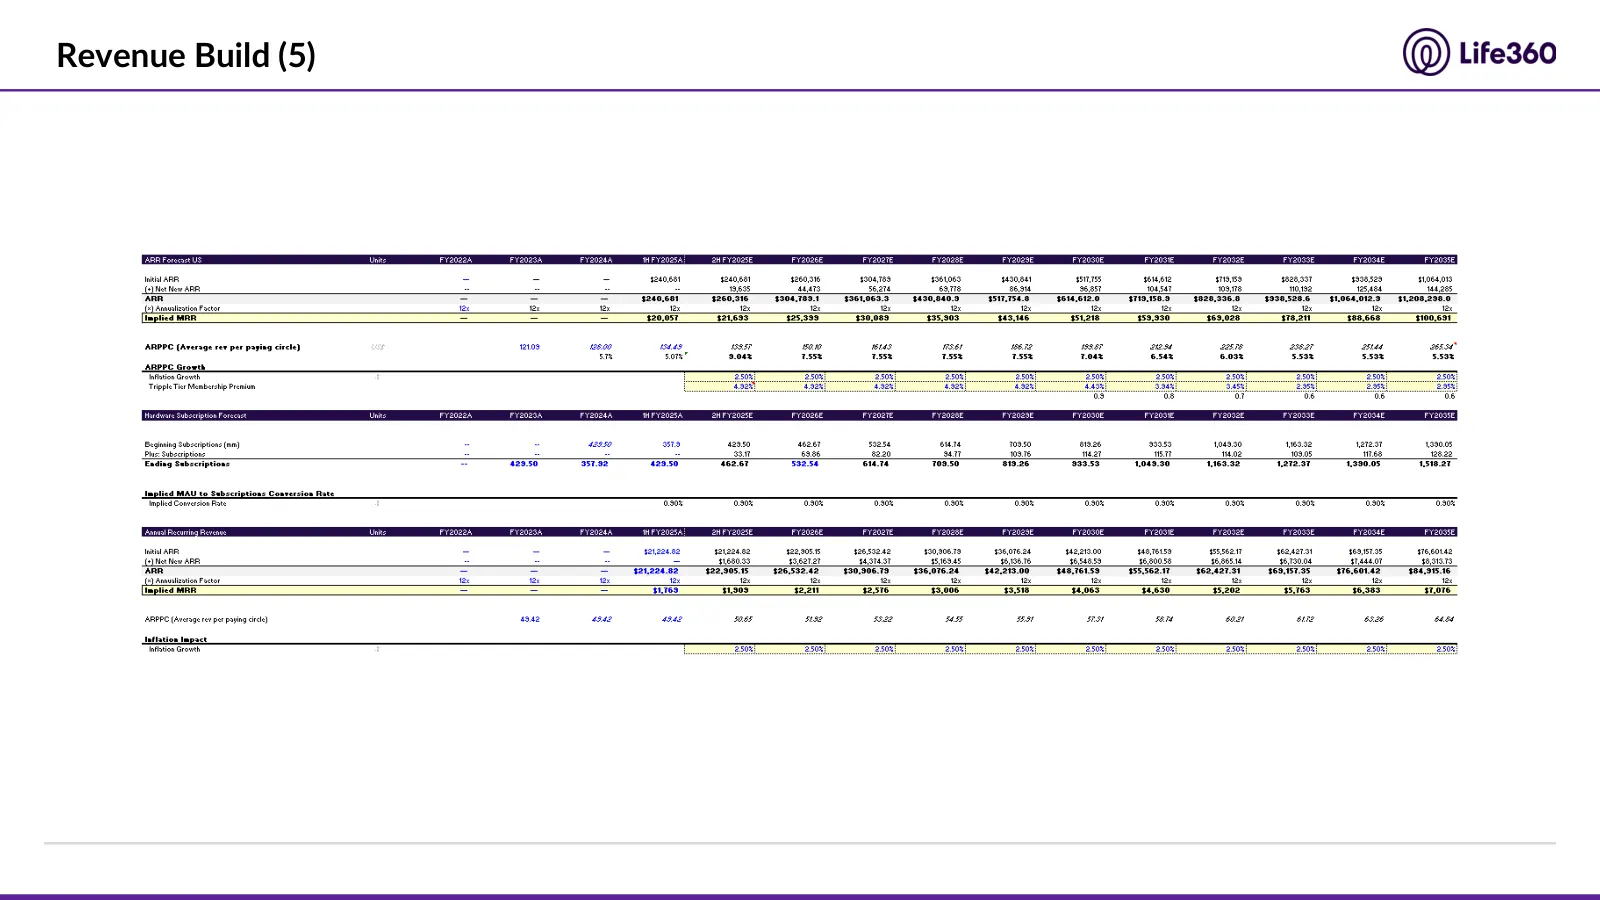
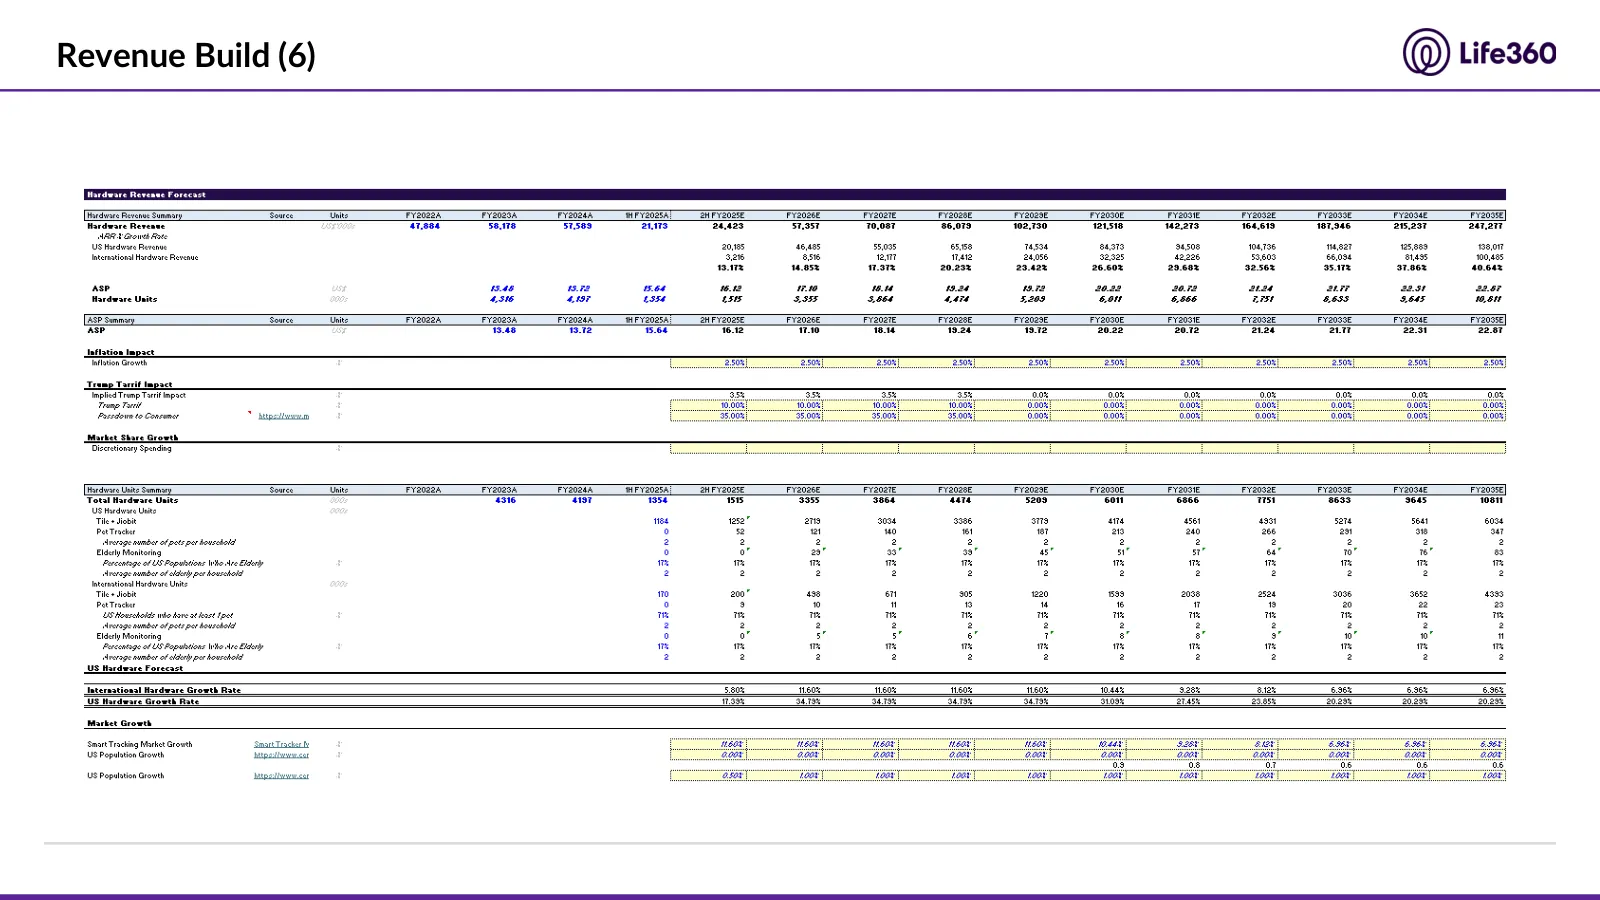
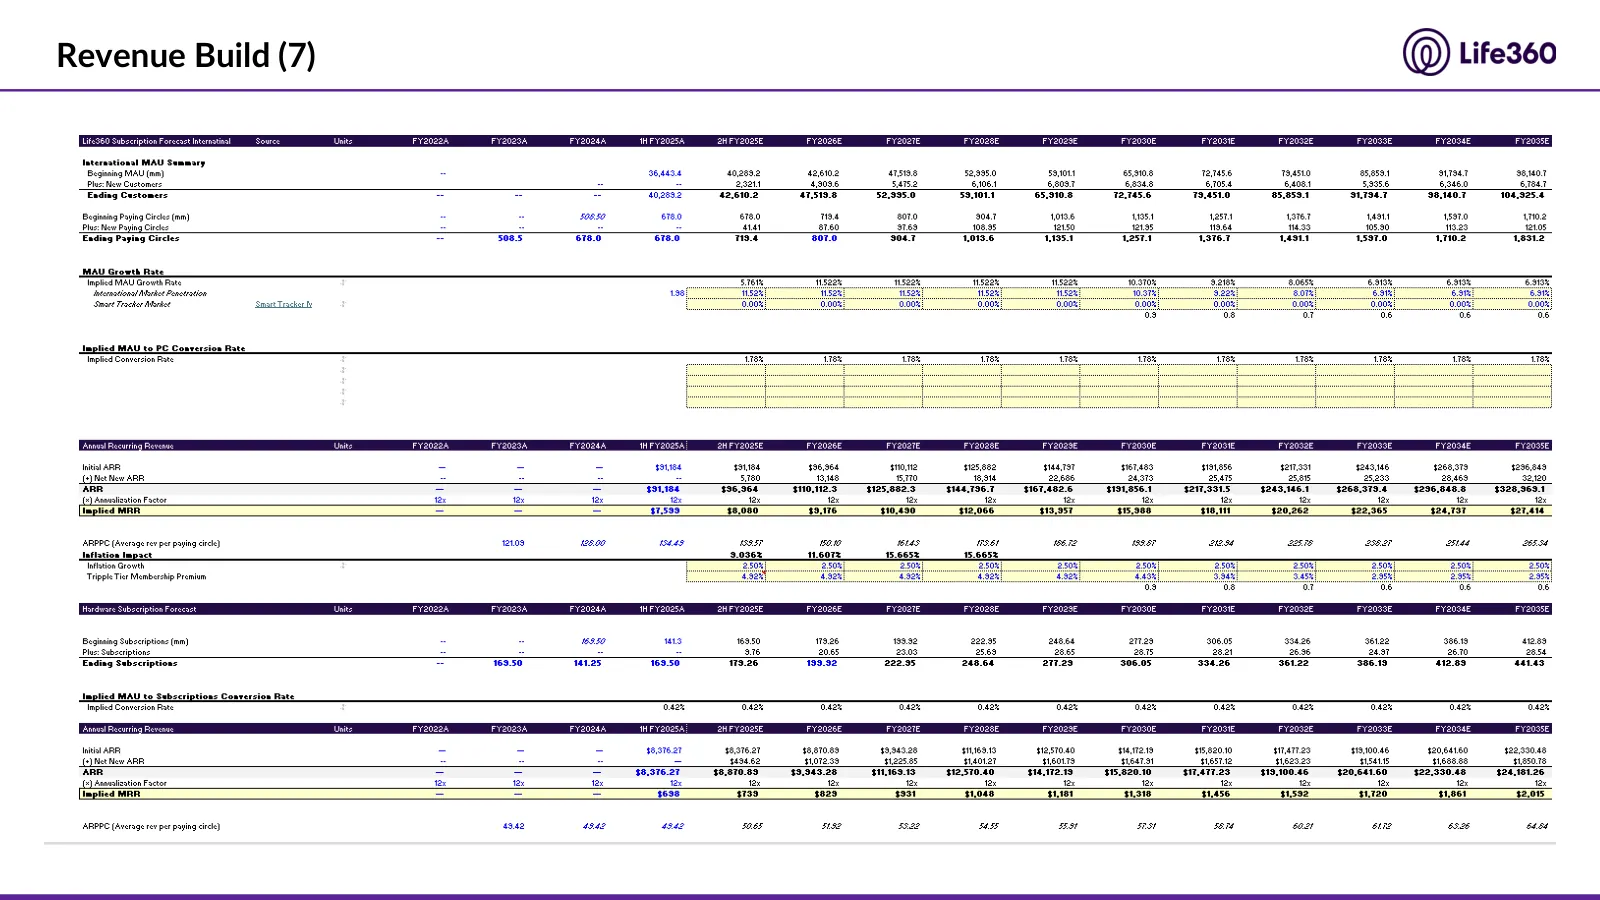
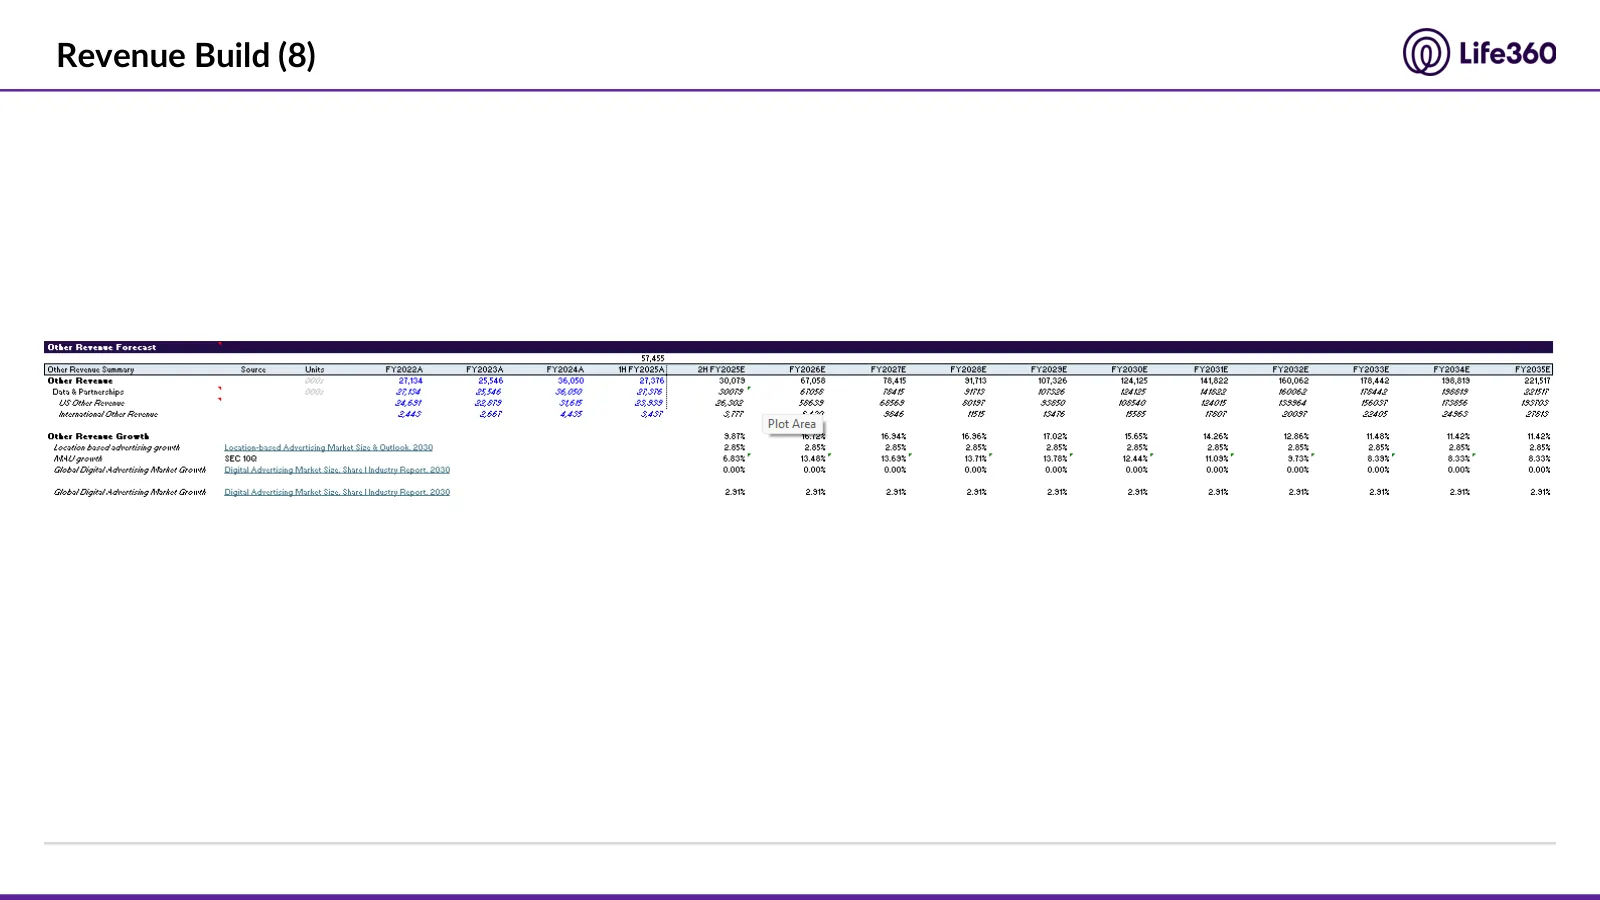
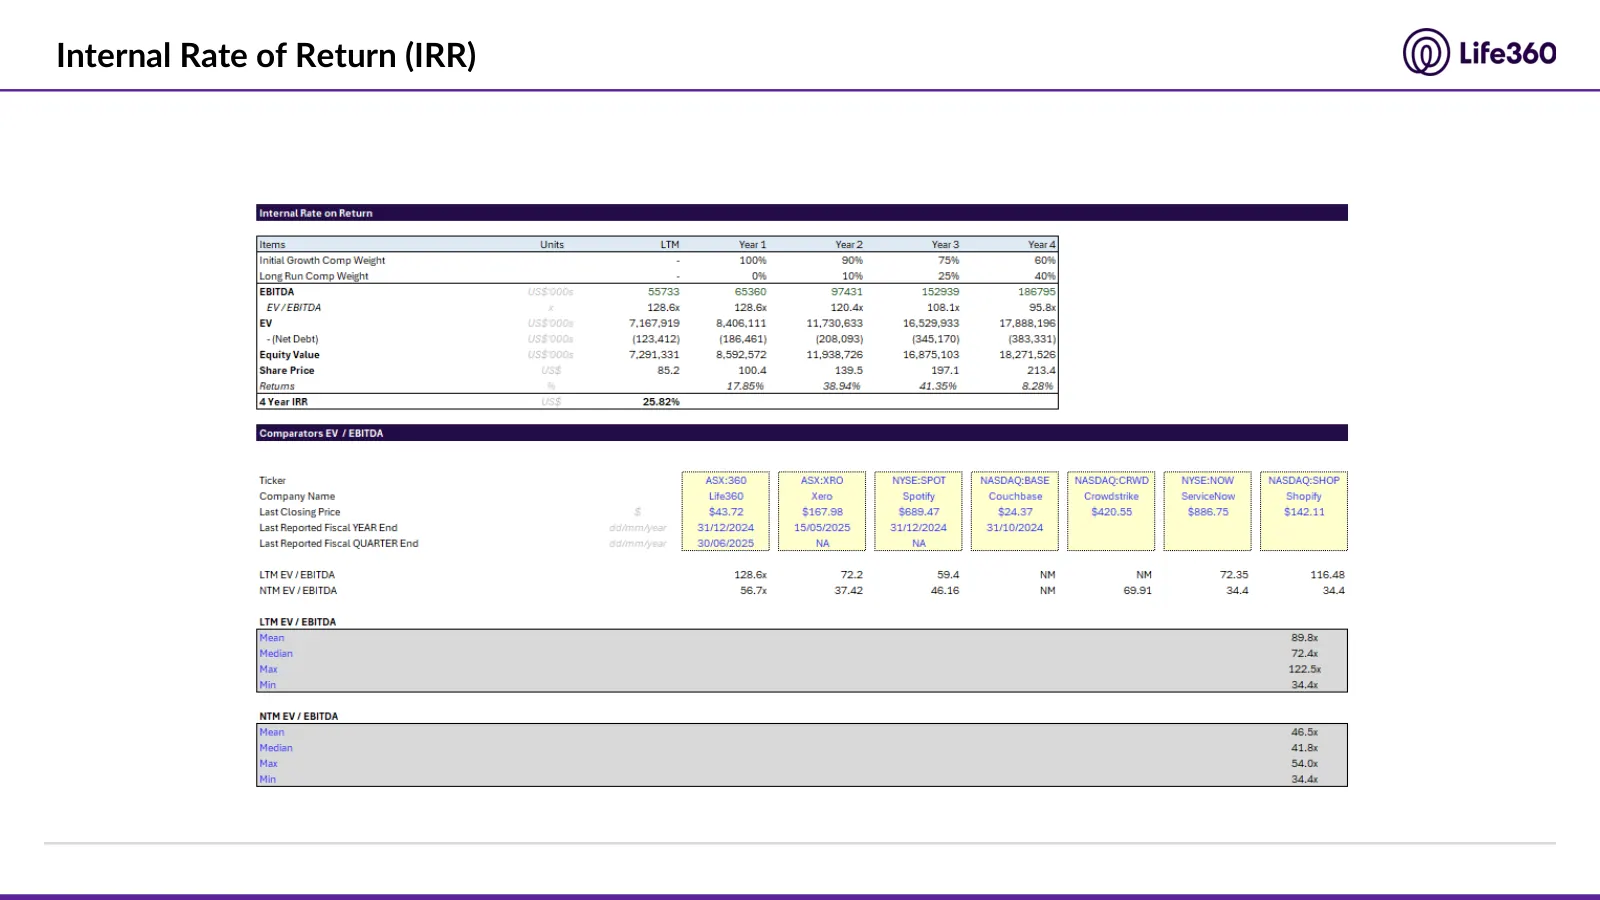
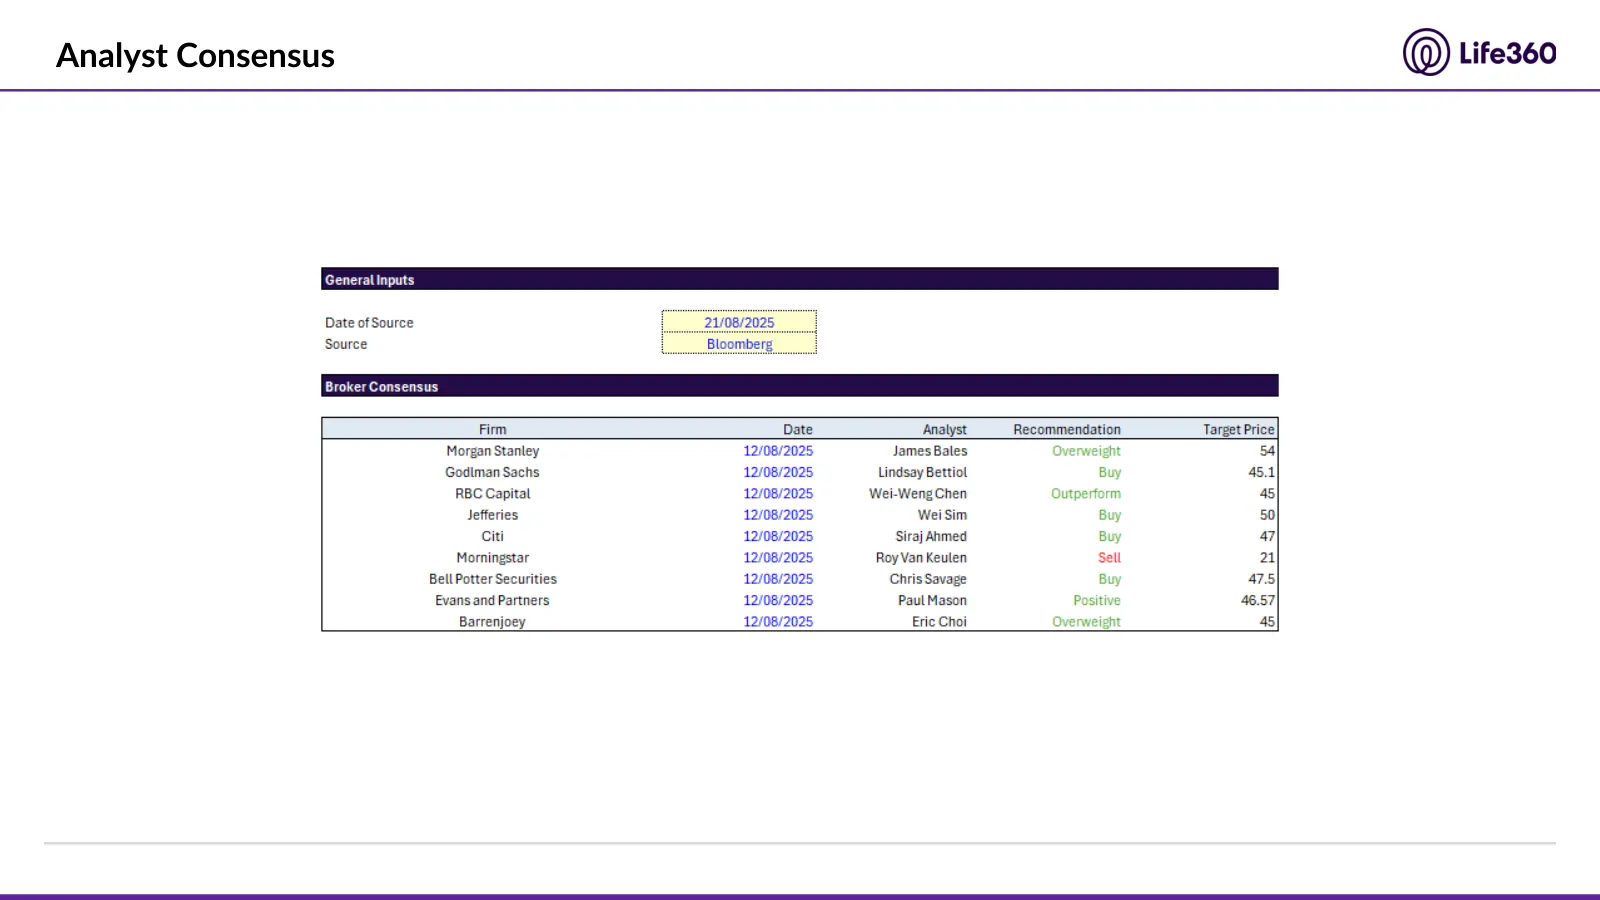
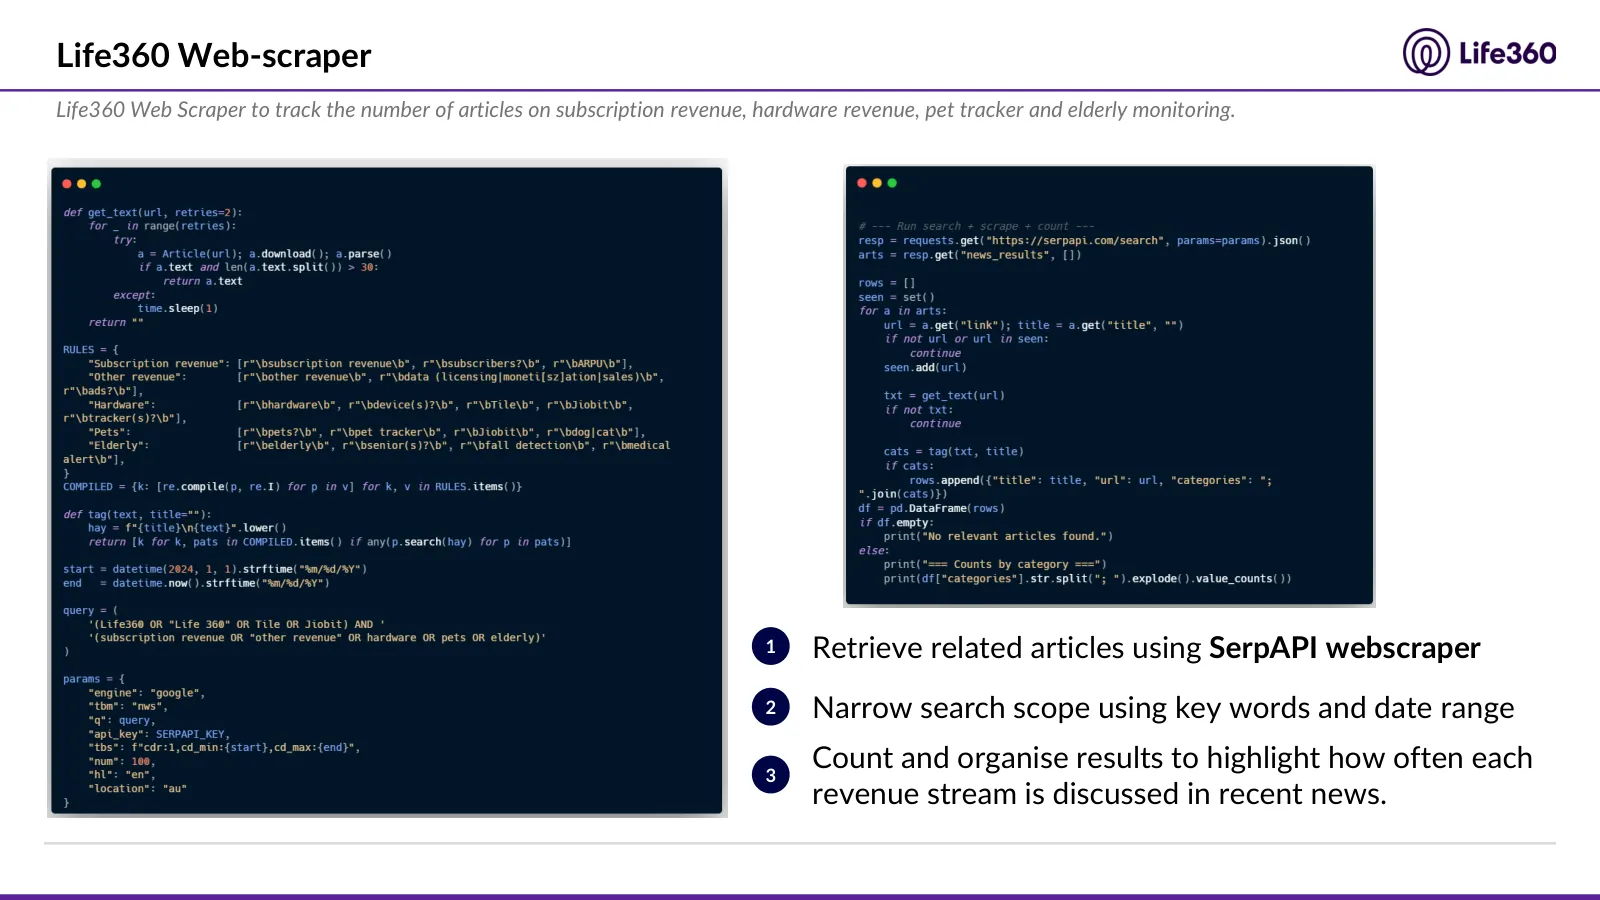
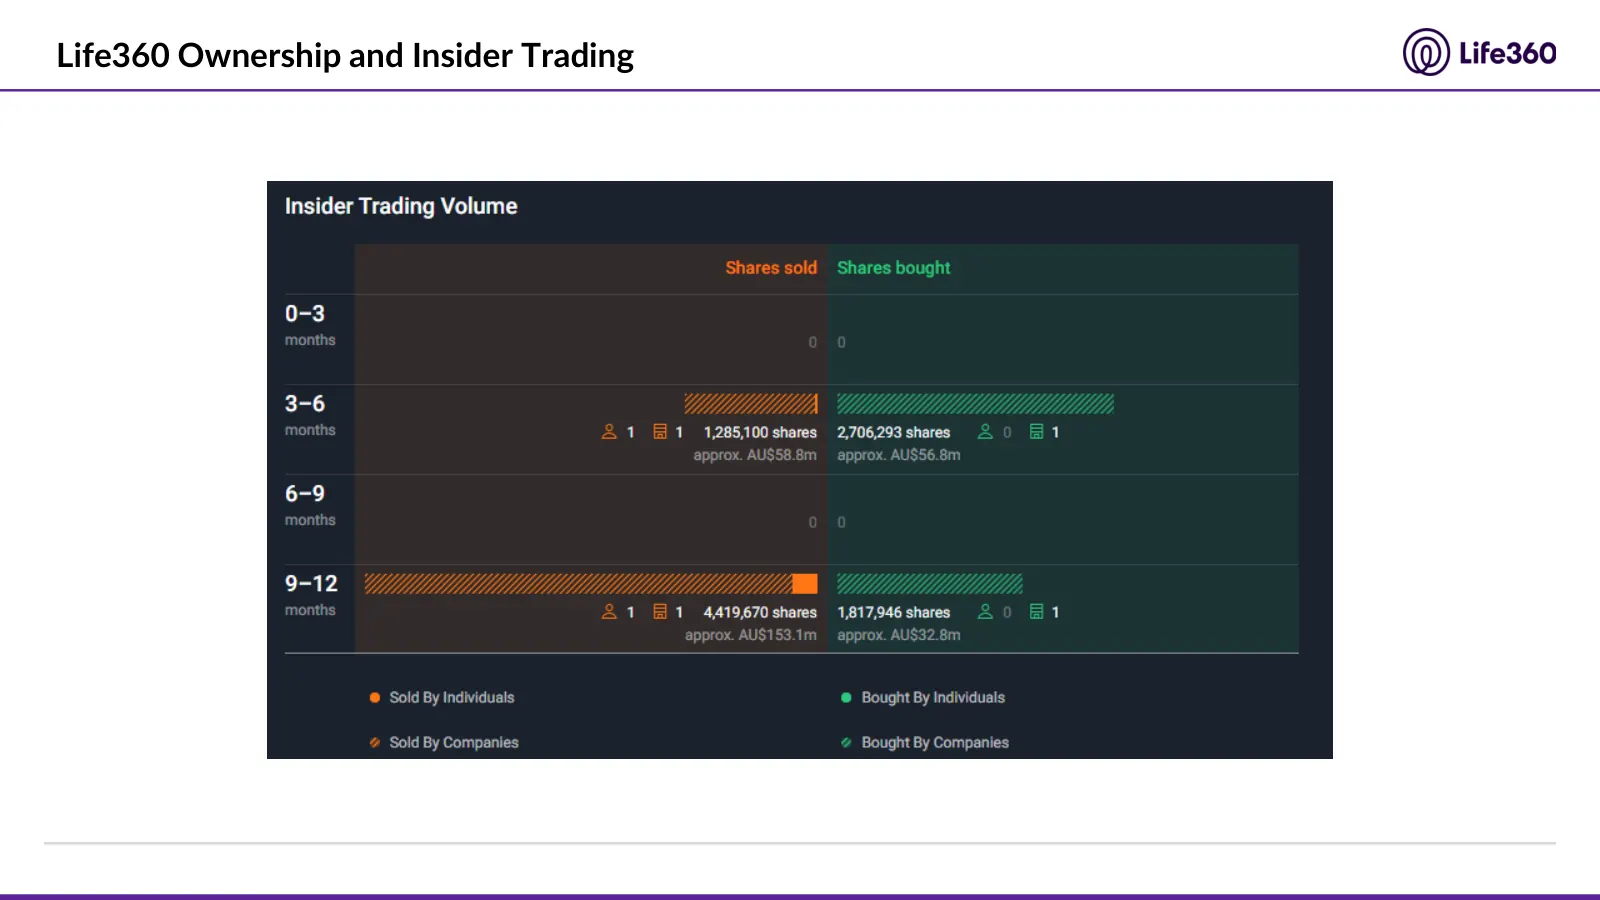
Life360: buy at A$43.72, with a A$53.63 target. August 2025, for Future IM/Pact. A recommendation for a growth fund's portfolio. The market was extrapolating near-term weakness and missing the growth in subscriptions and hardware. Team of four, as PIC Capital.
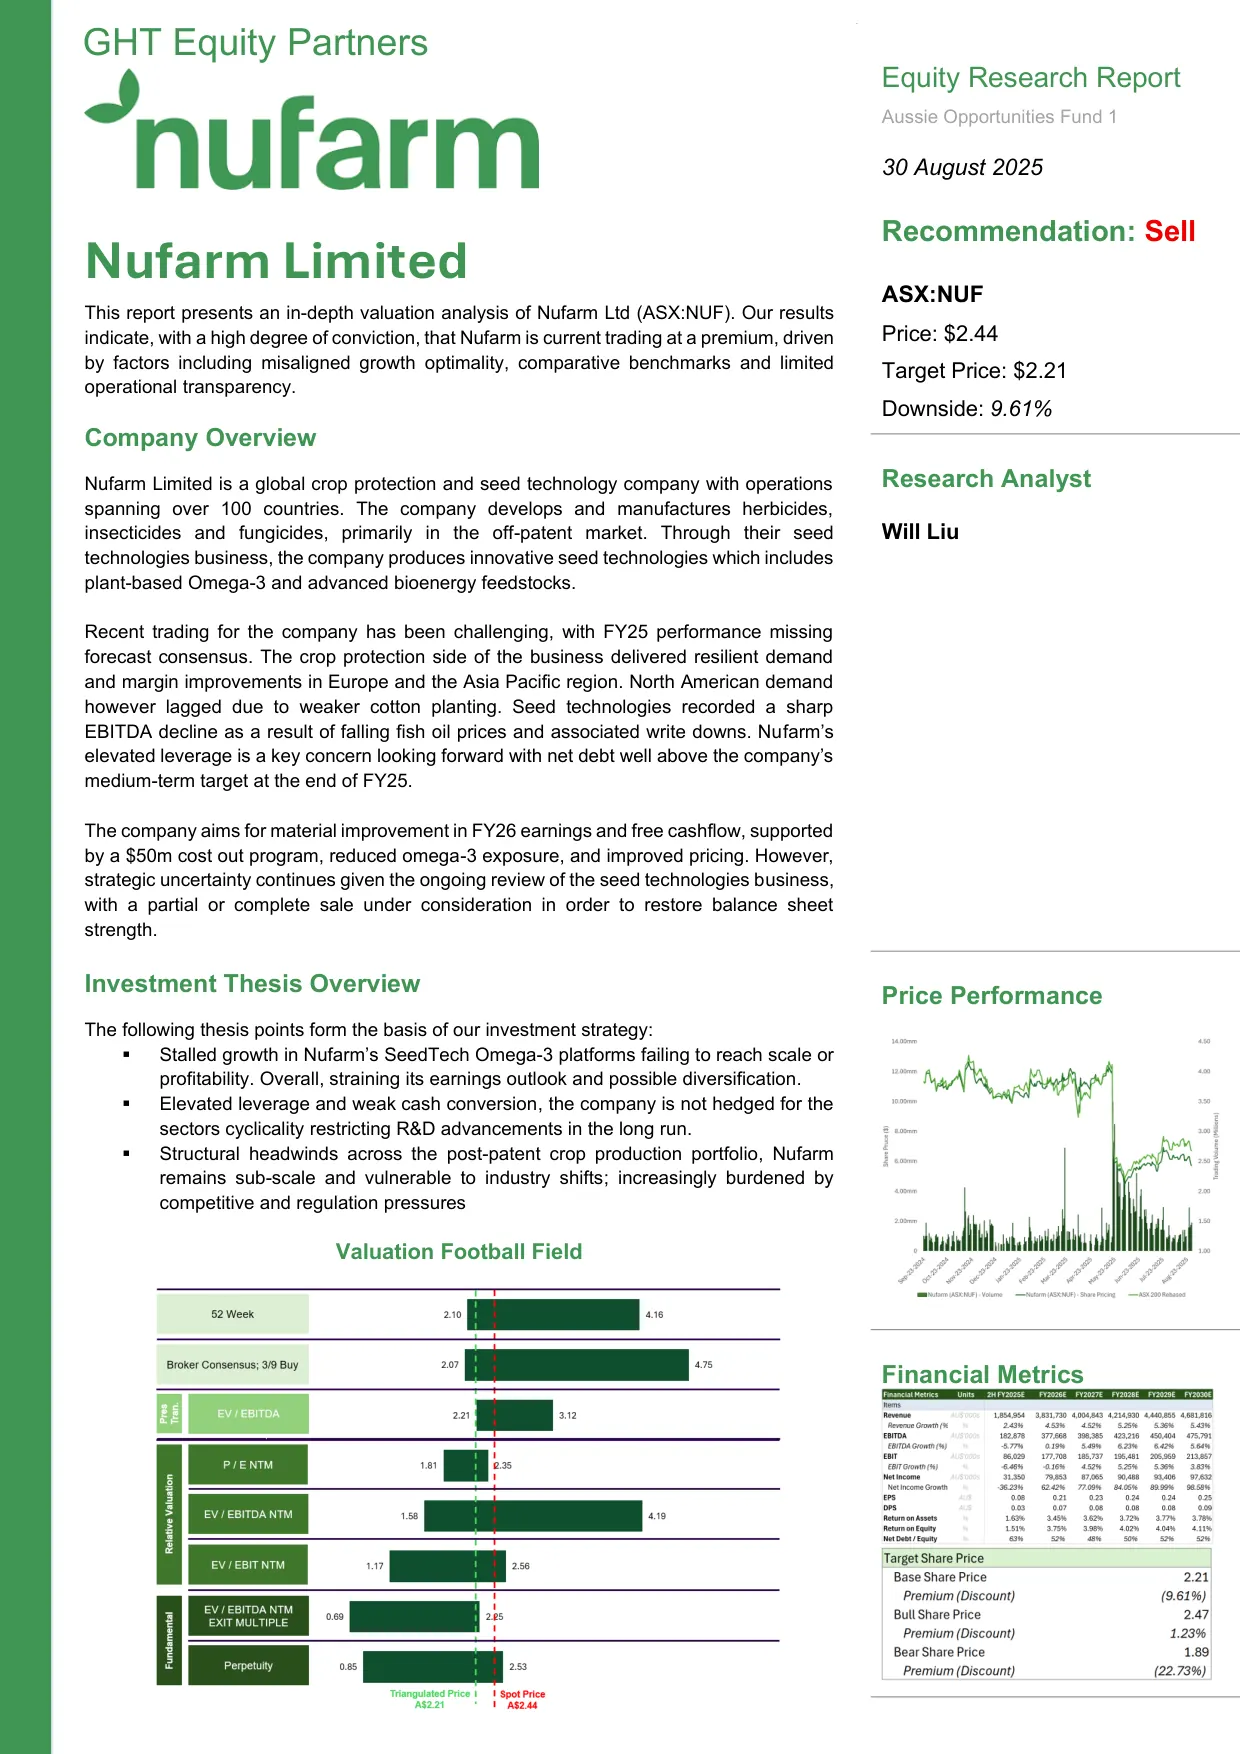
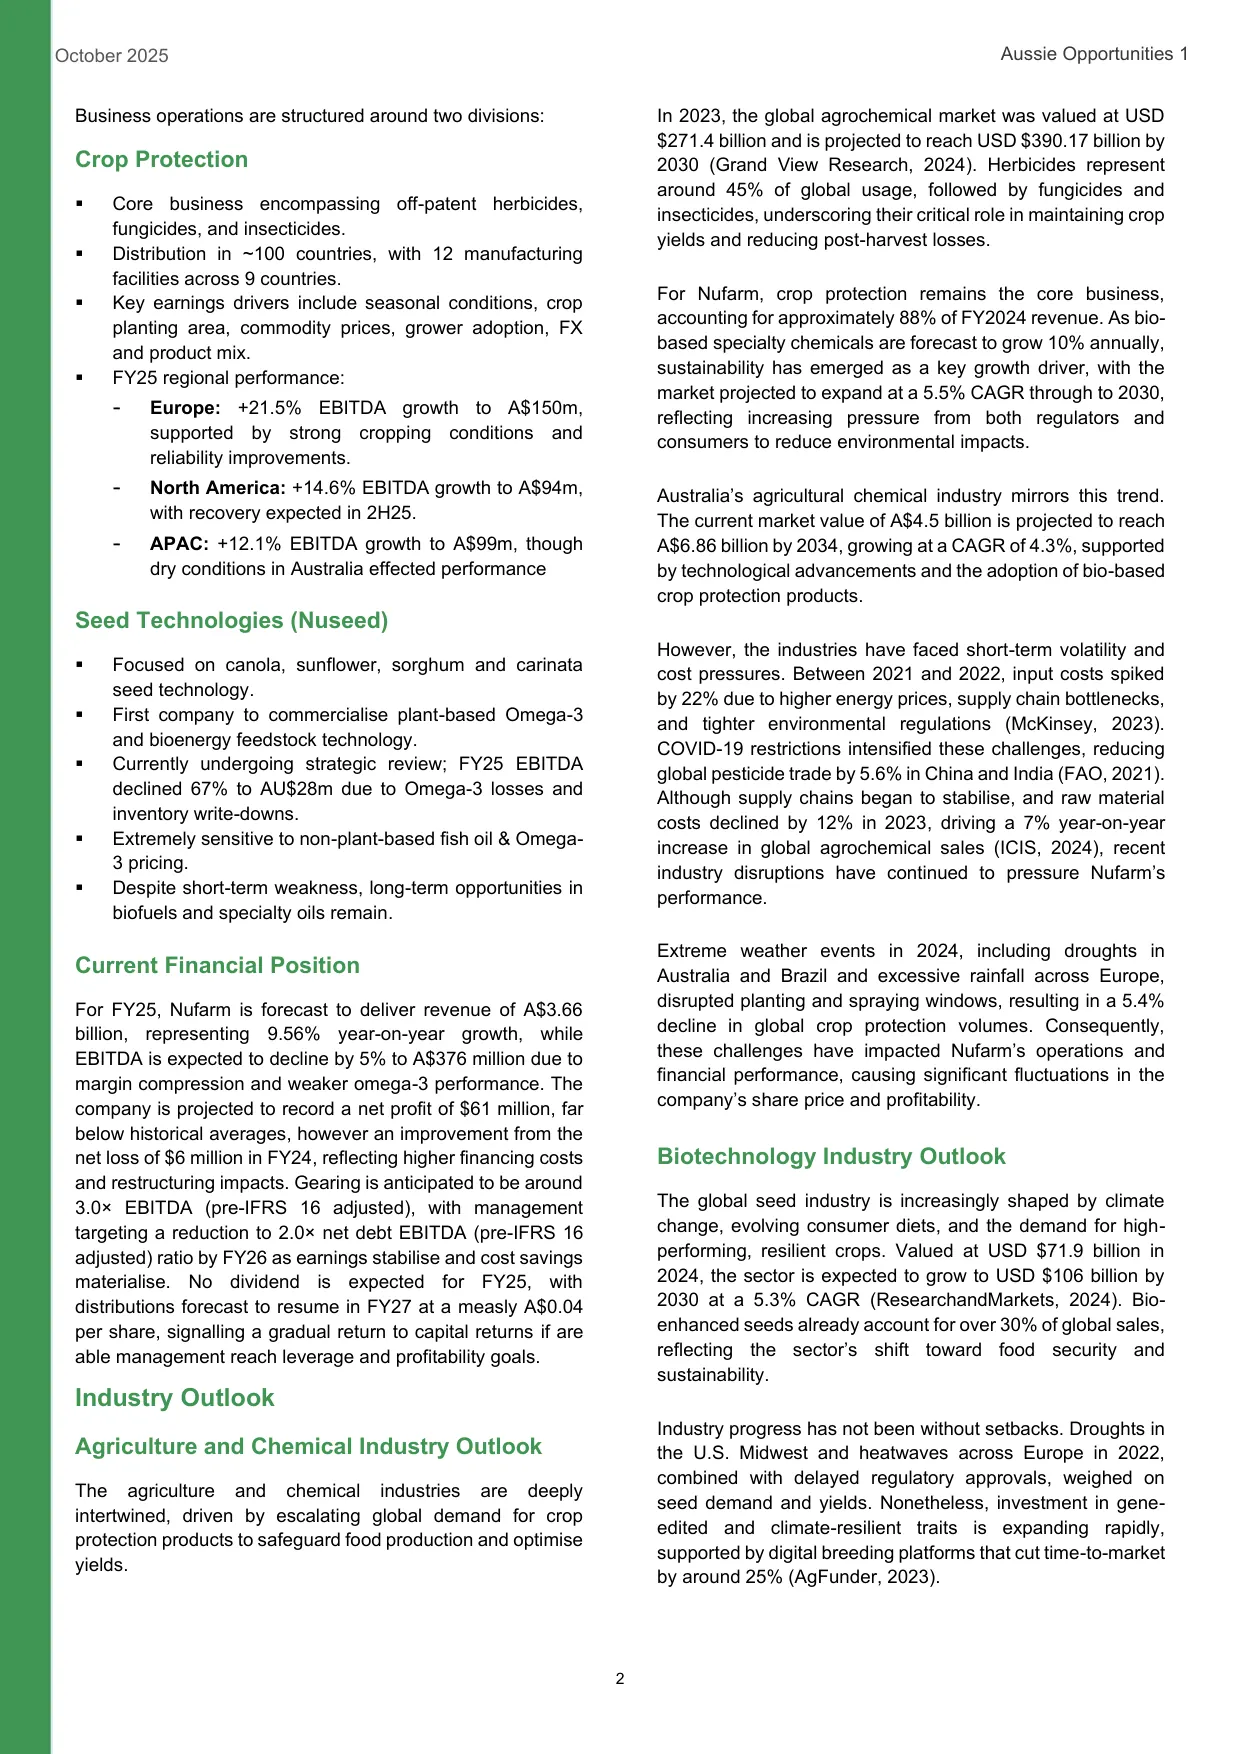
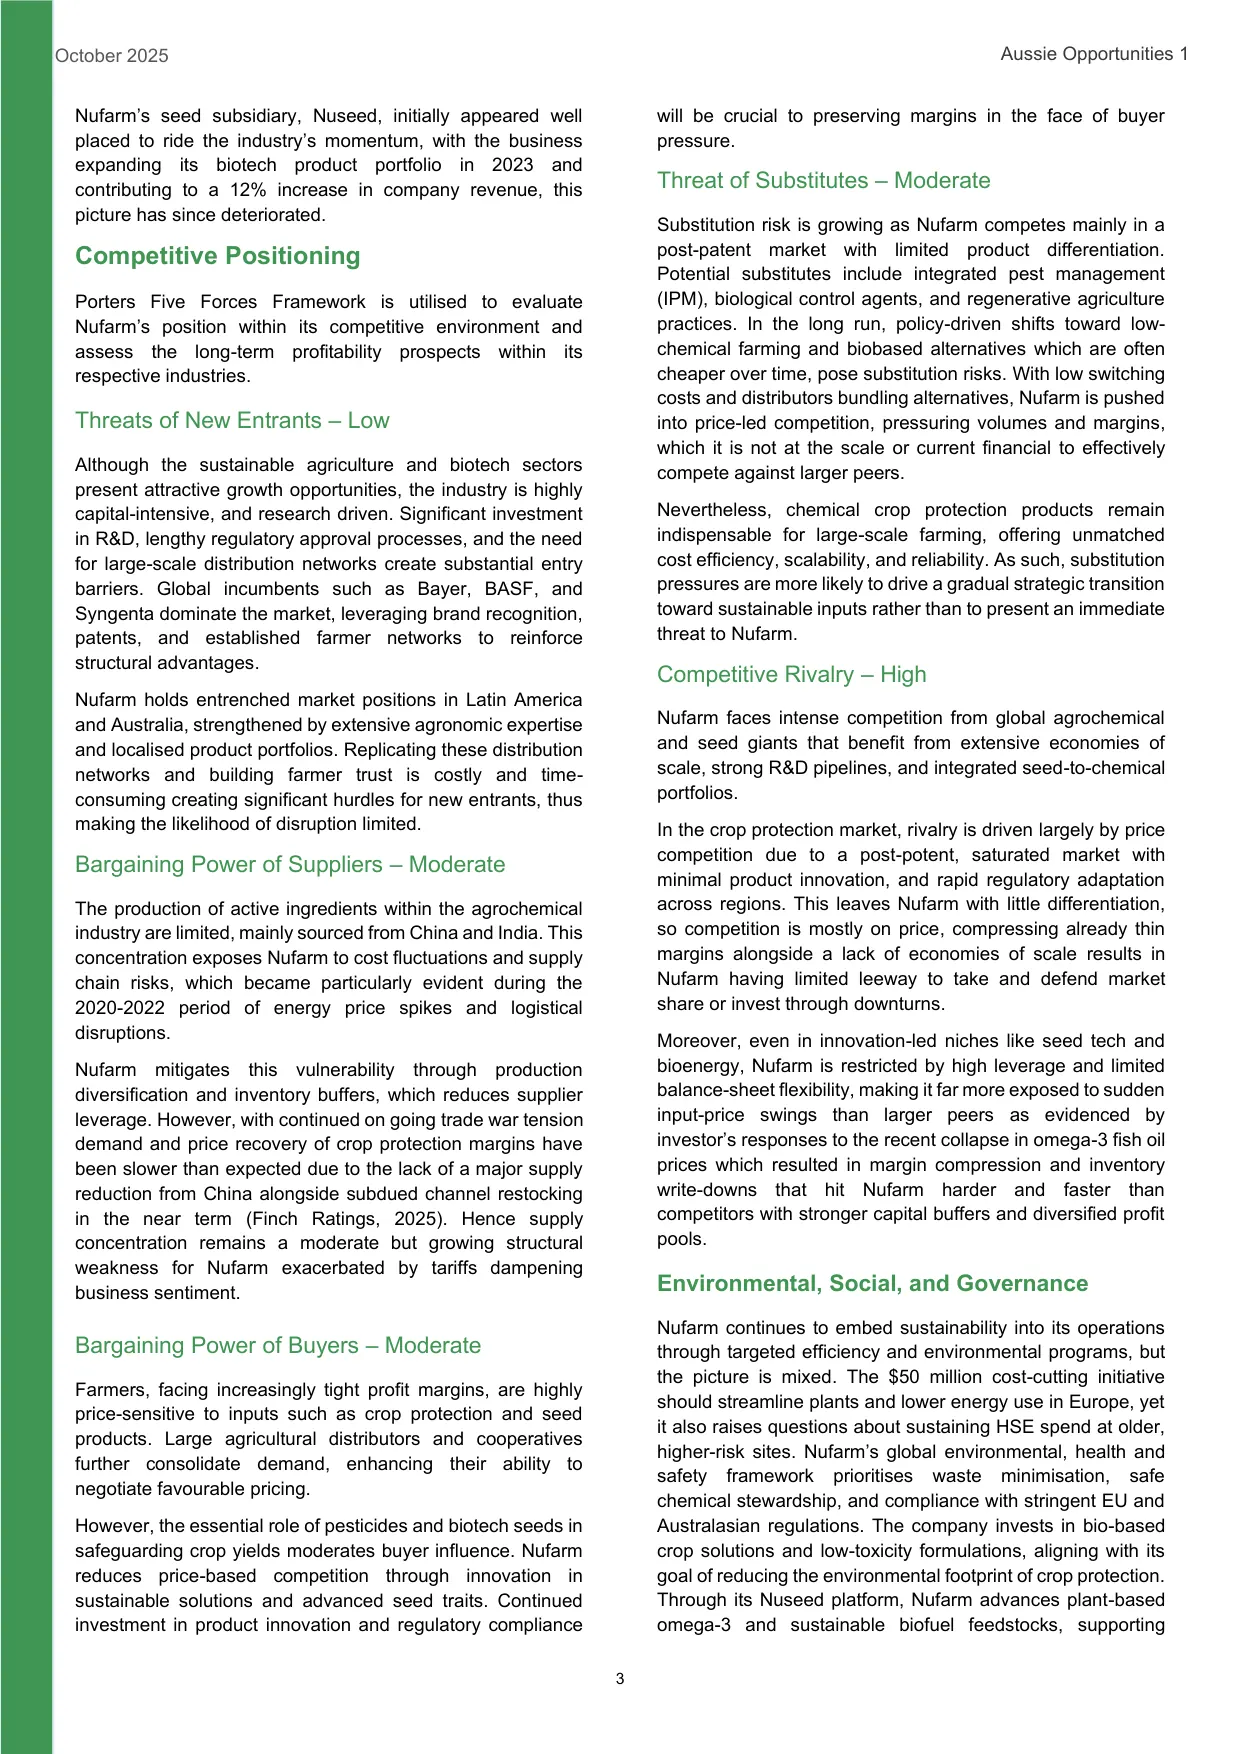
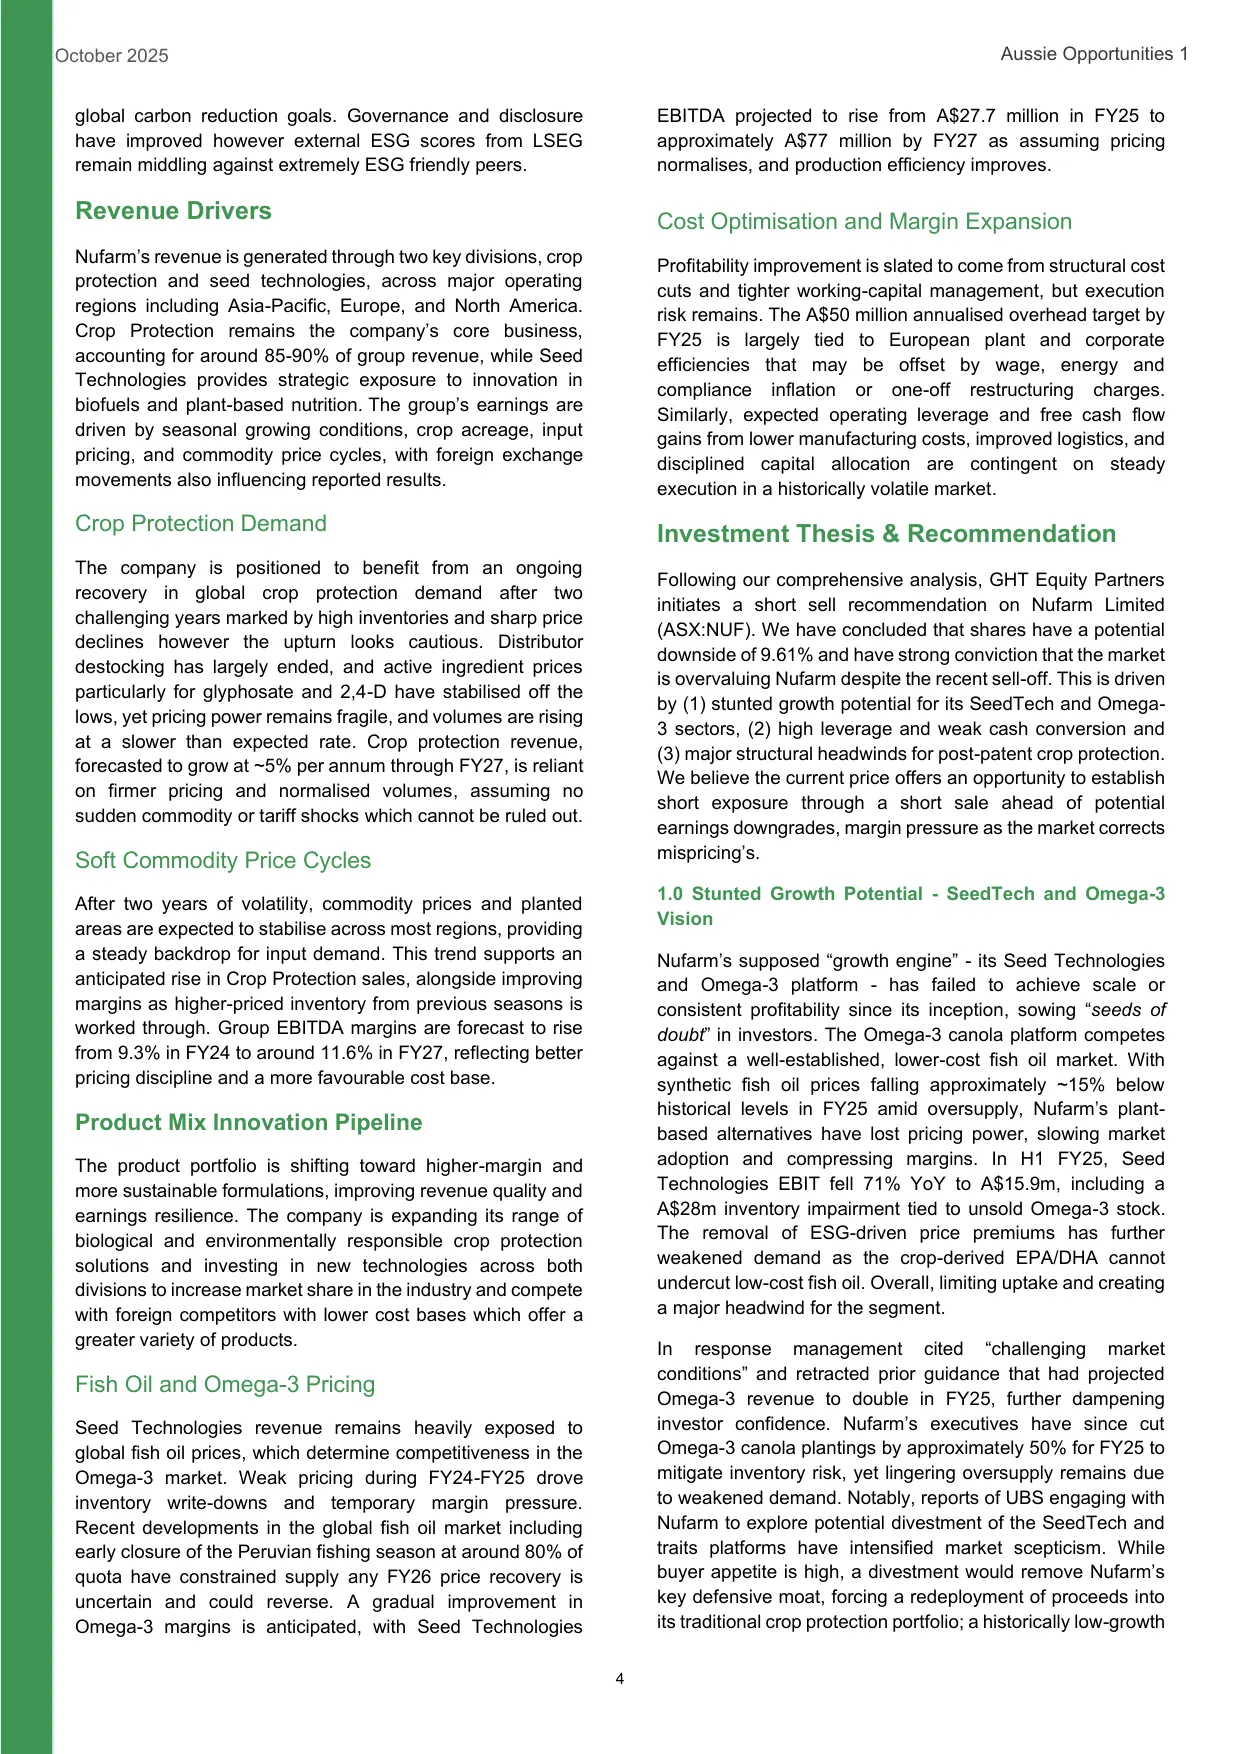
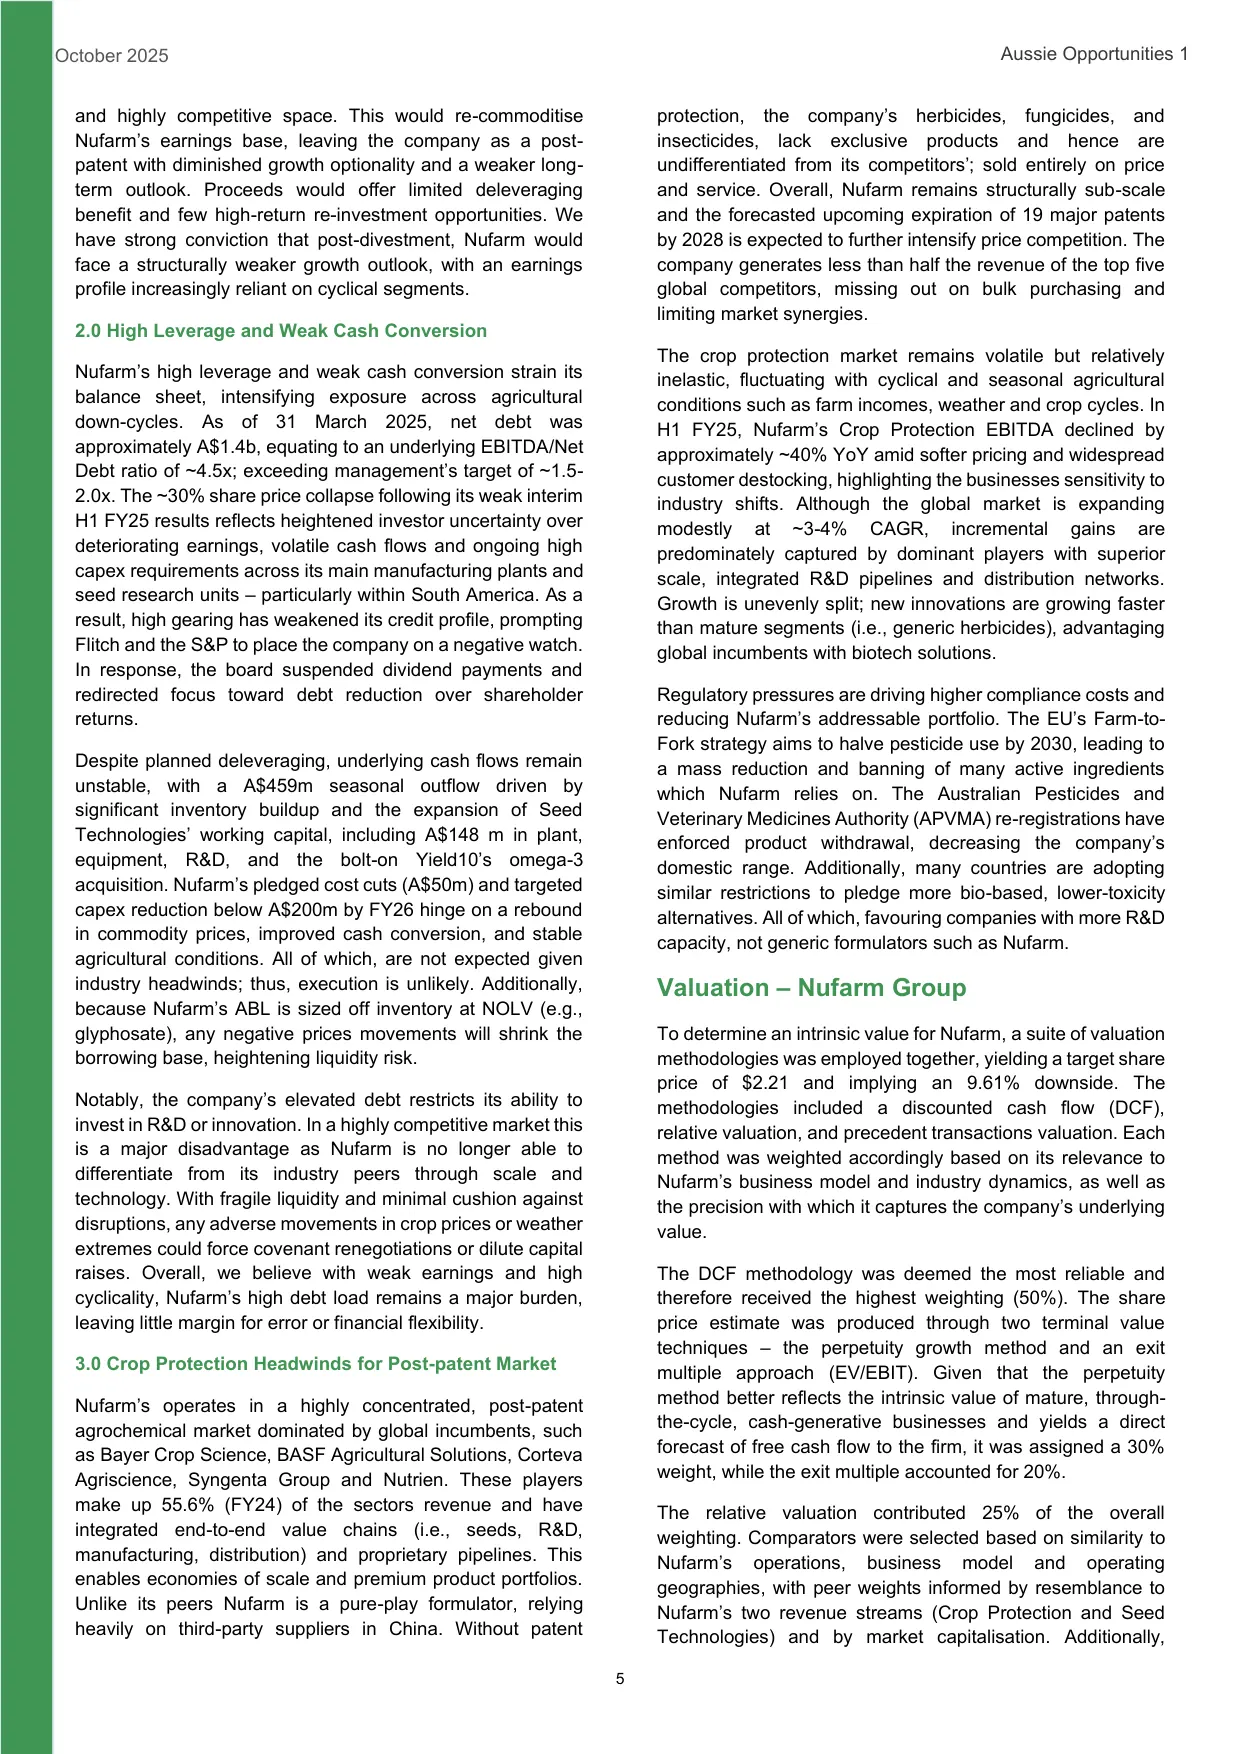
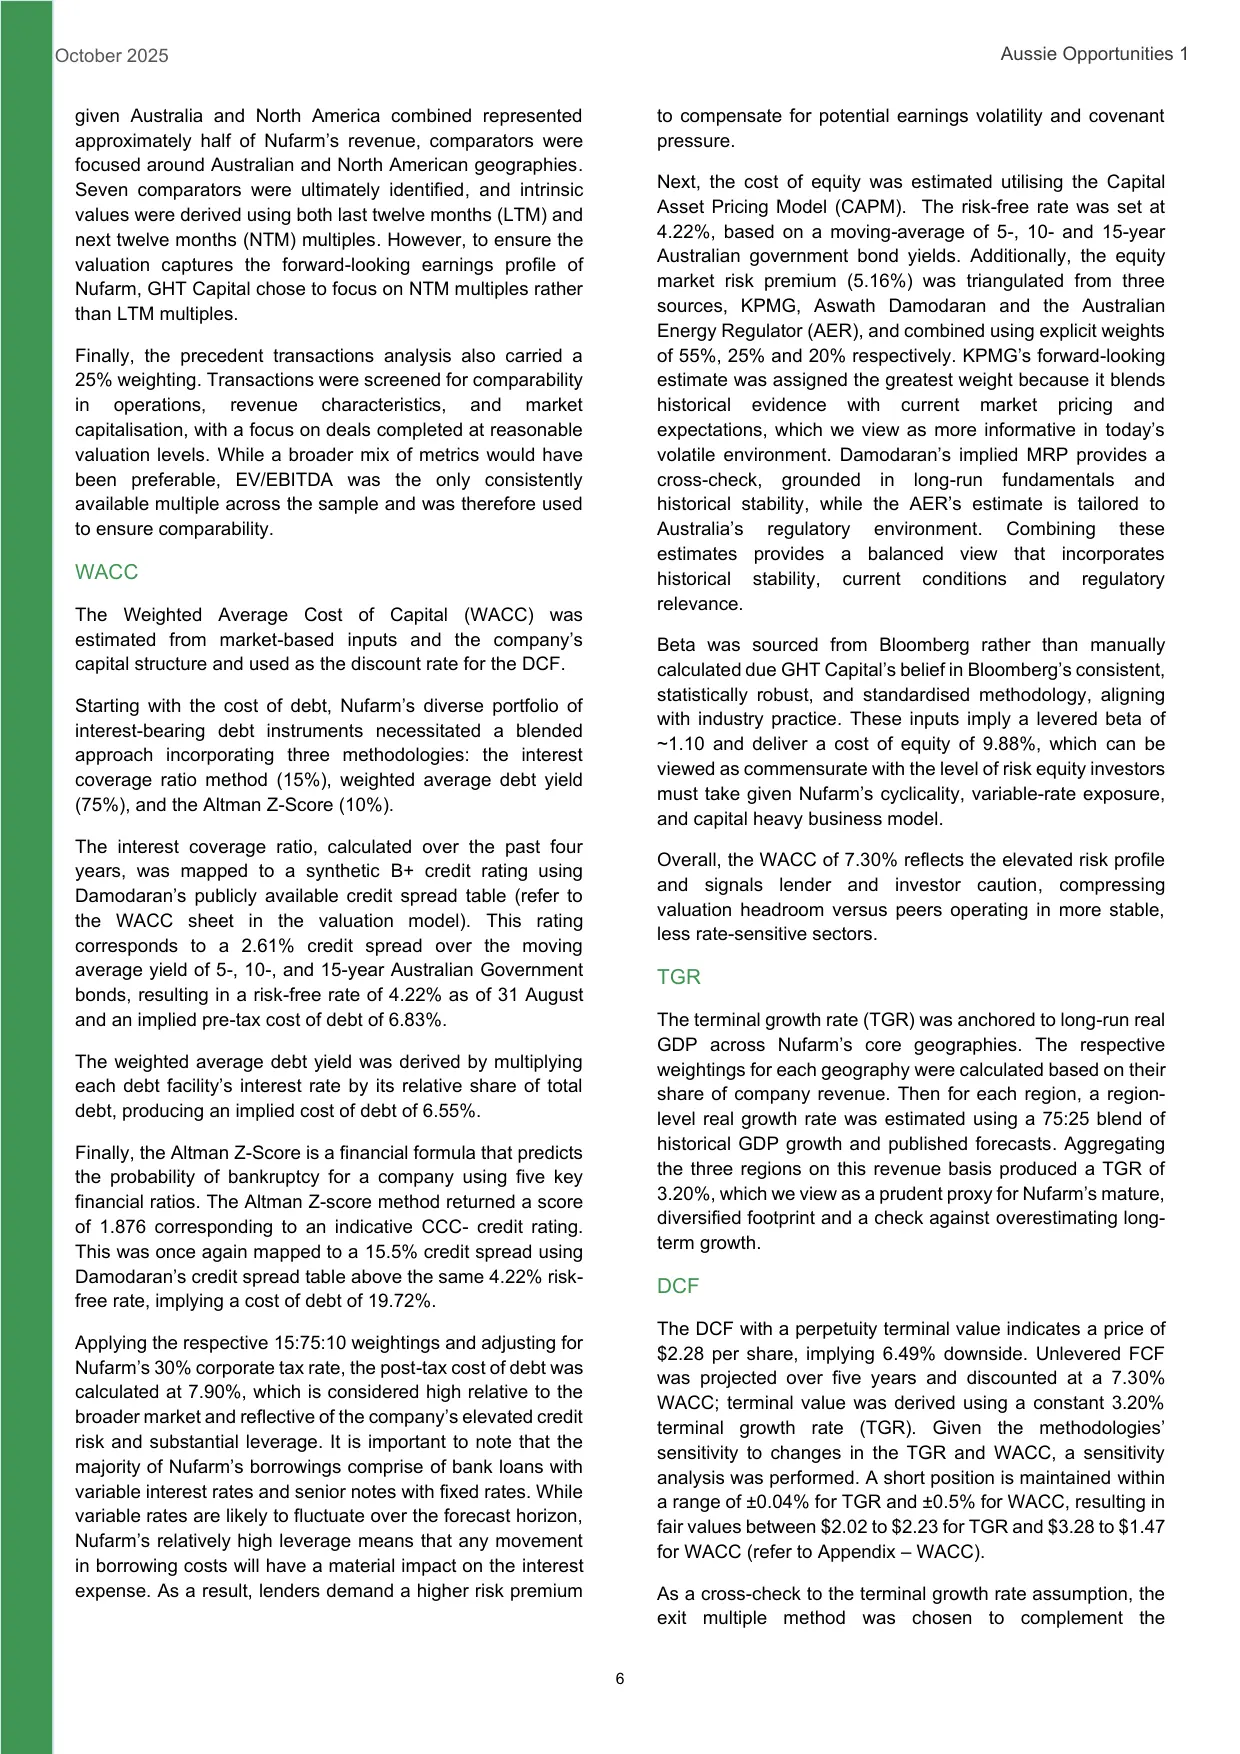
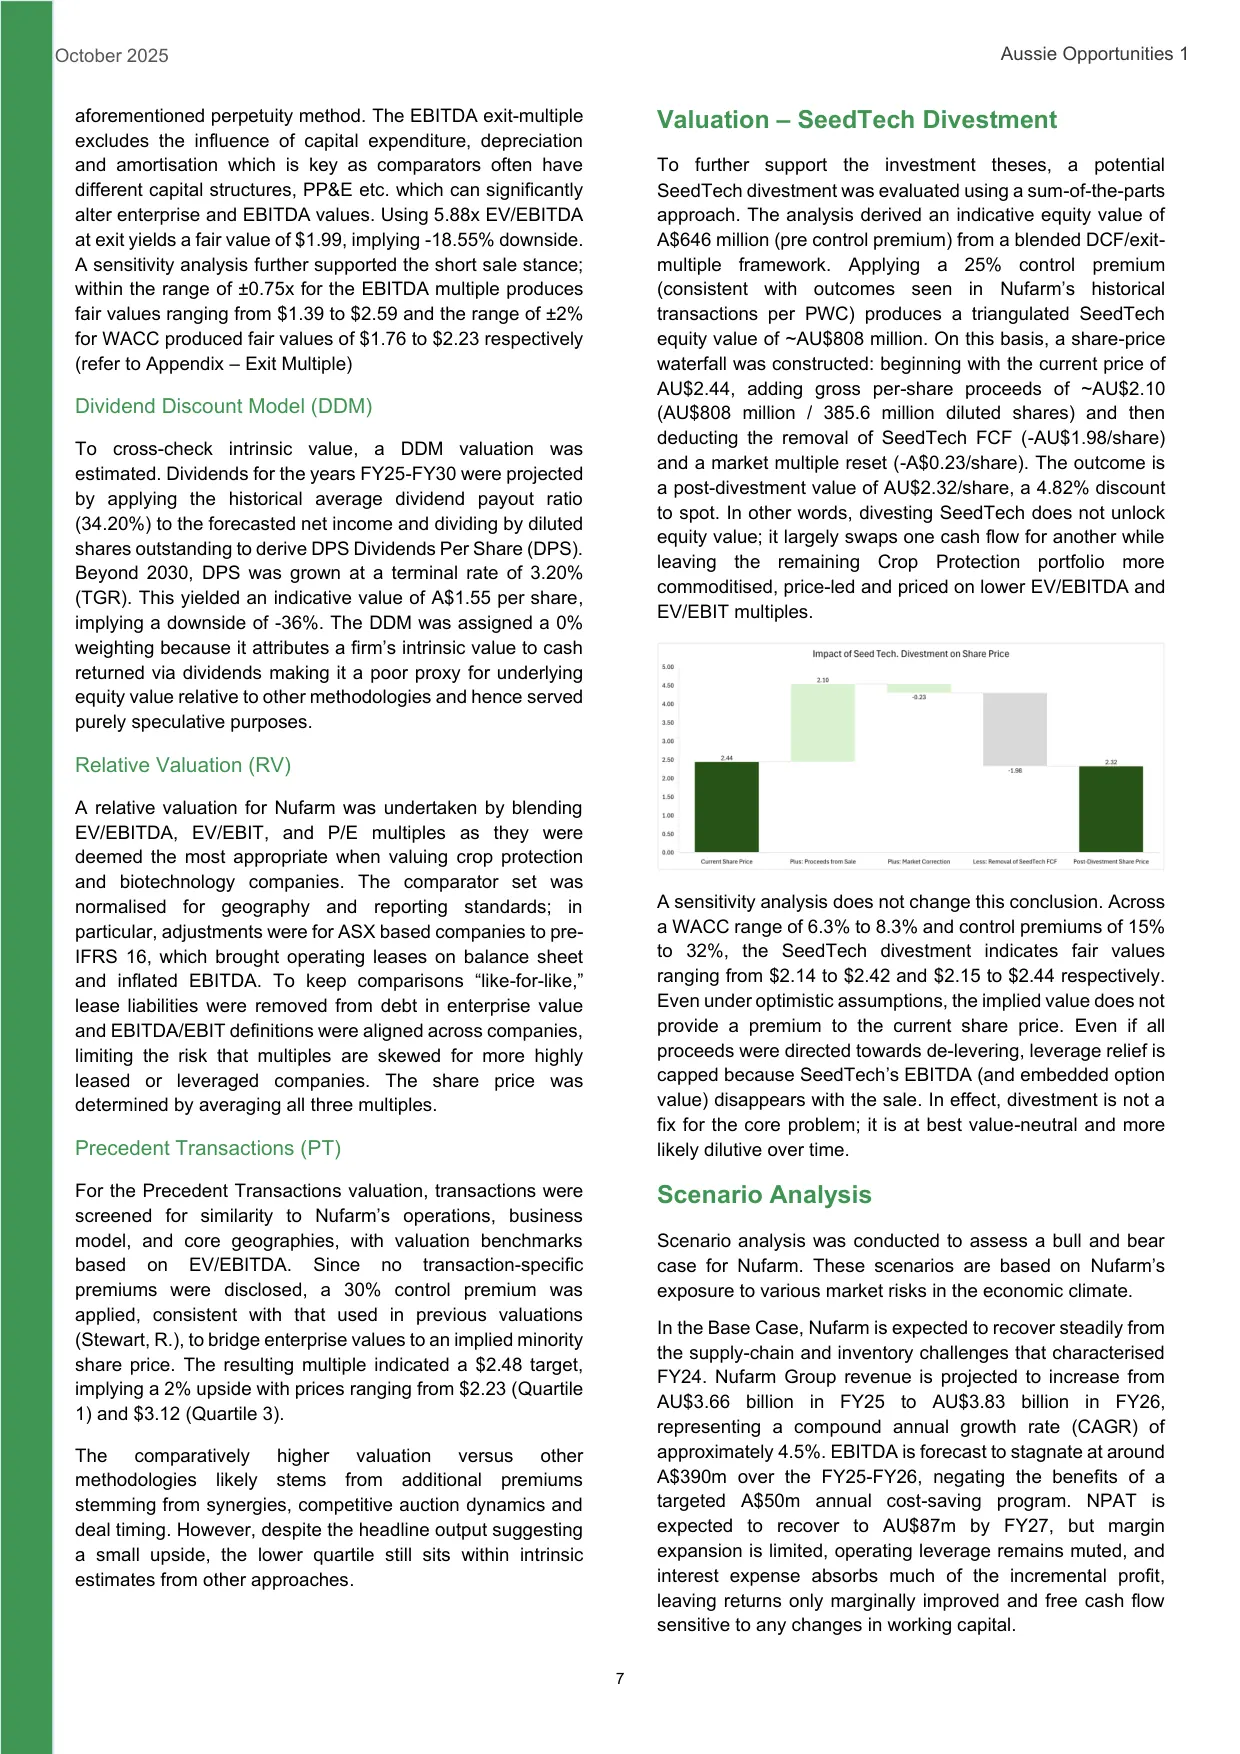
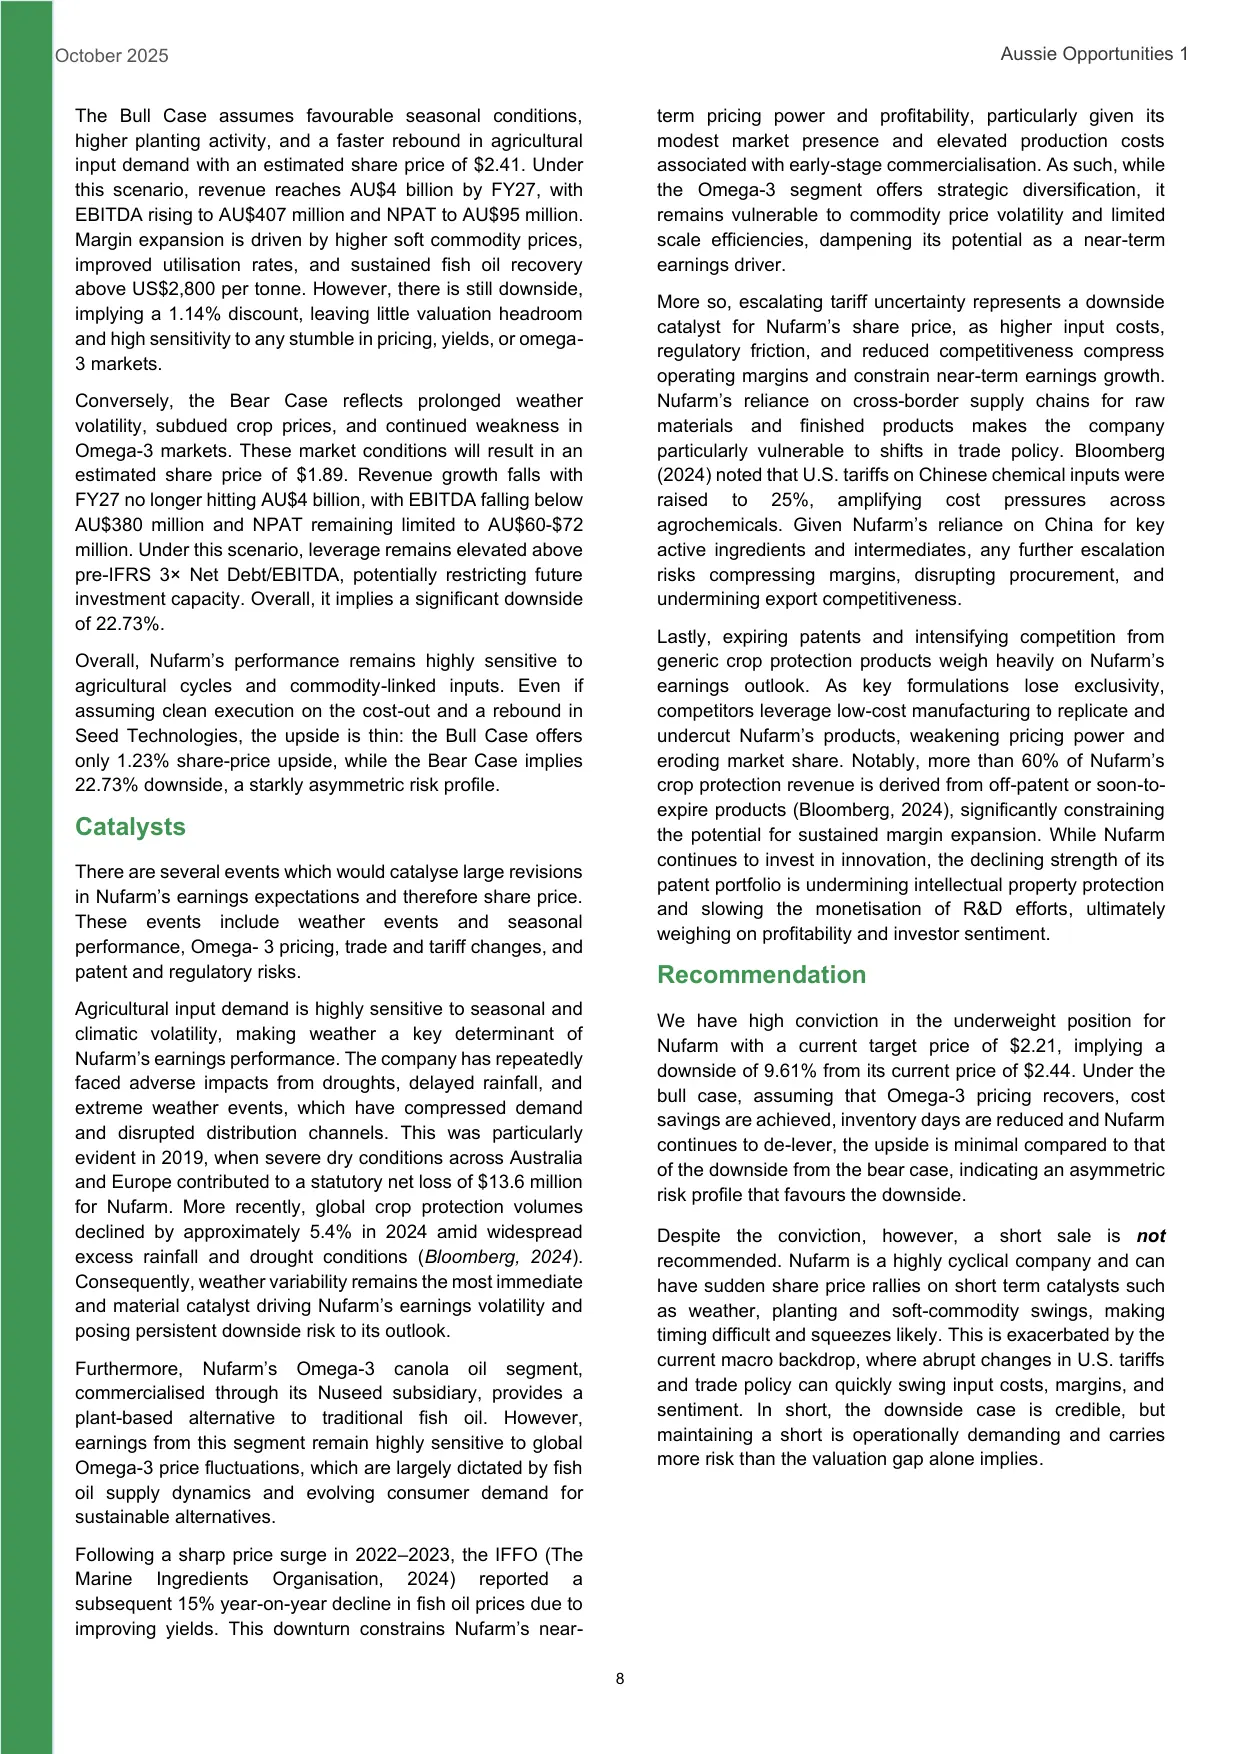
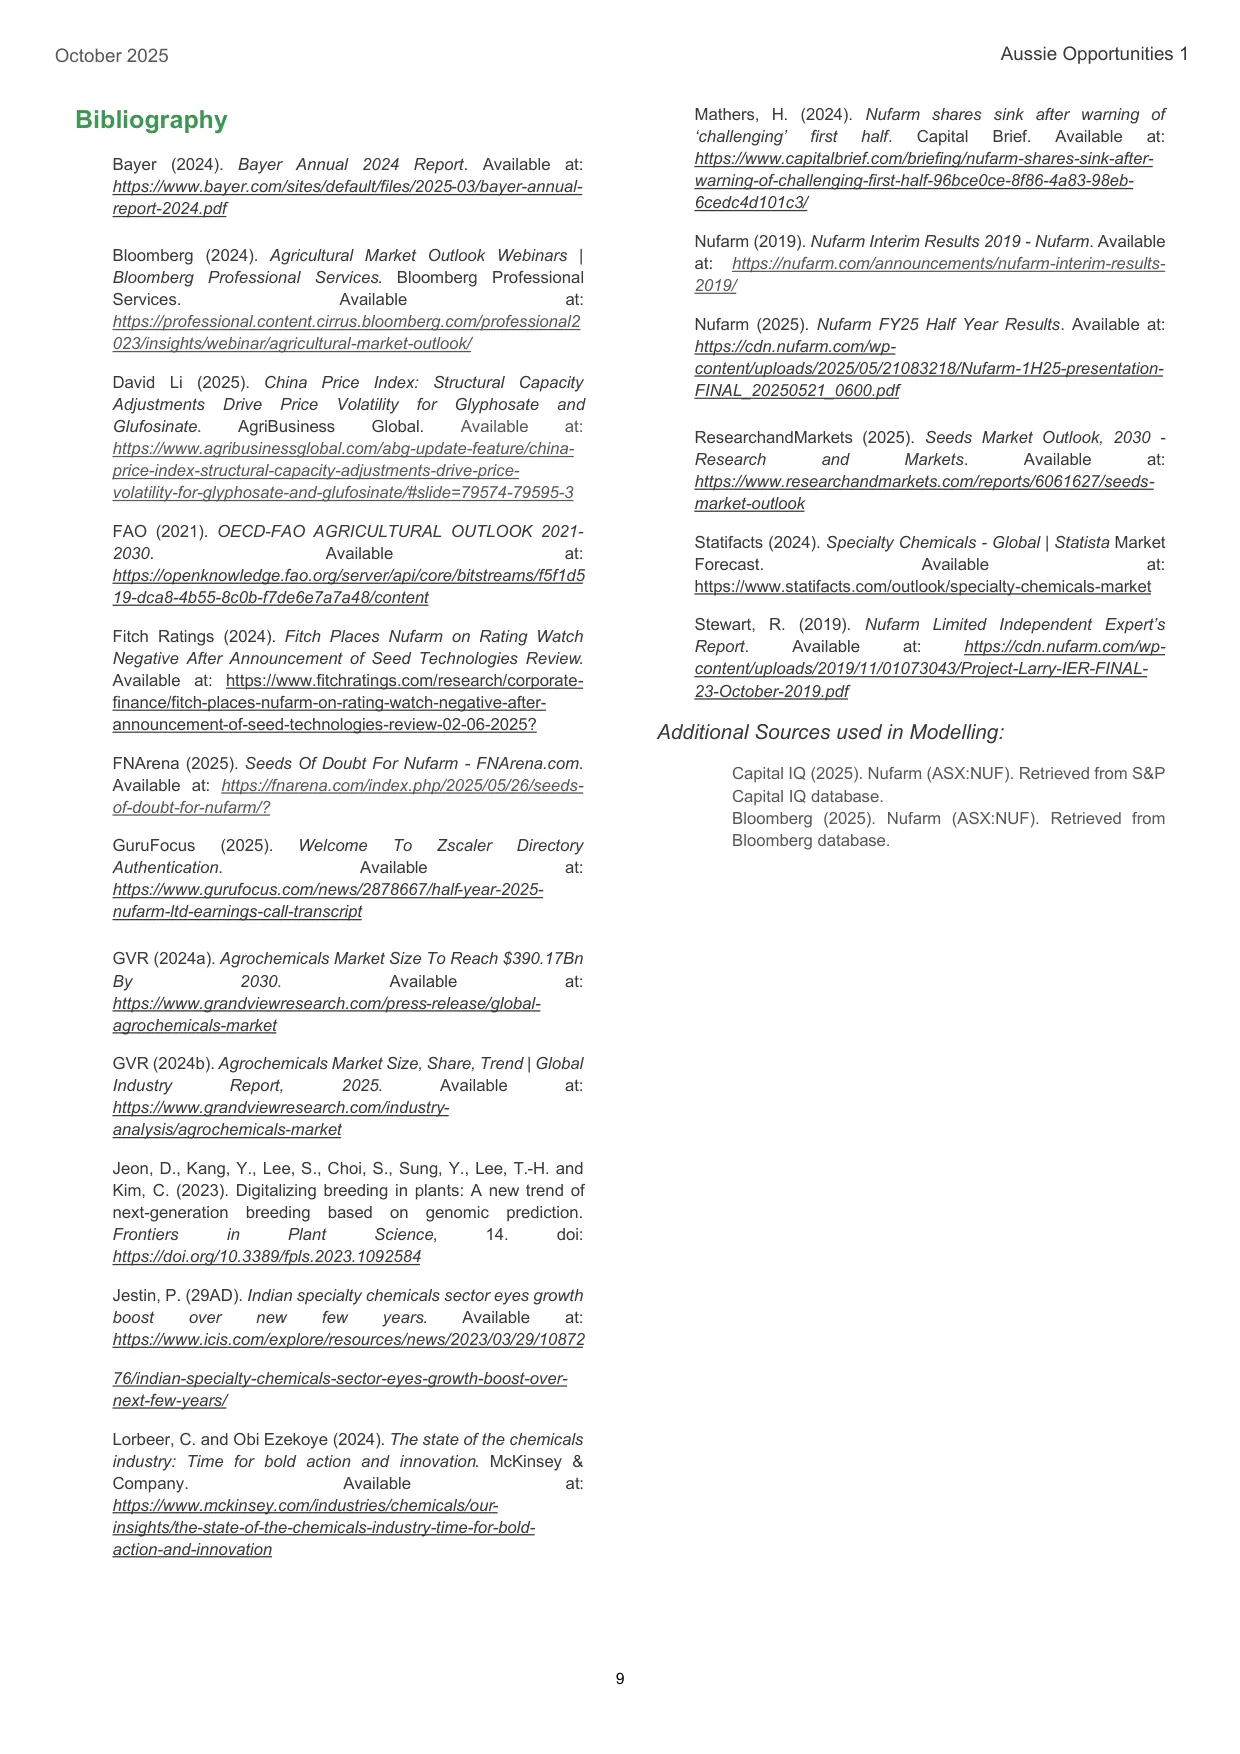
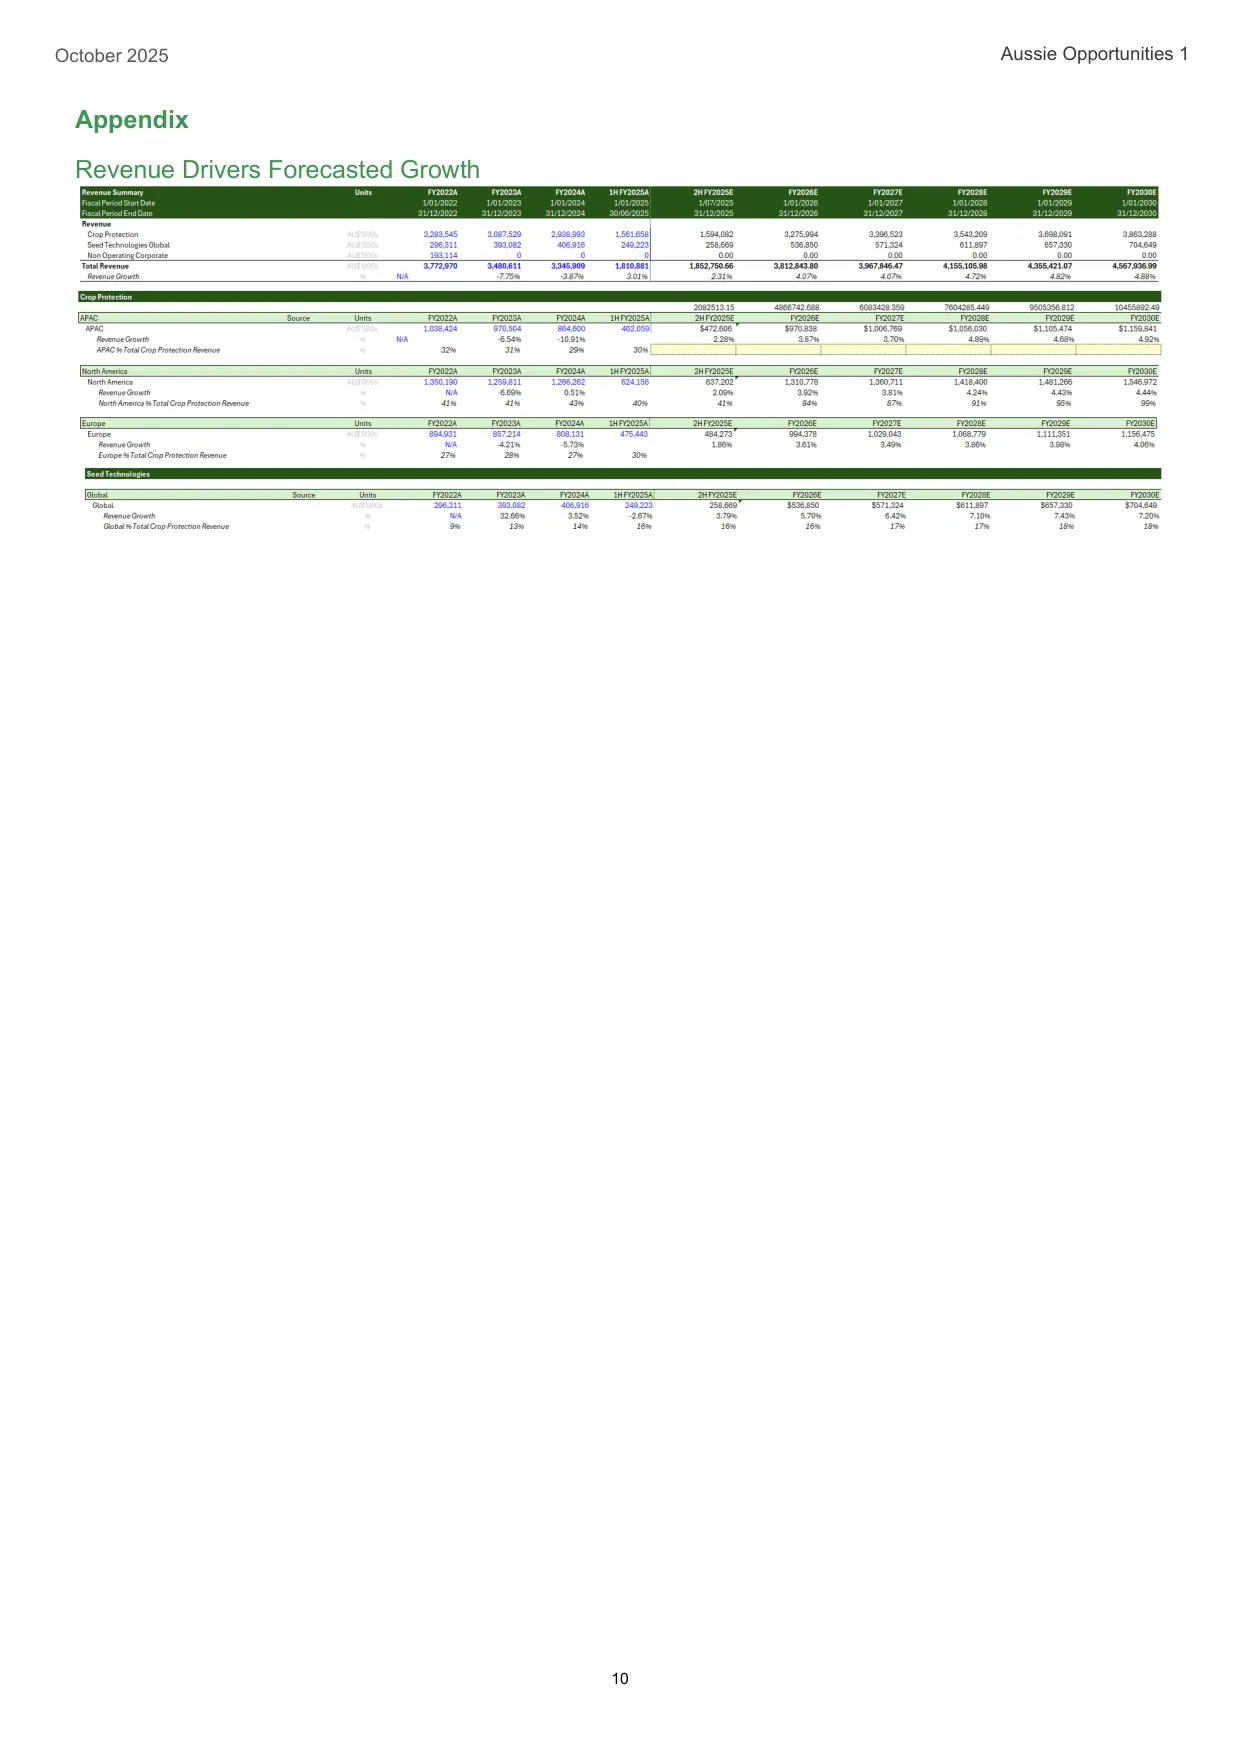
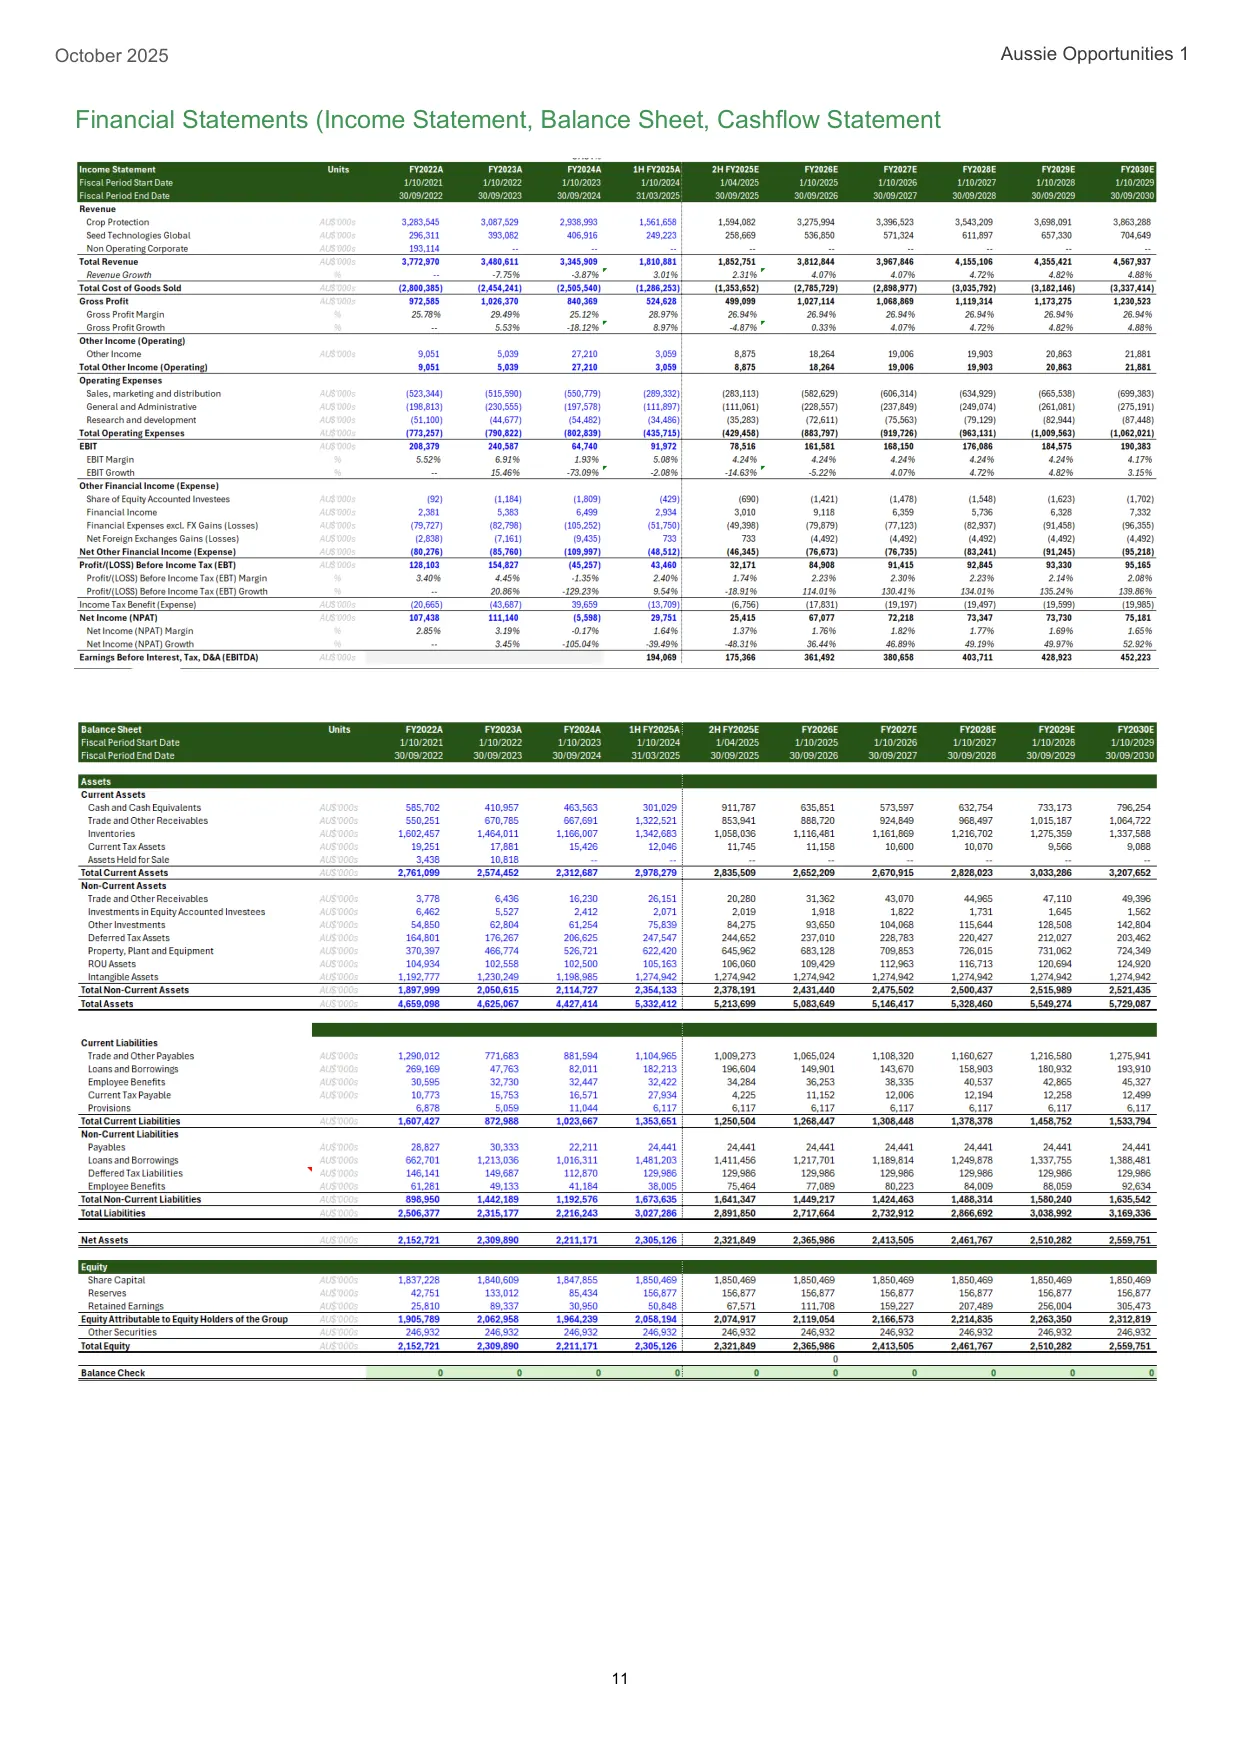
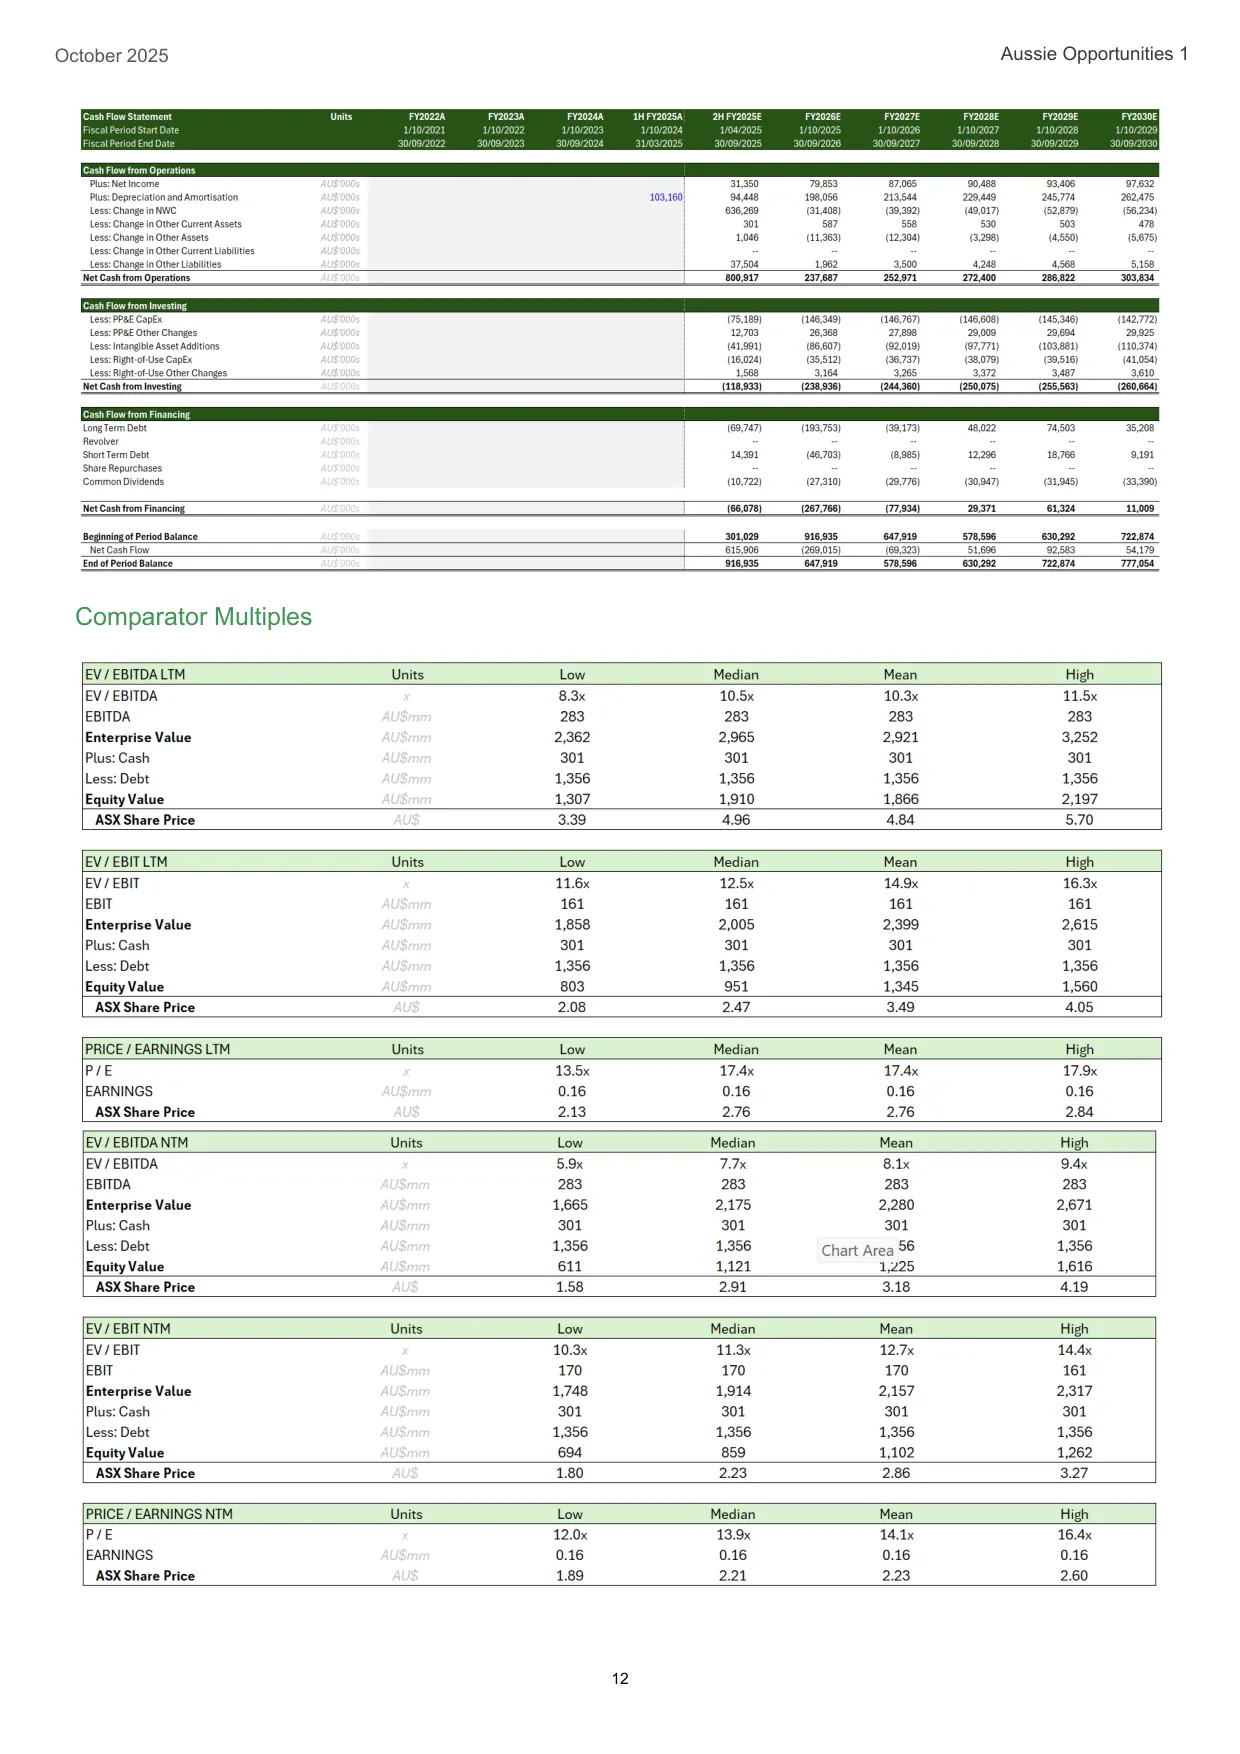
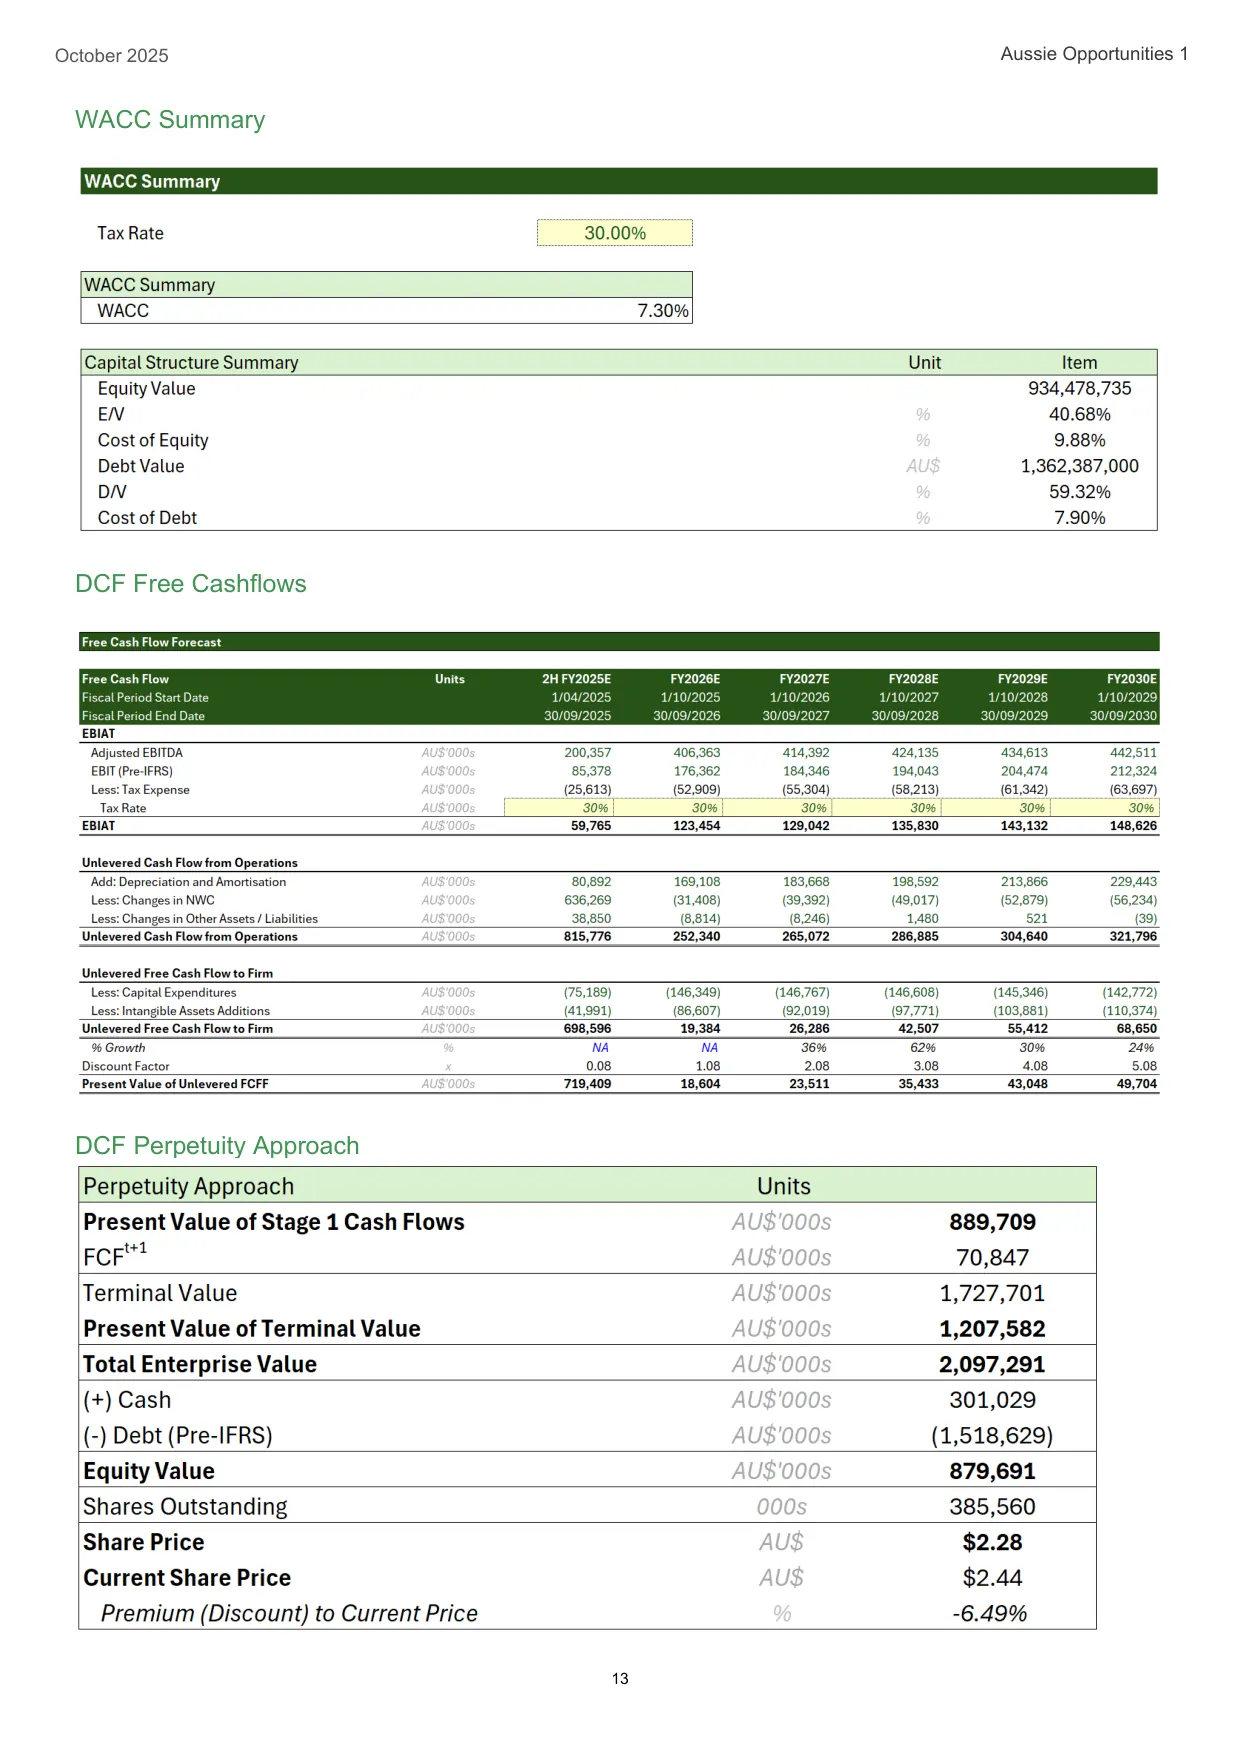
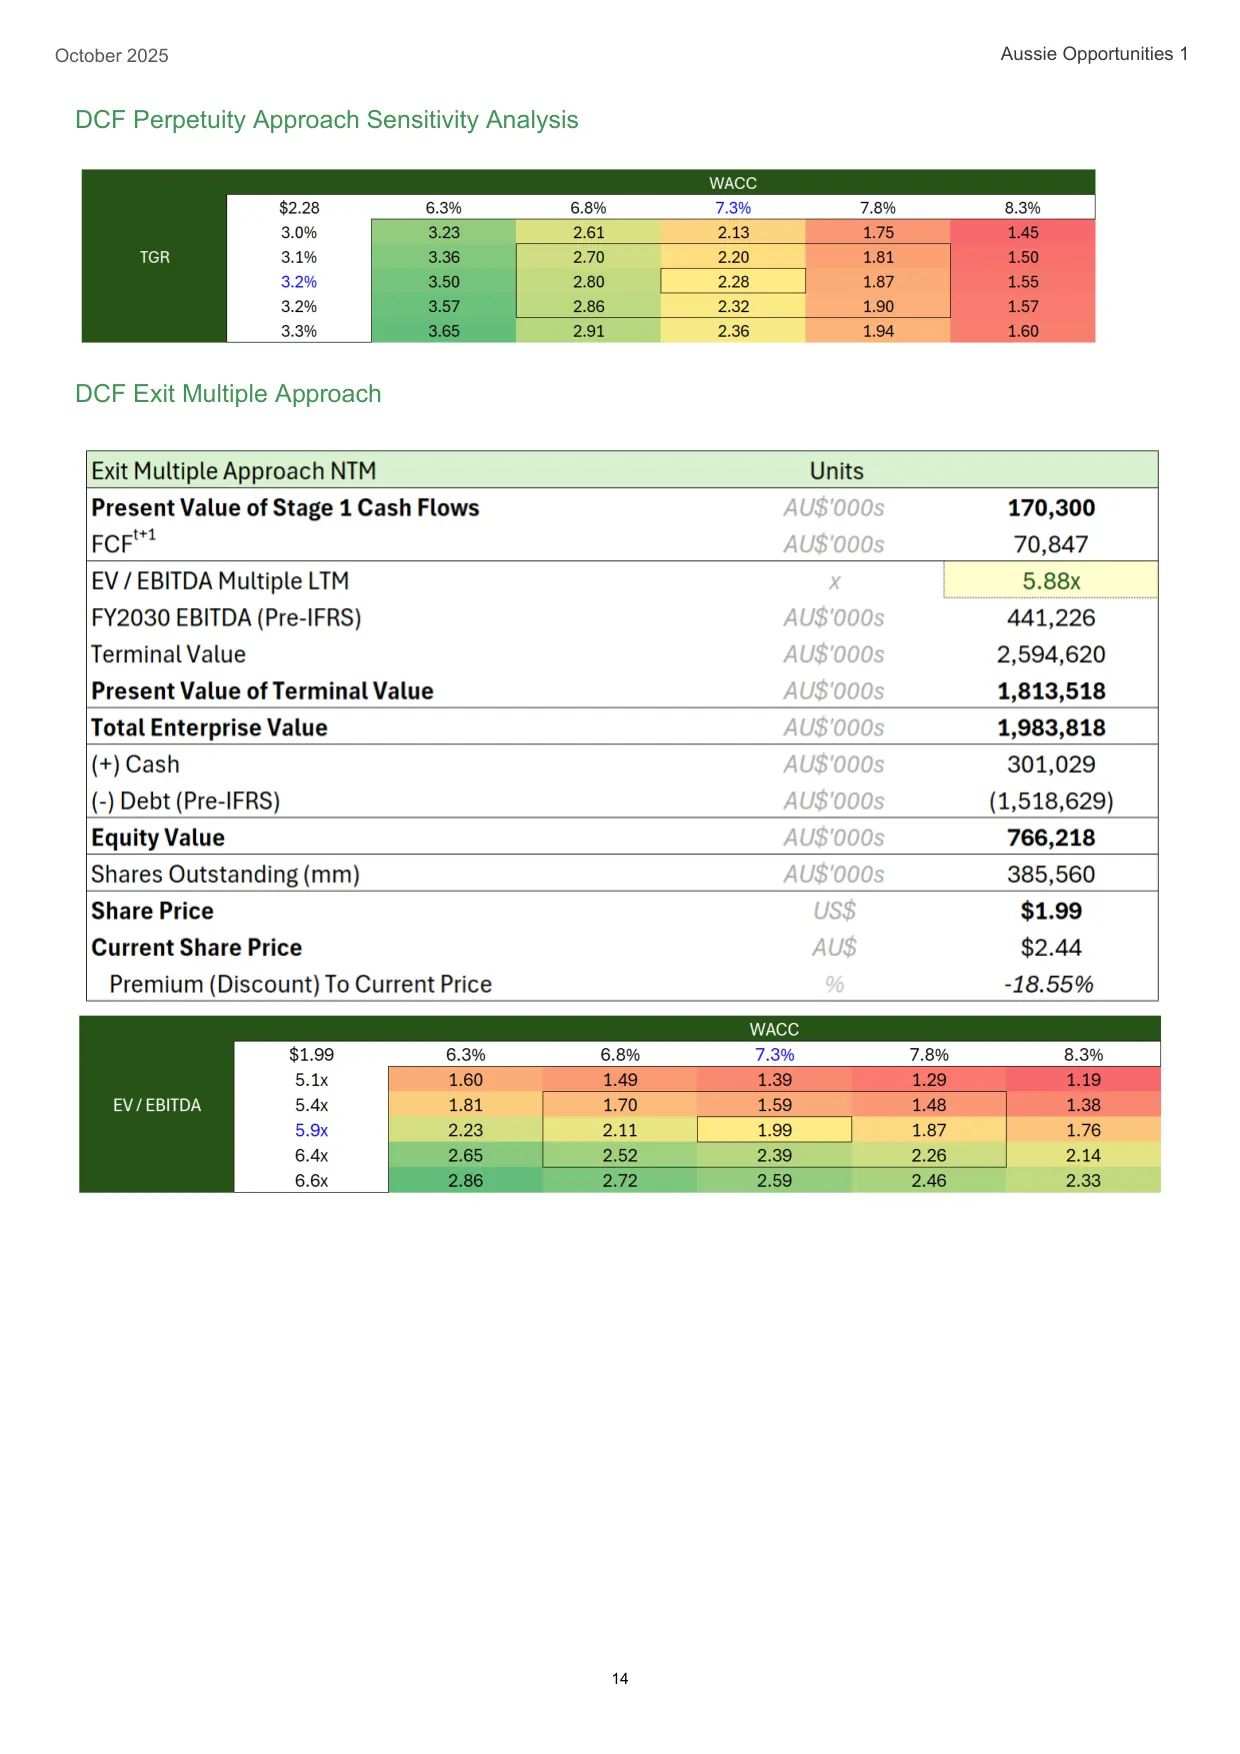
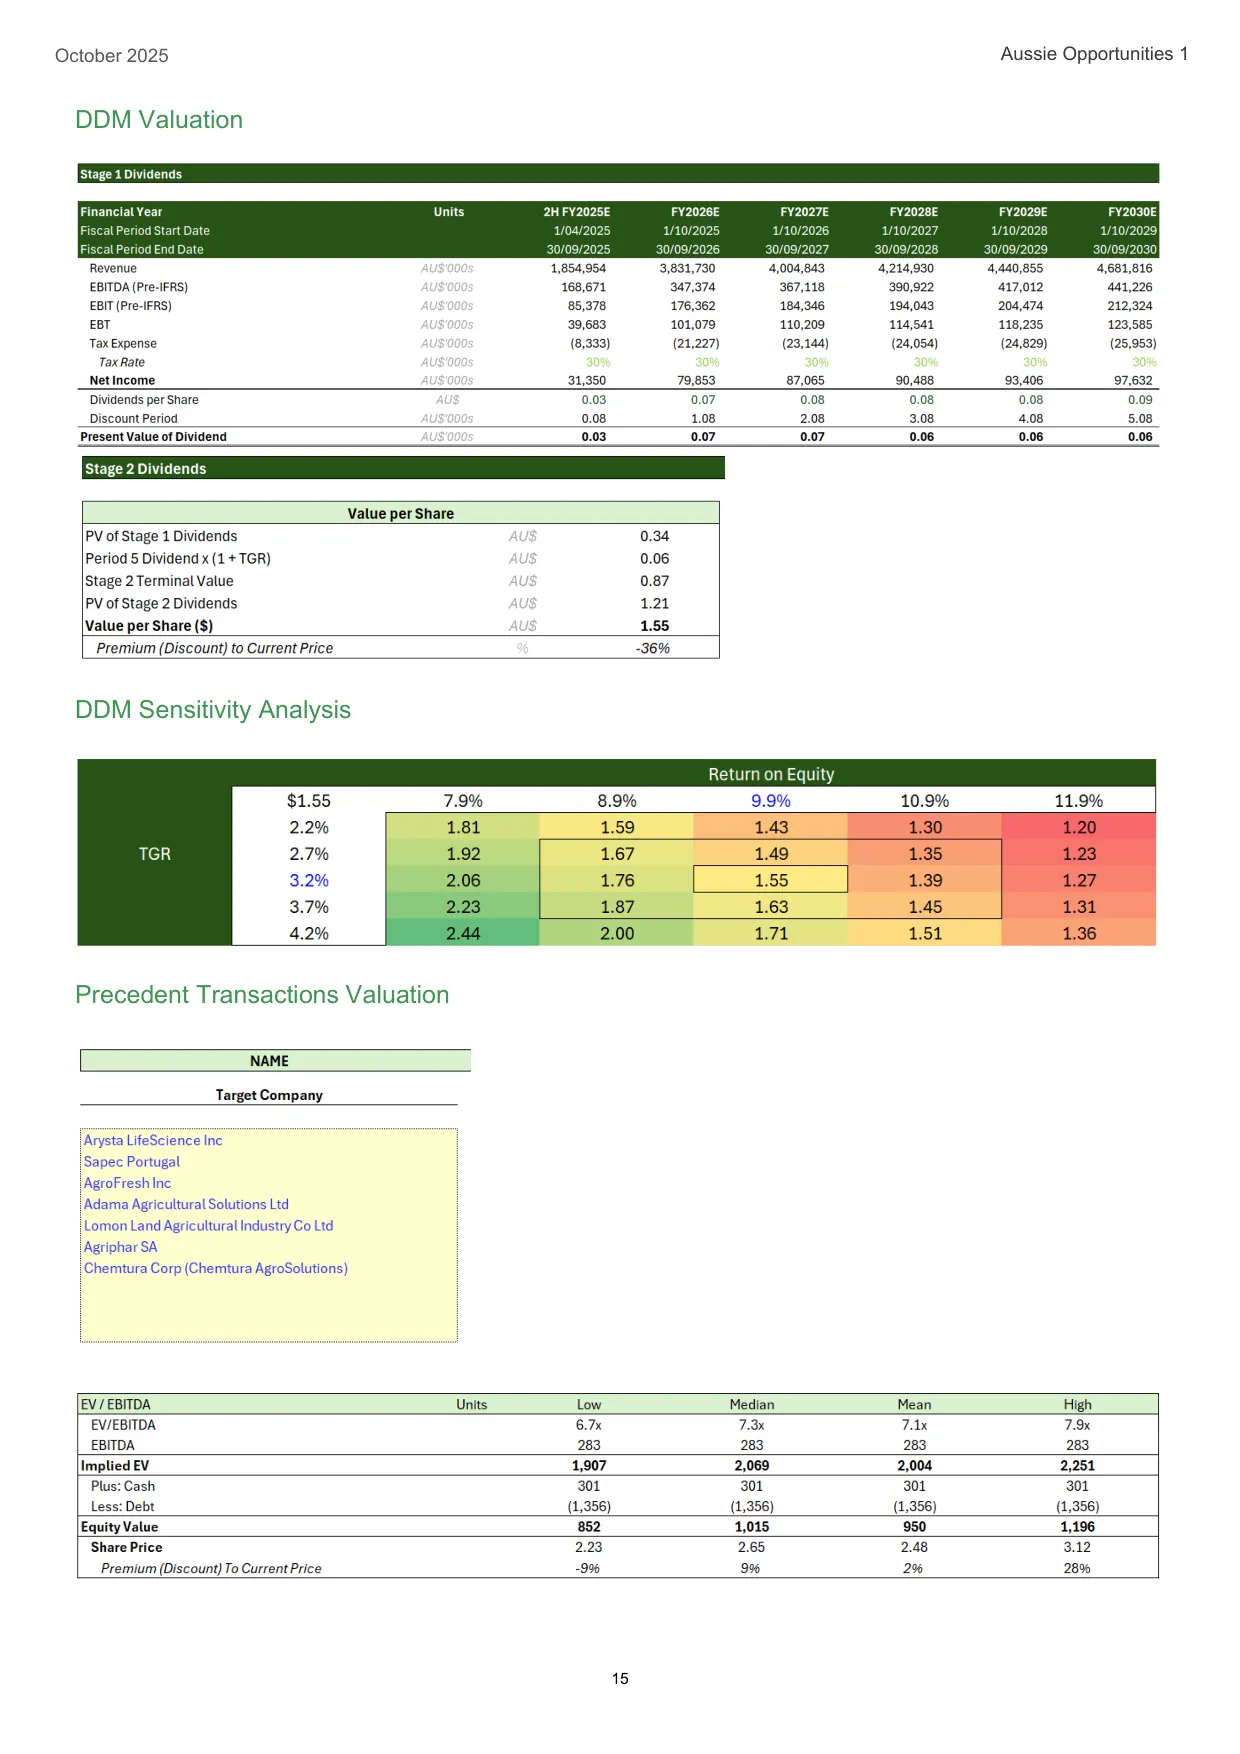
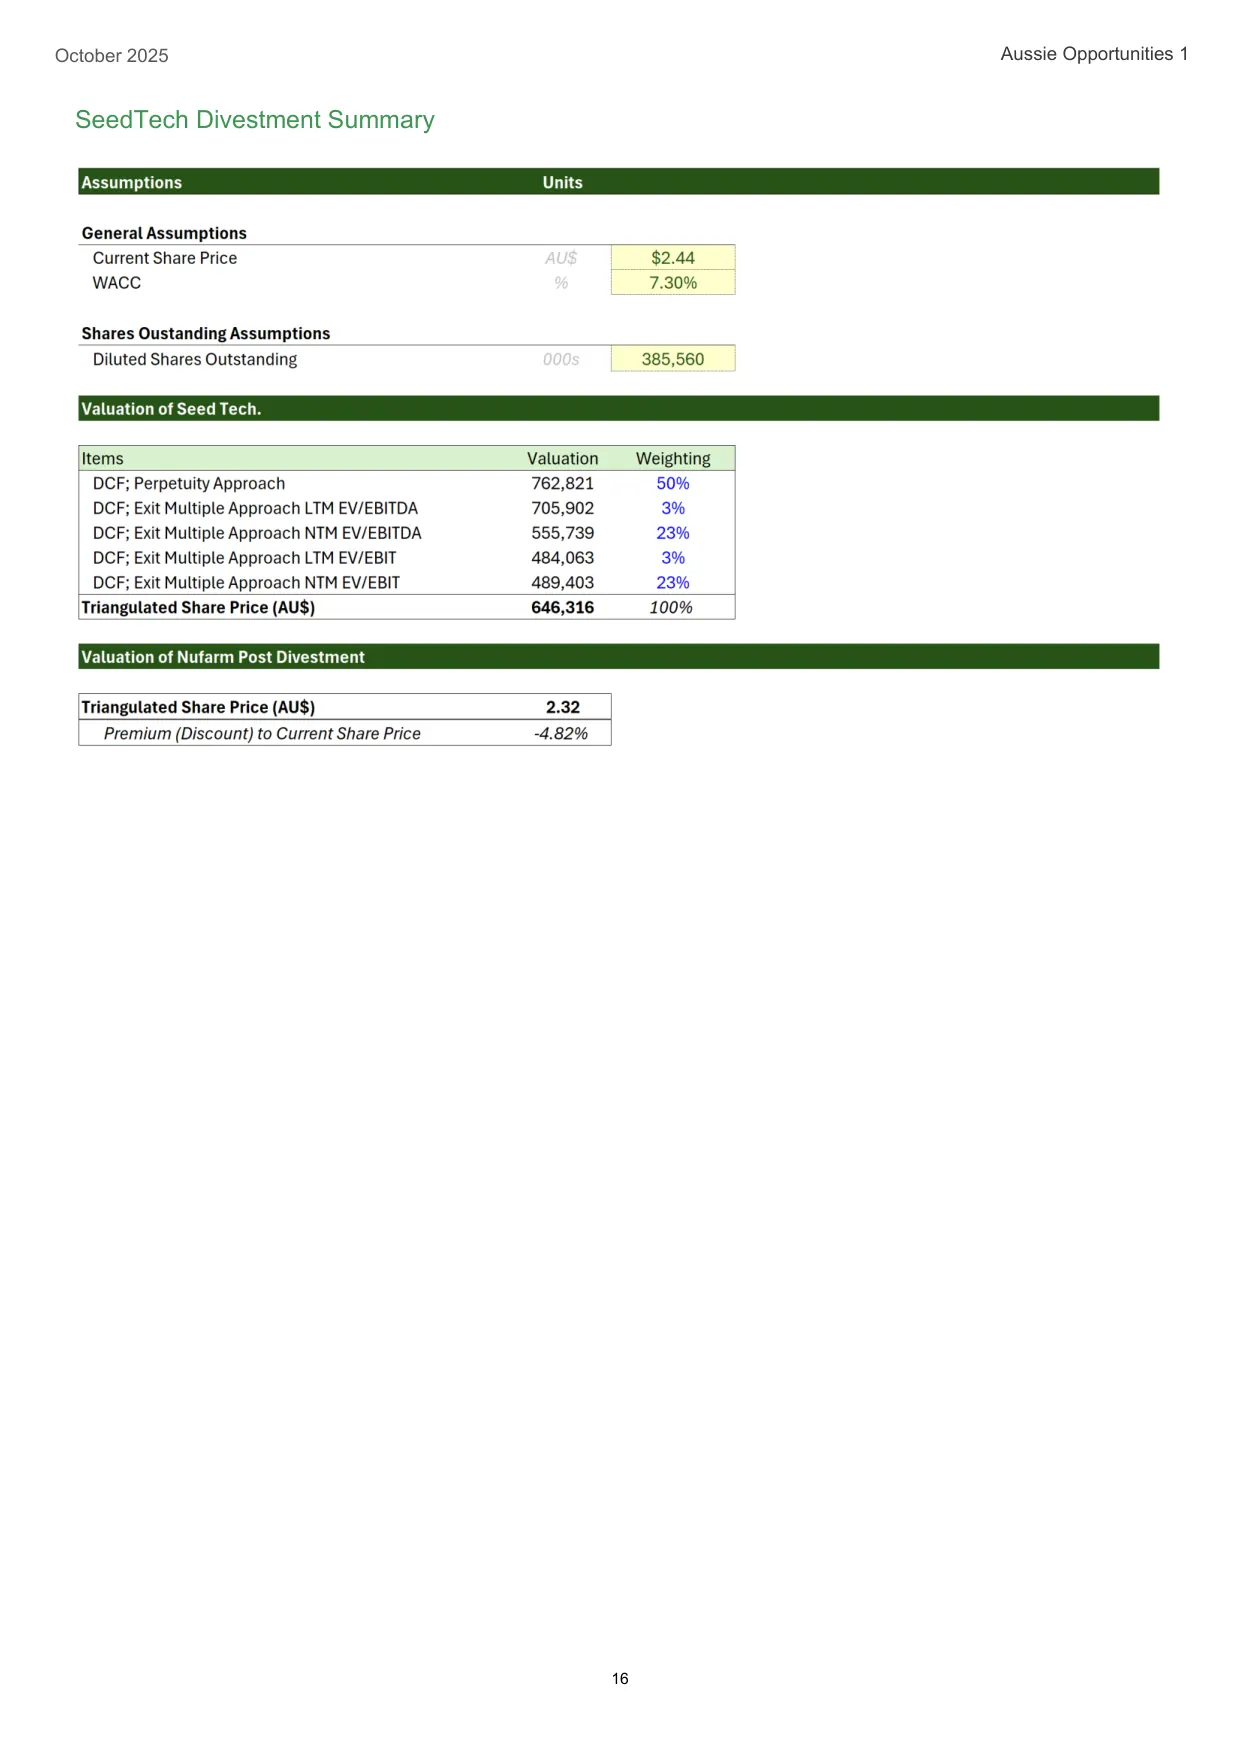
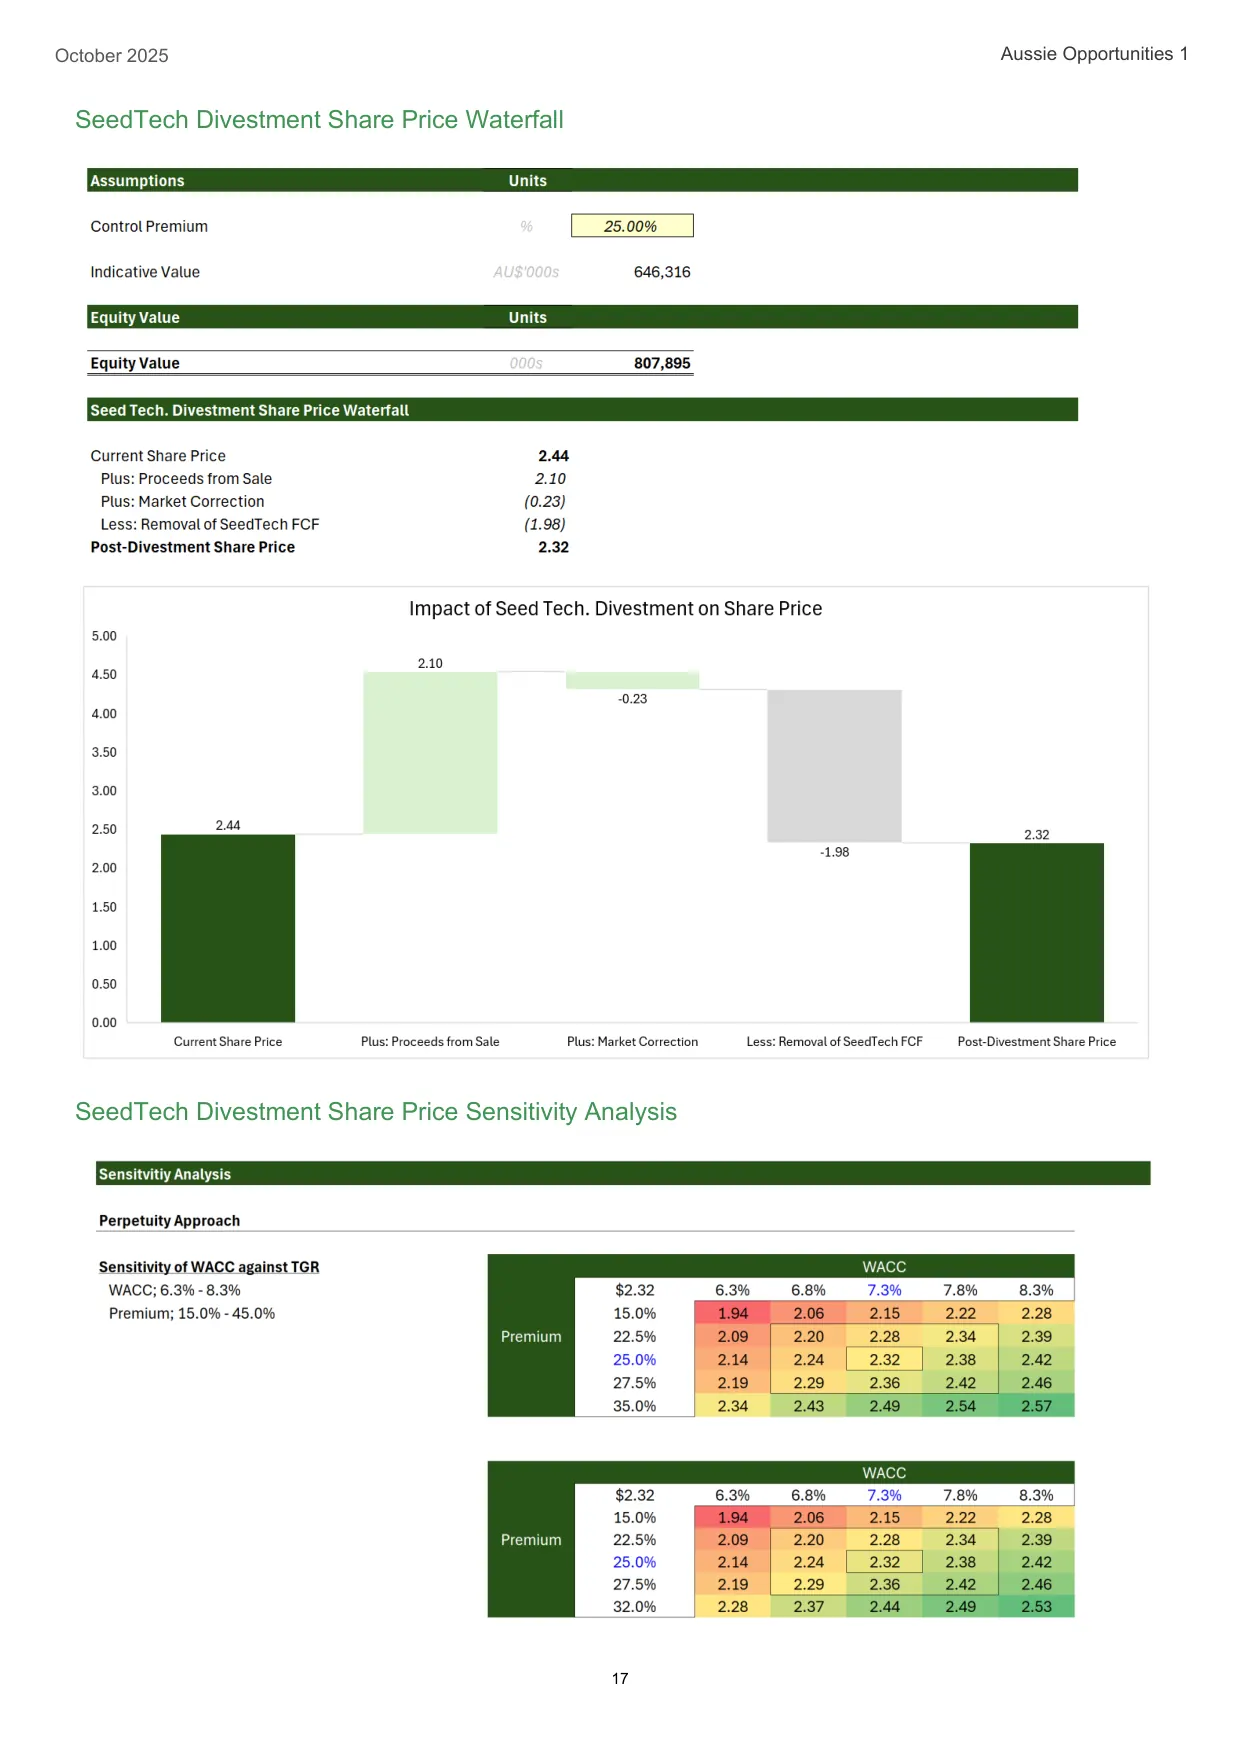
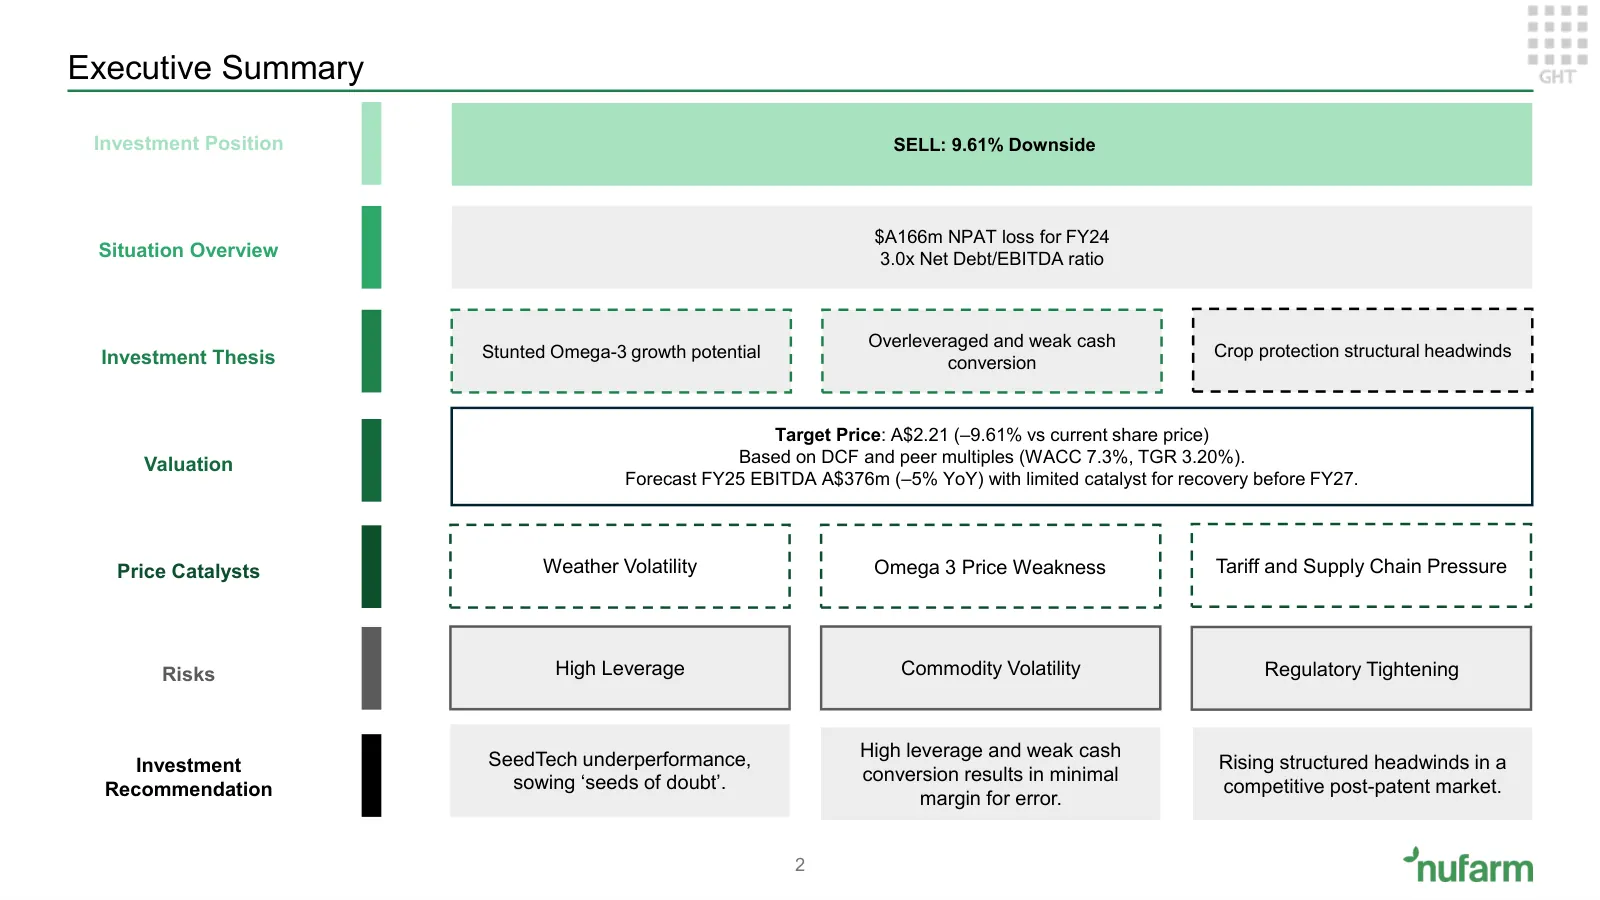
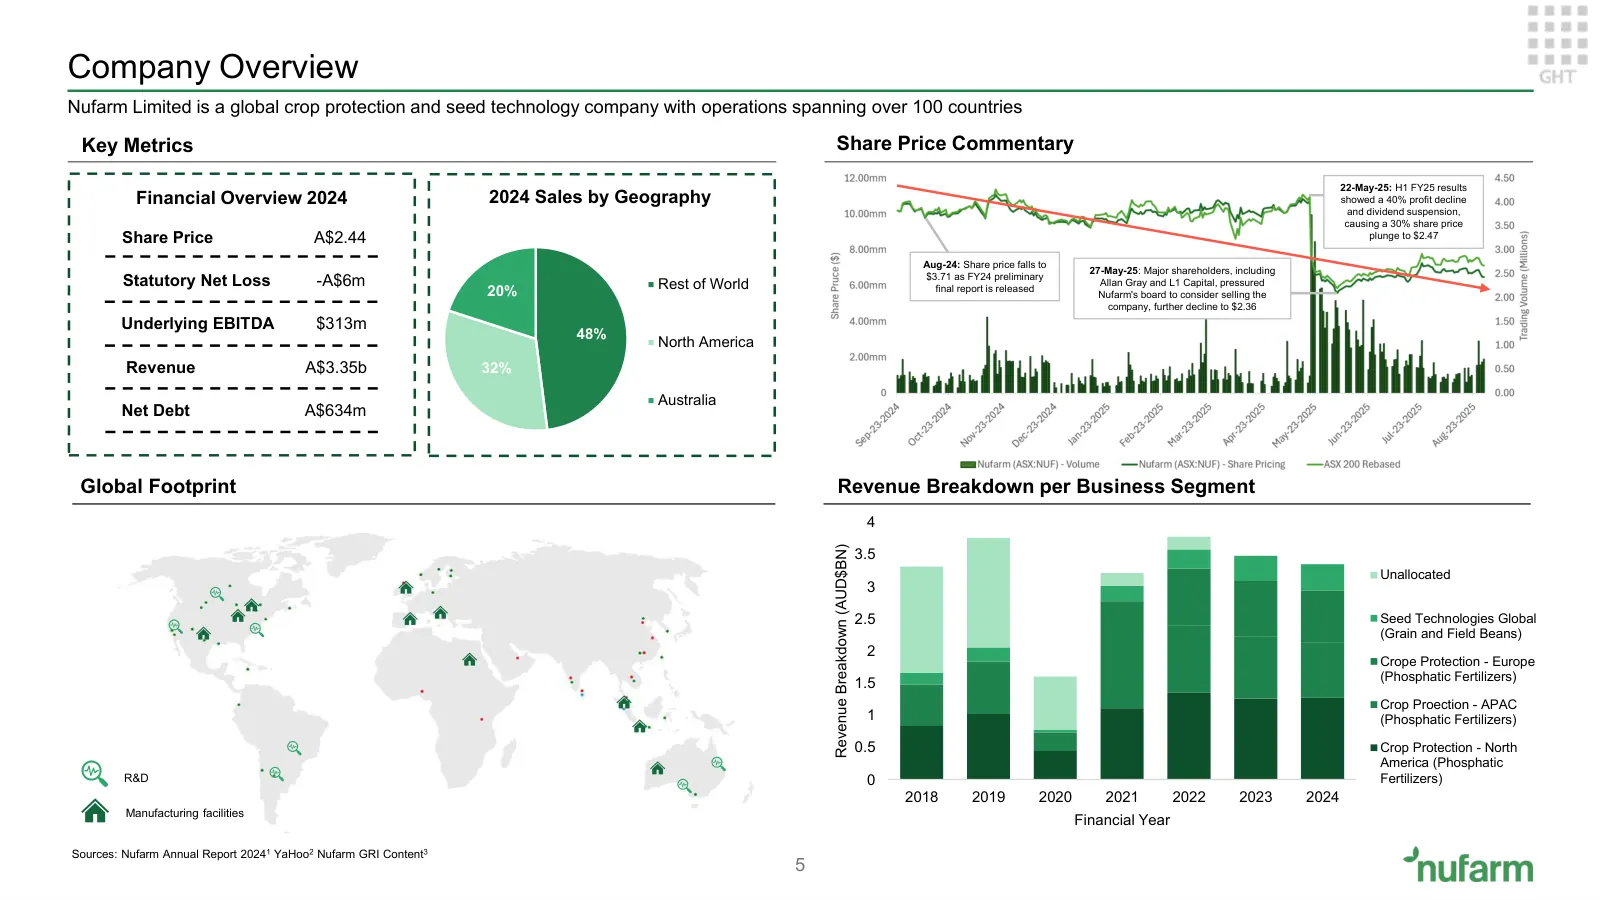
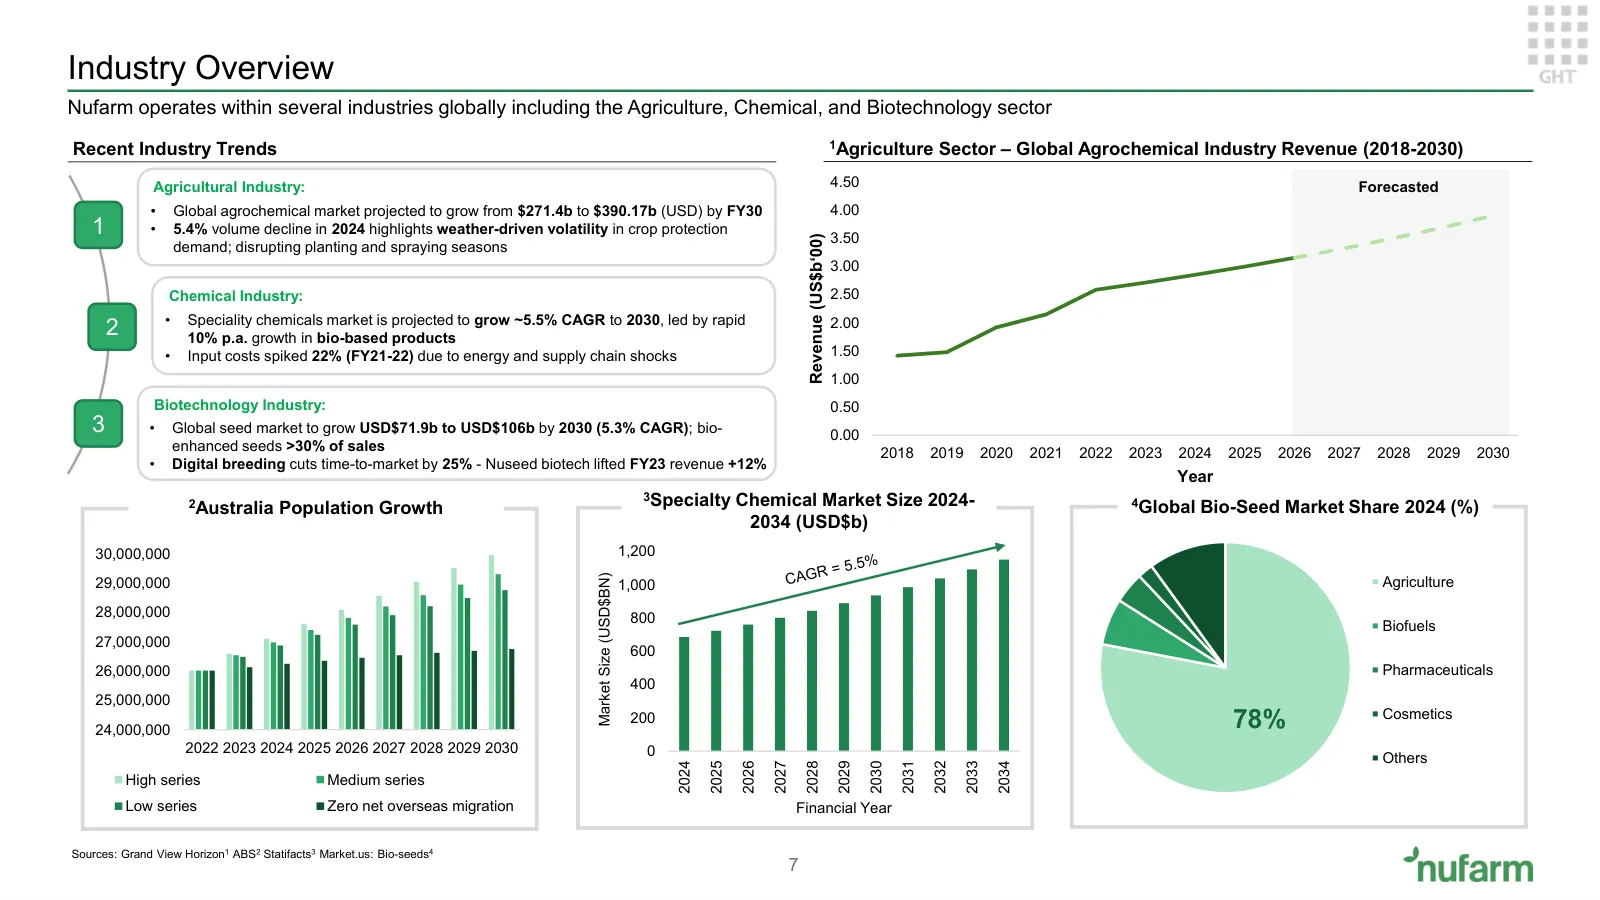
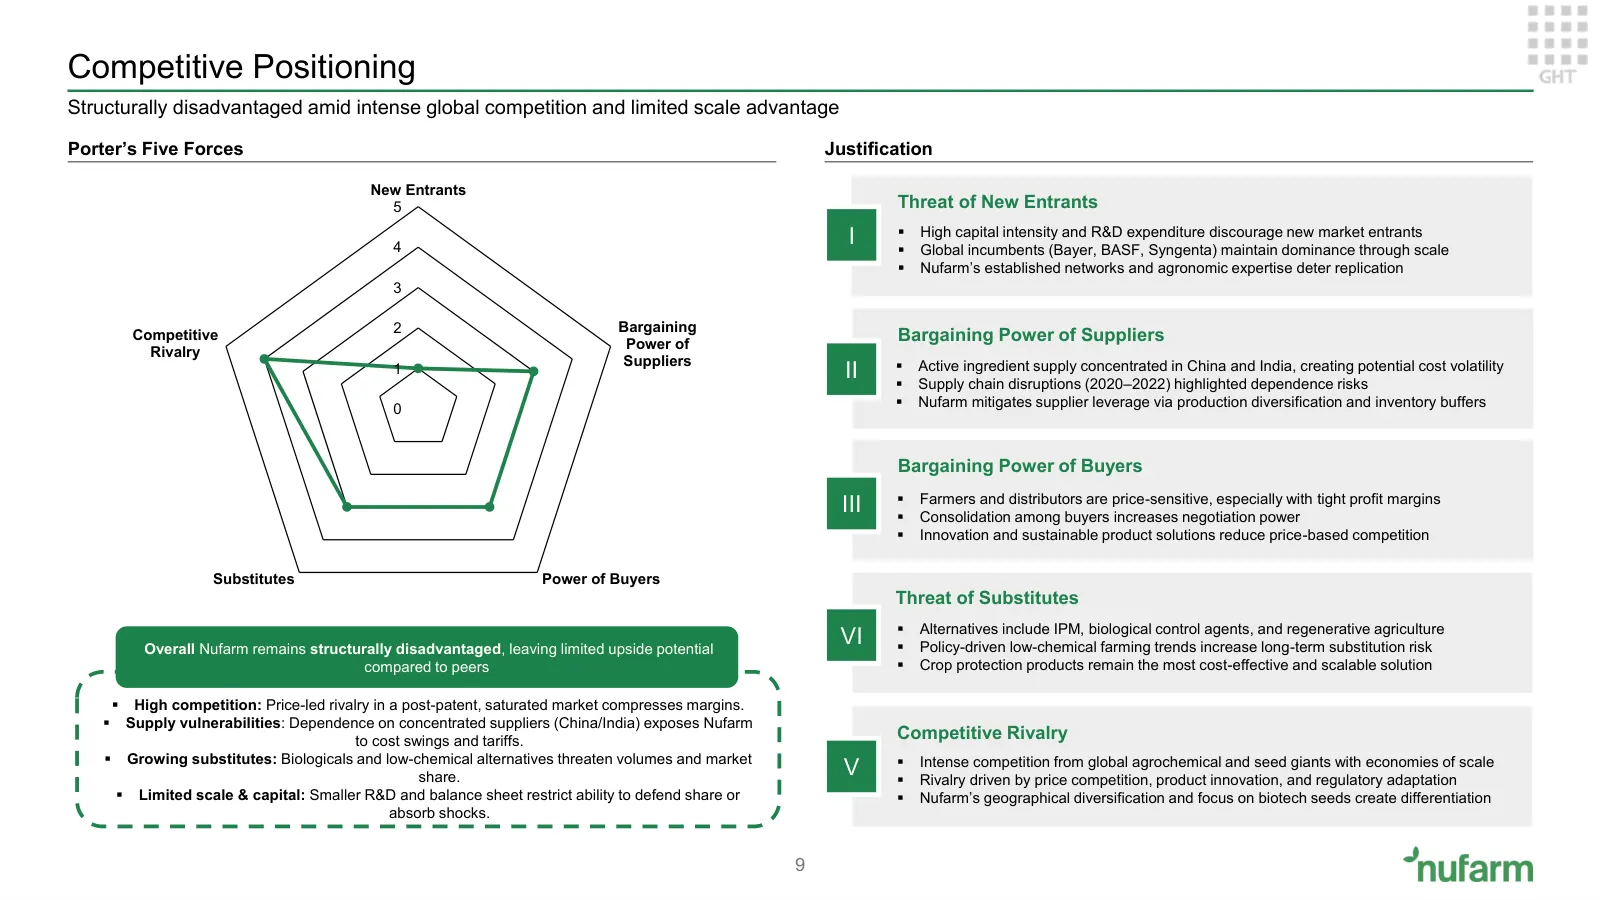
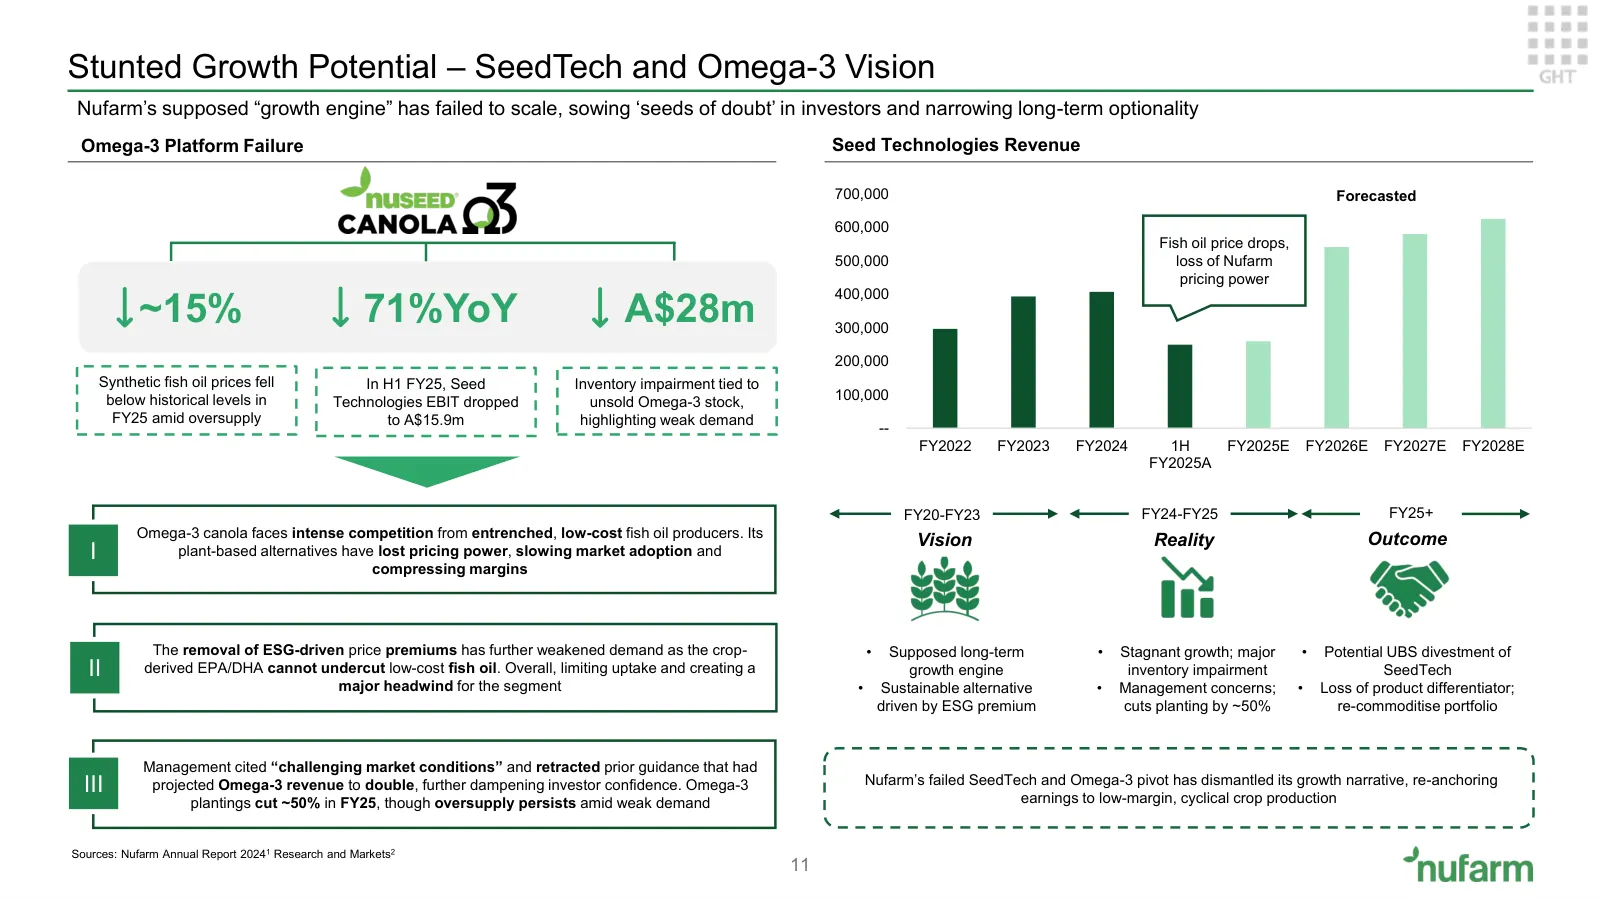
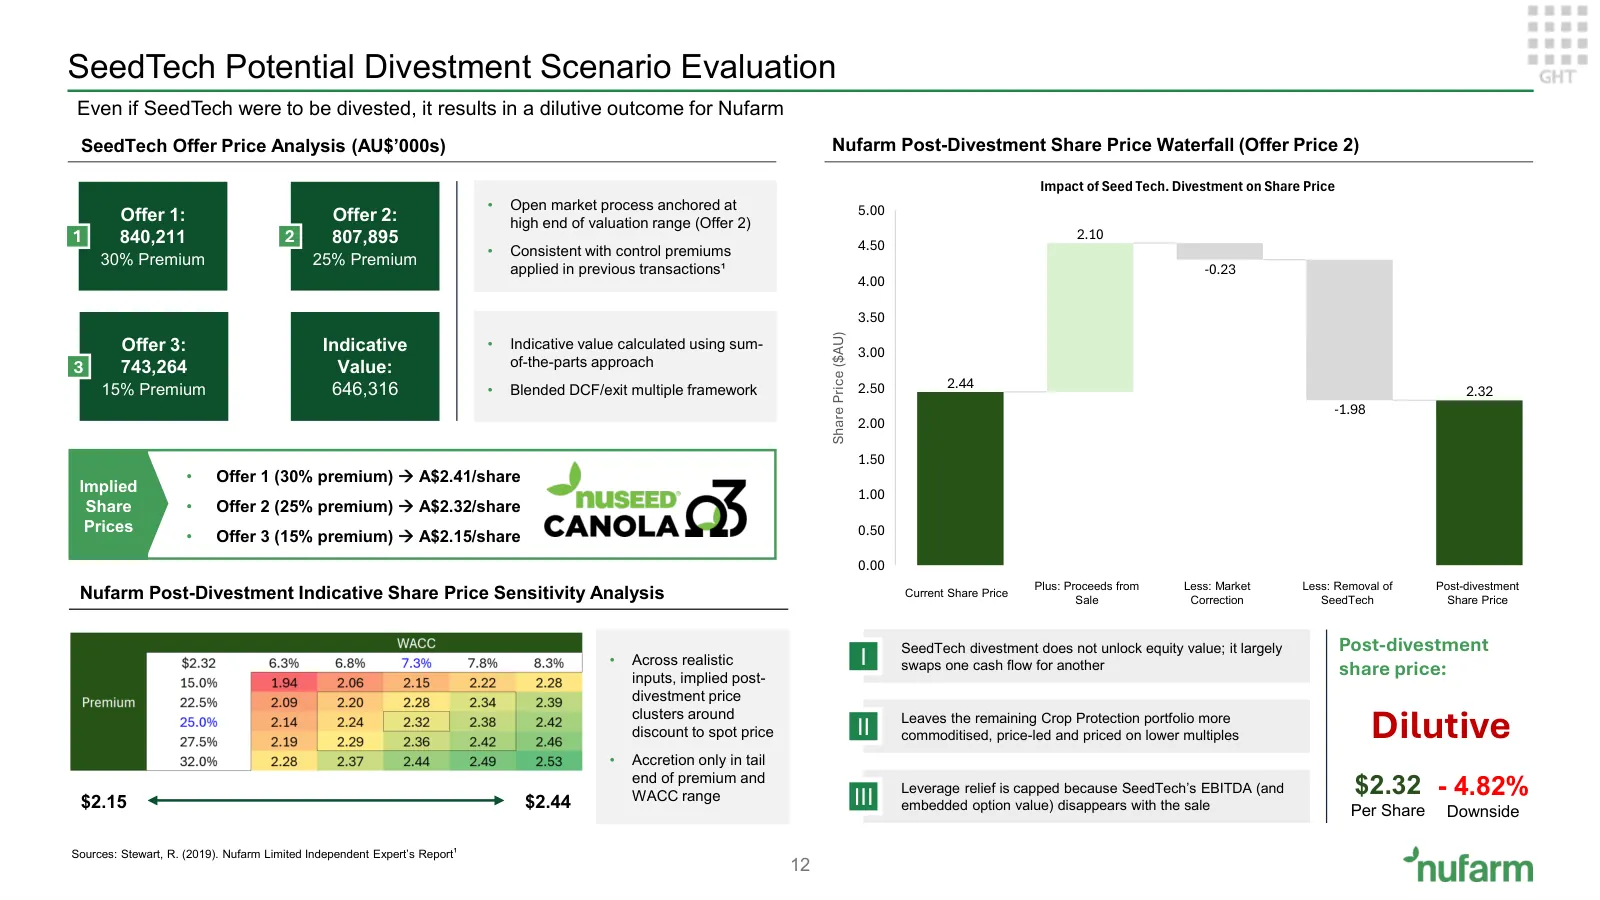
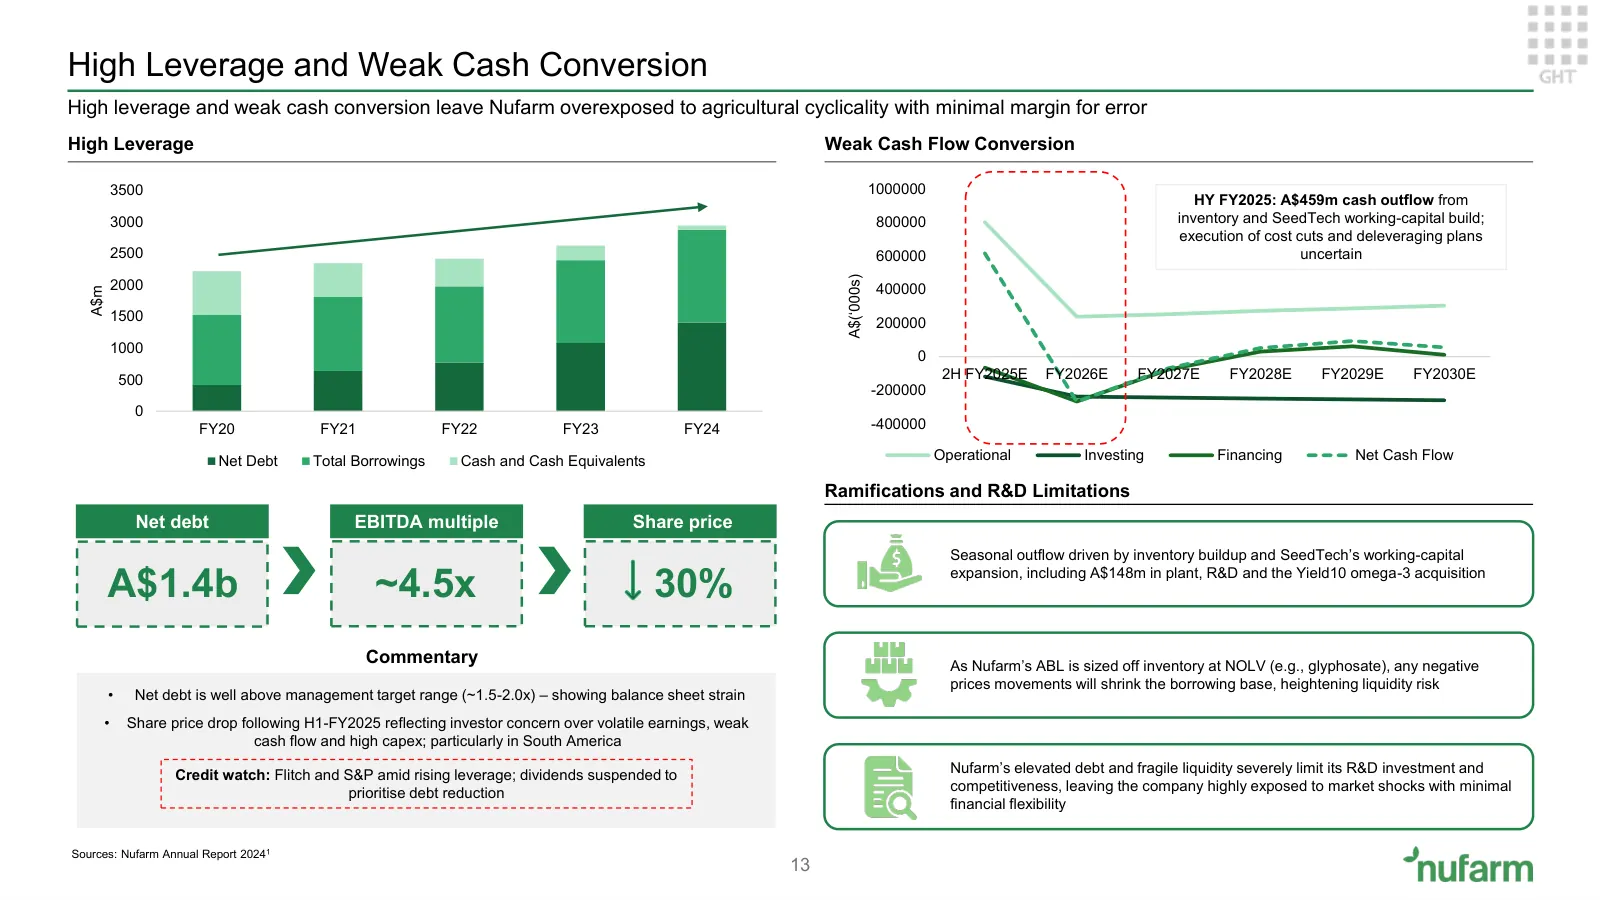
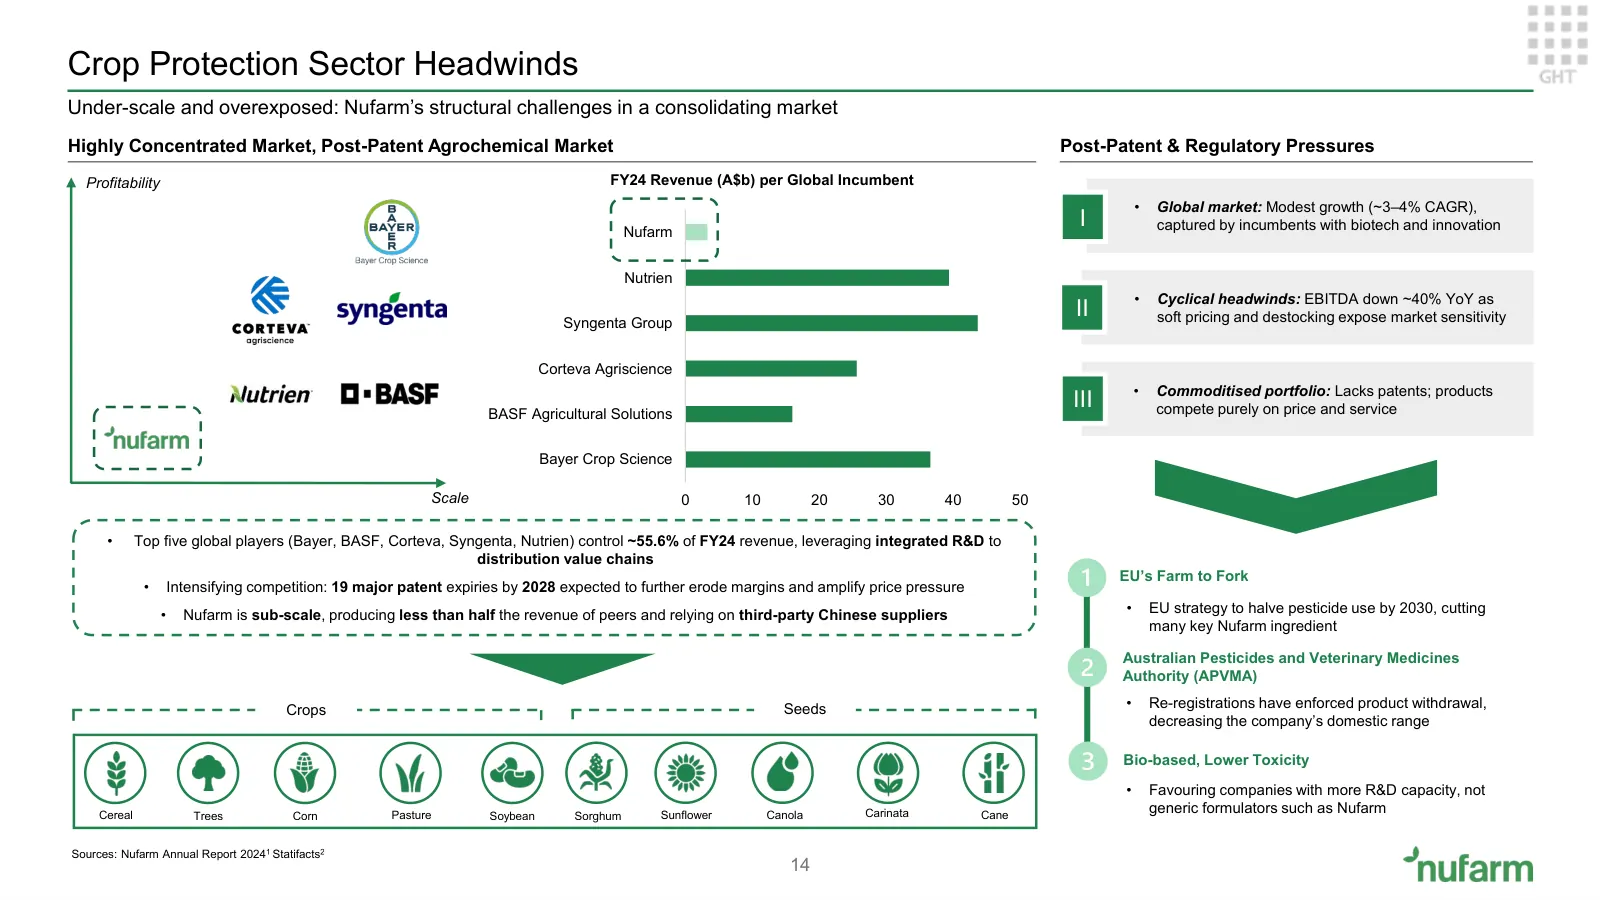
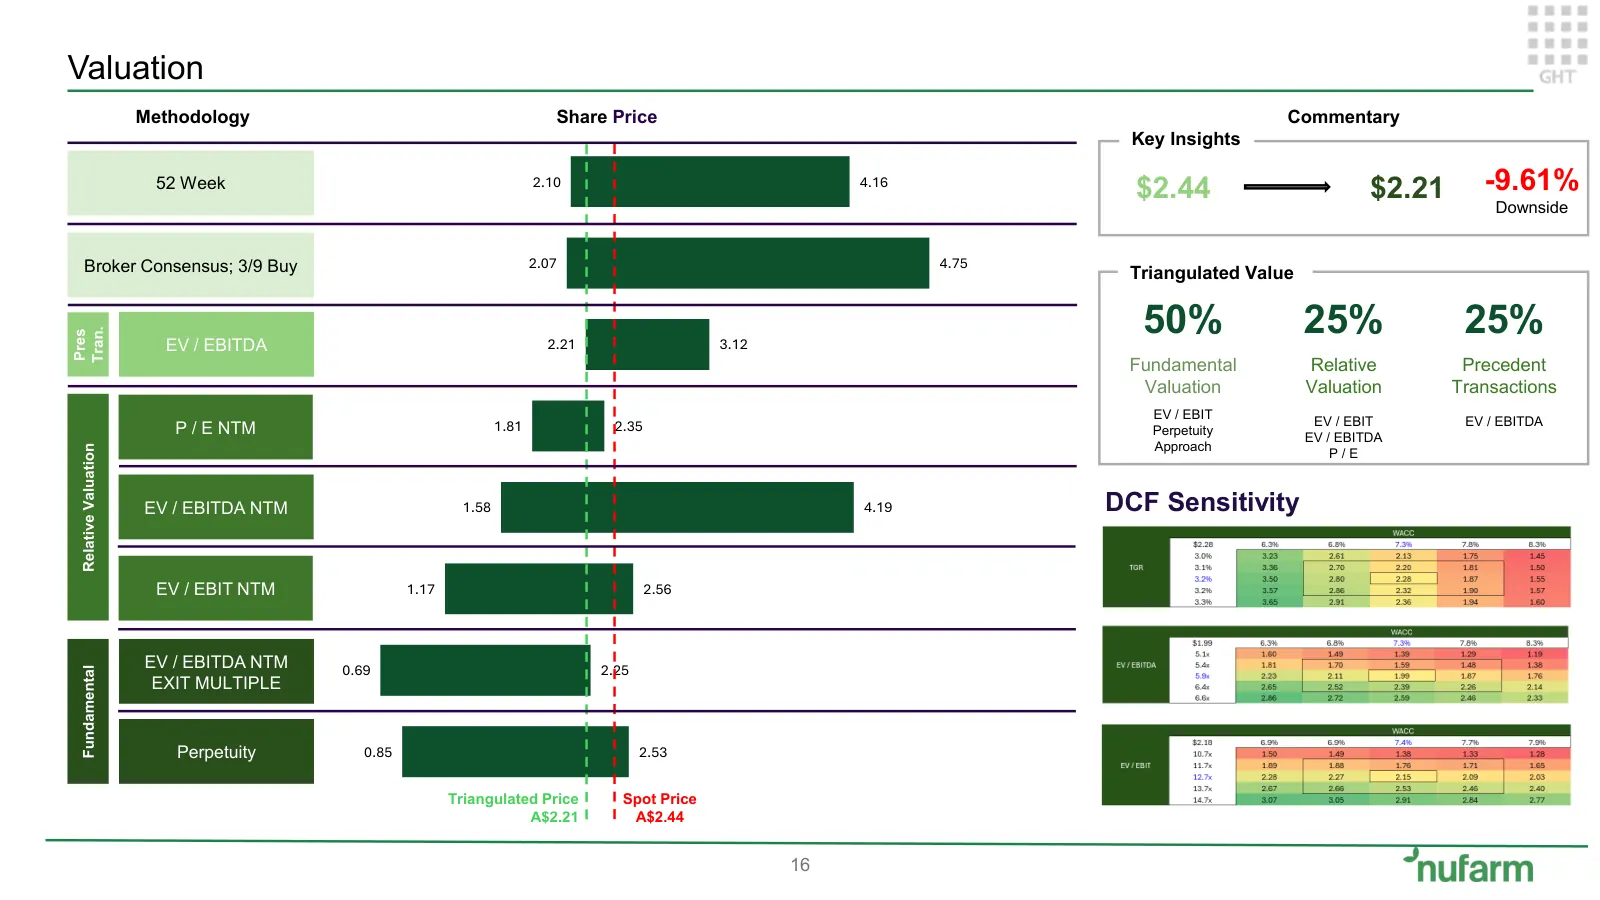
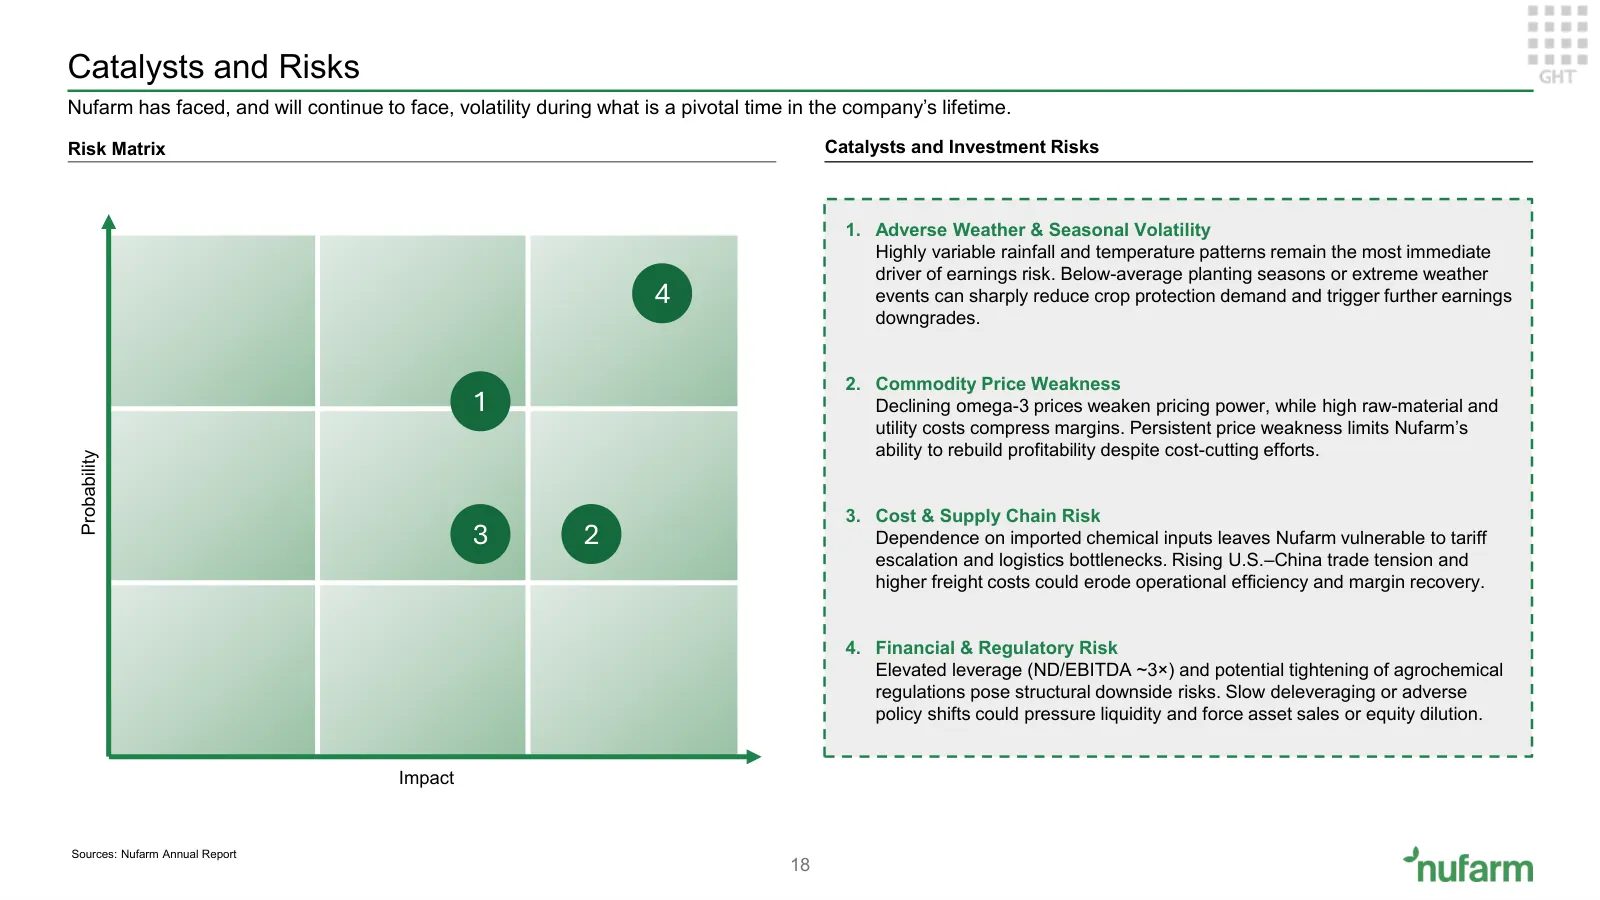
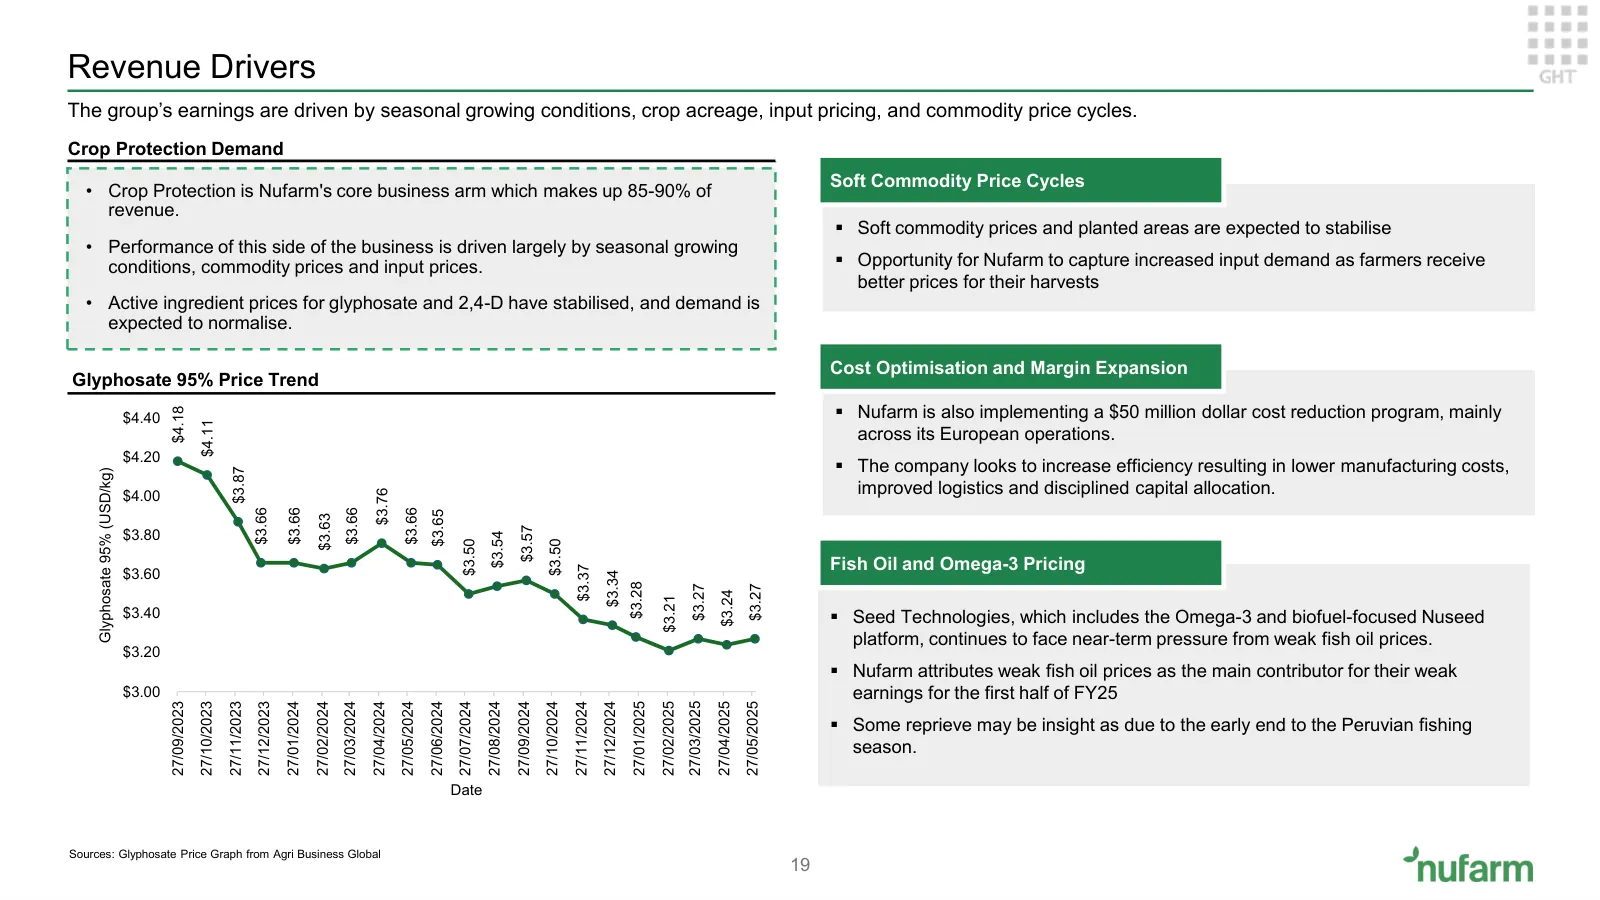
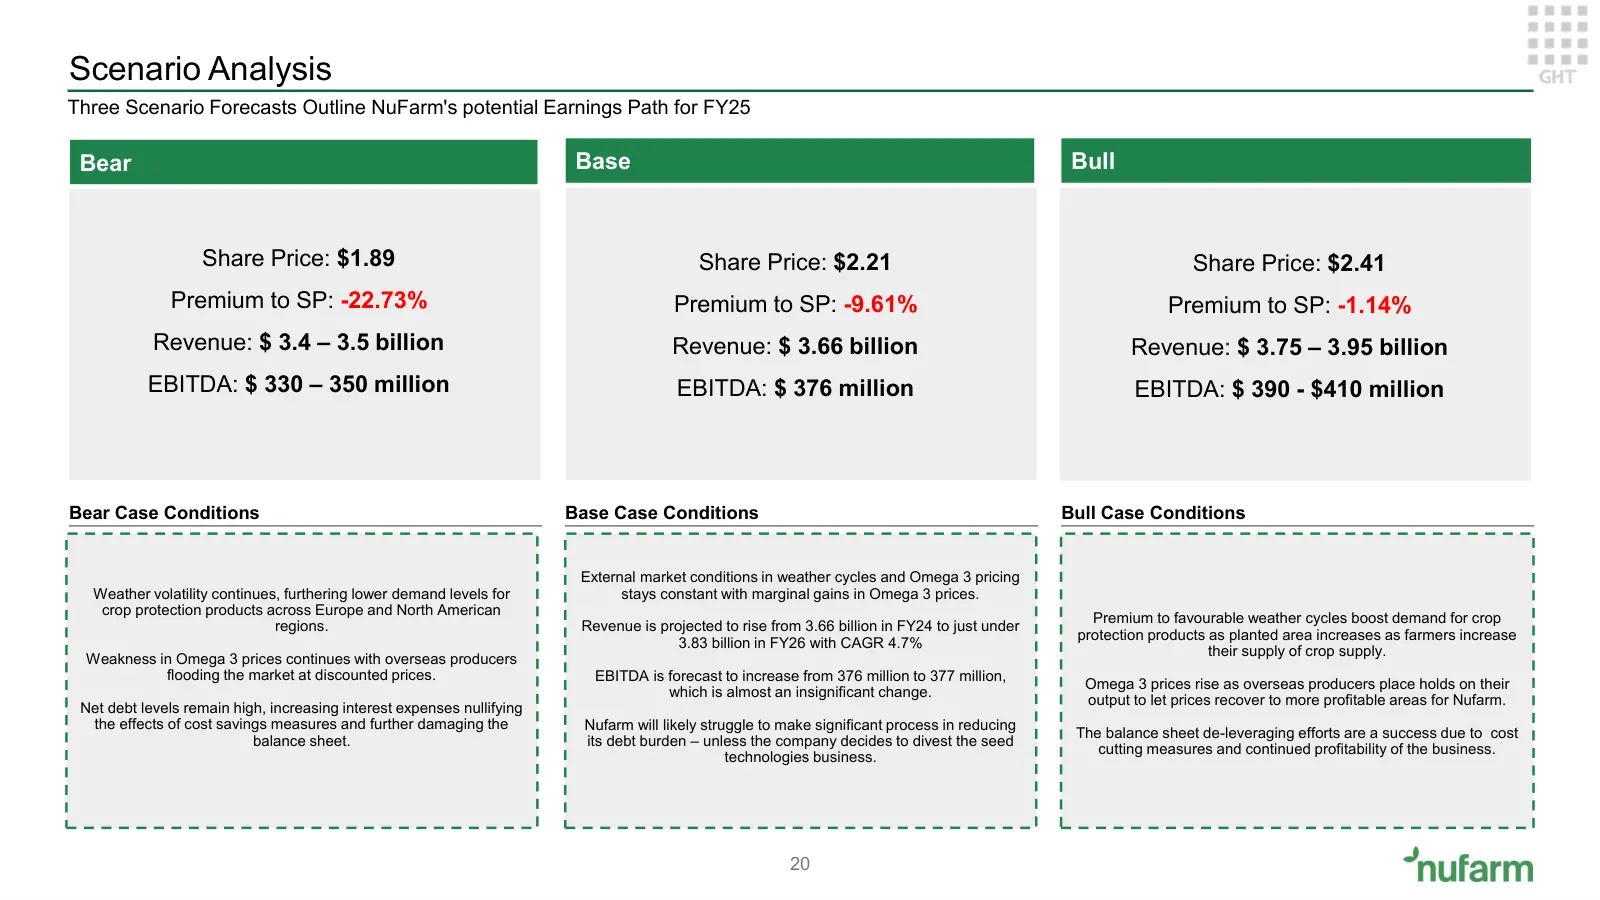
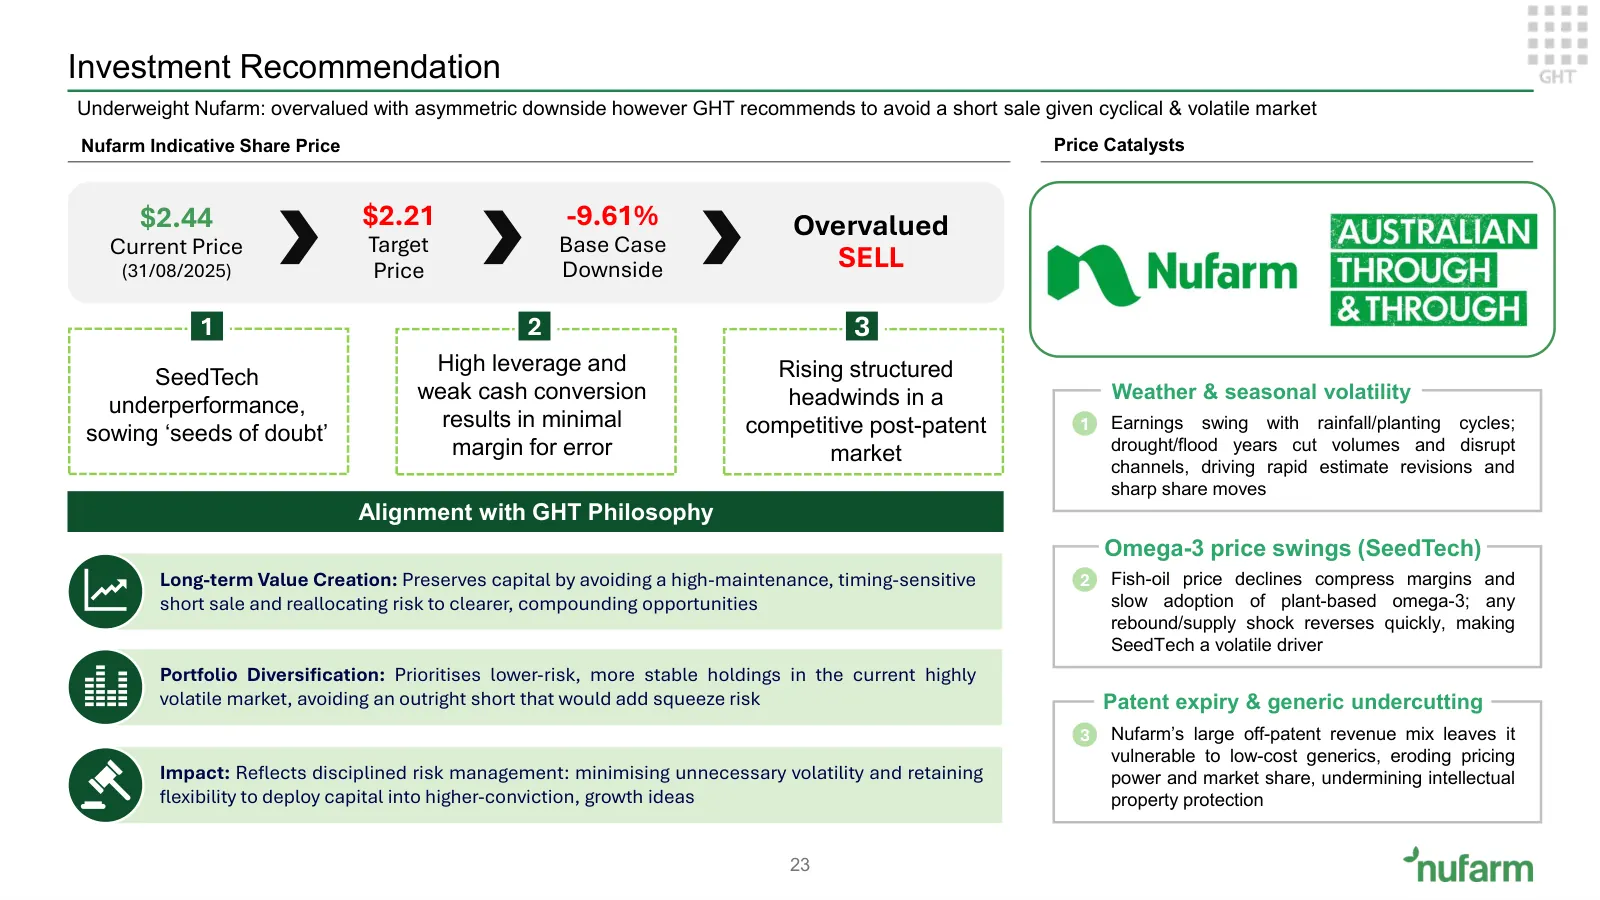
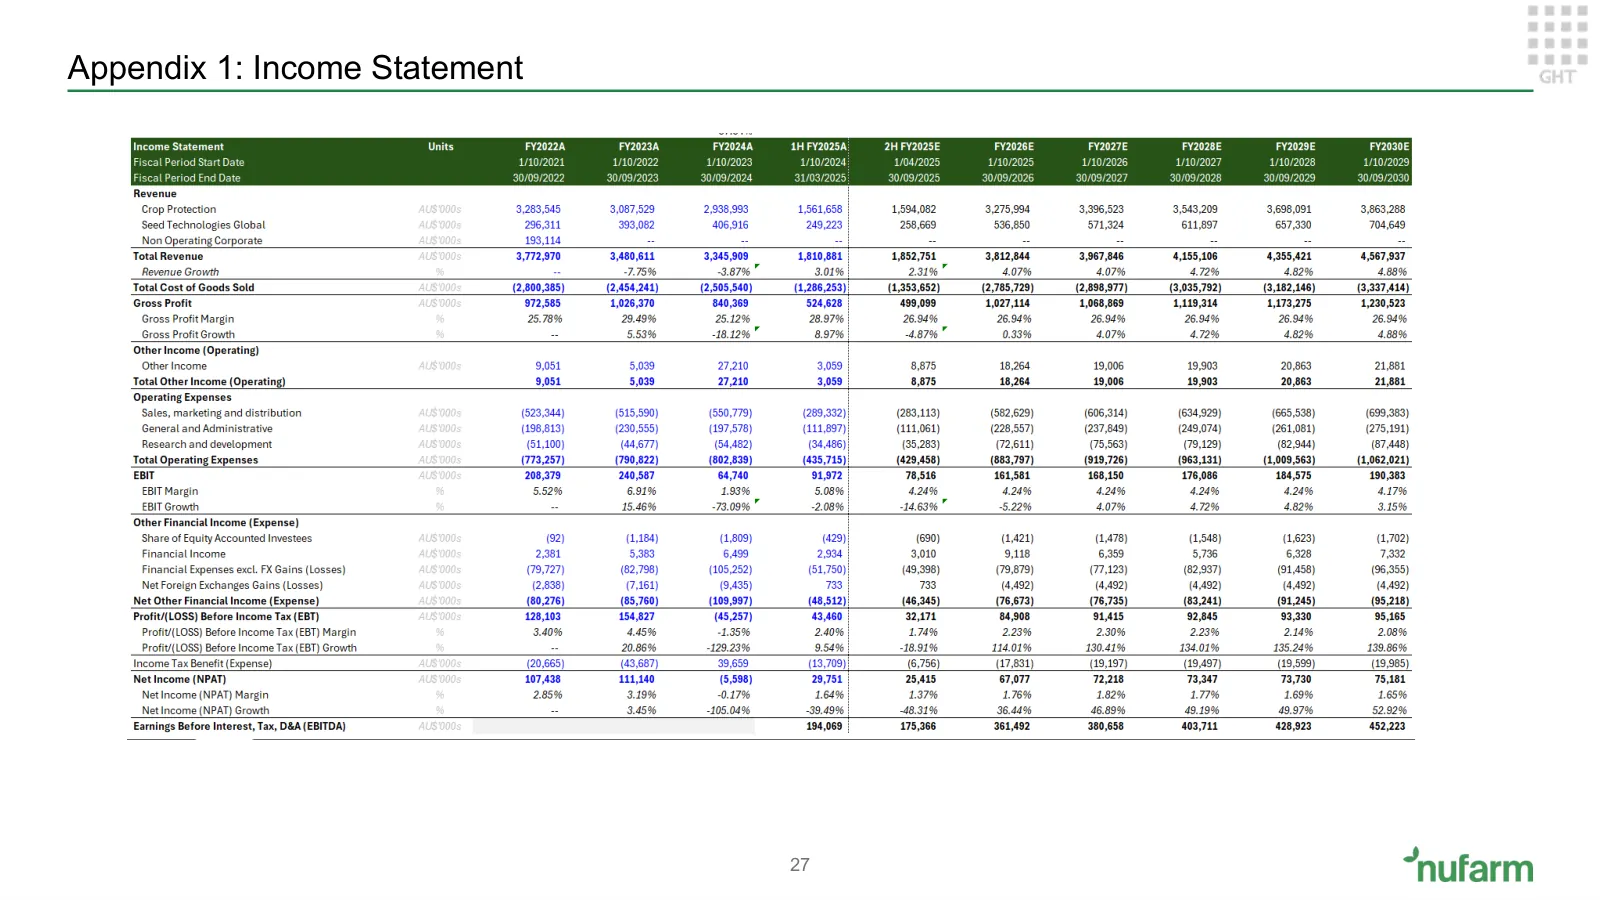
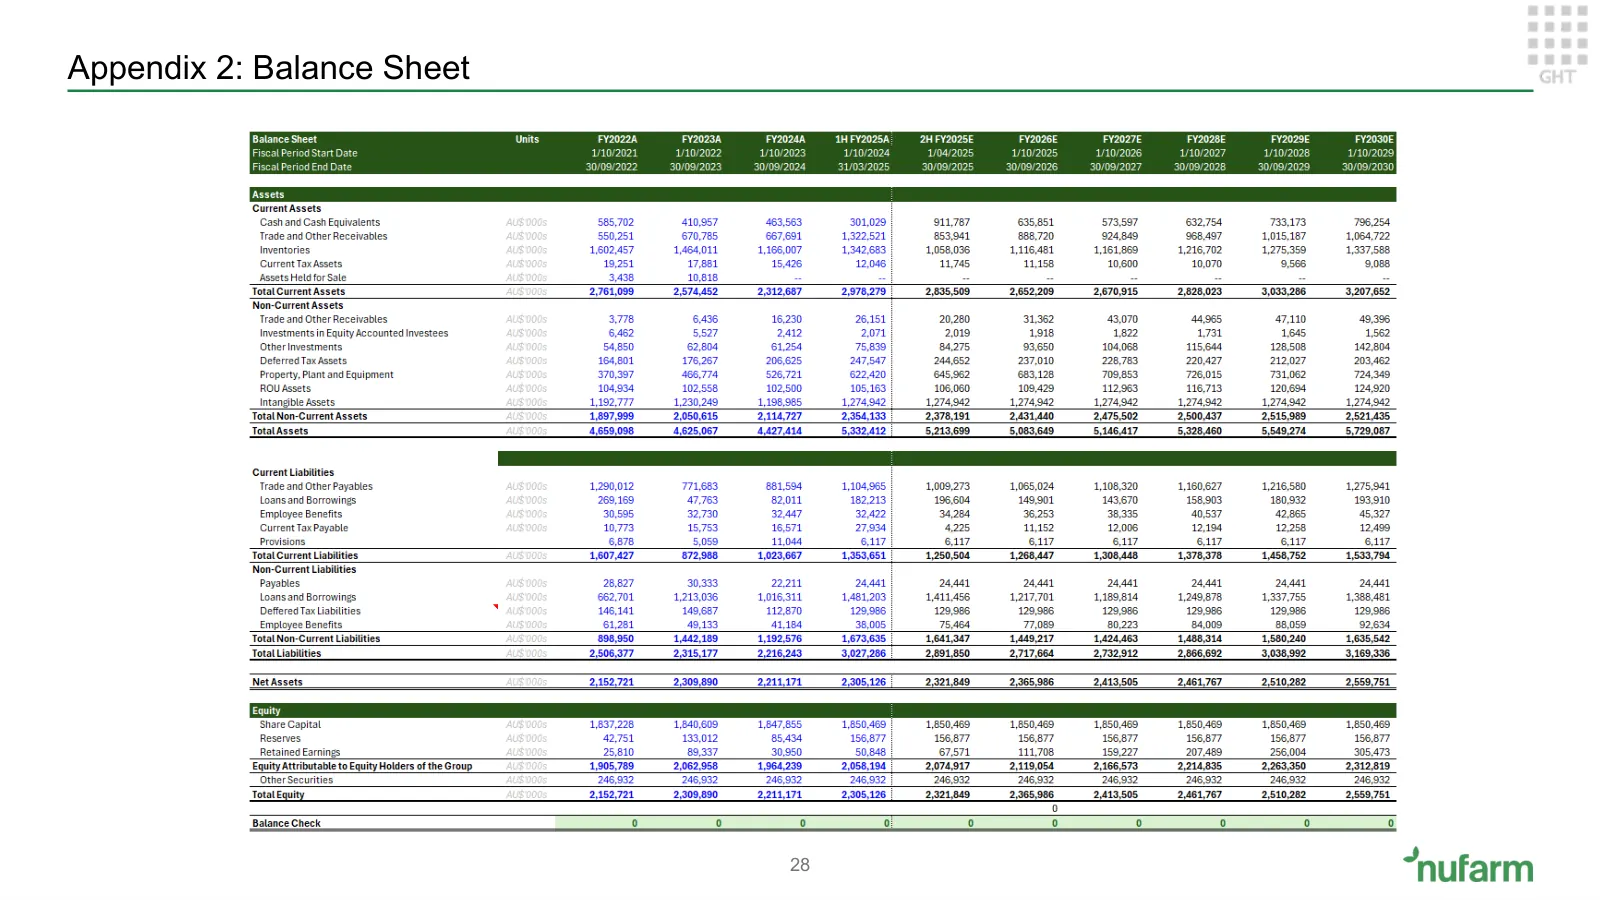
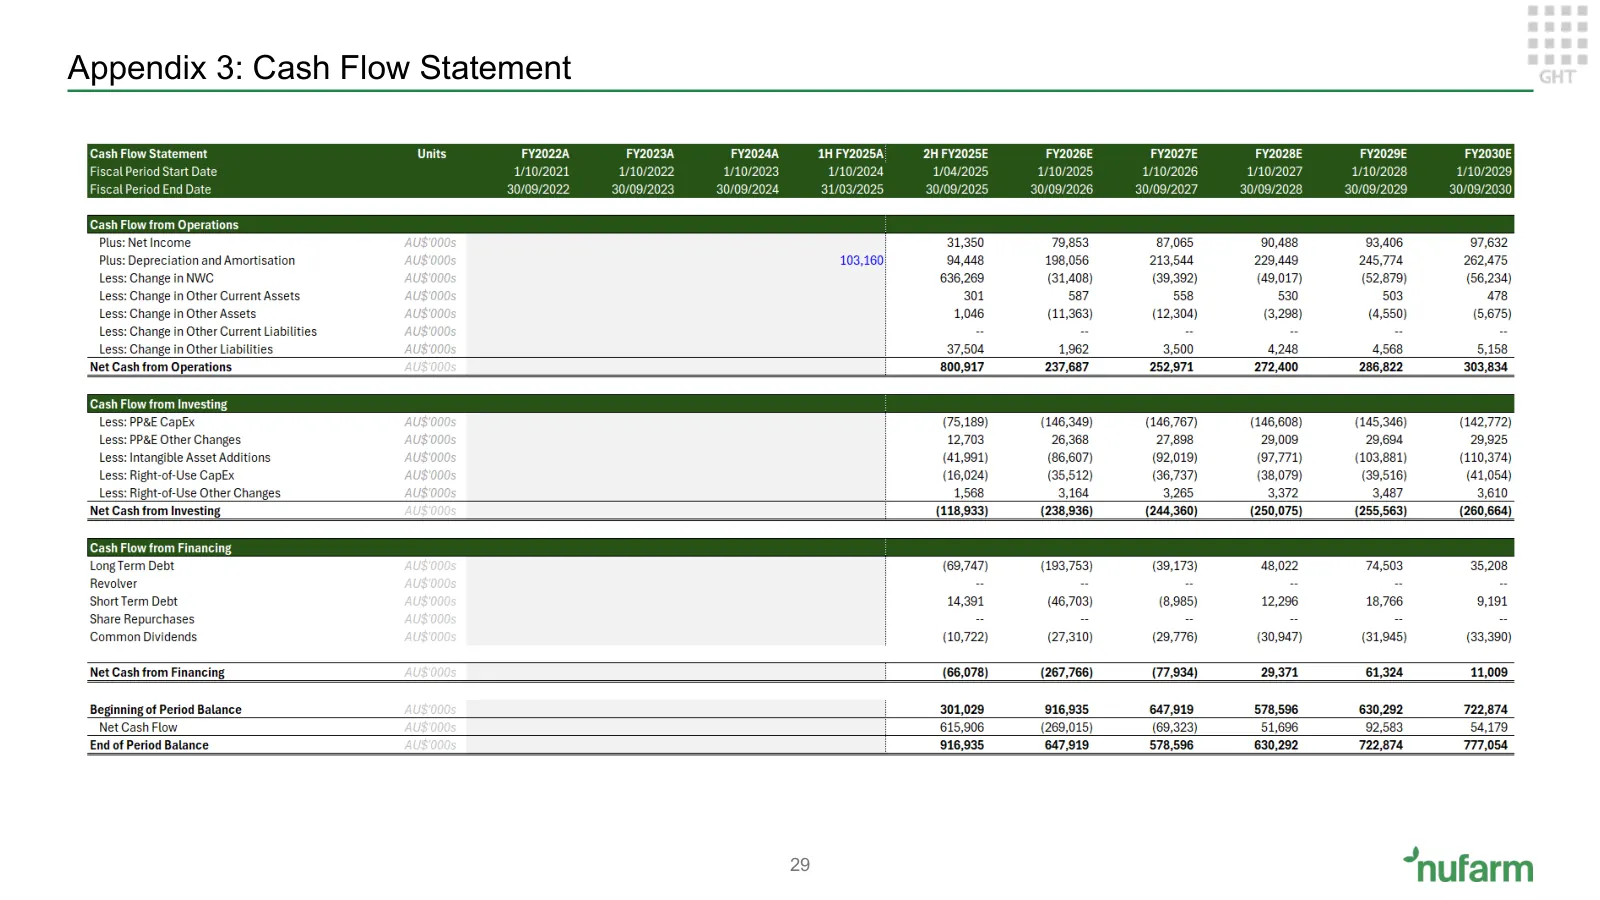
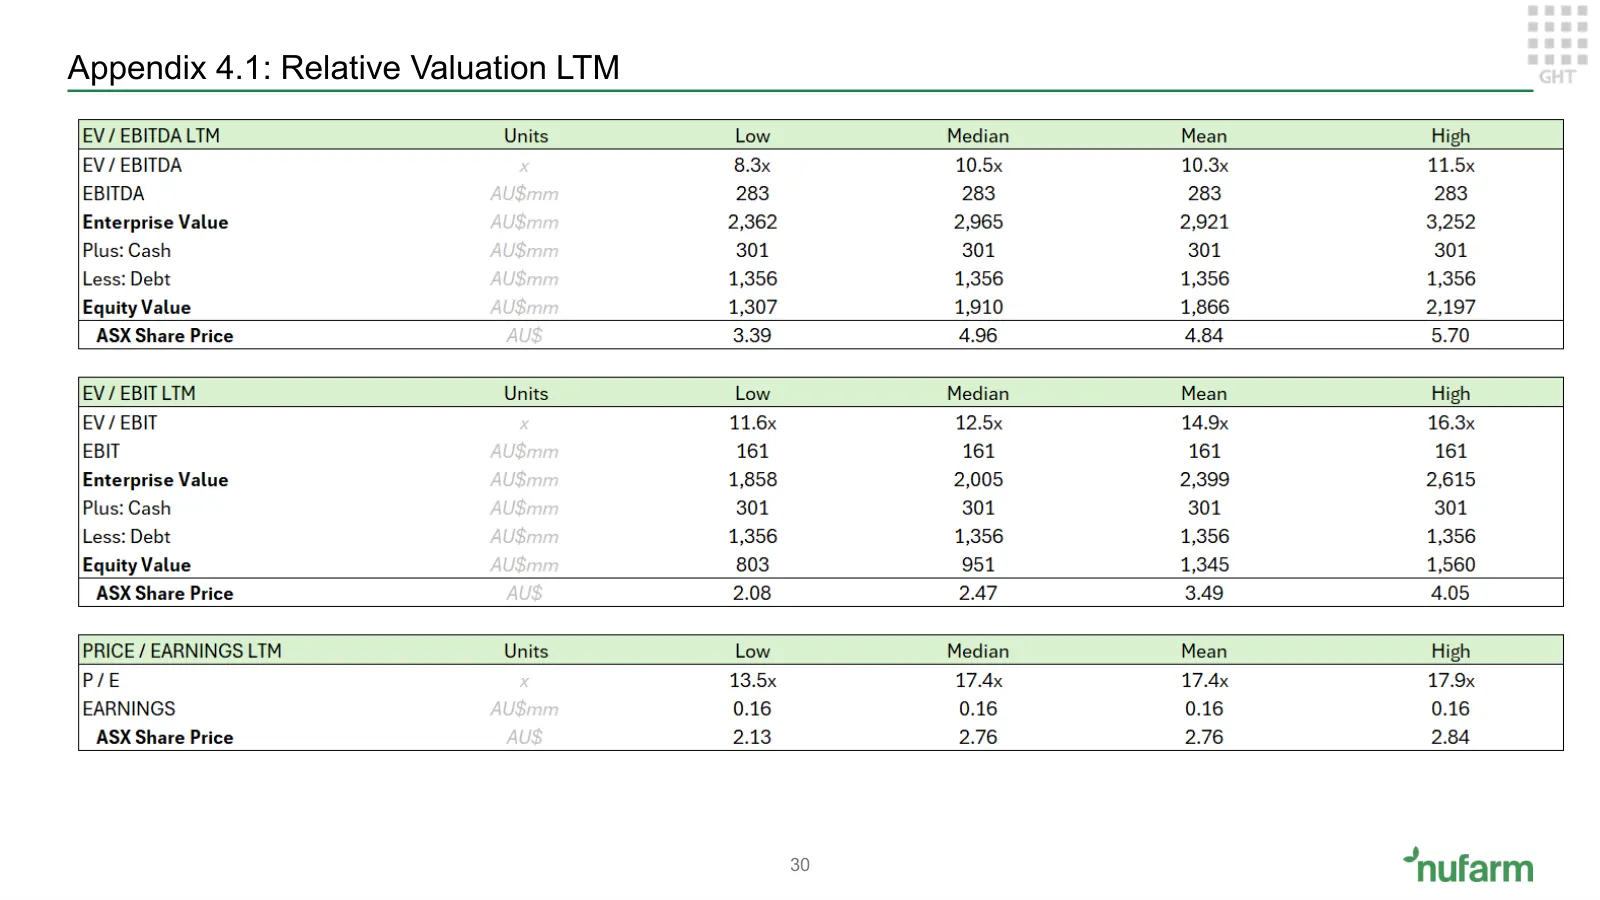
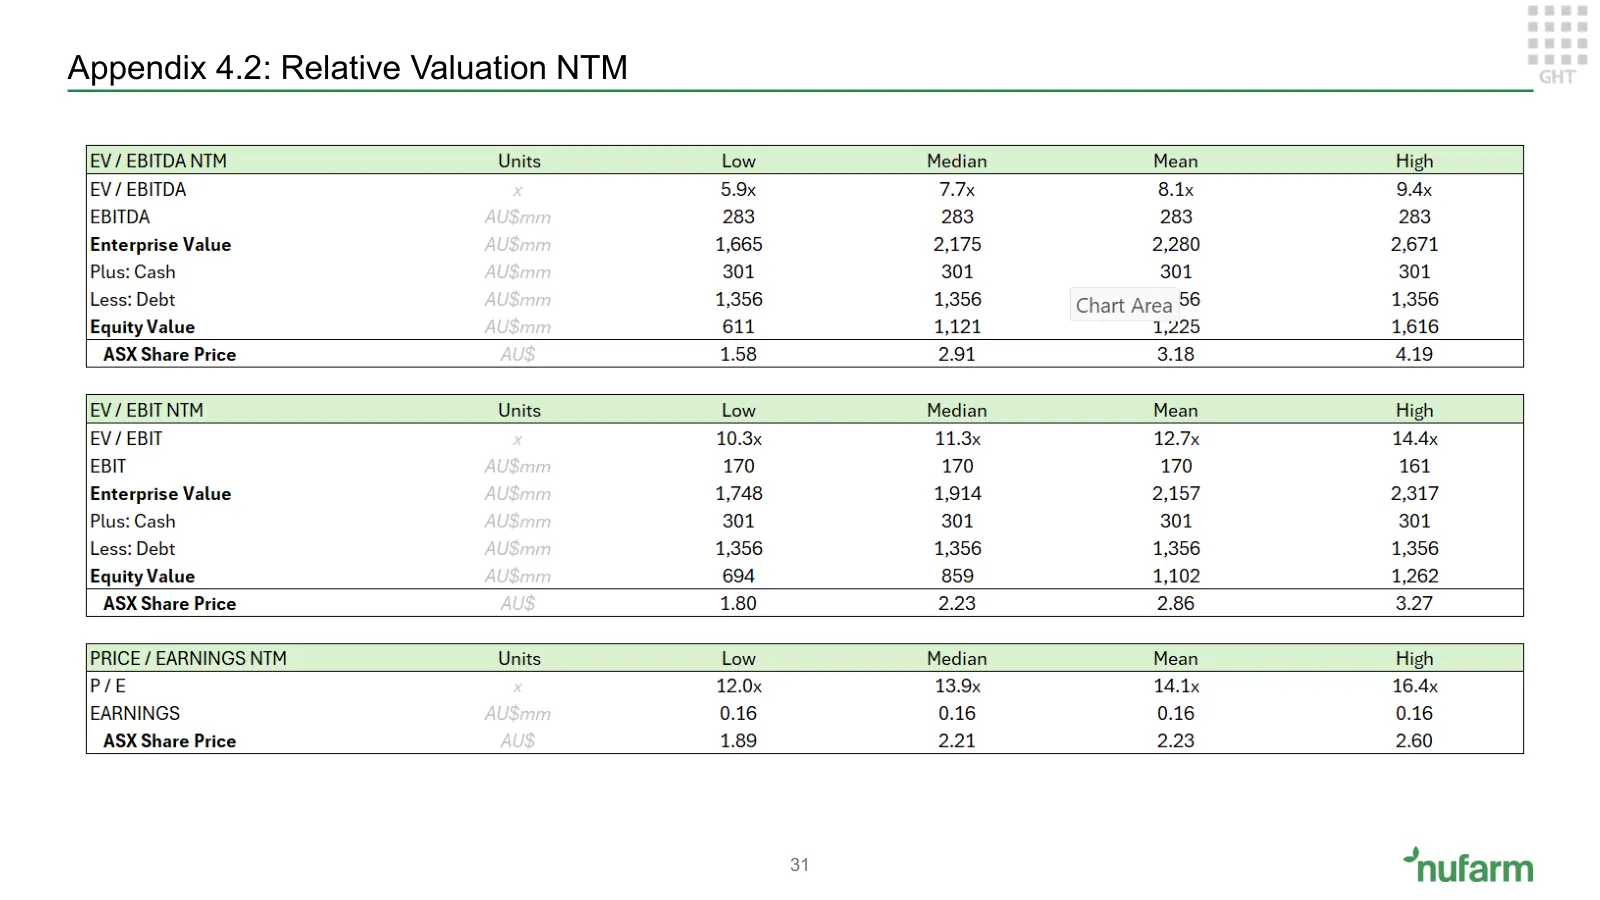
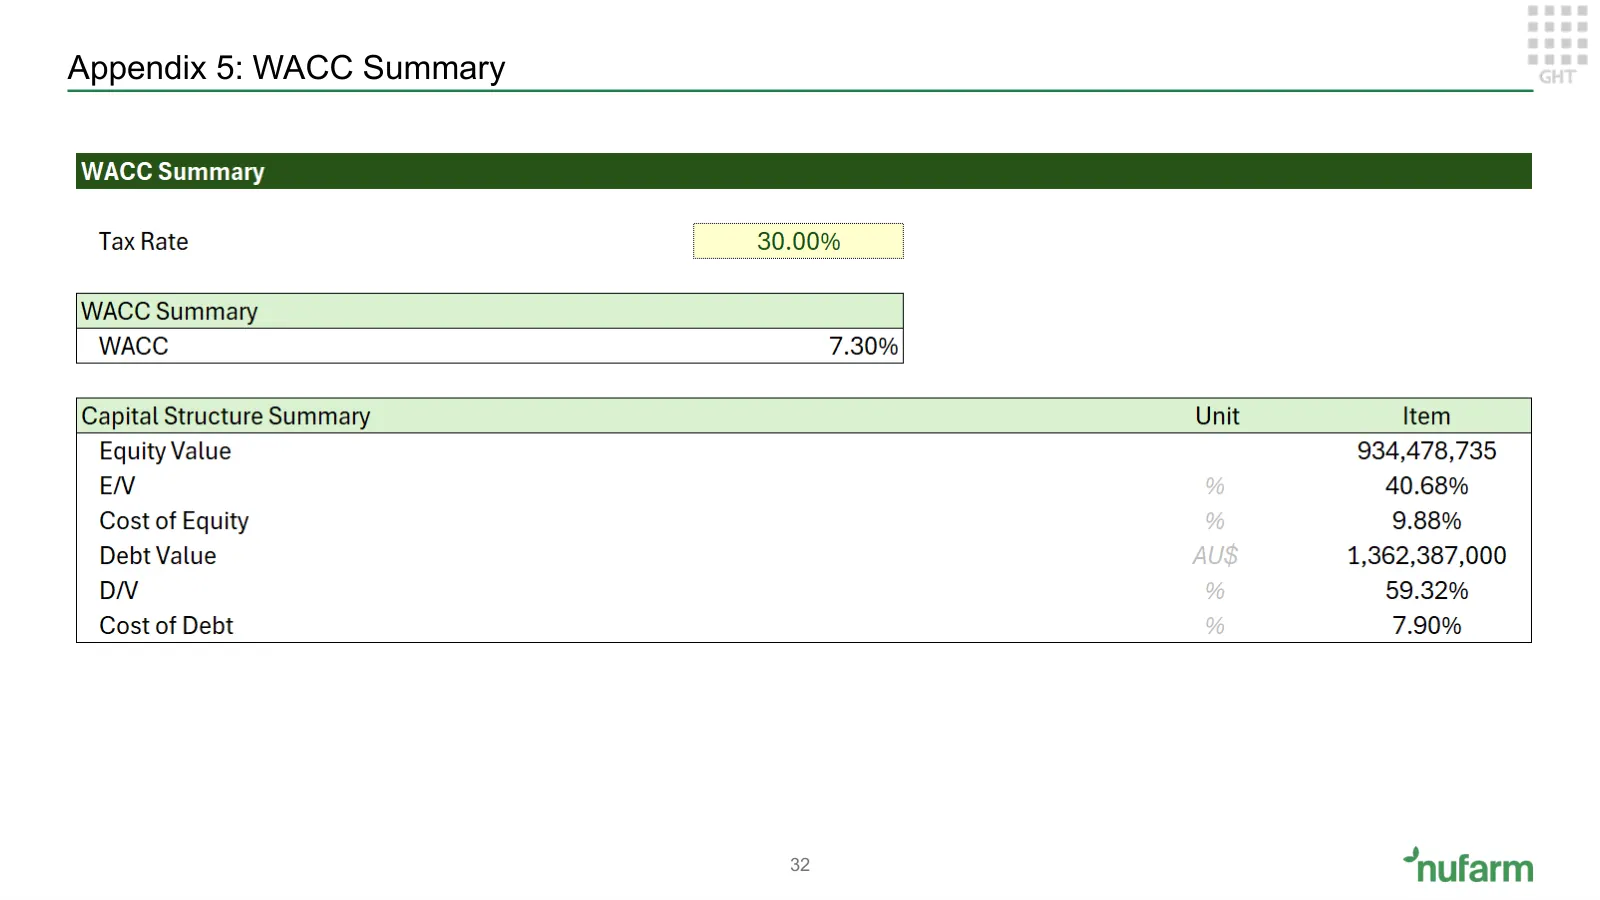
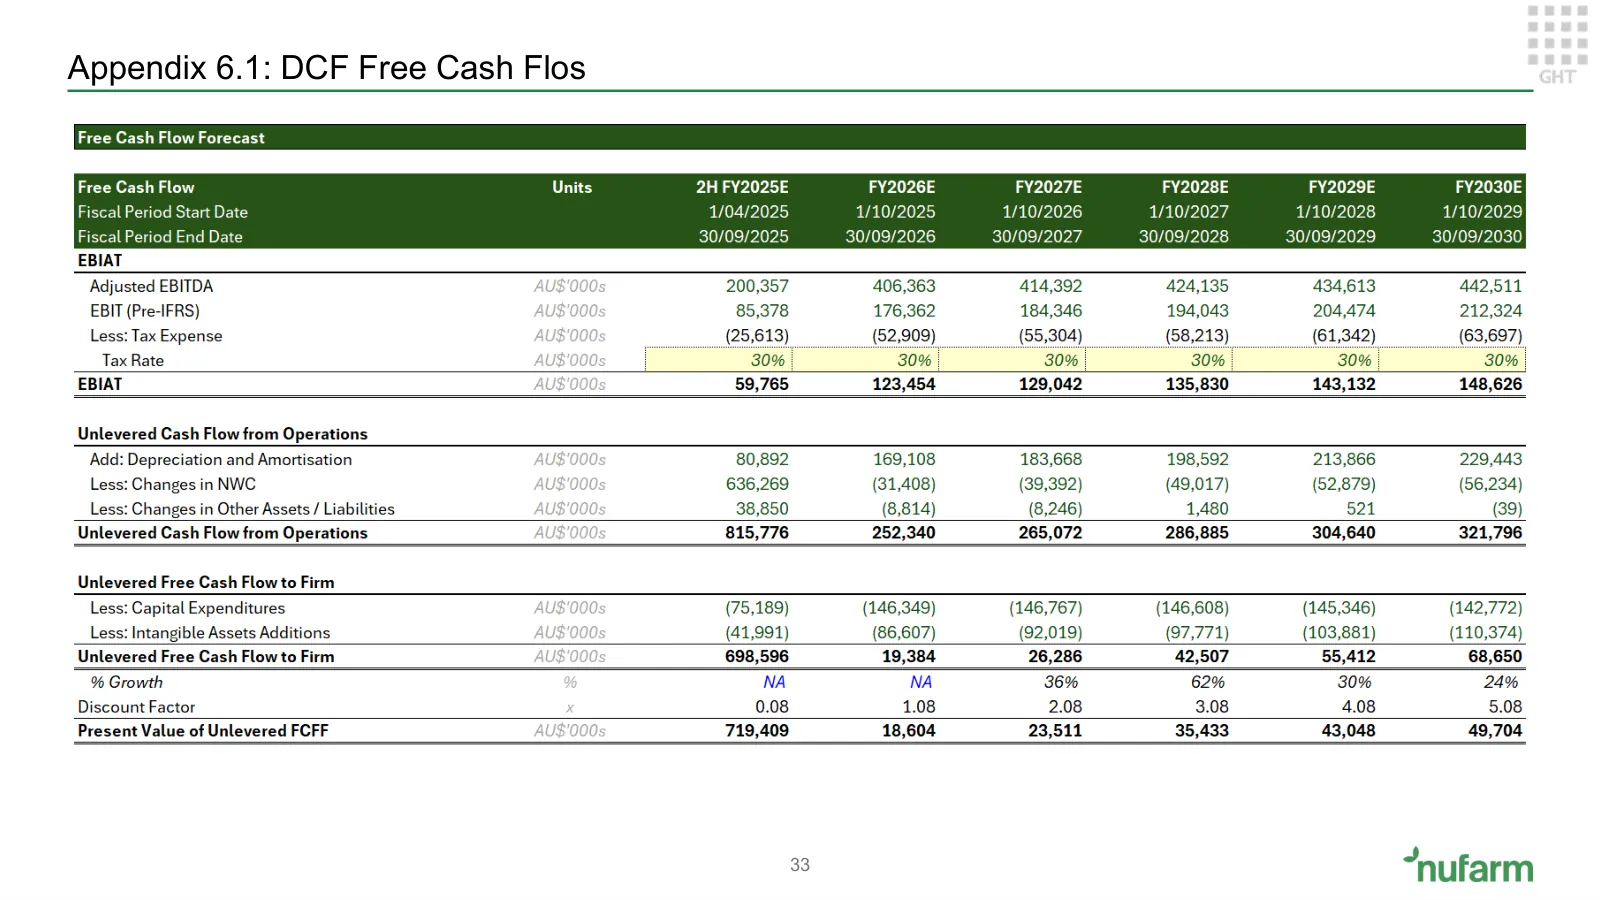
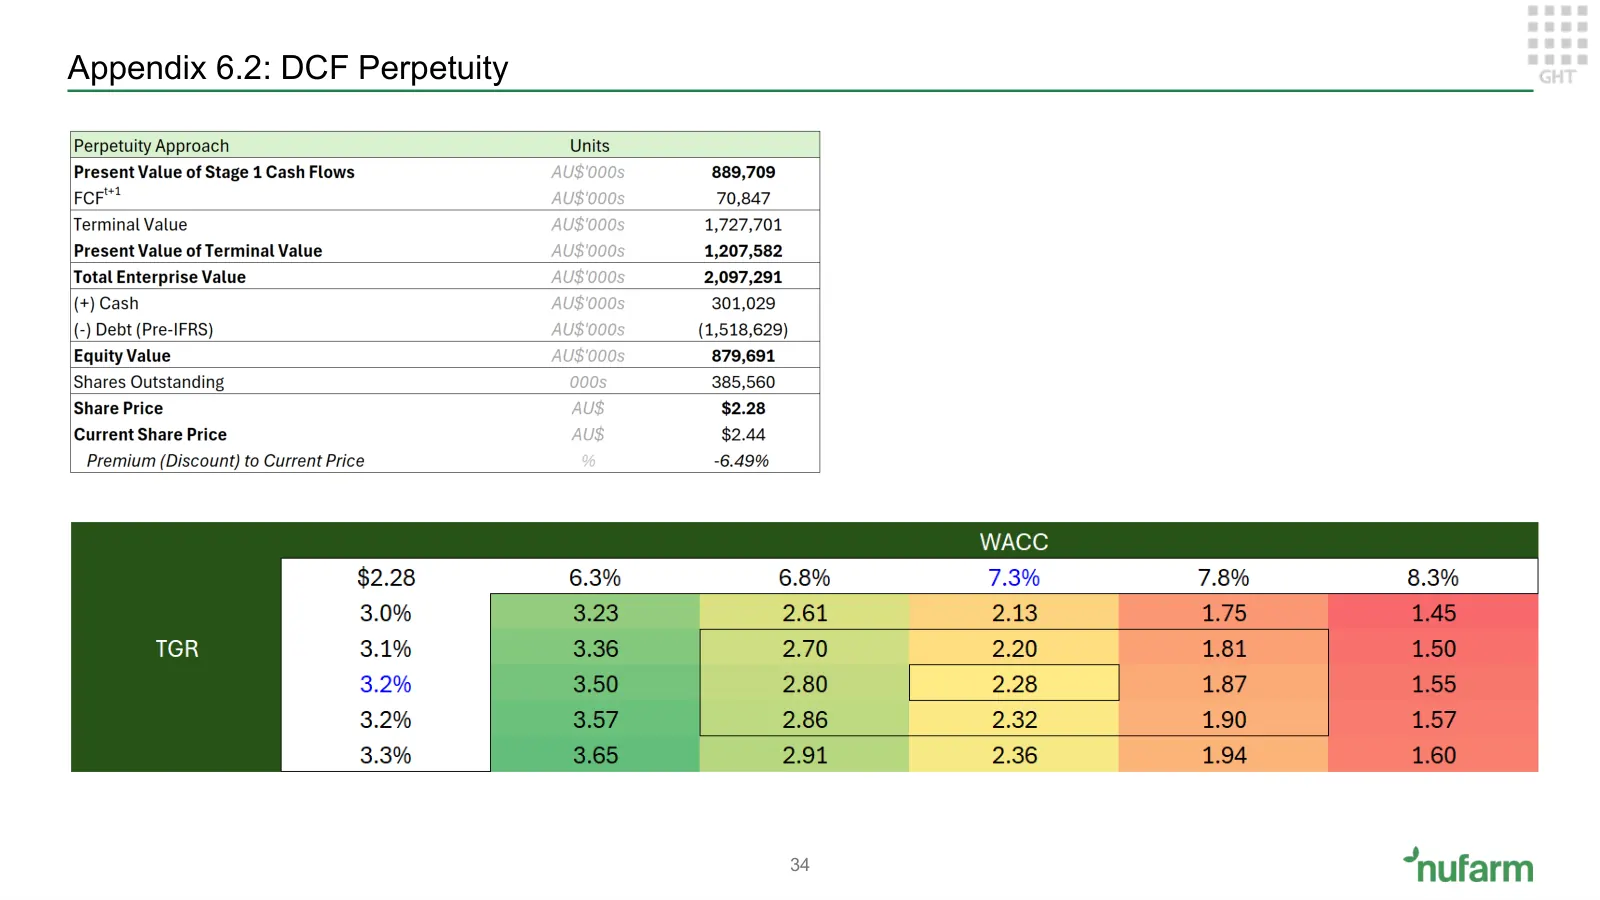
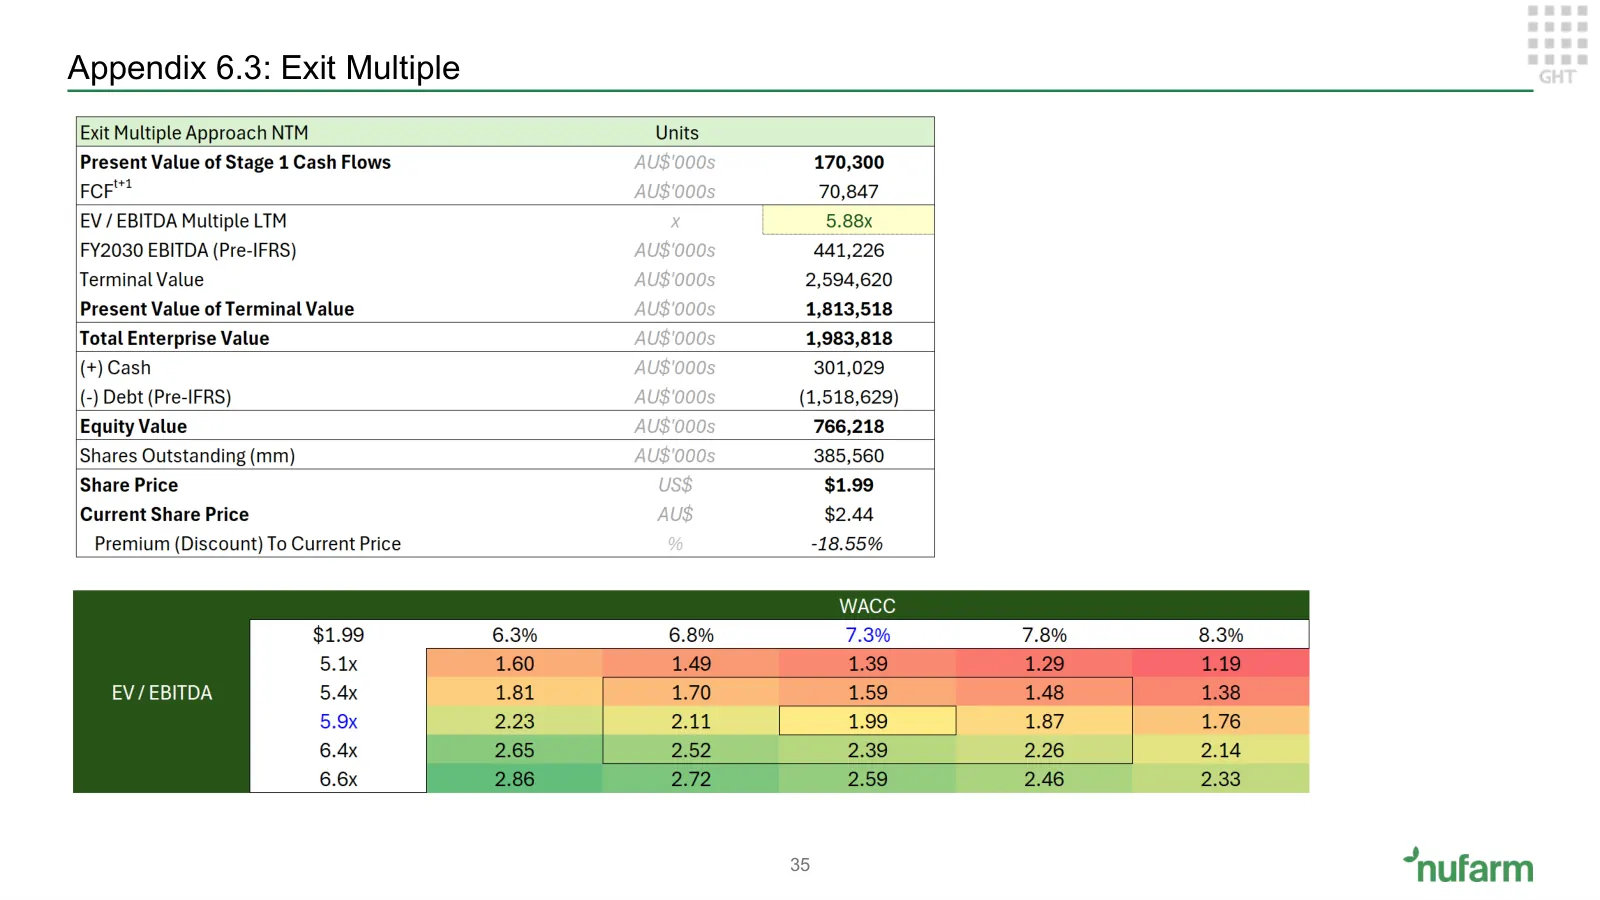
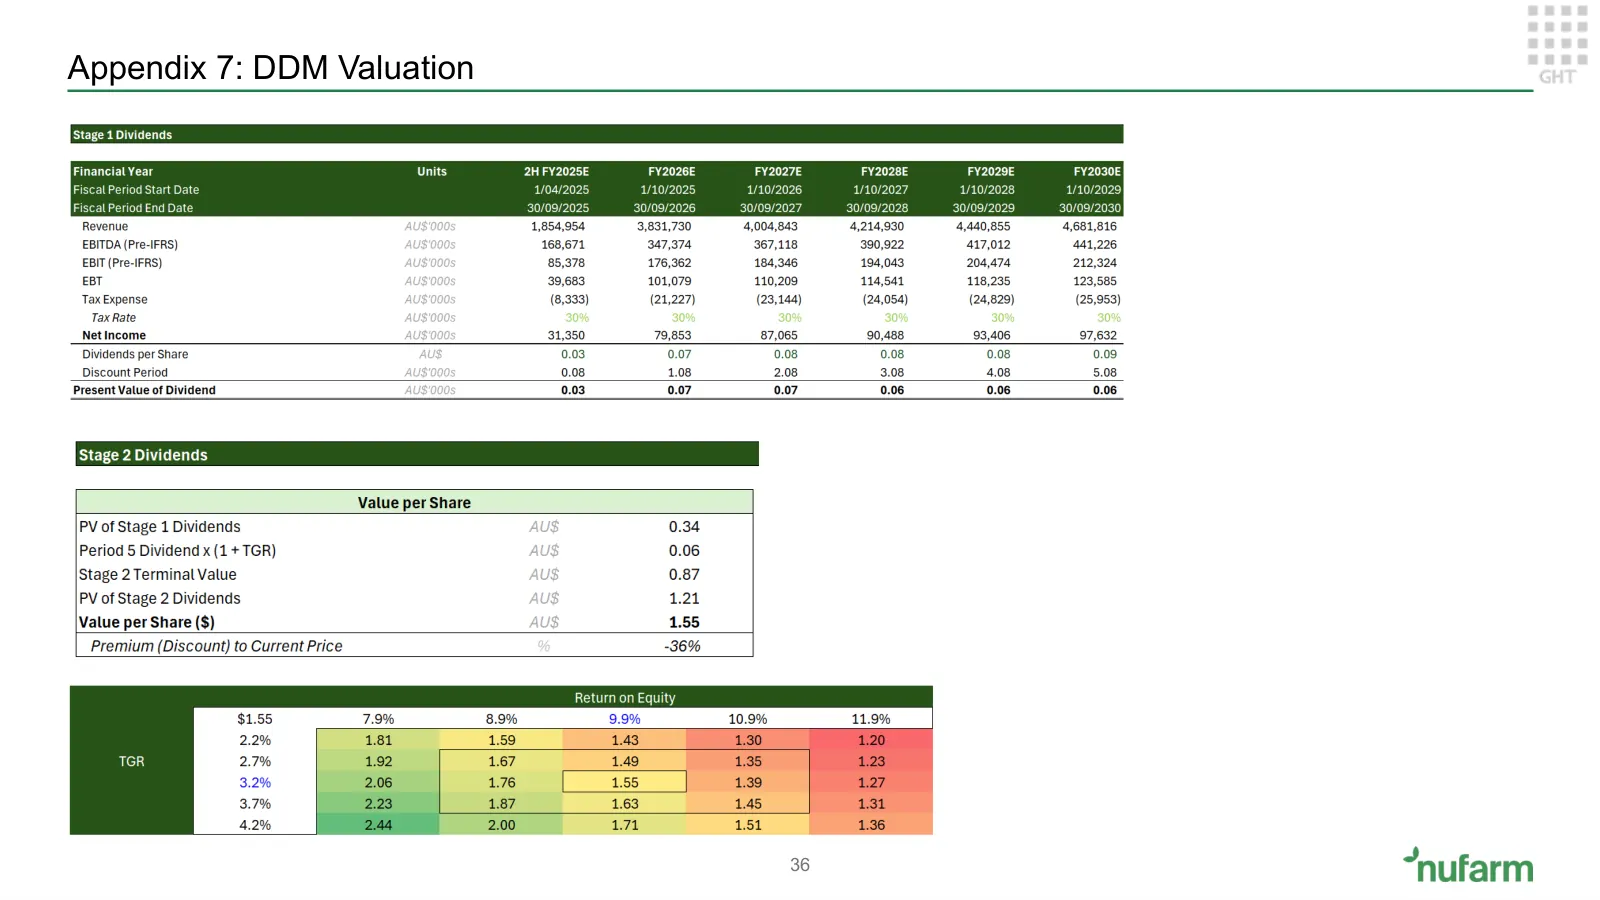
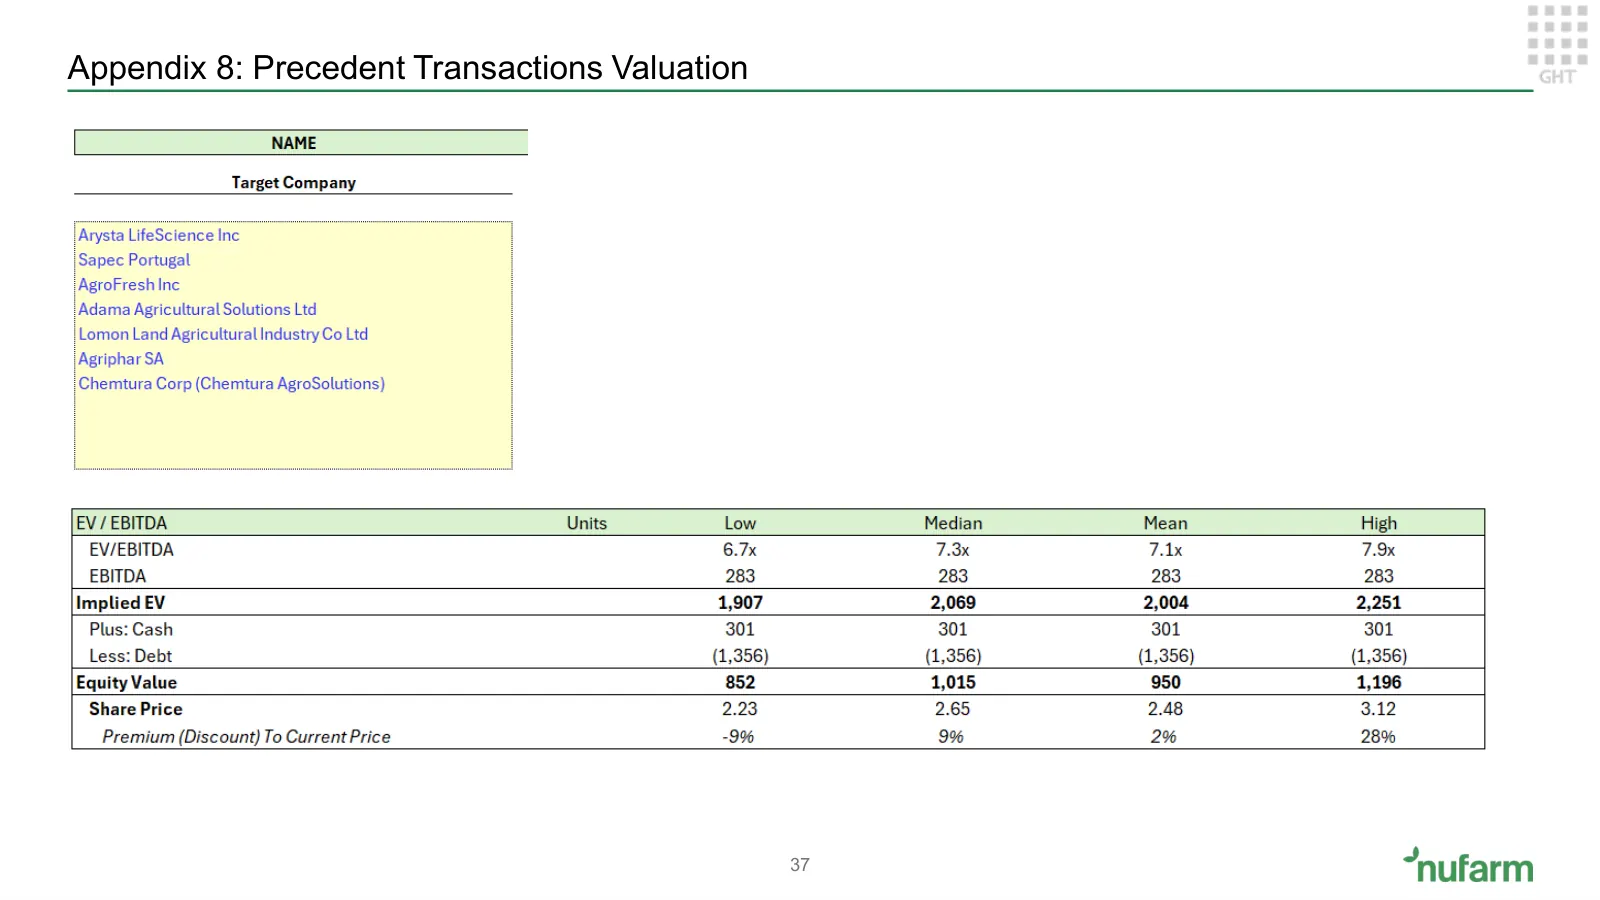
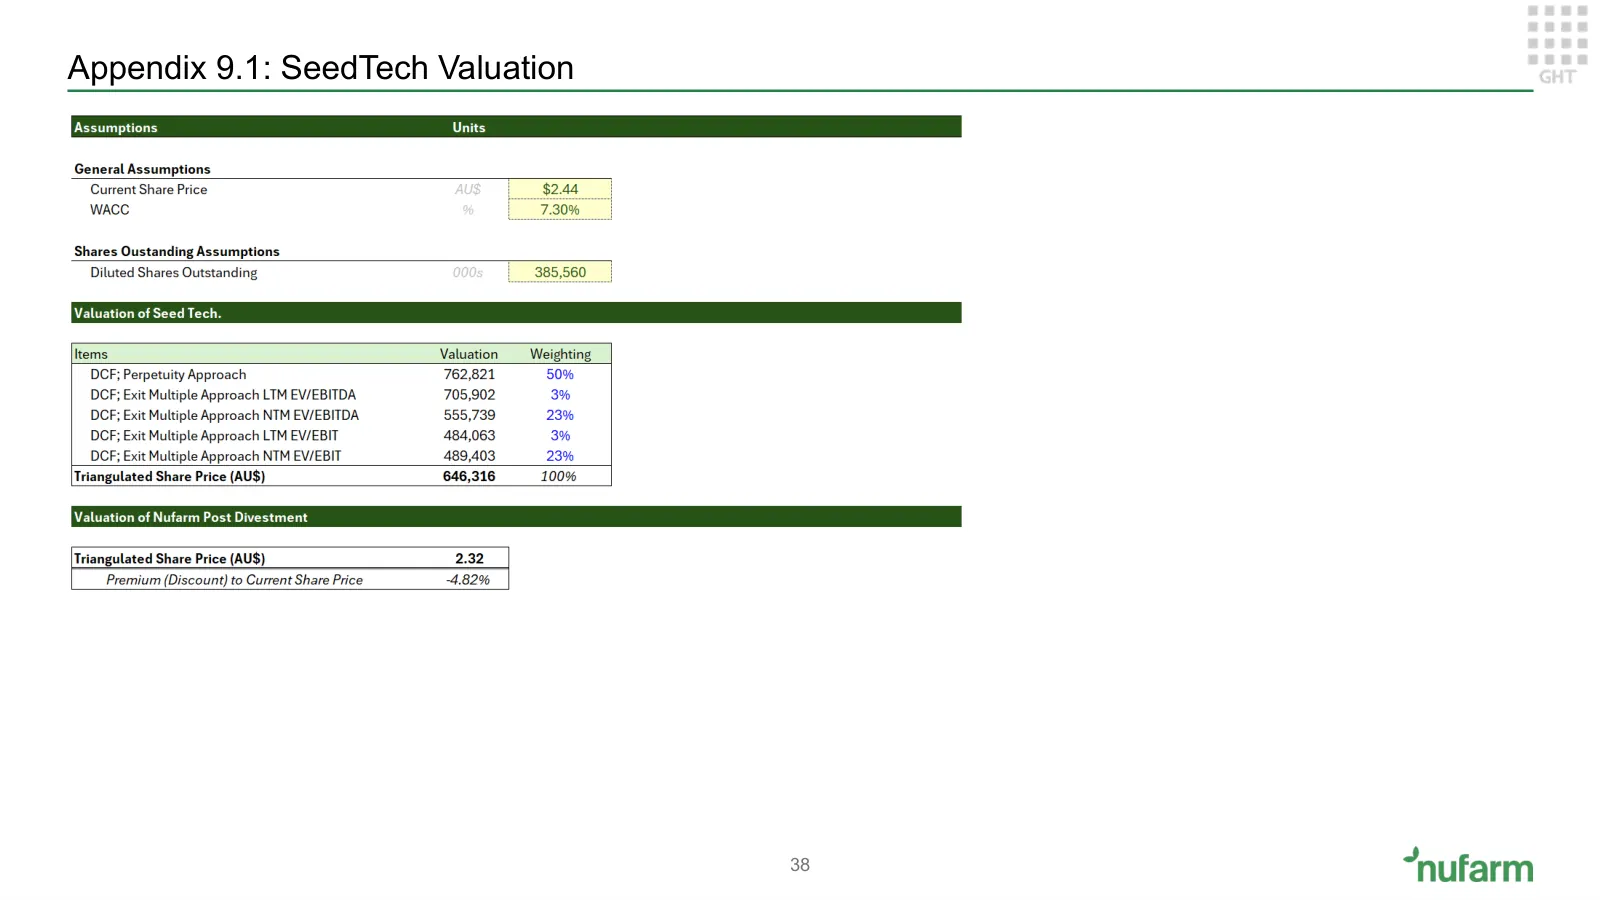
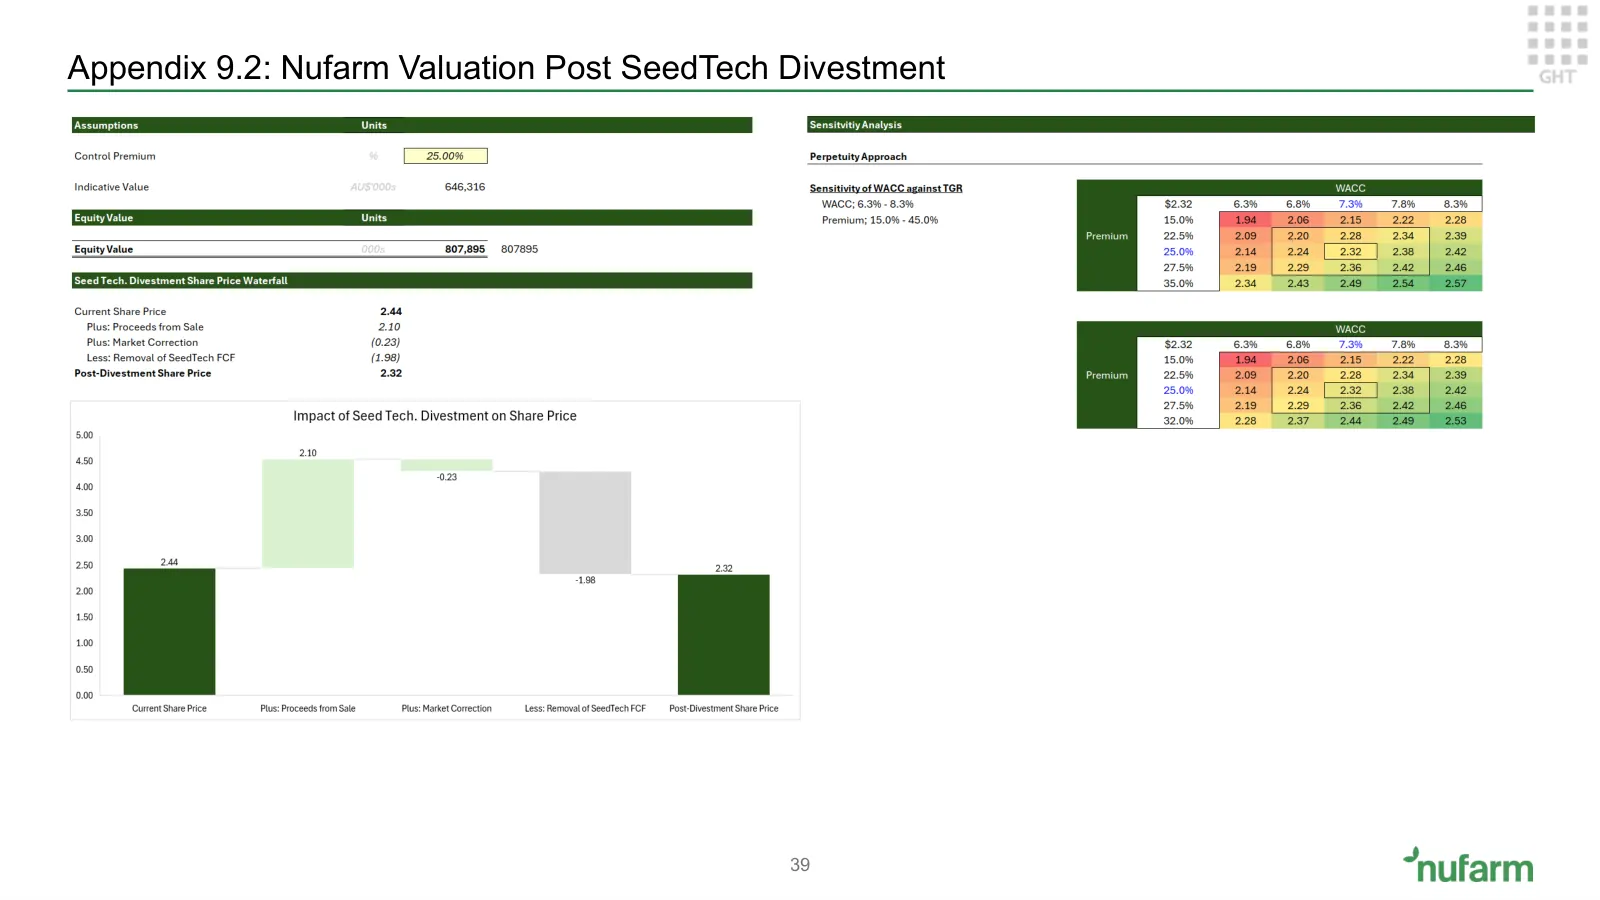
Nufarm: sell at A$2.44, with a A$2.21 target. August 2025, for a university equity valuation course. A crop protection company with net debt above its own target and a seed technology arm that has not reached scale. Valued by DCF and peer multiples, with a scenario for selling the seed business. Team of four.
Infrastructure
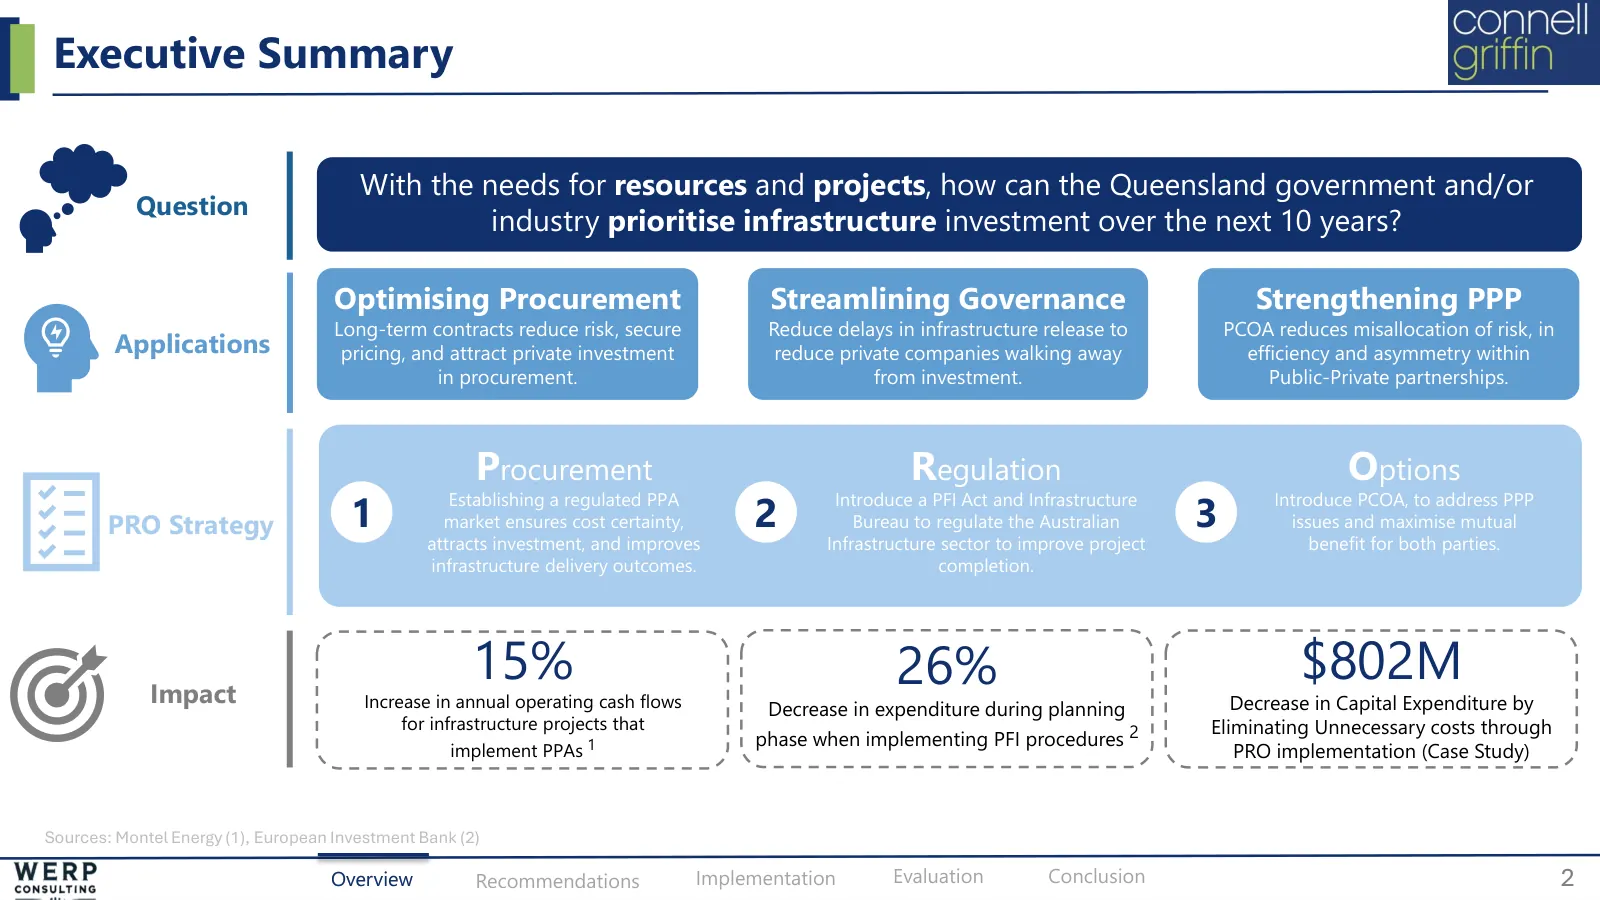
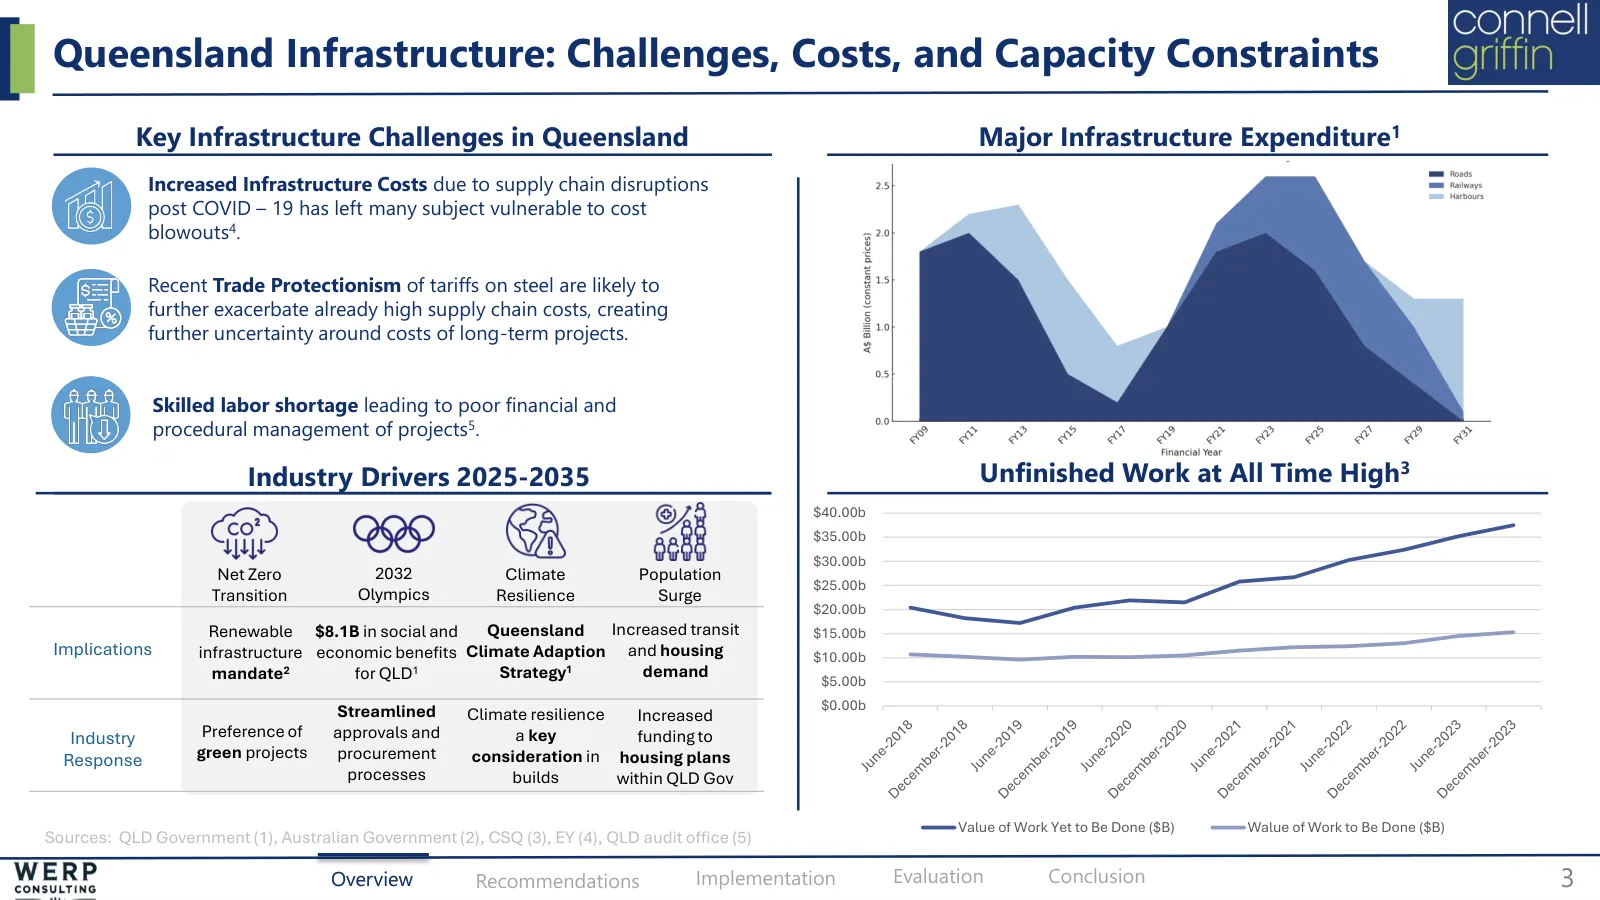
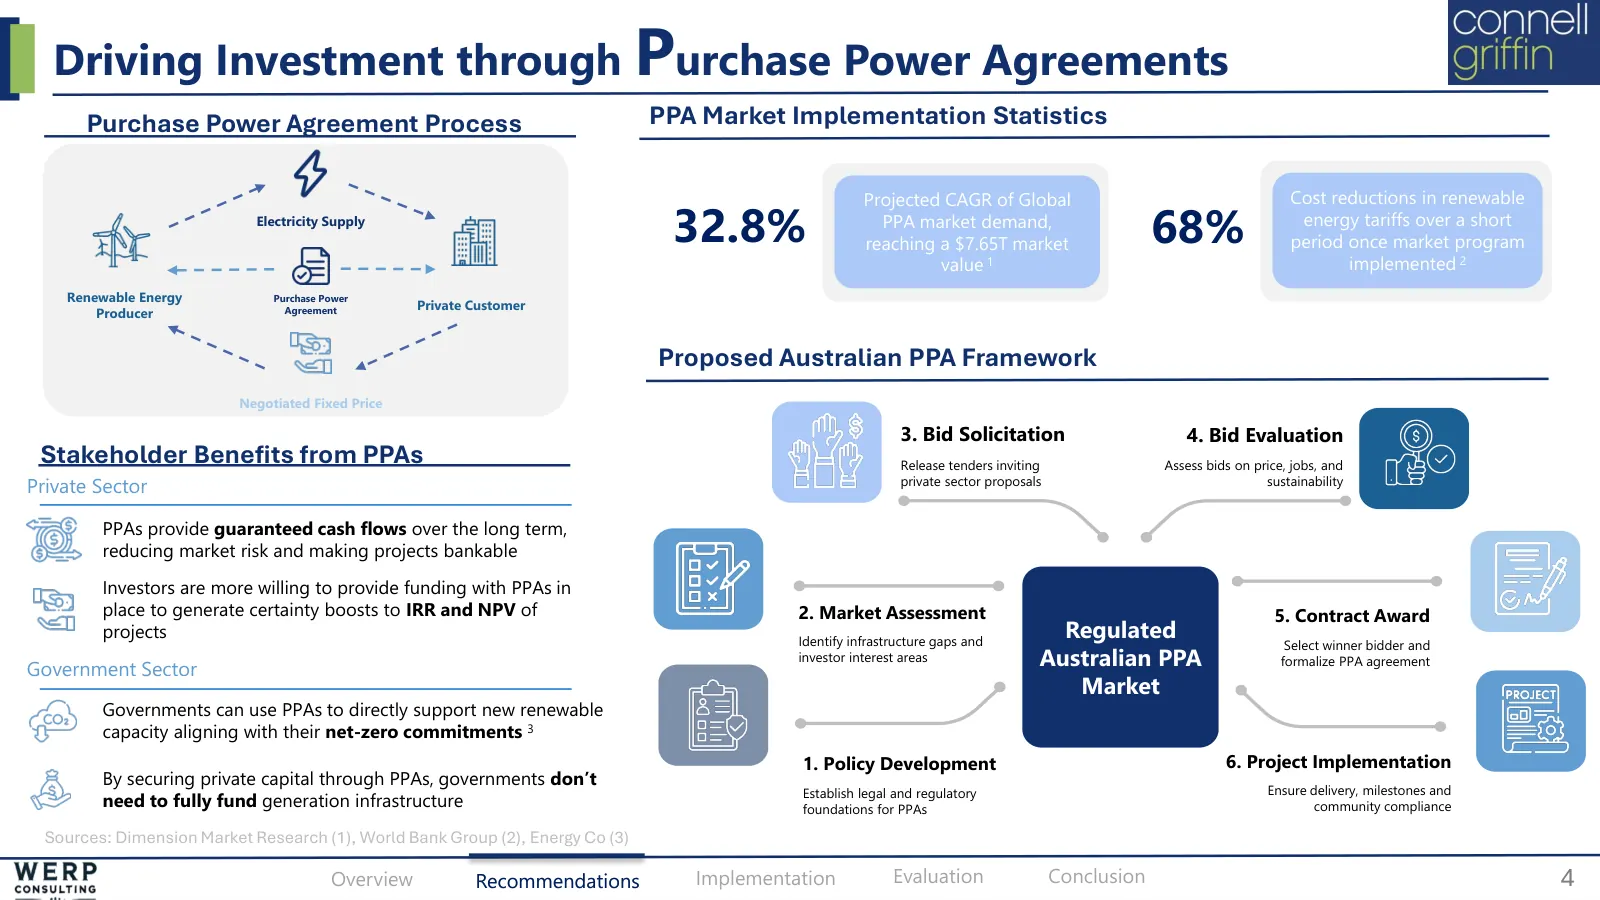
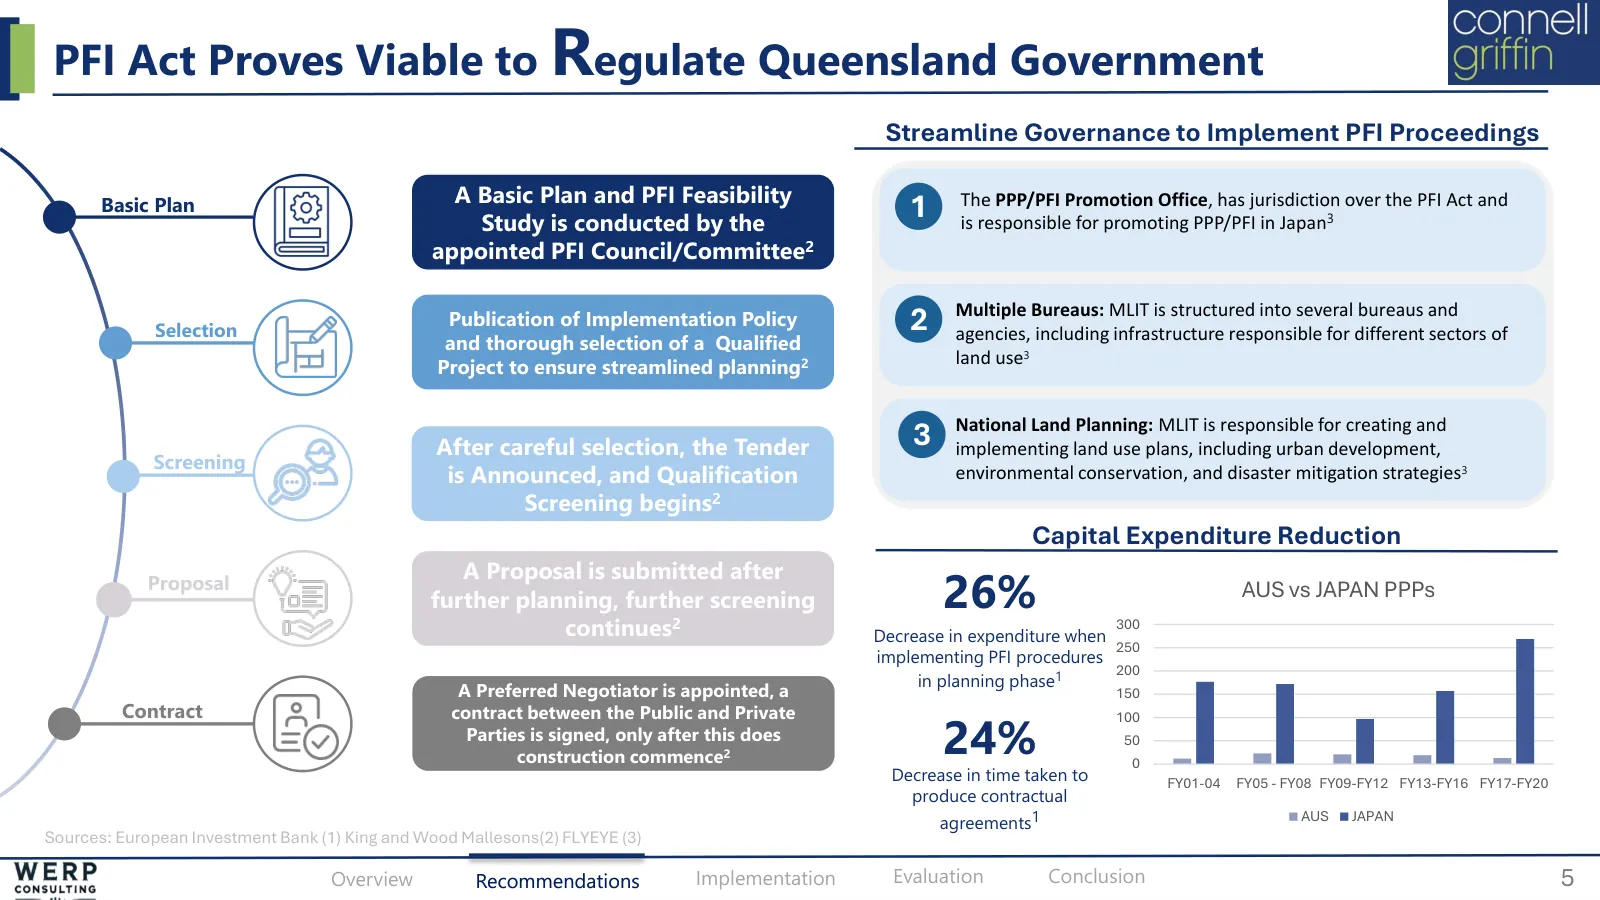
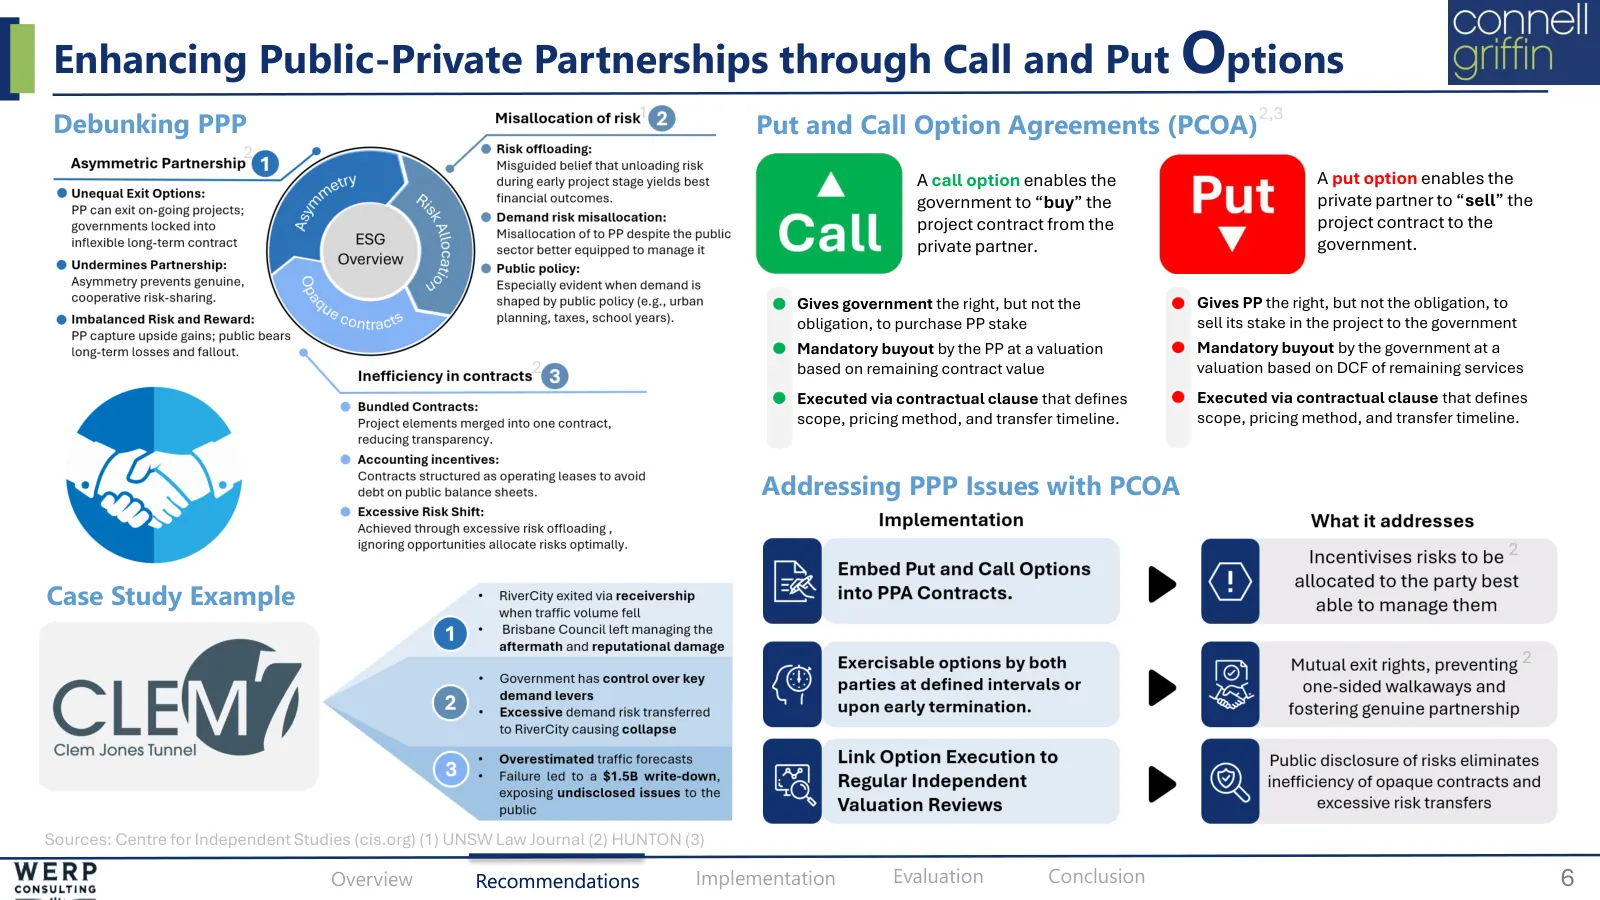
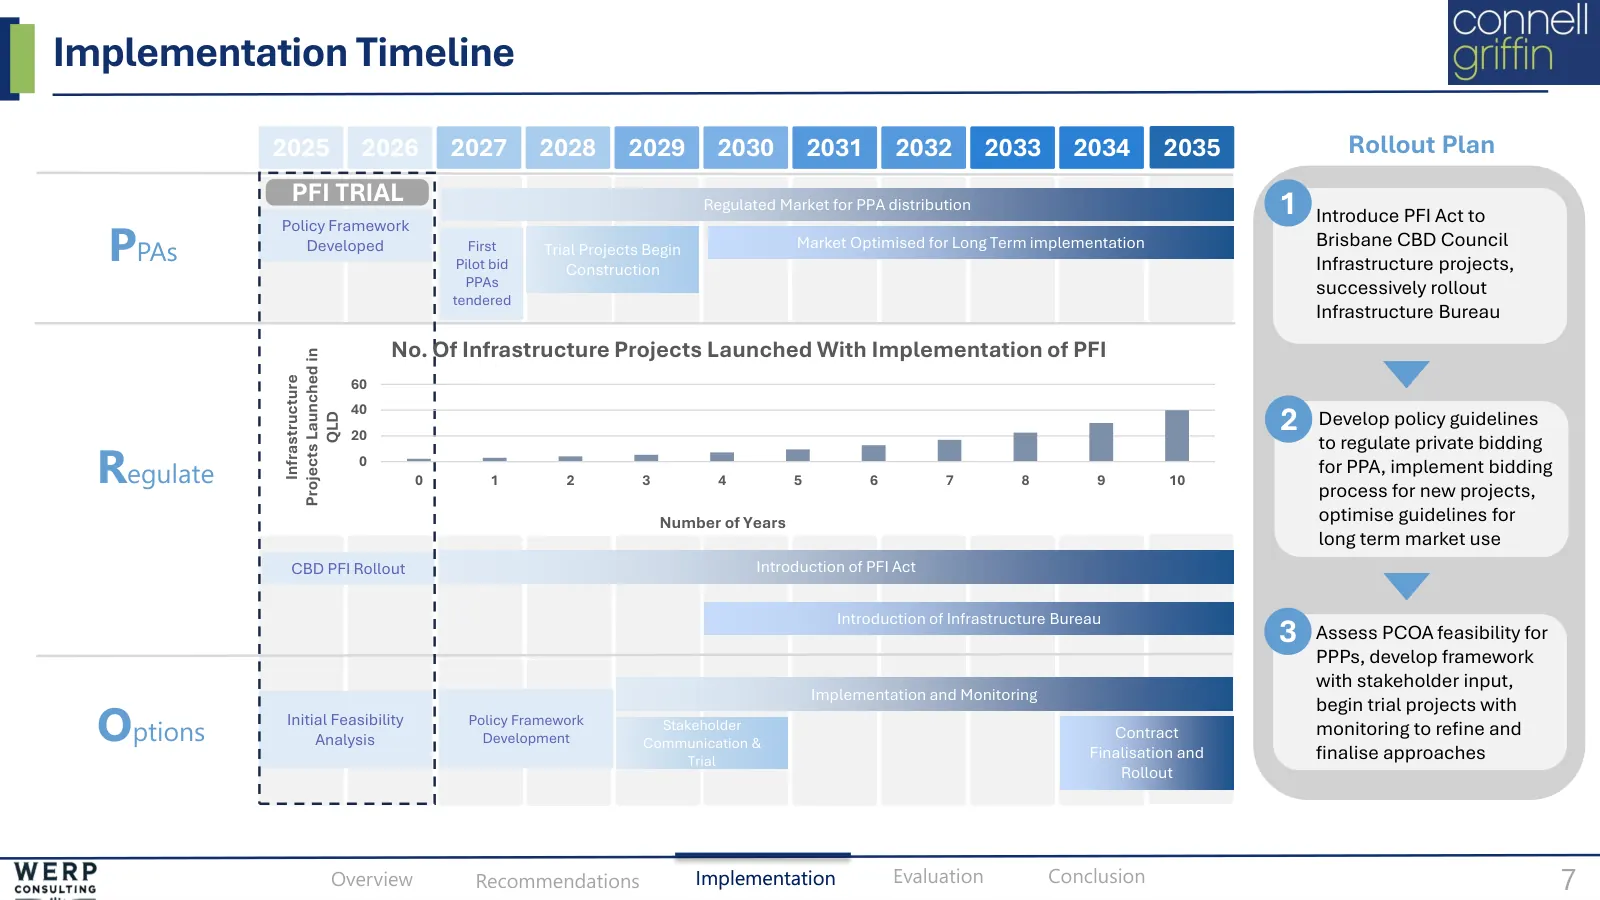
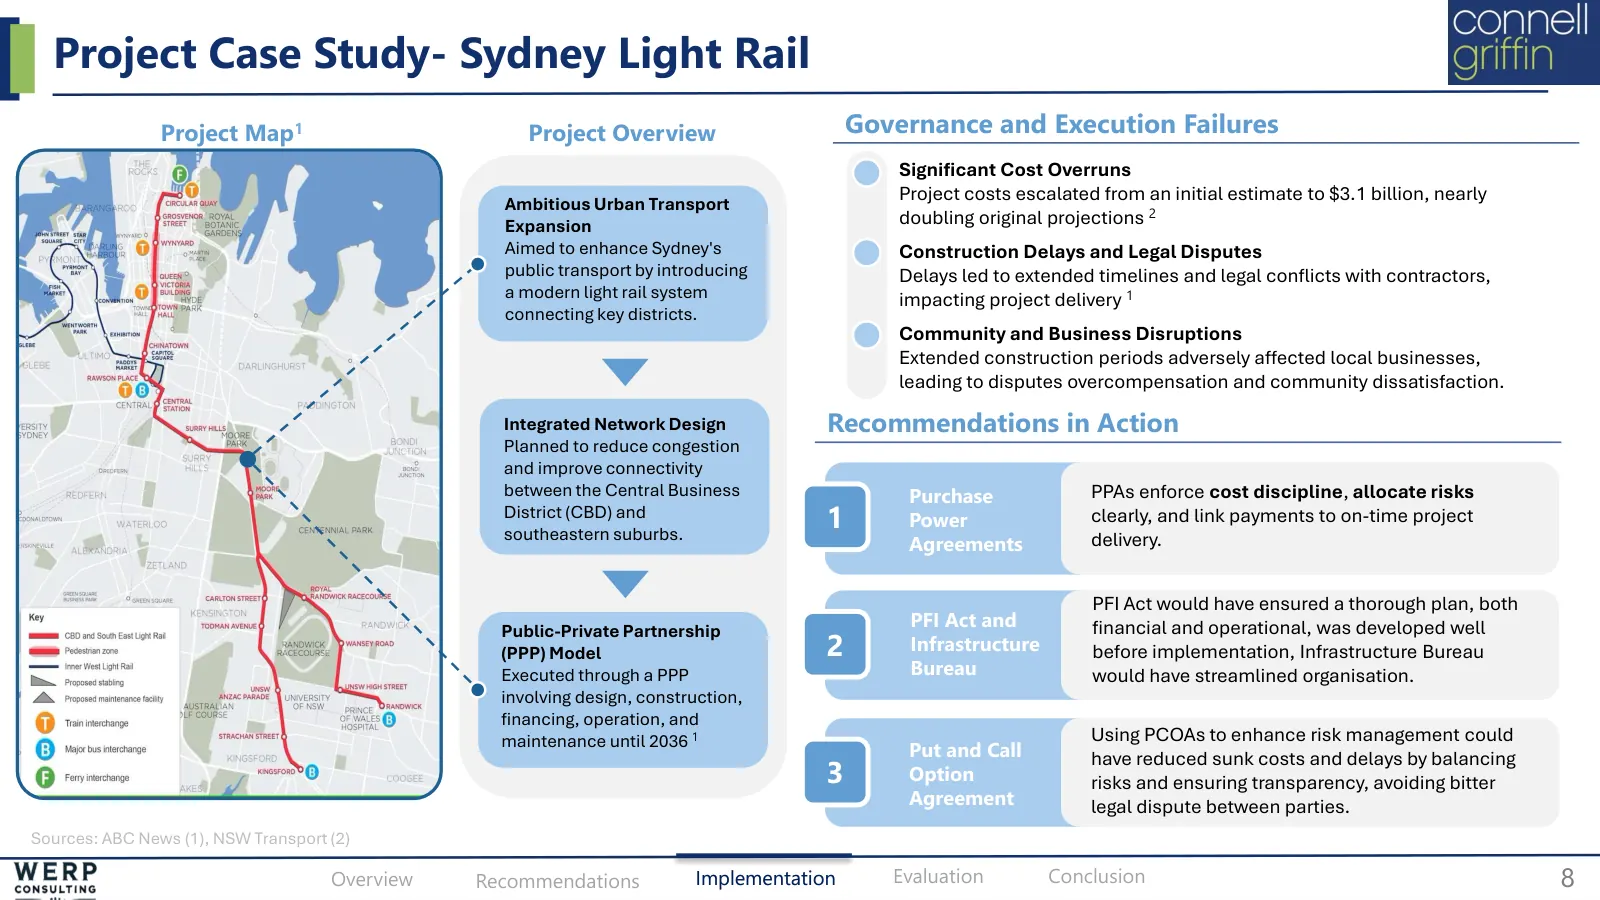
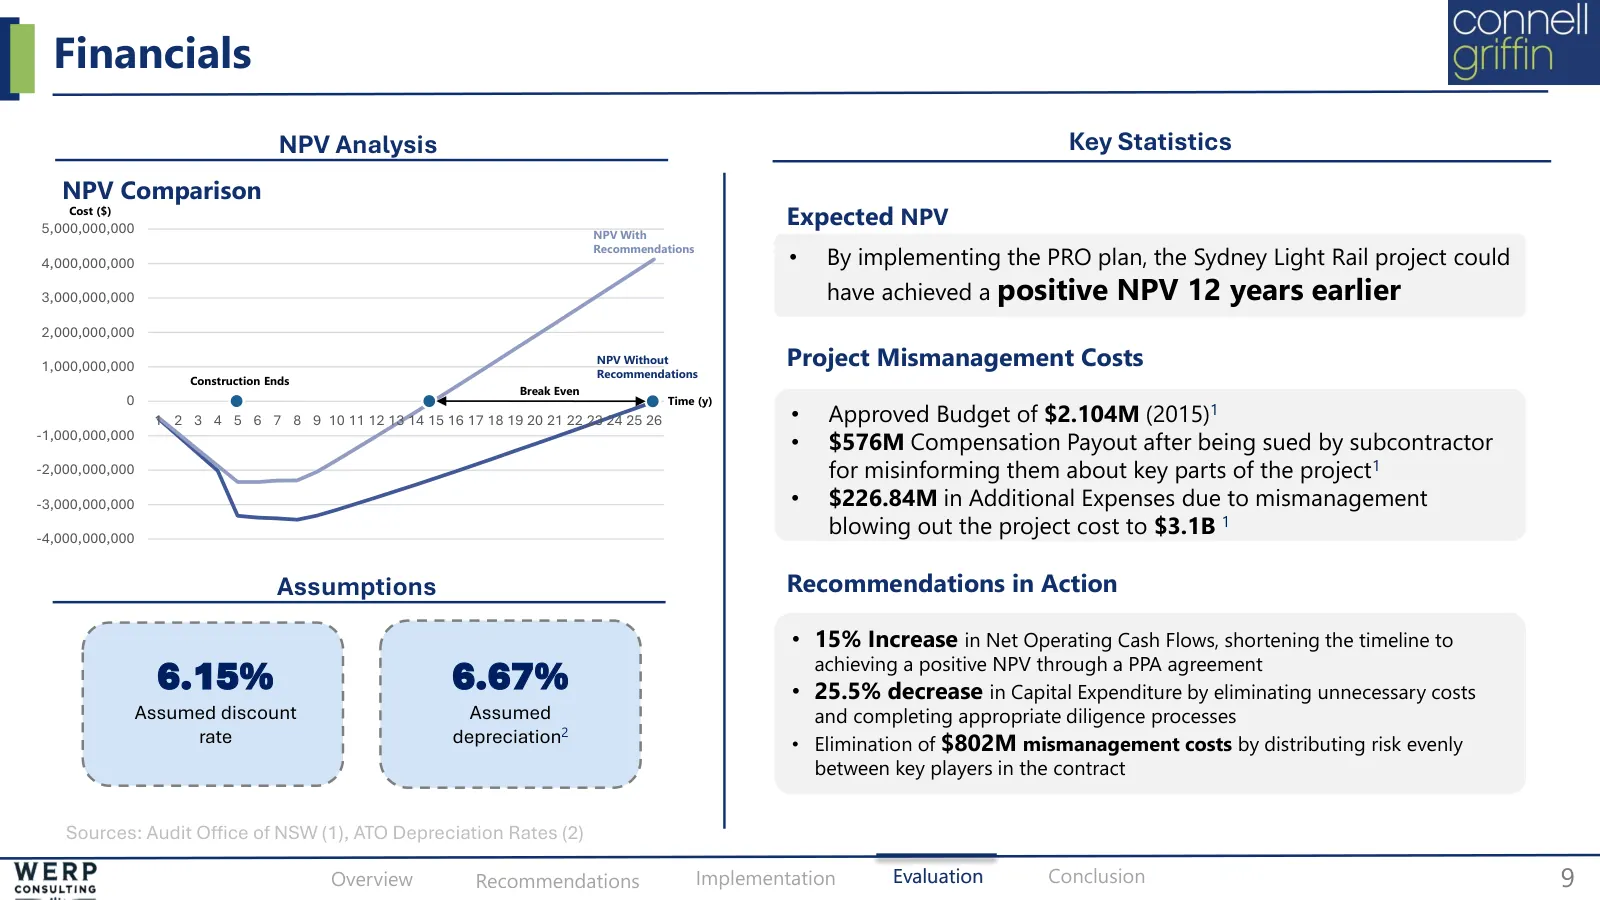
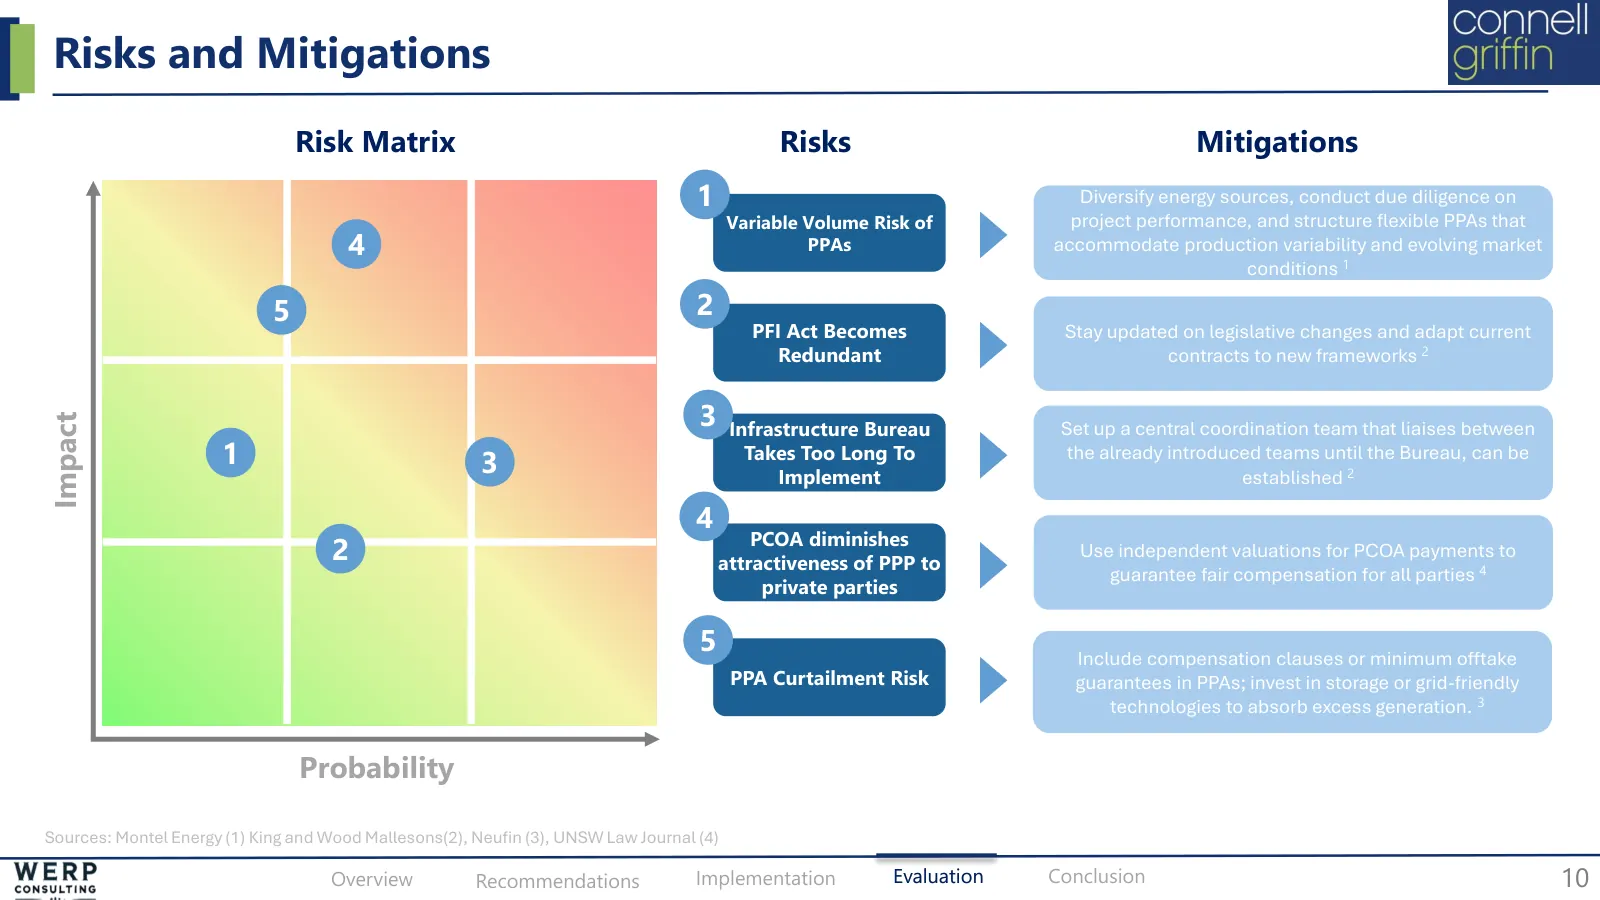
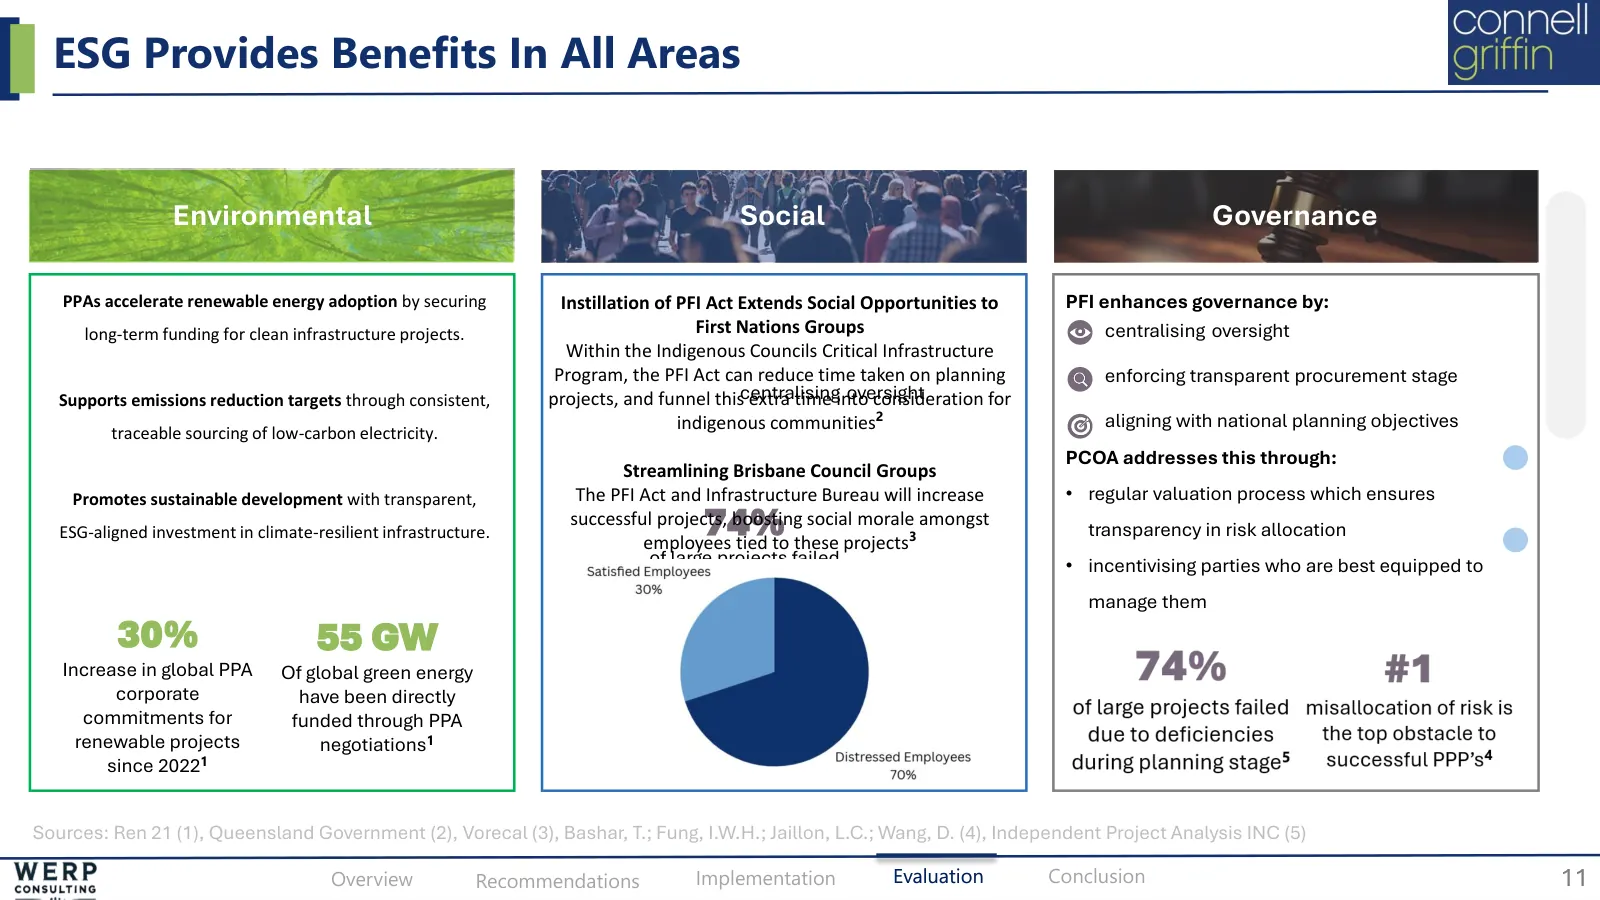
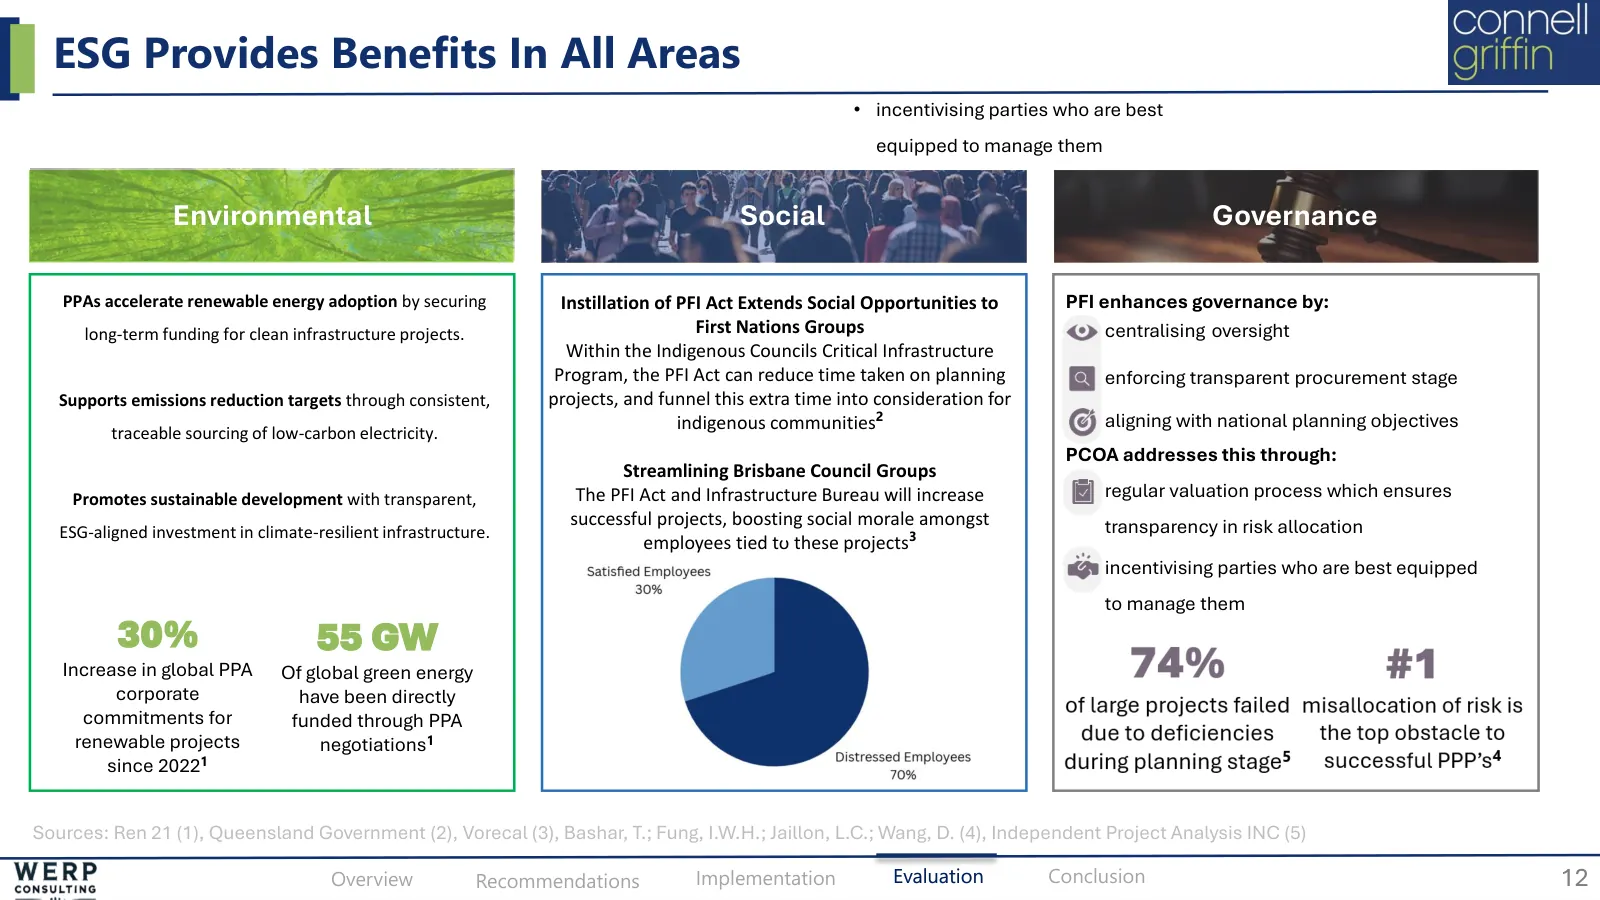
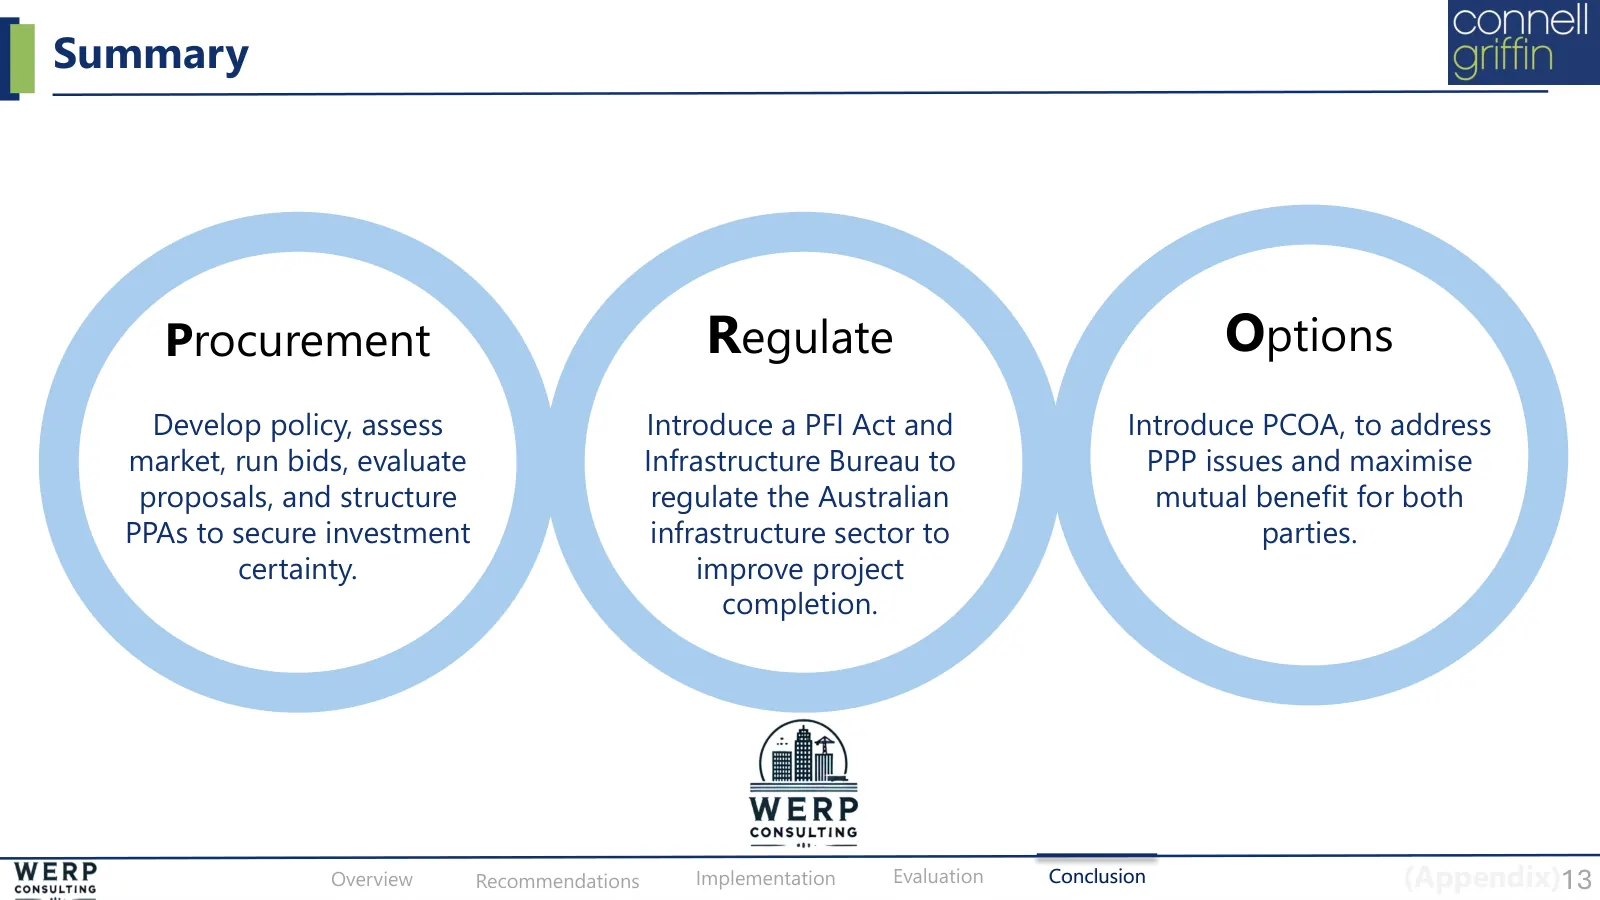
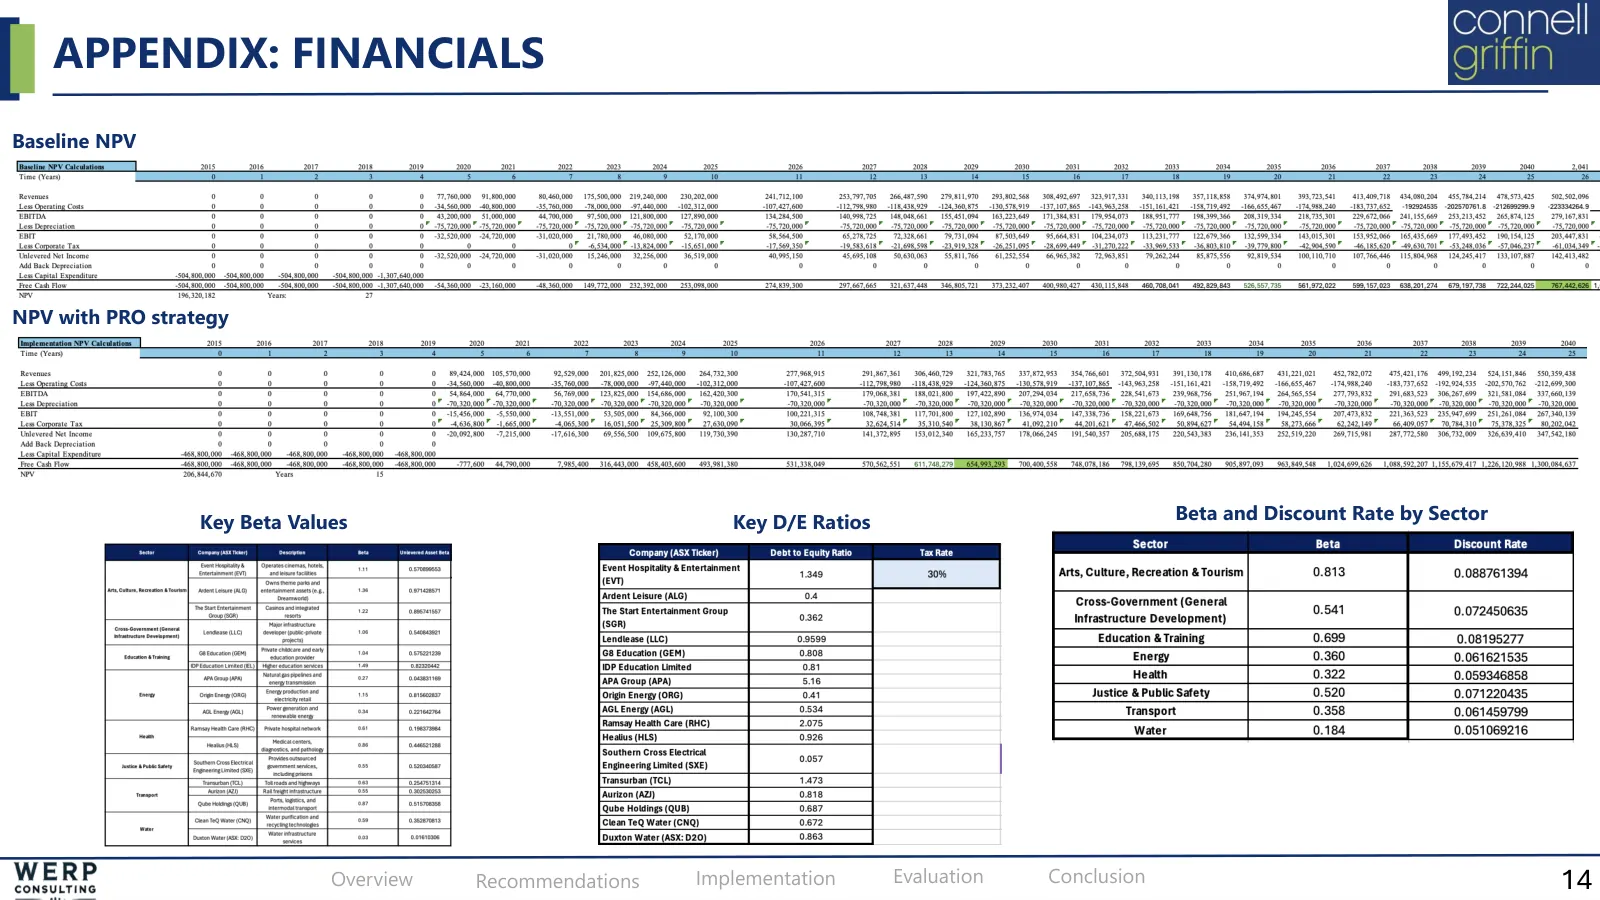
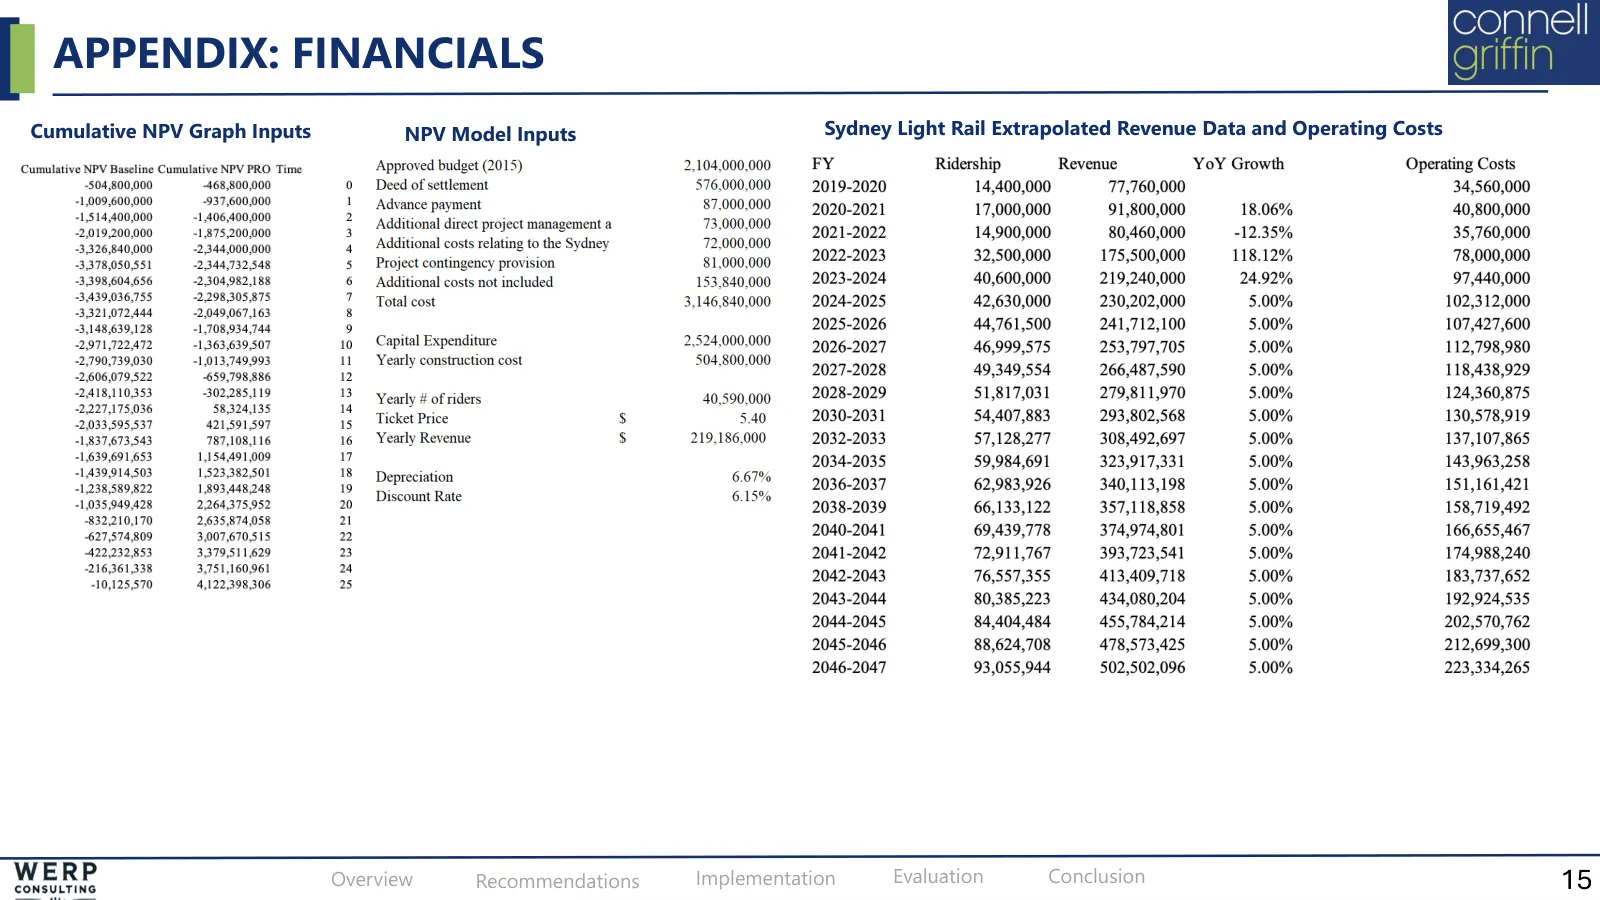
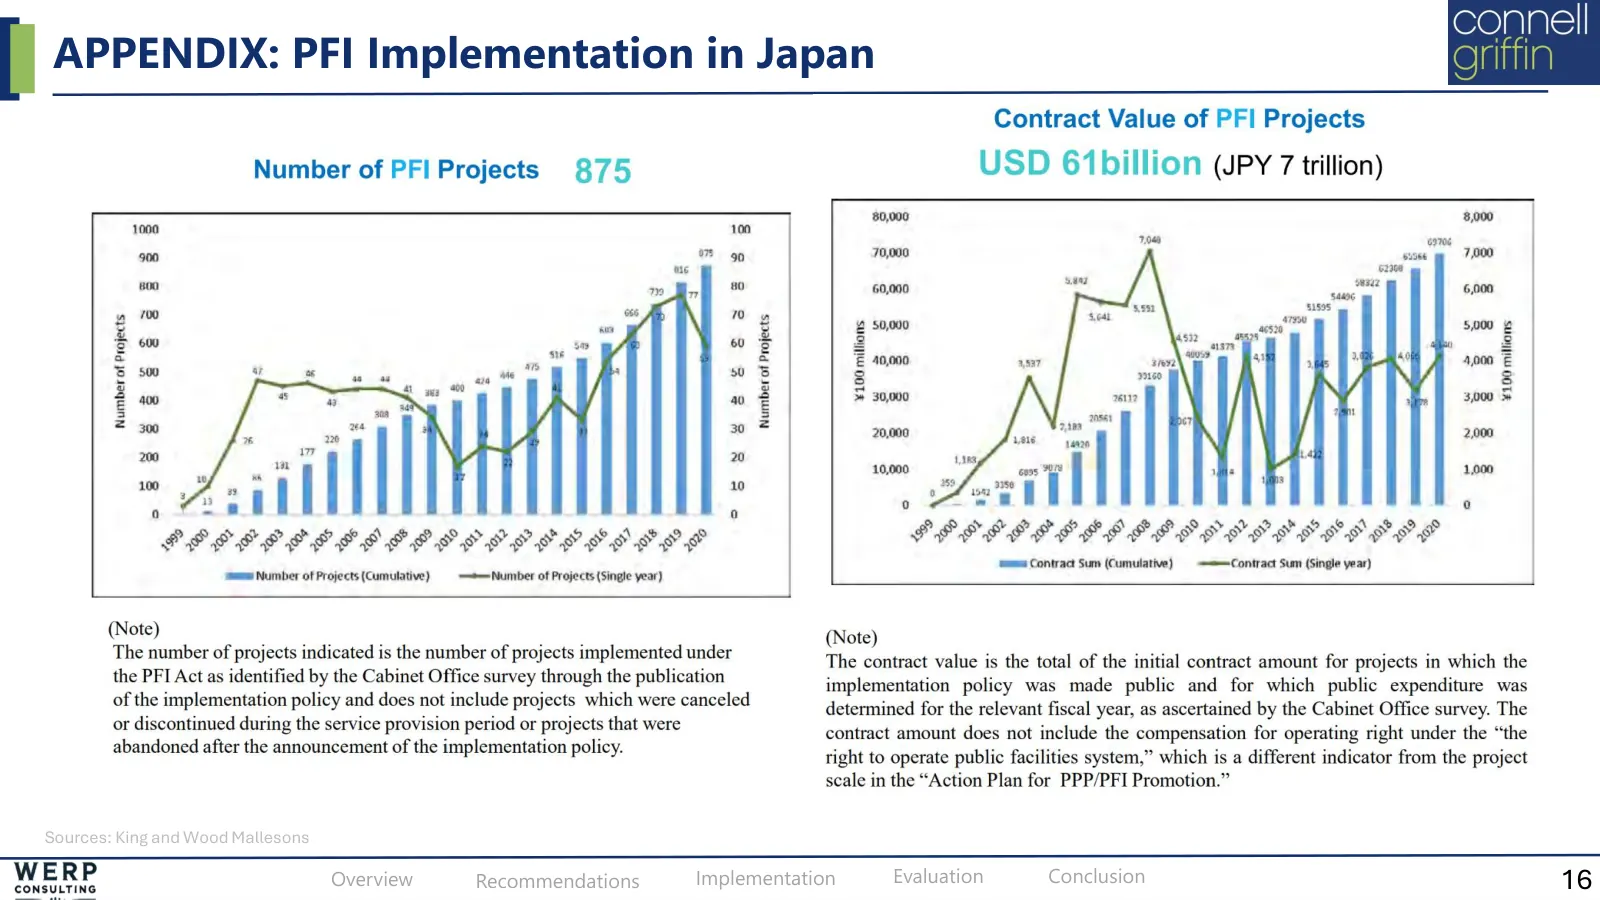
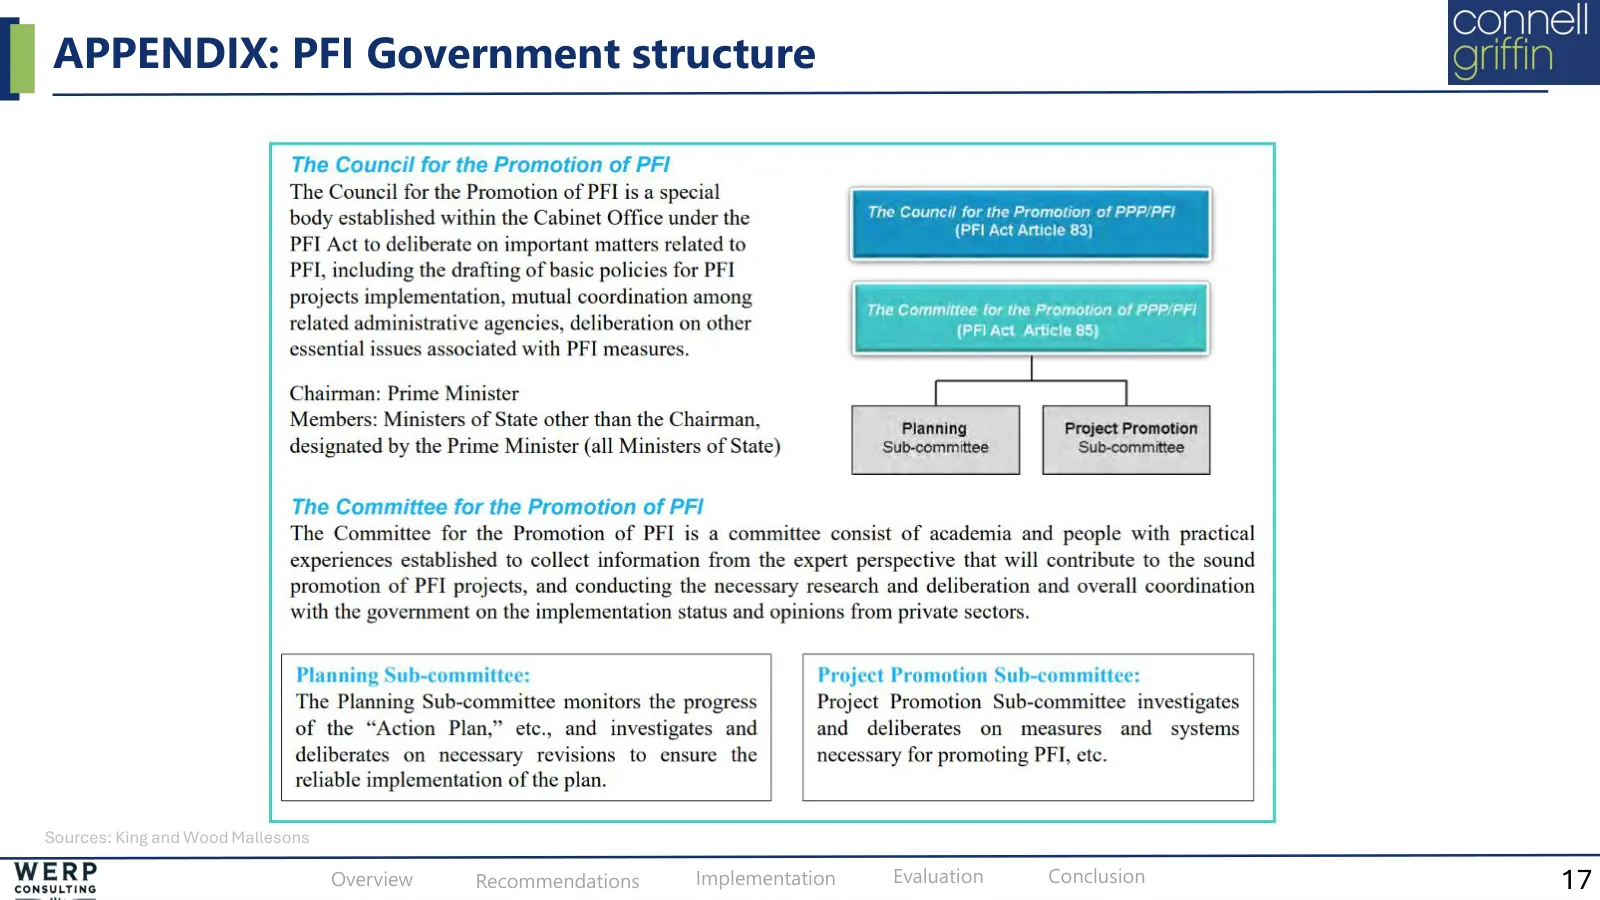
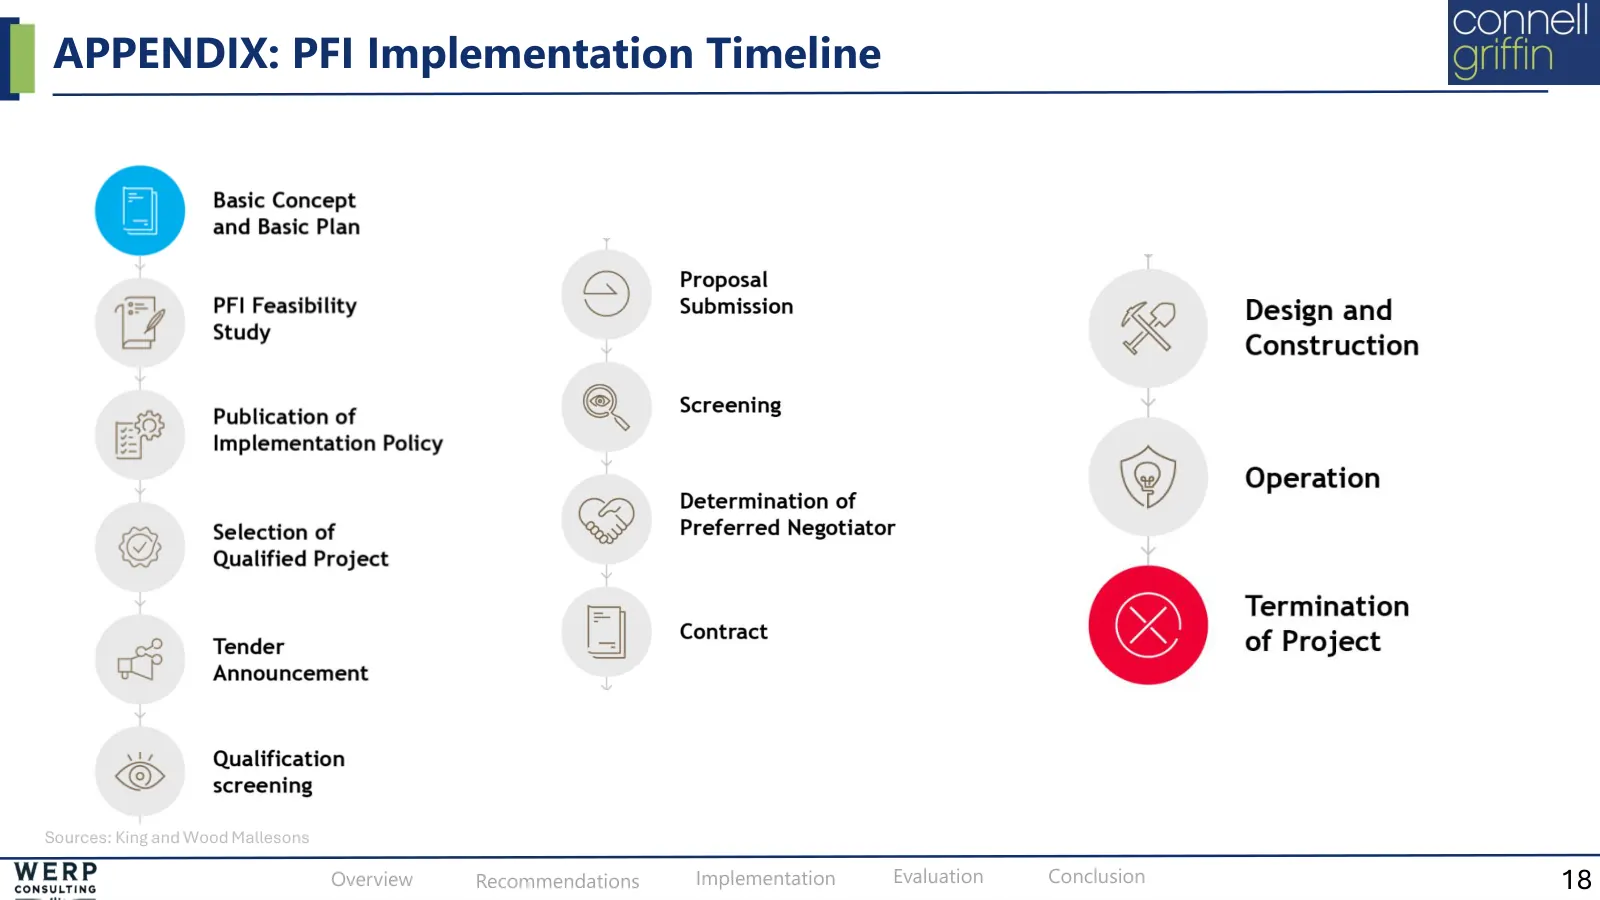
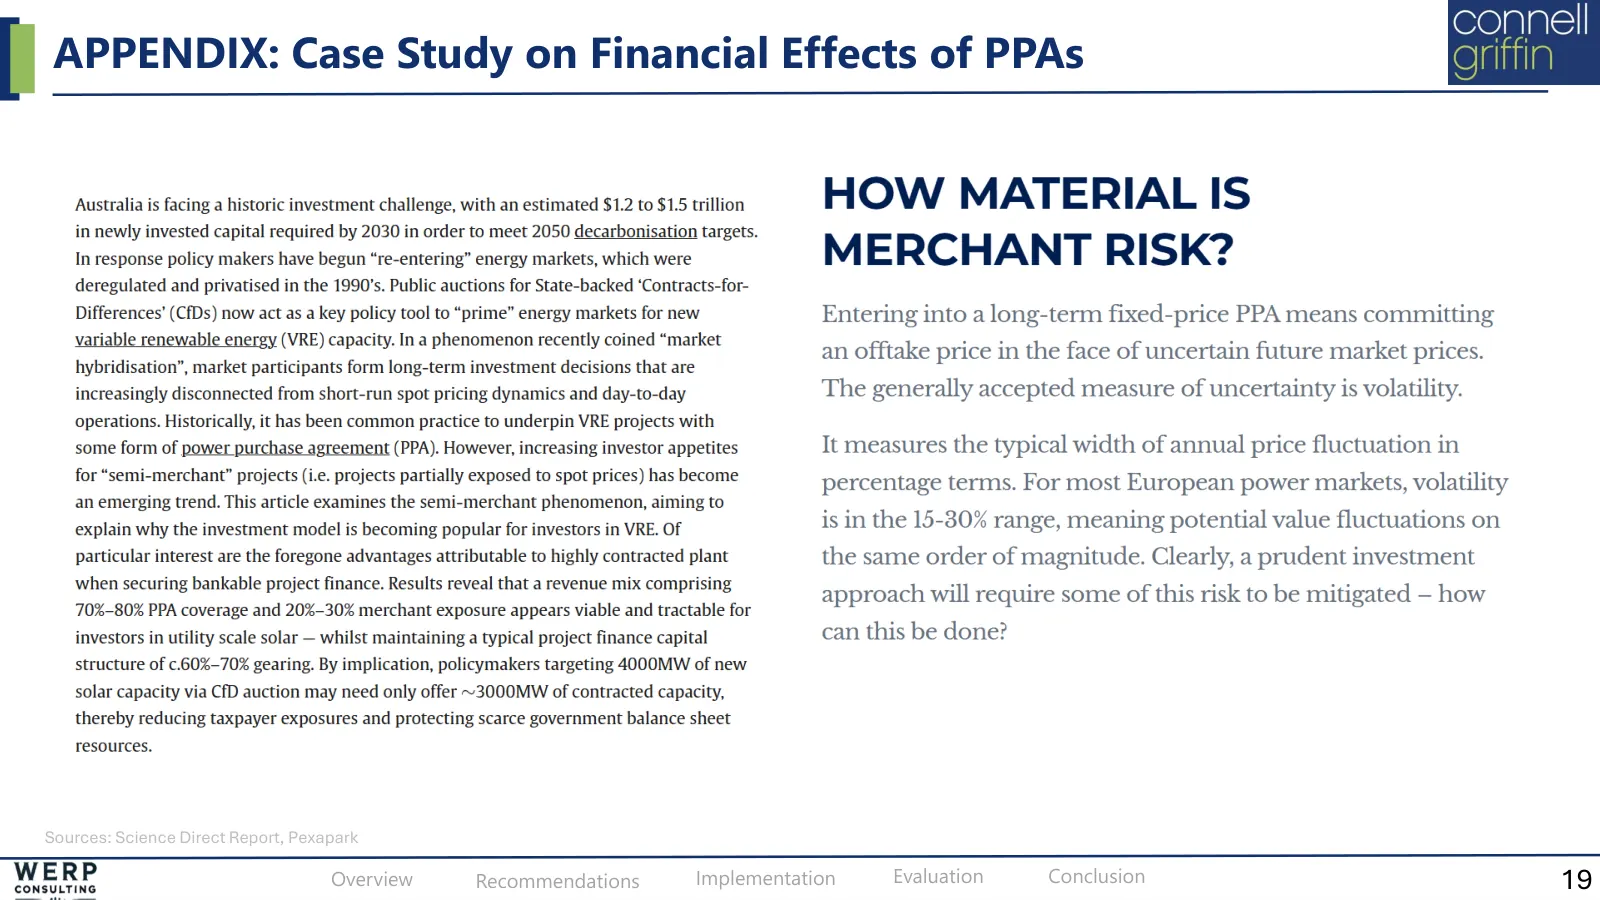
How Queensland should prioritise infrastructure investment over the next 10 years. 2025, for Connell Griffin. Three recommendations: a regulated market for long-term power purchase agreements, so projects get cost certainty and private capital; a private finance law and infrastructure bureau to get more projects finished; and clearer risk sharing in public-private partnerships. Team of four, as WERP Consulting. Second place.
Econometrics
Two research reports for a university econometrics course. 2026. Individual, with the analysis in R and Python.
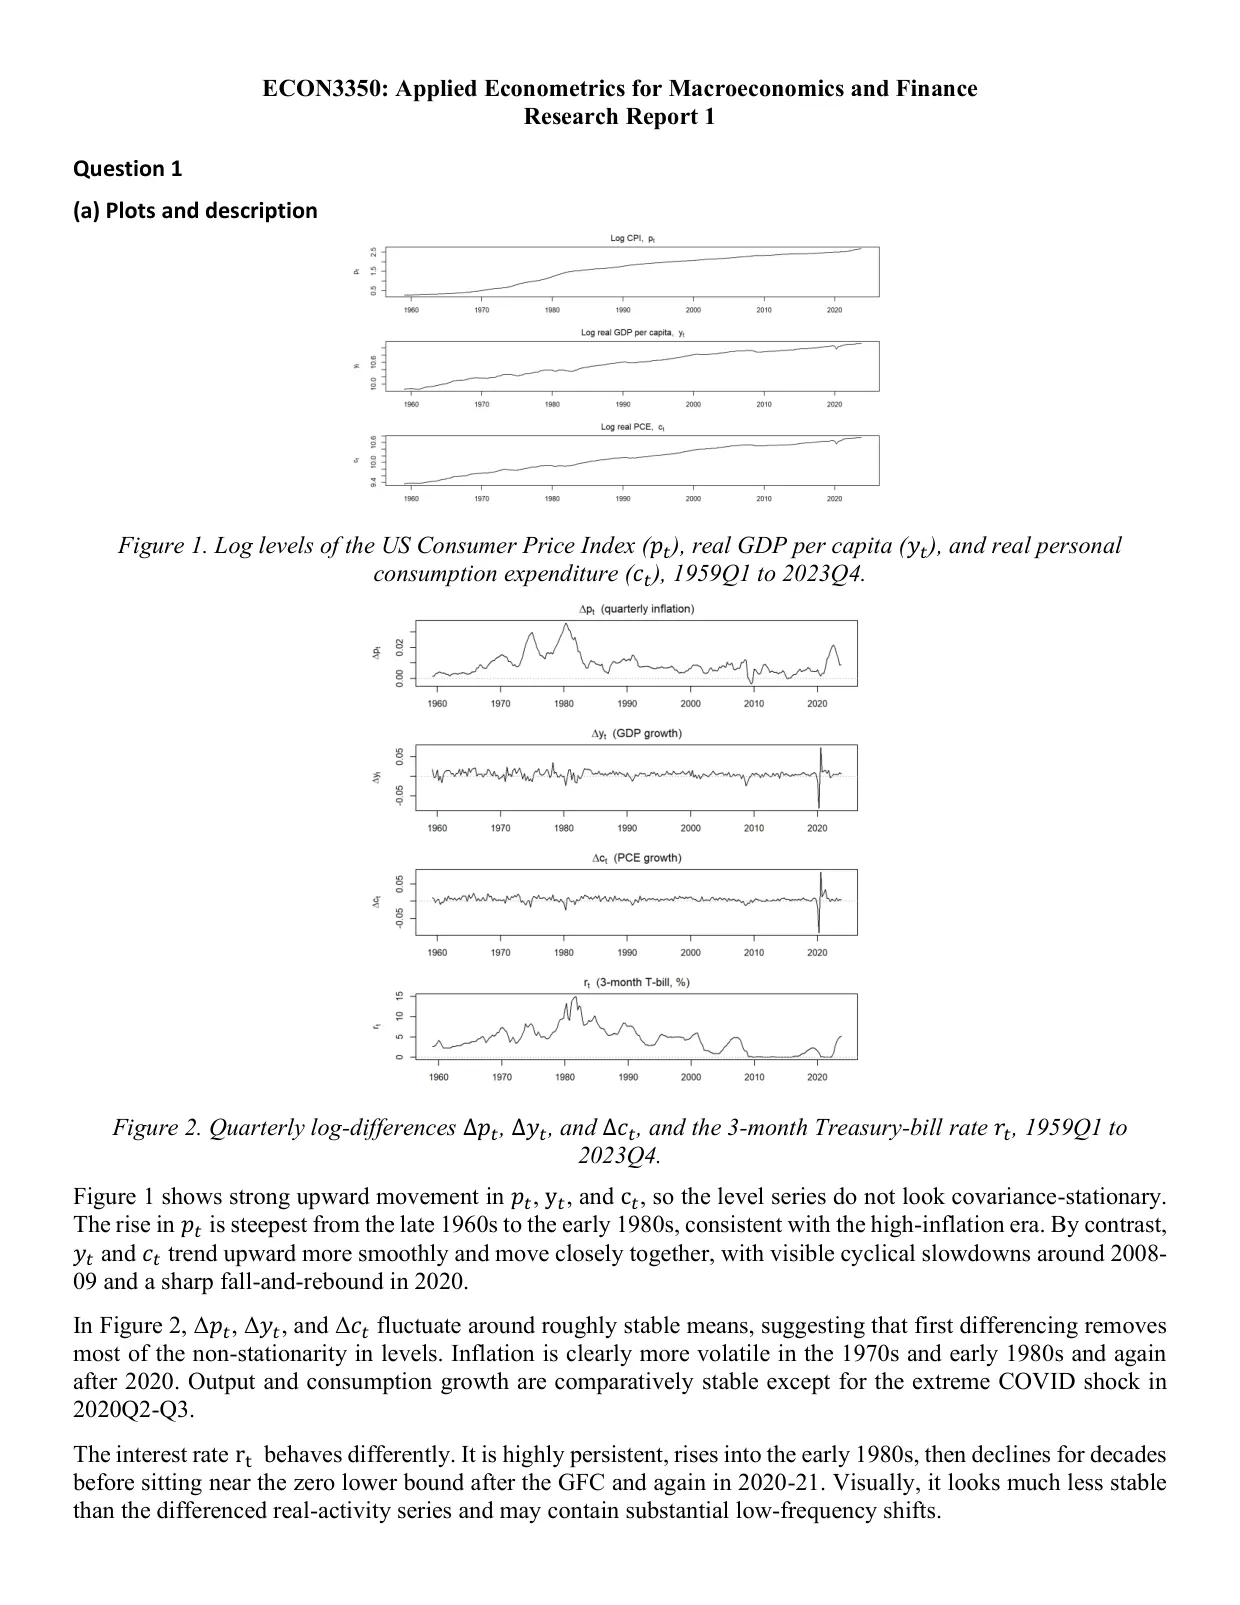
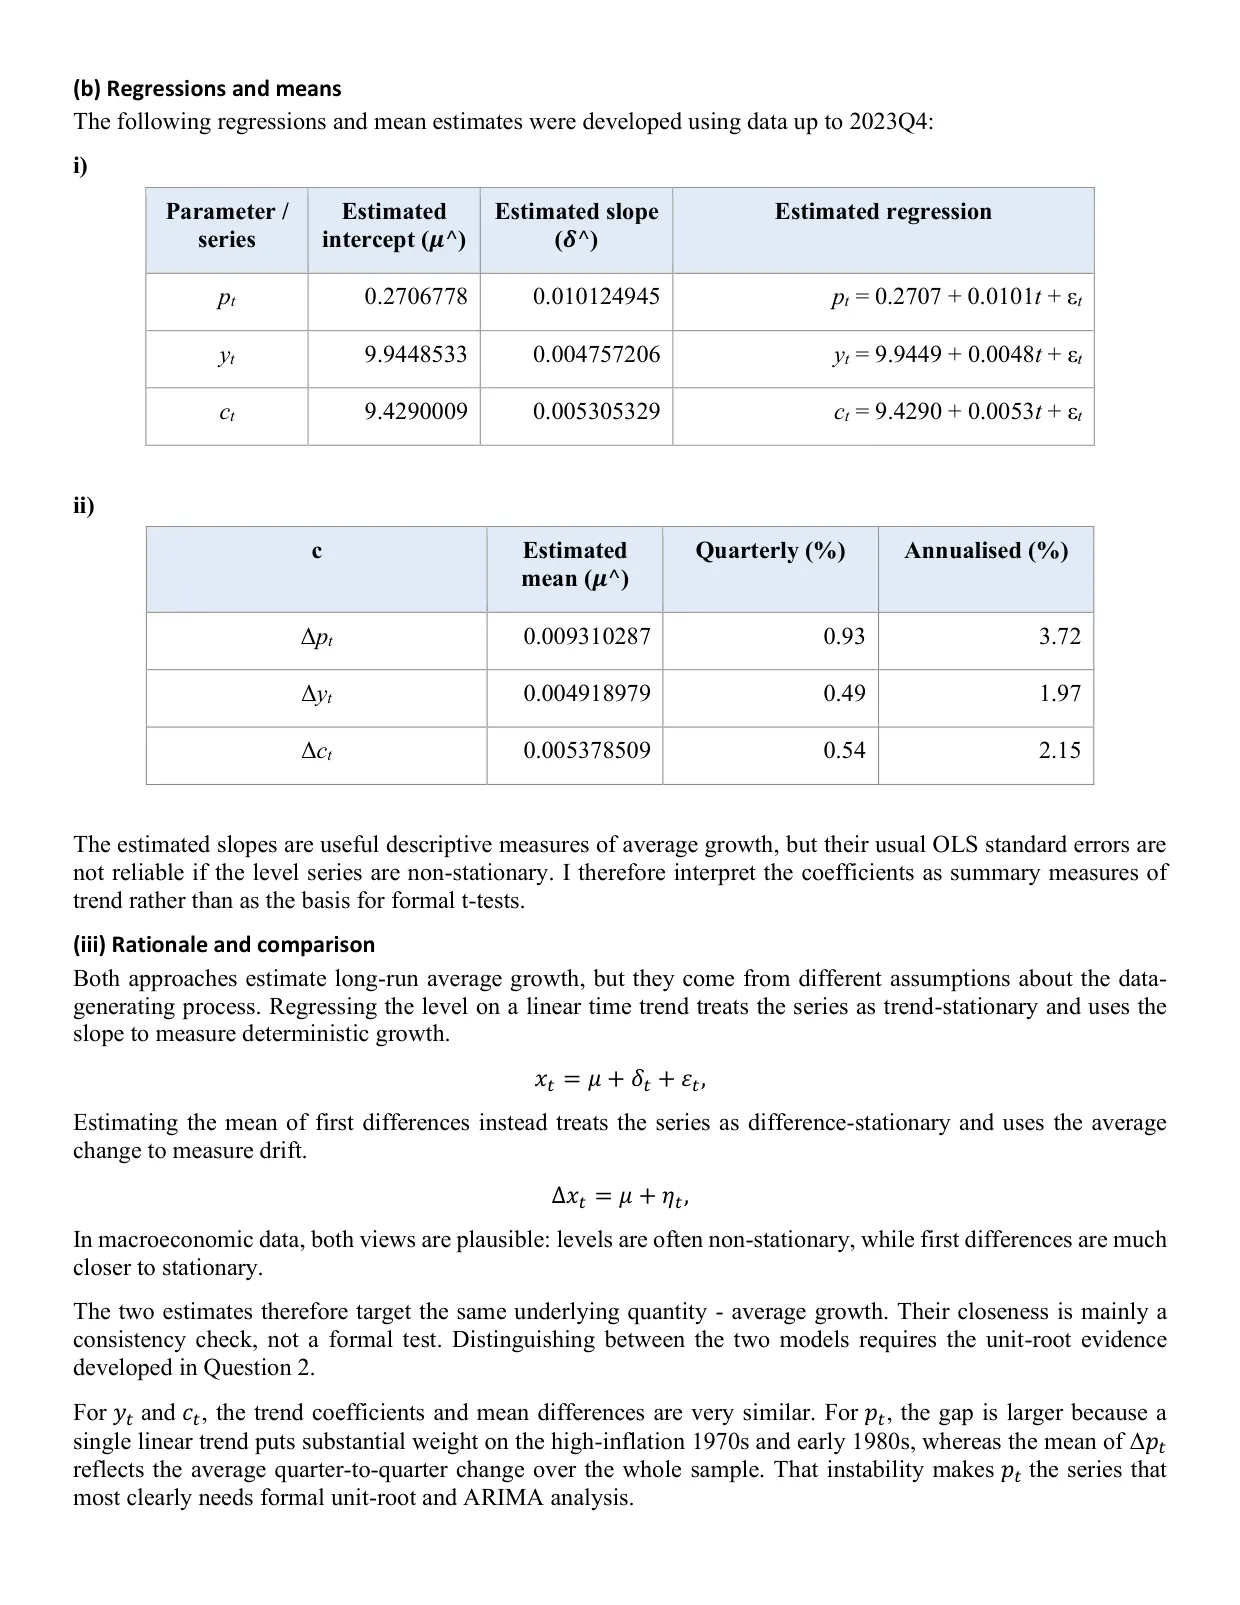
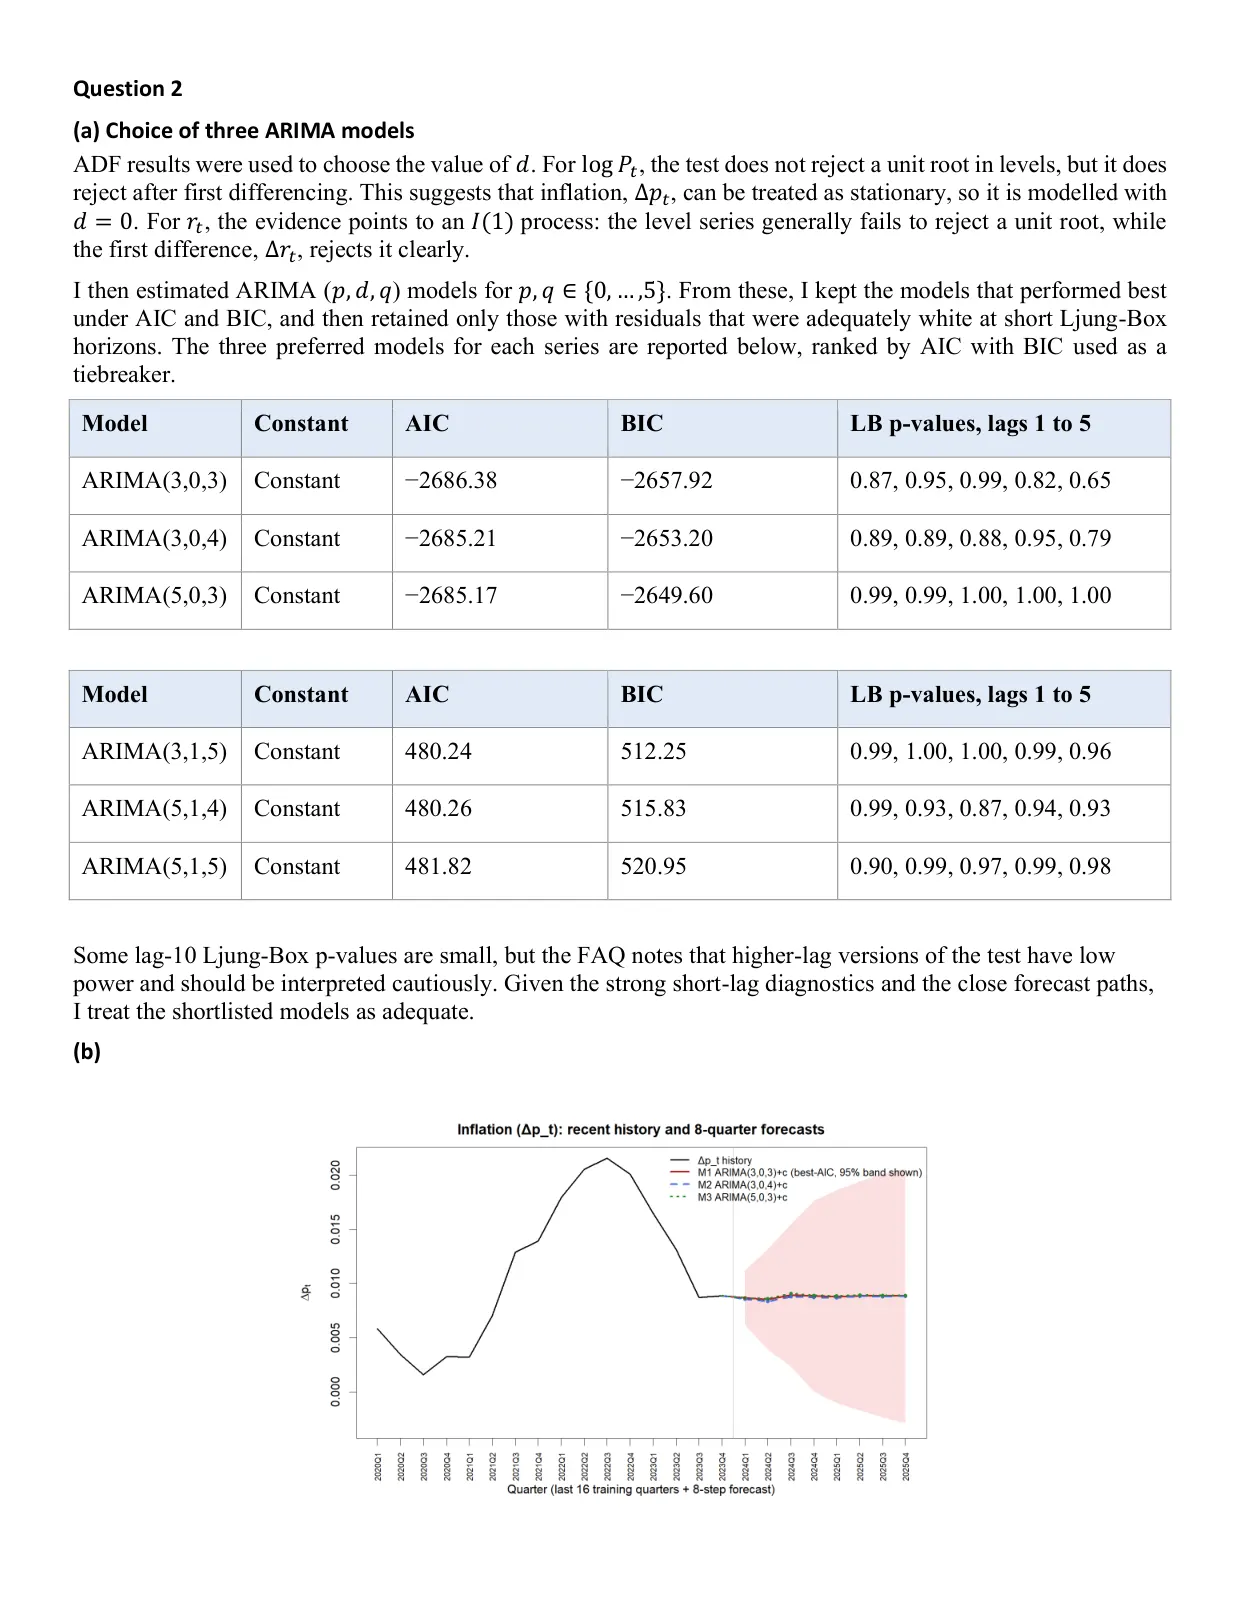
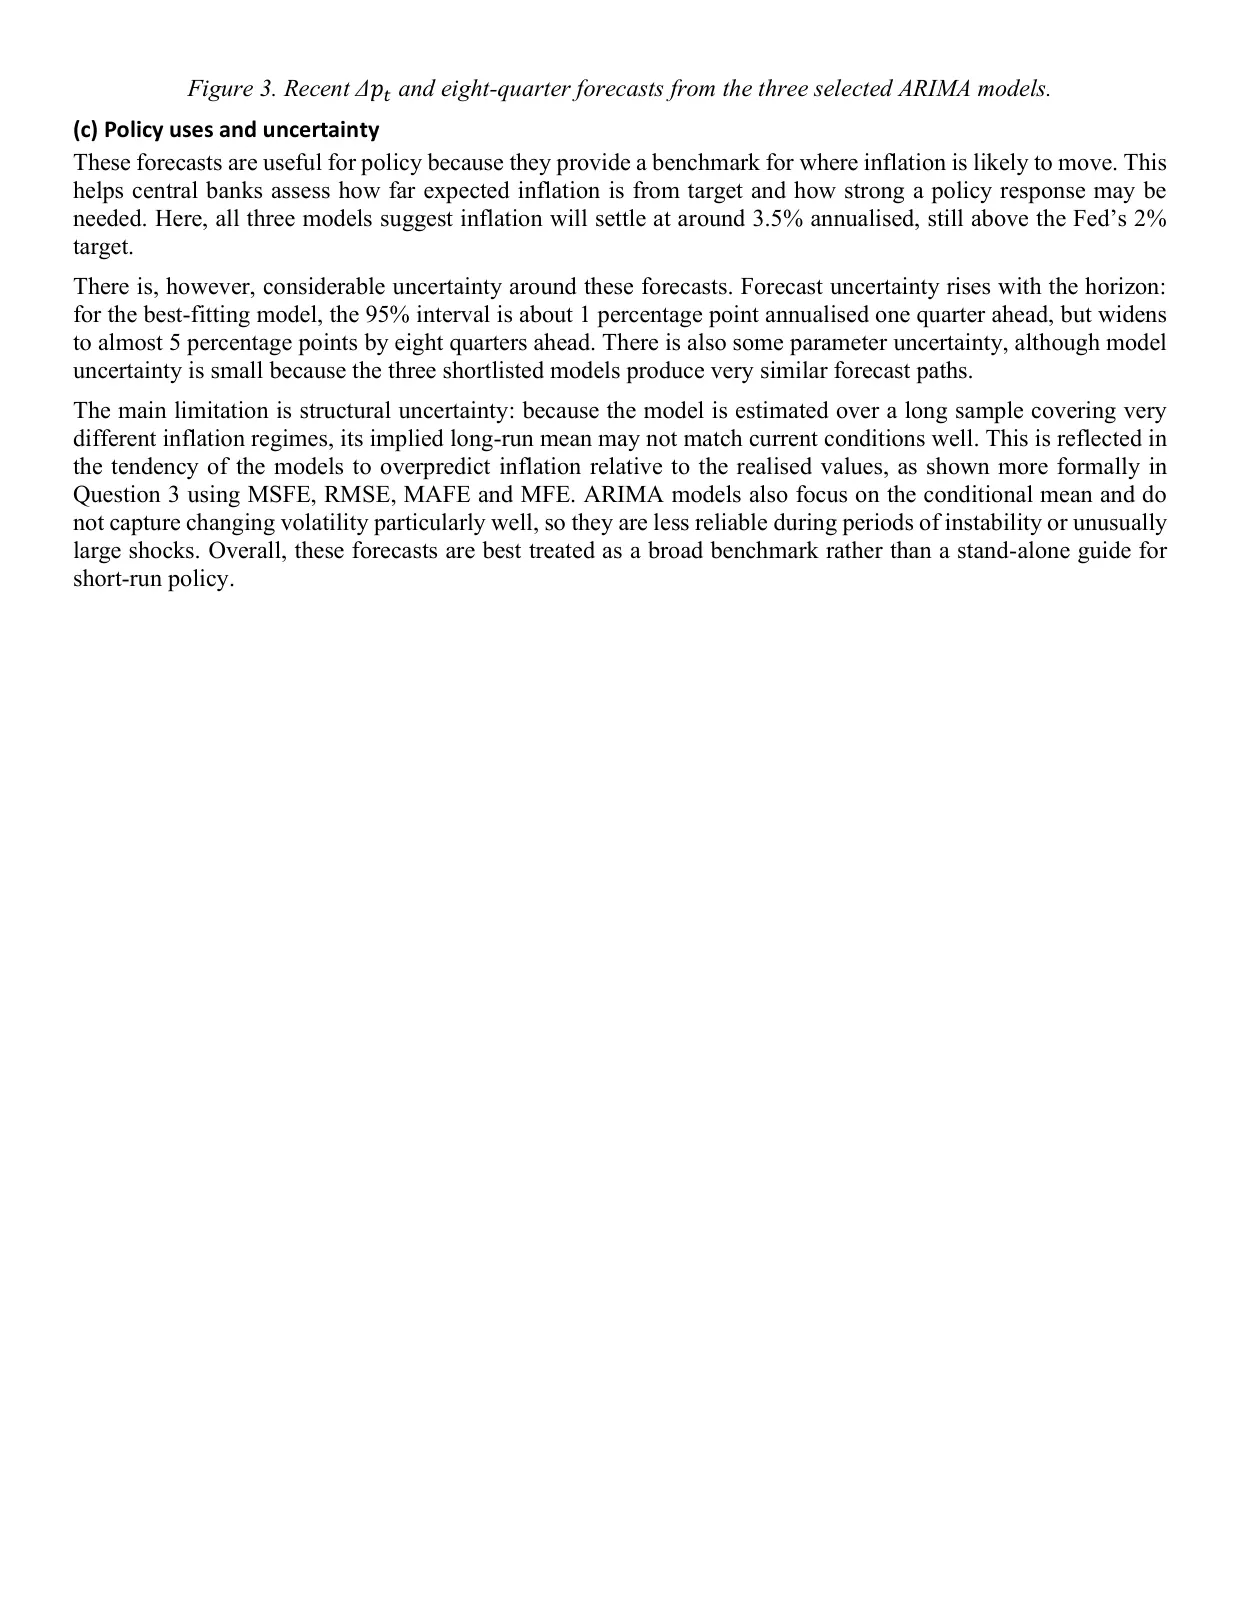
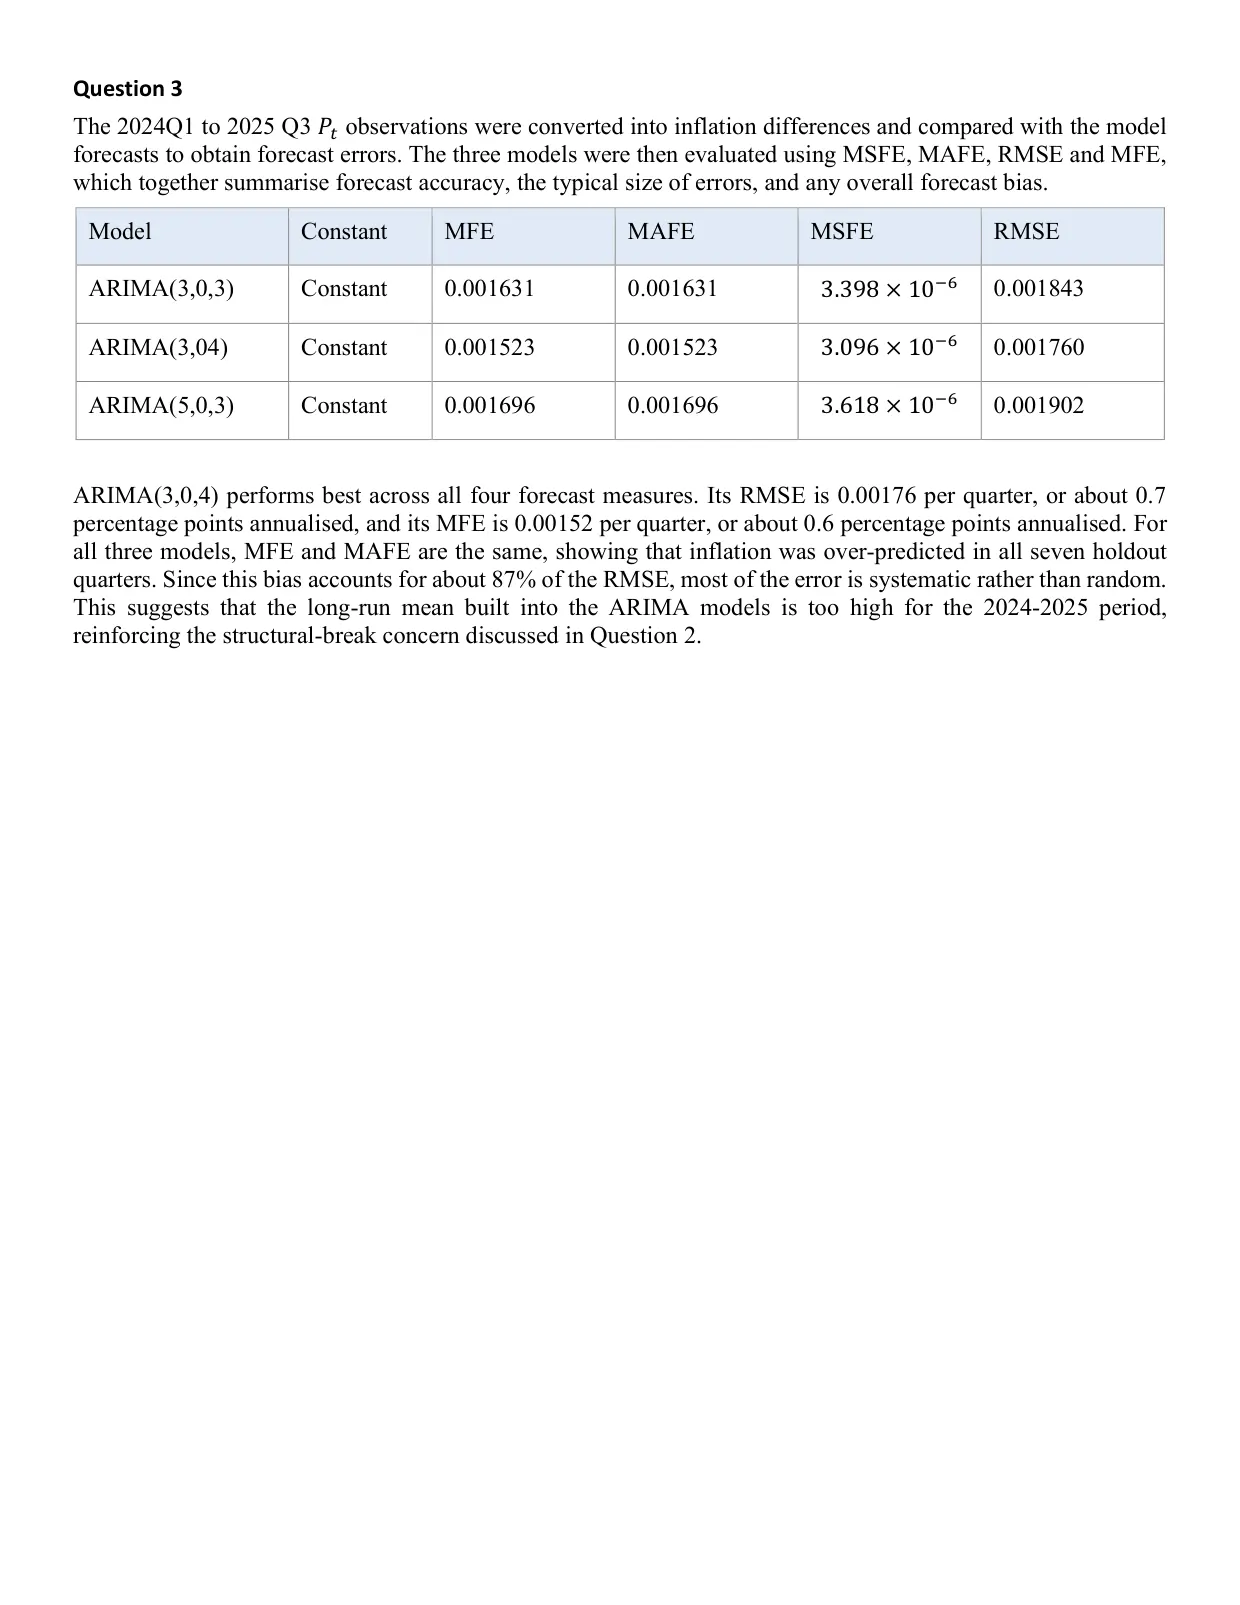
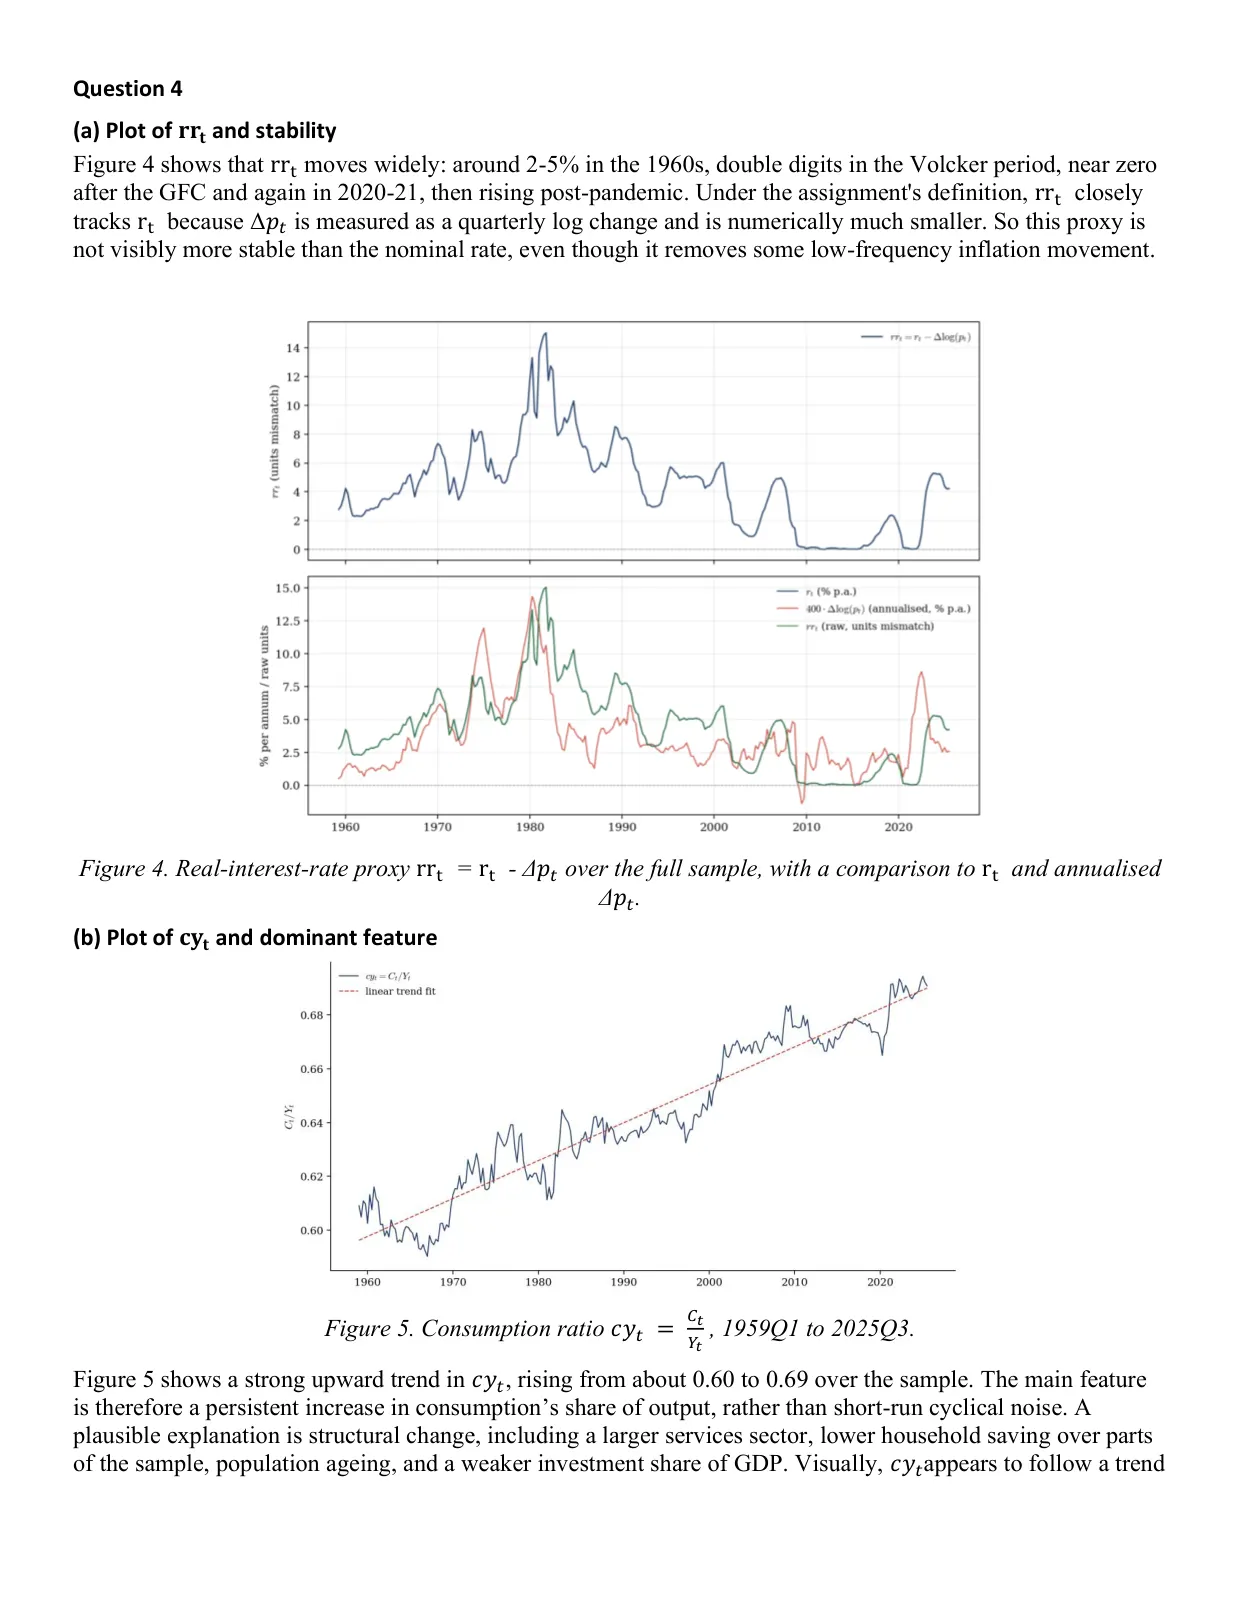
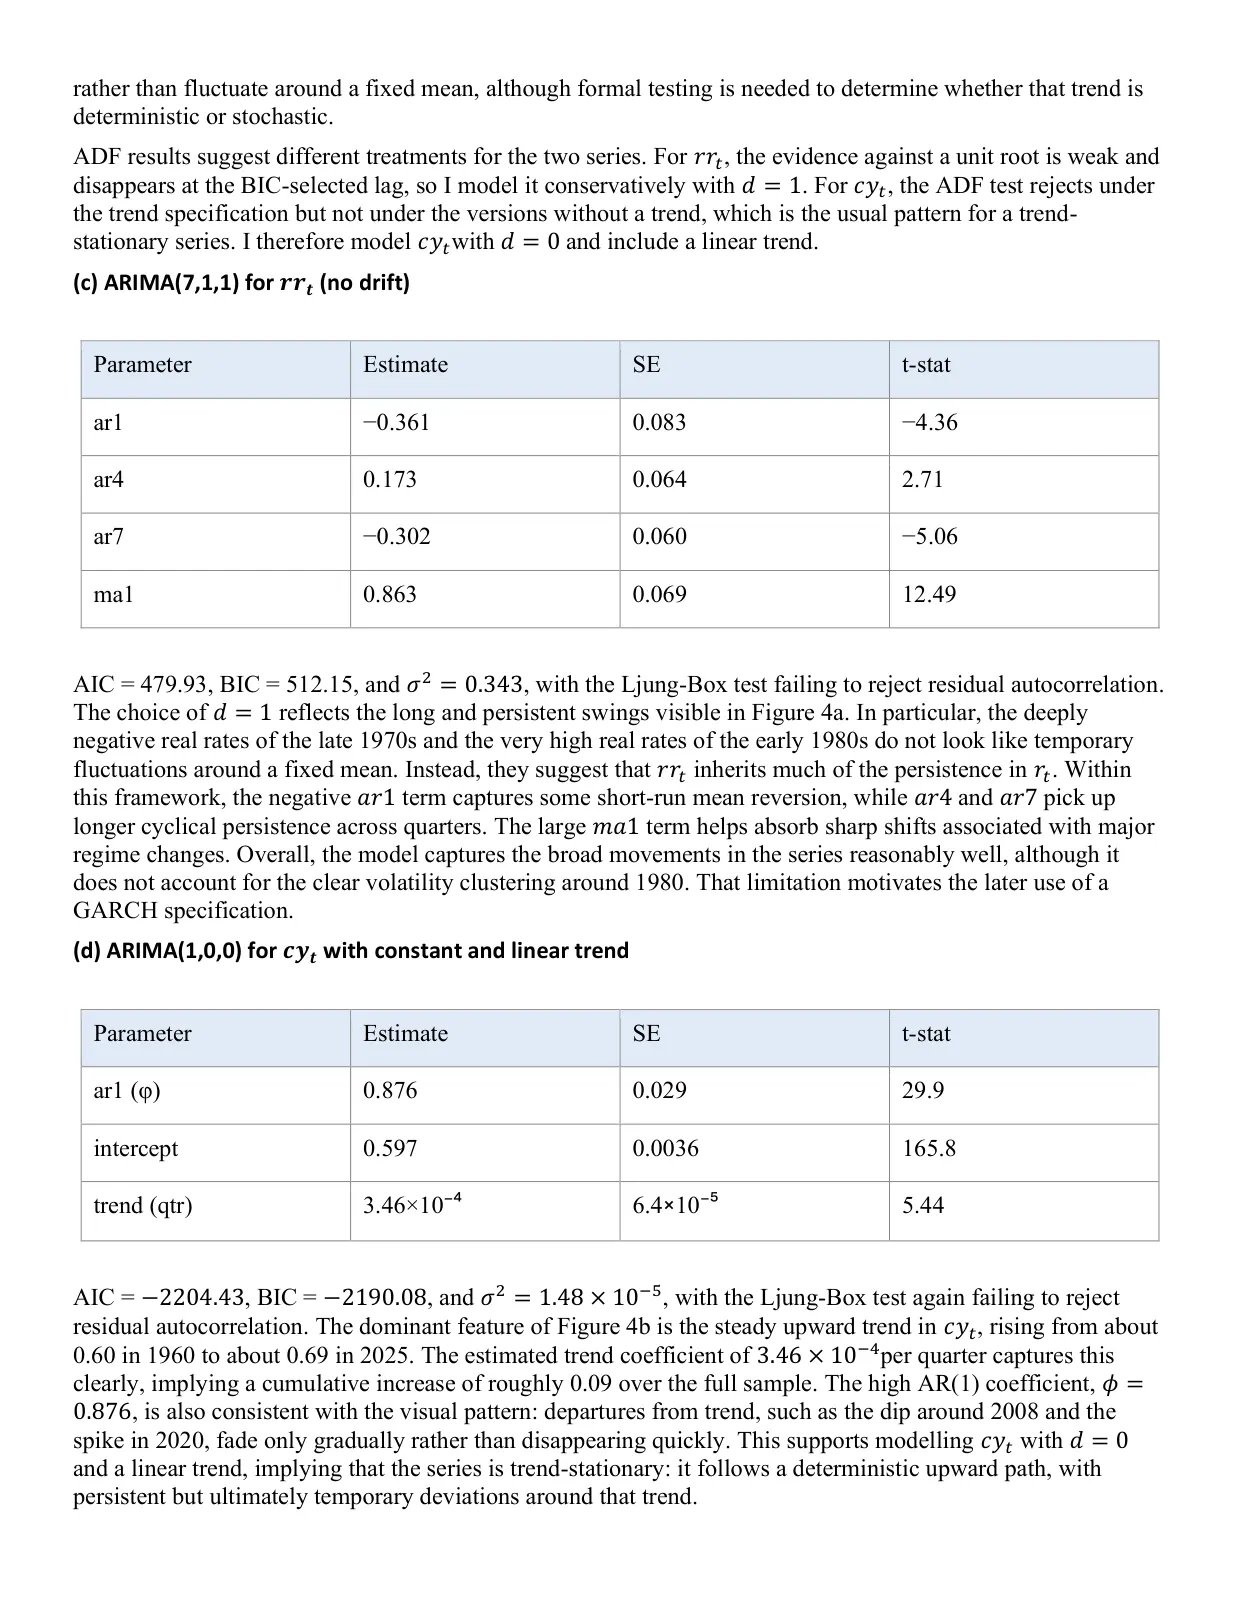
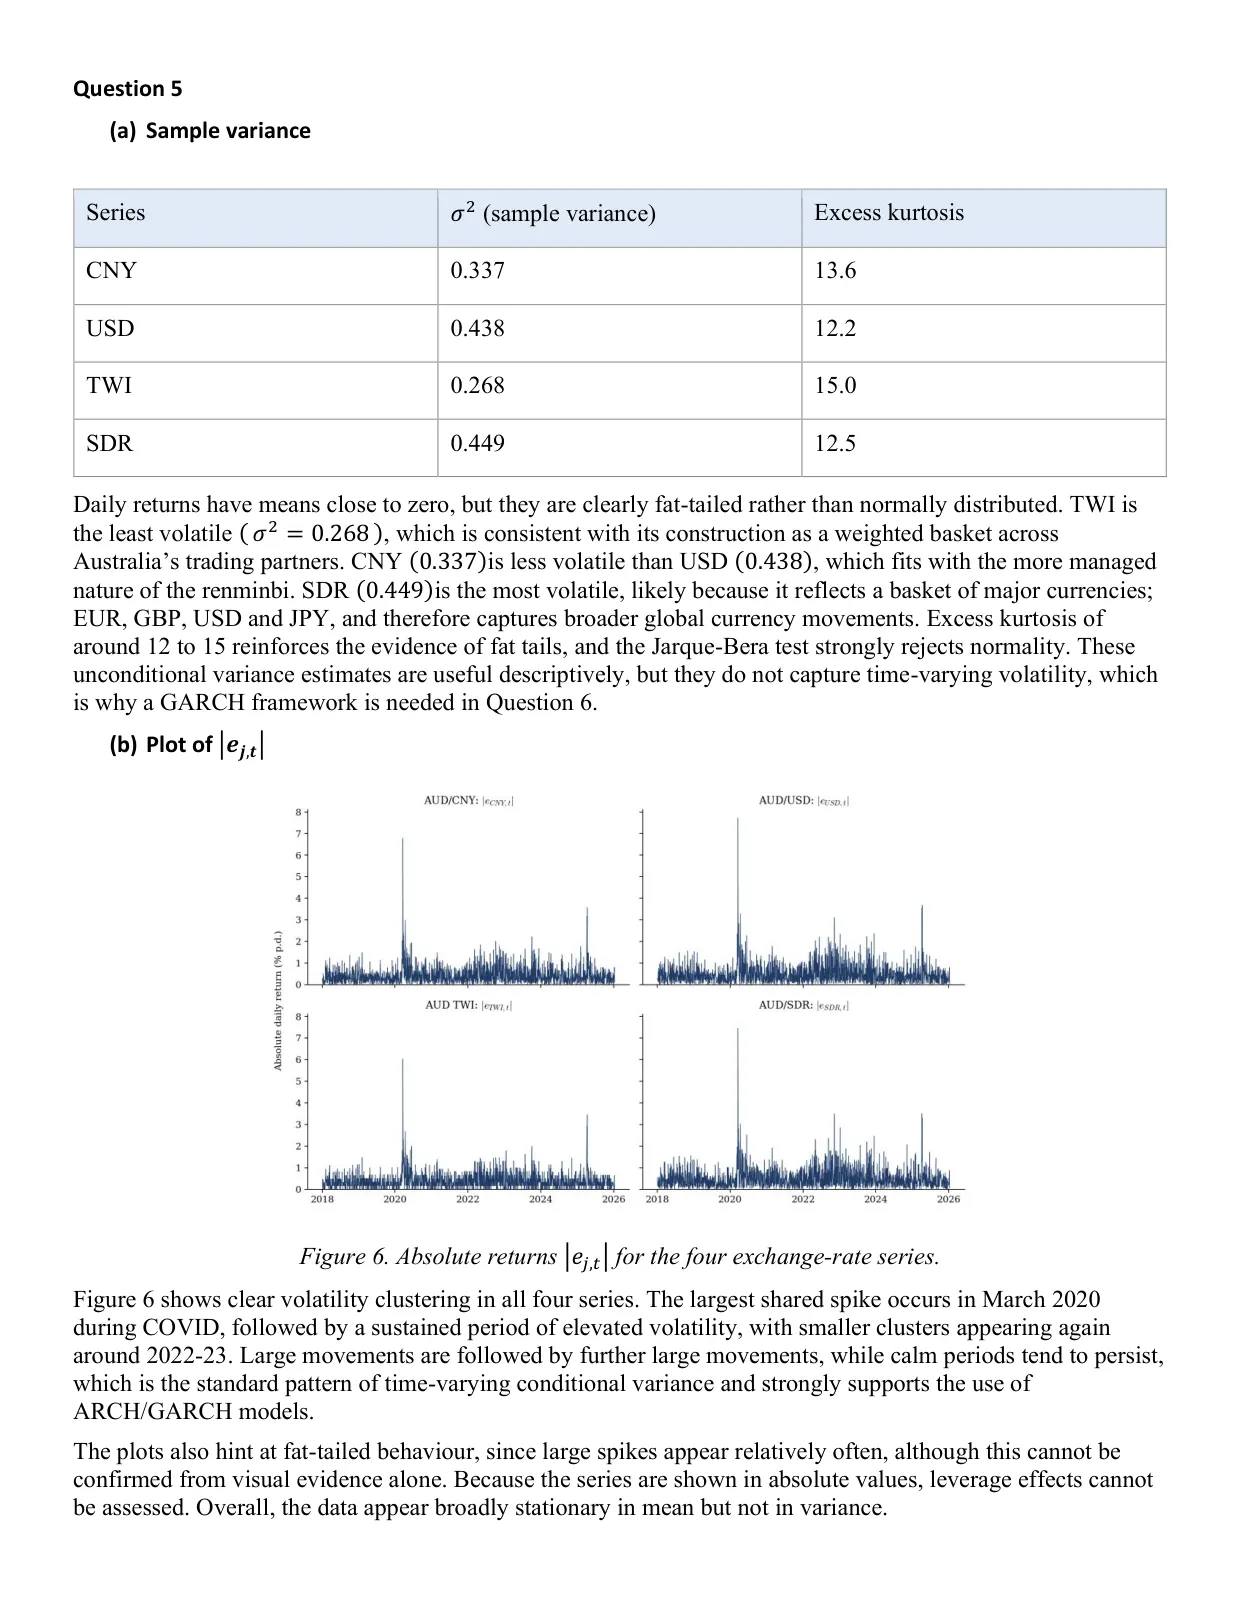
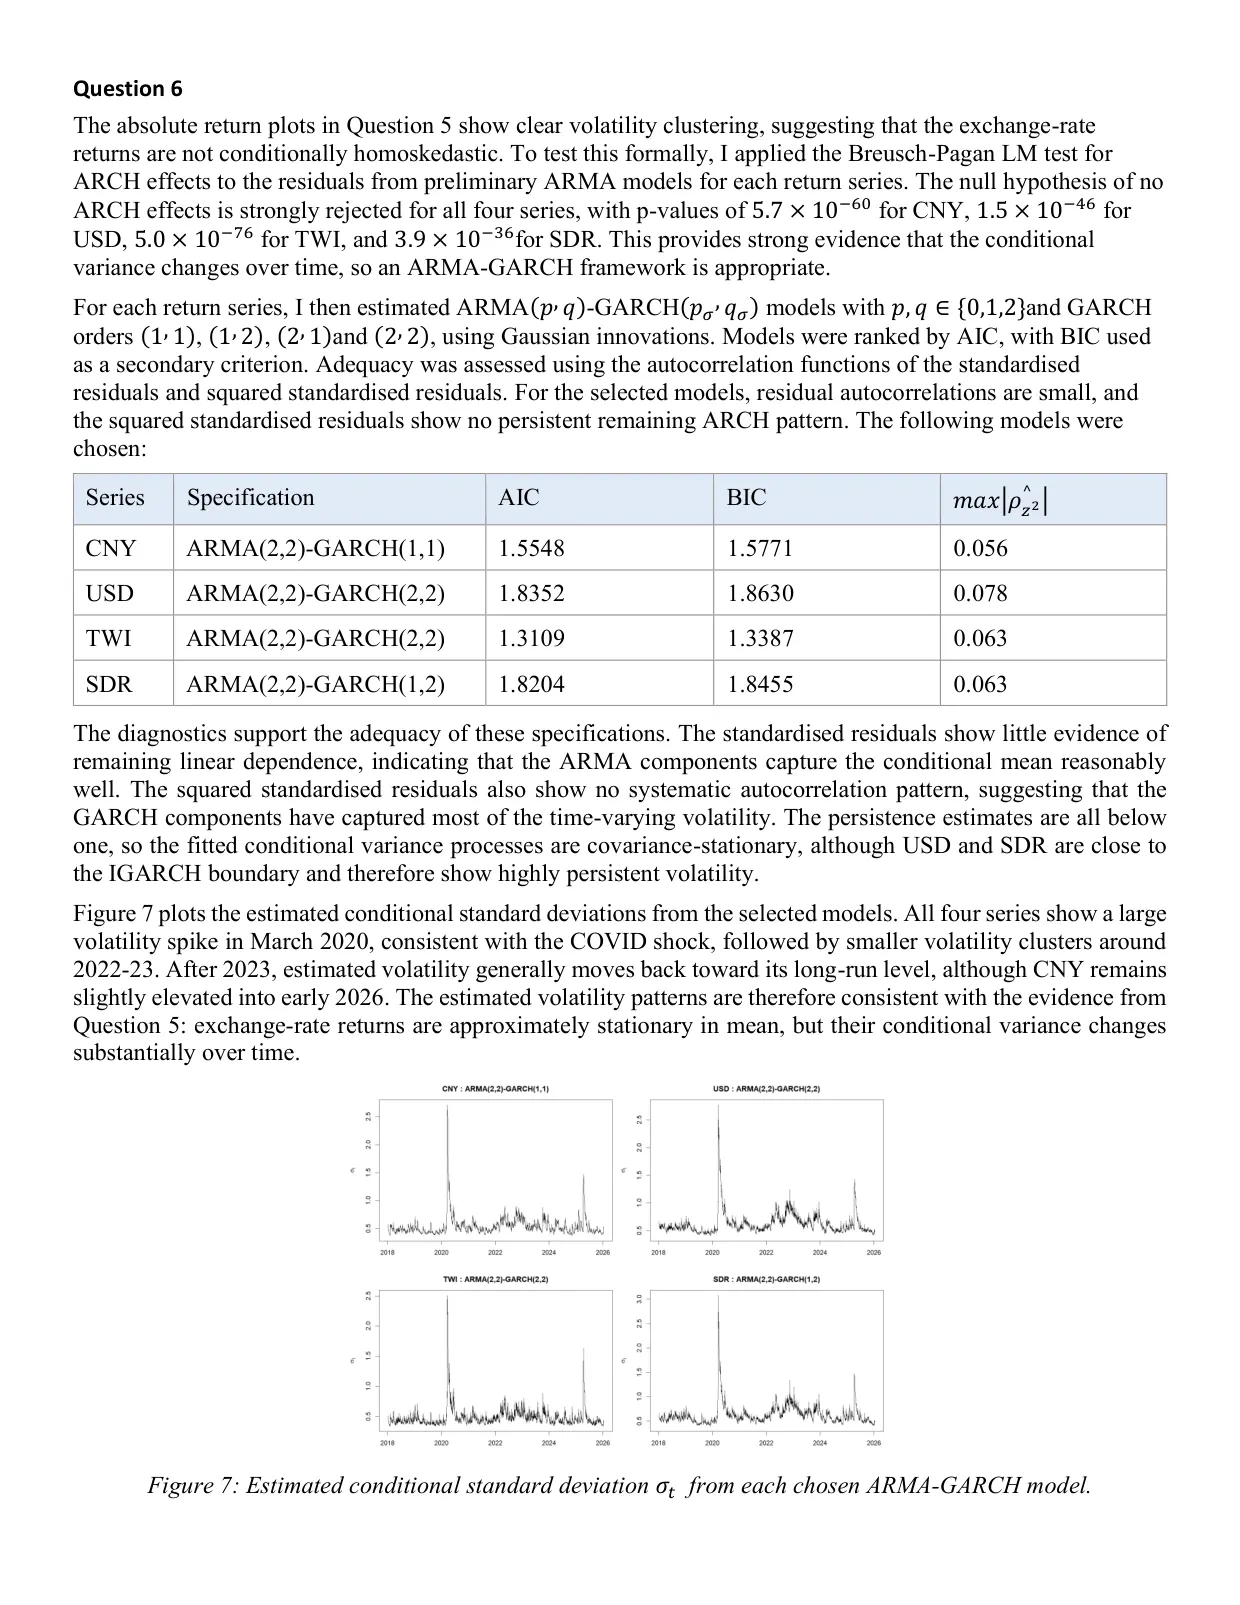
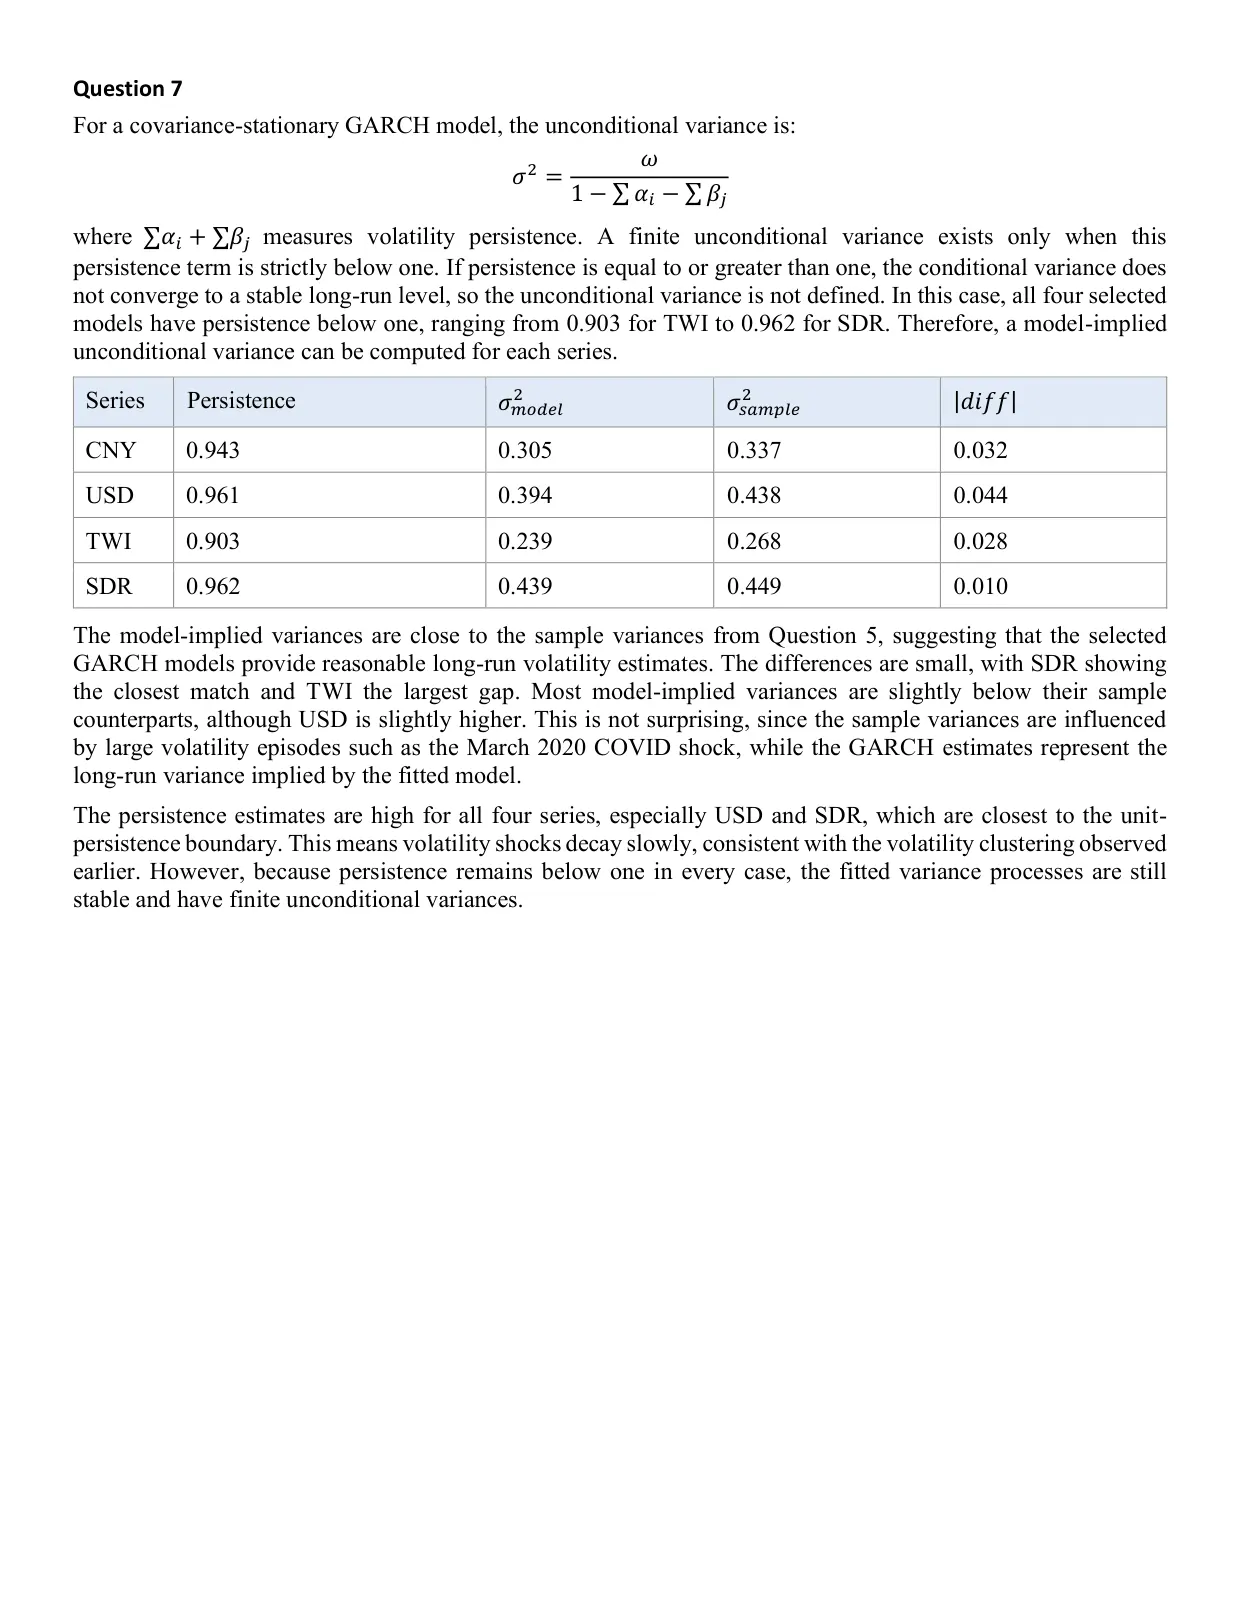
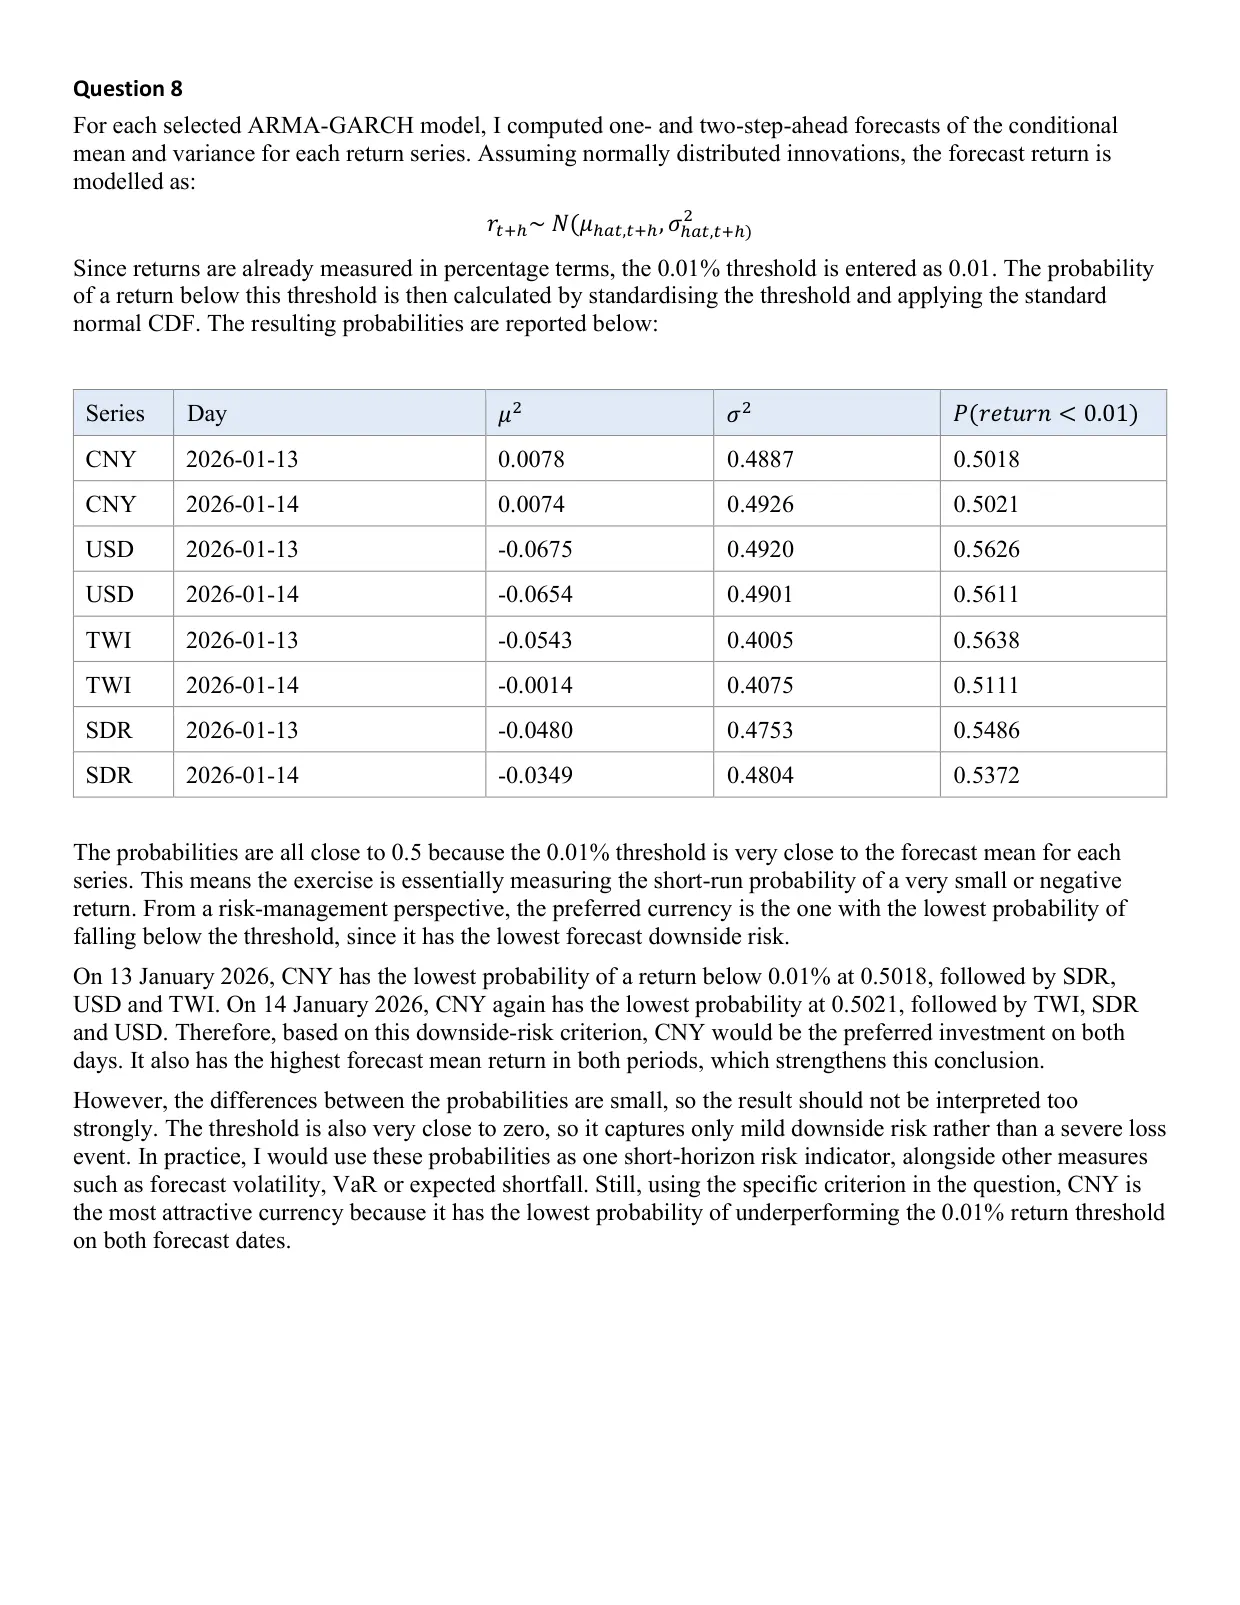
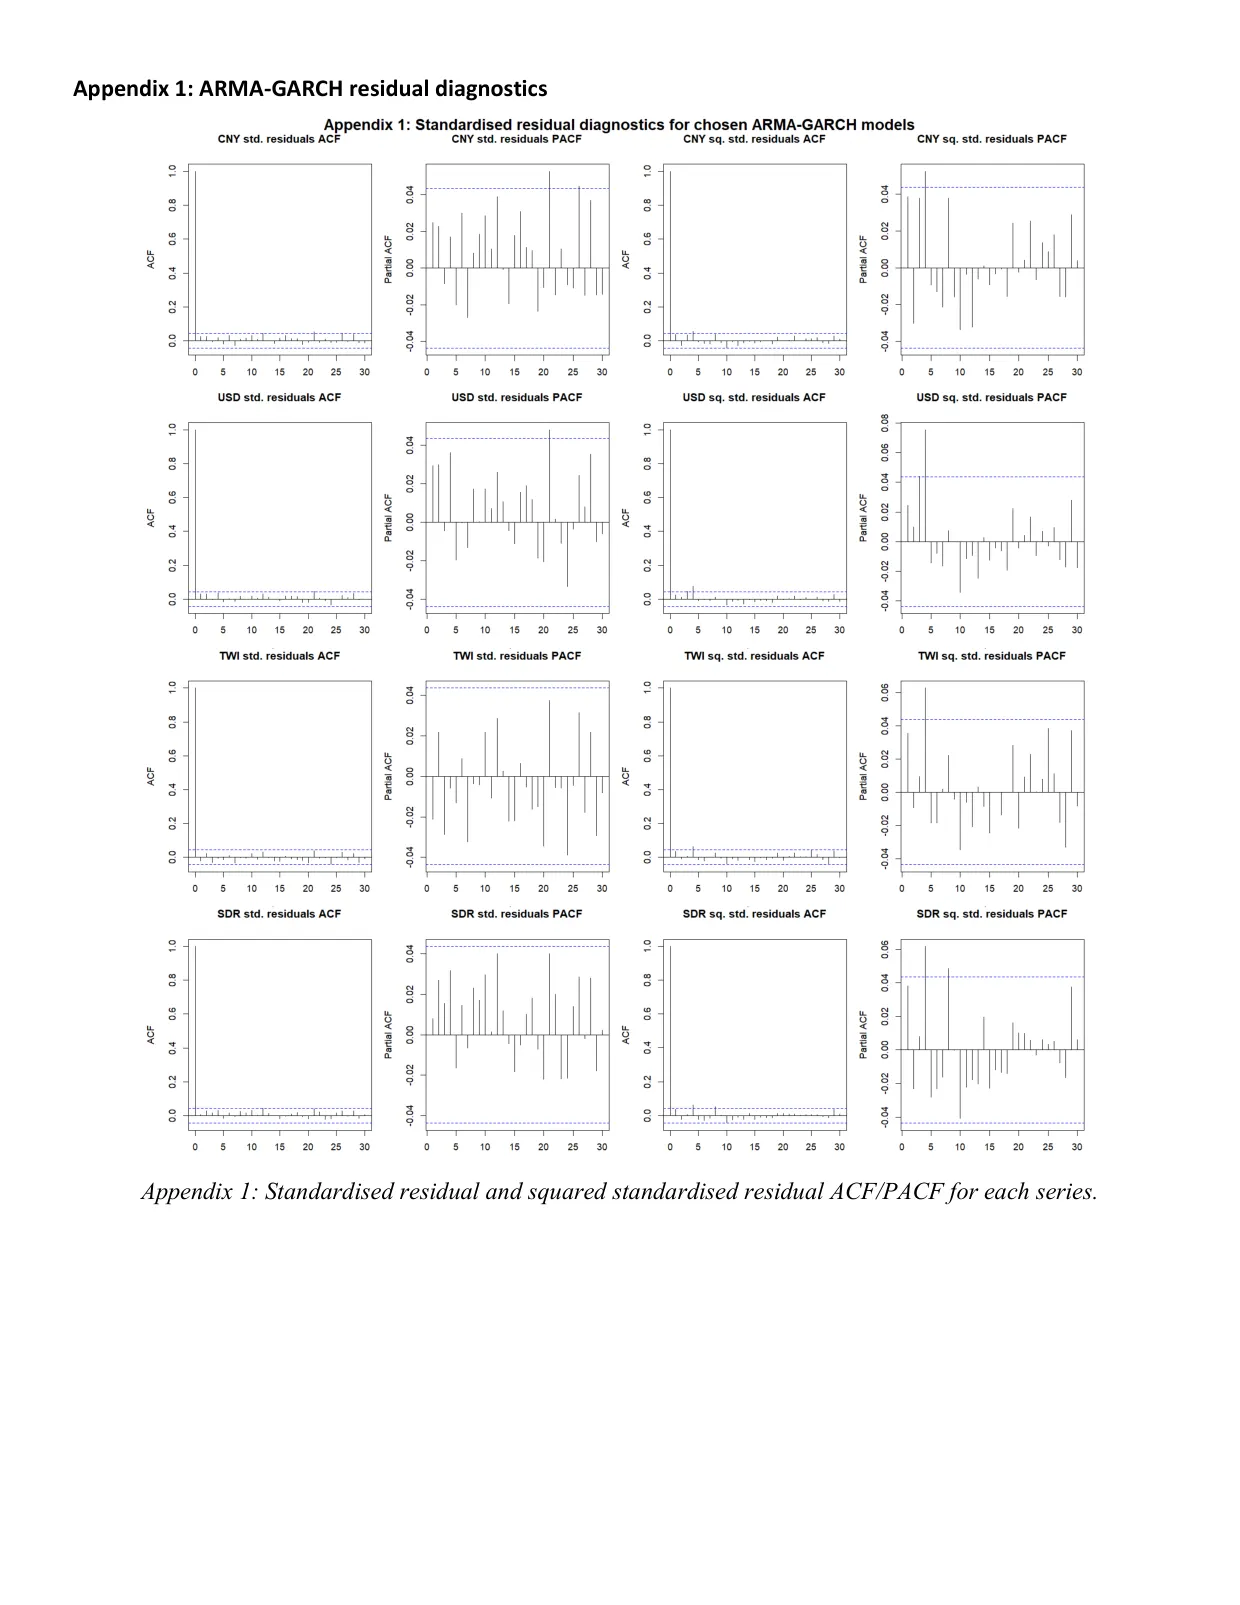
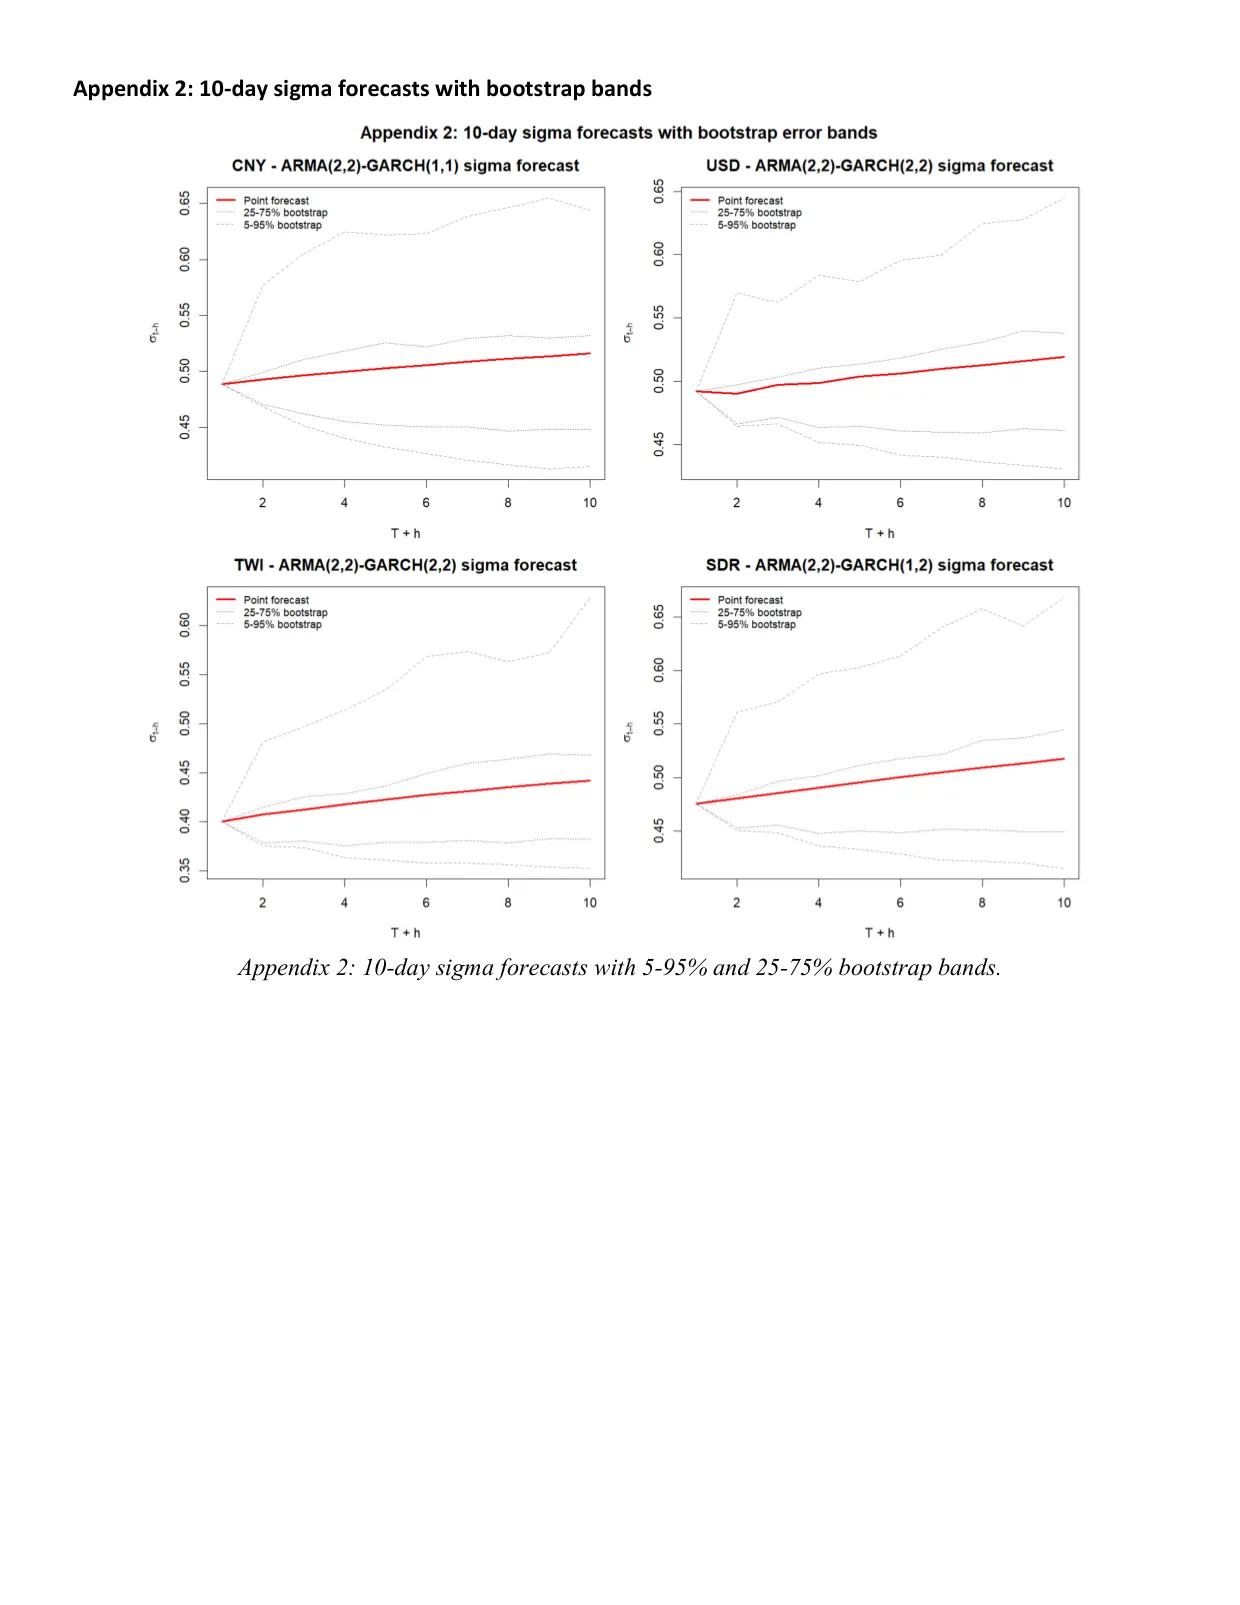
- US inflation, interest rates and exchange rates. Unit-root tests and ARIMA models for US inflation from 1959, compared on how well they forecast; models of the real interest rate and the consumption share of income; and ARMA-GARCH models of volatility in four exchange rates, with 10-day volatility forecasts.
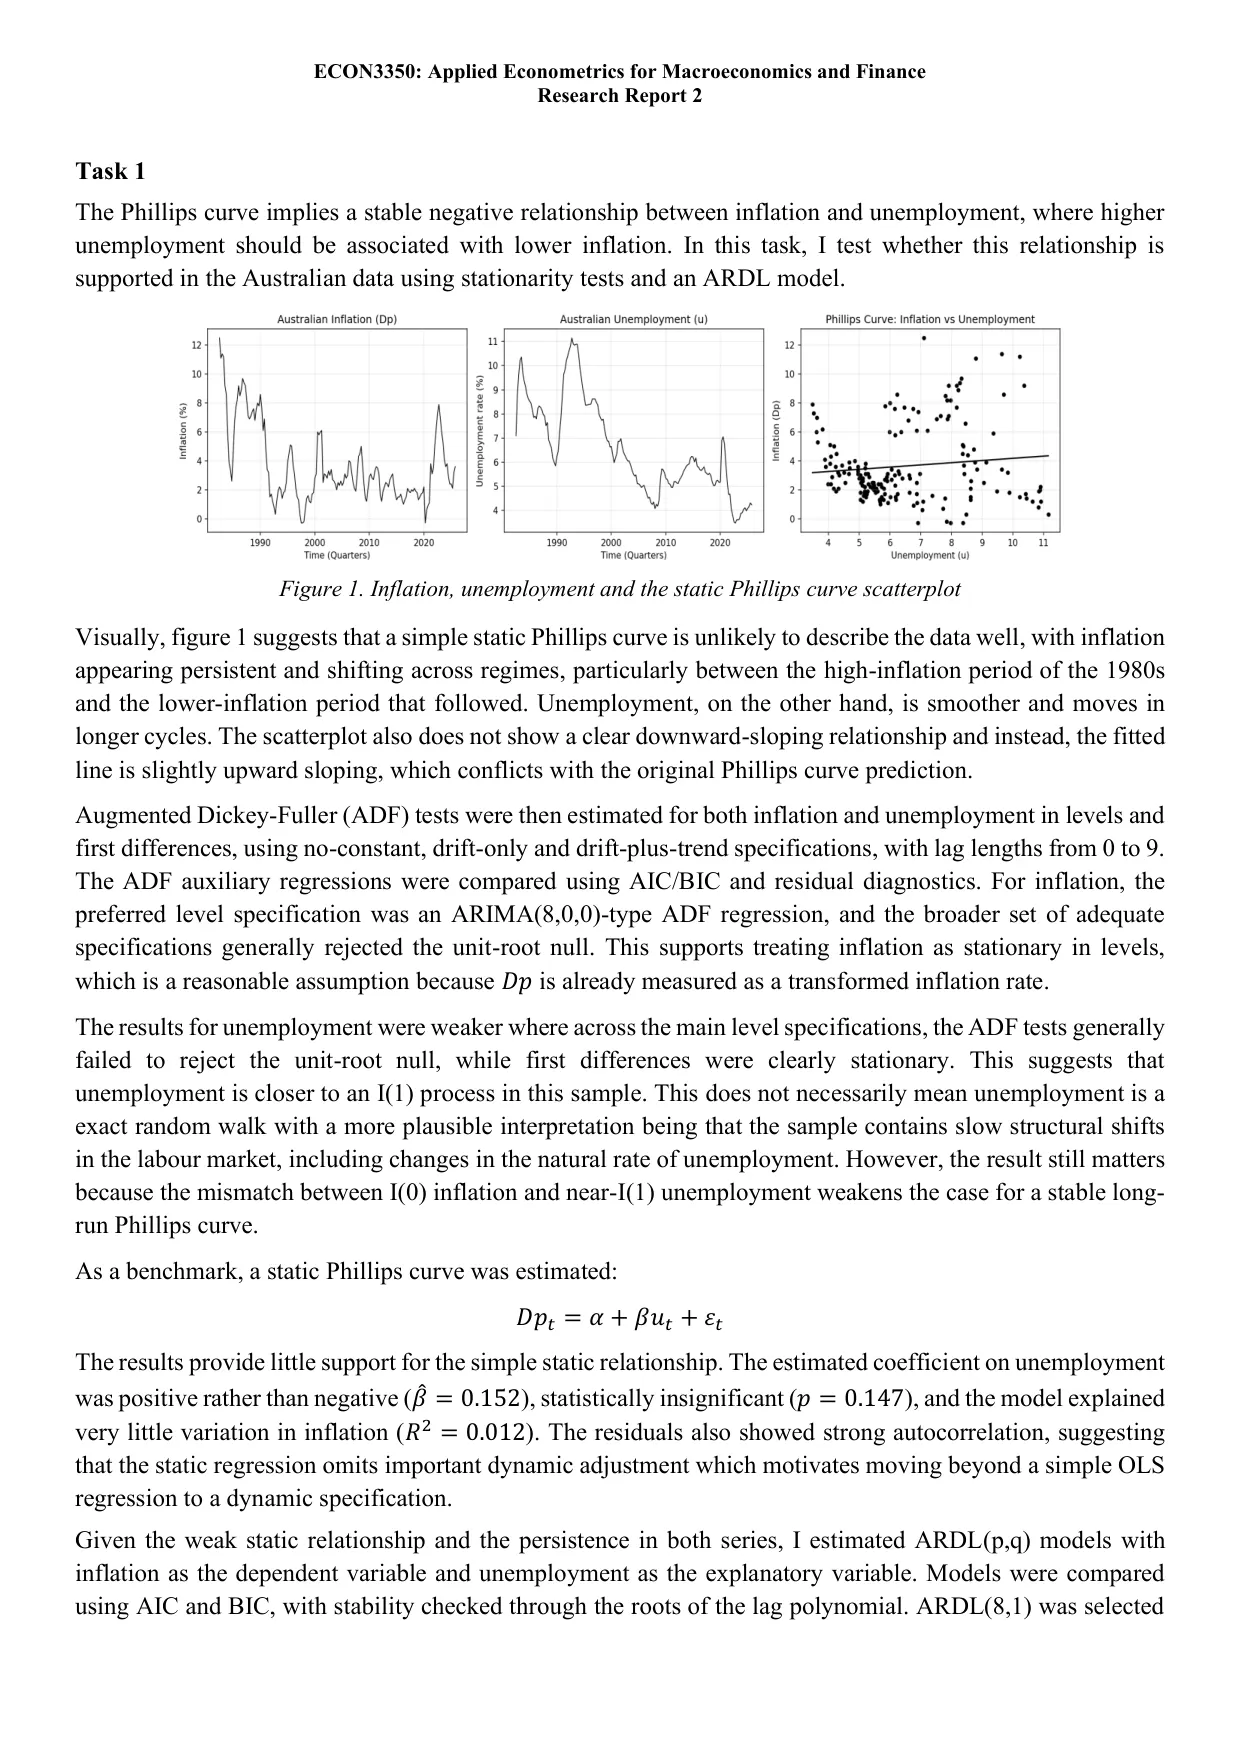
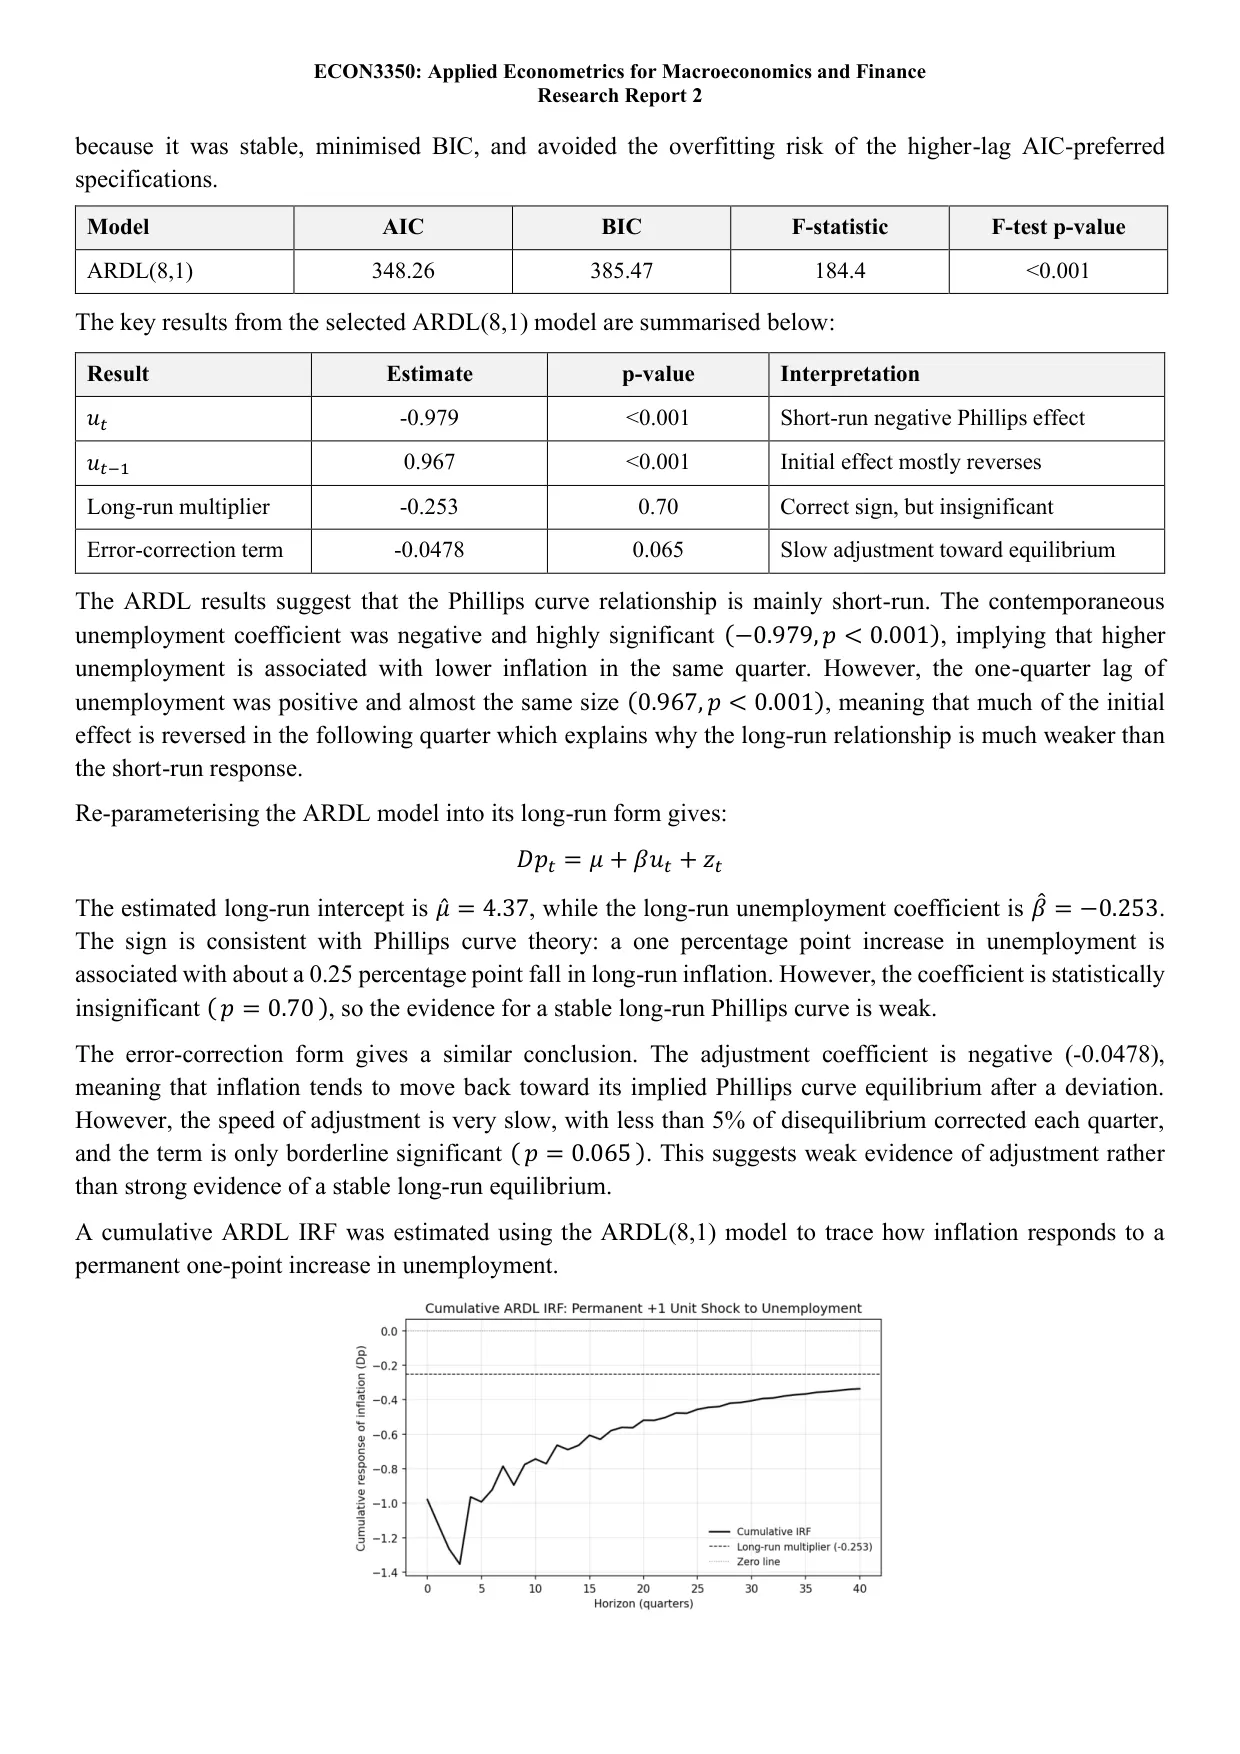
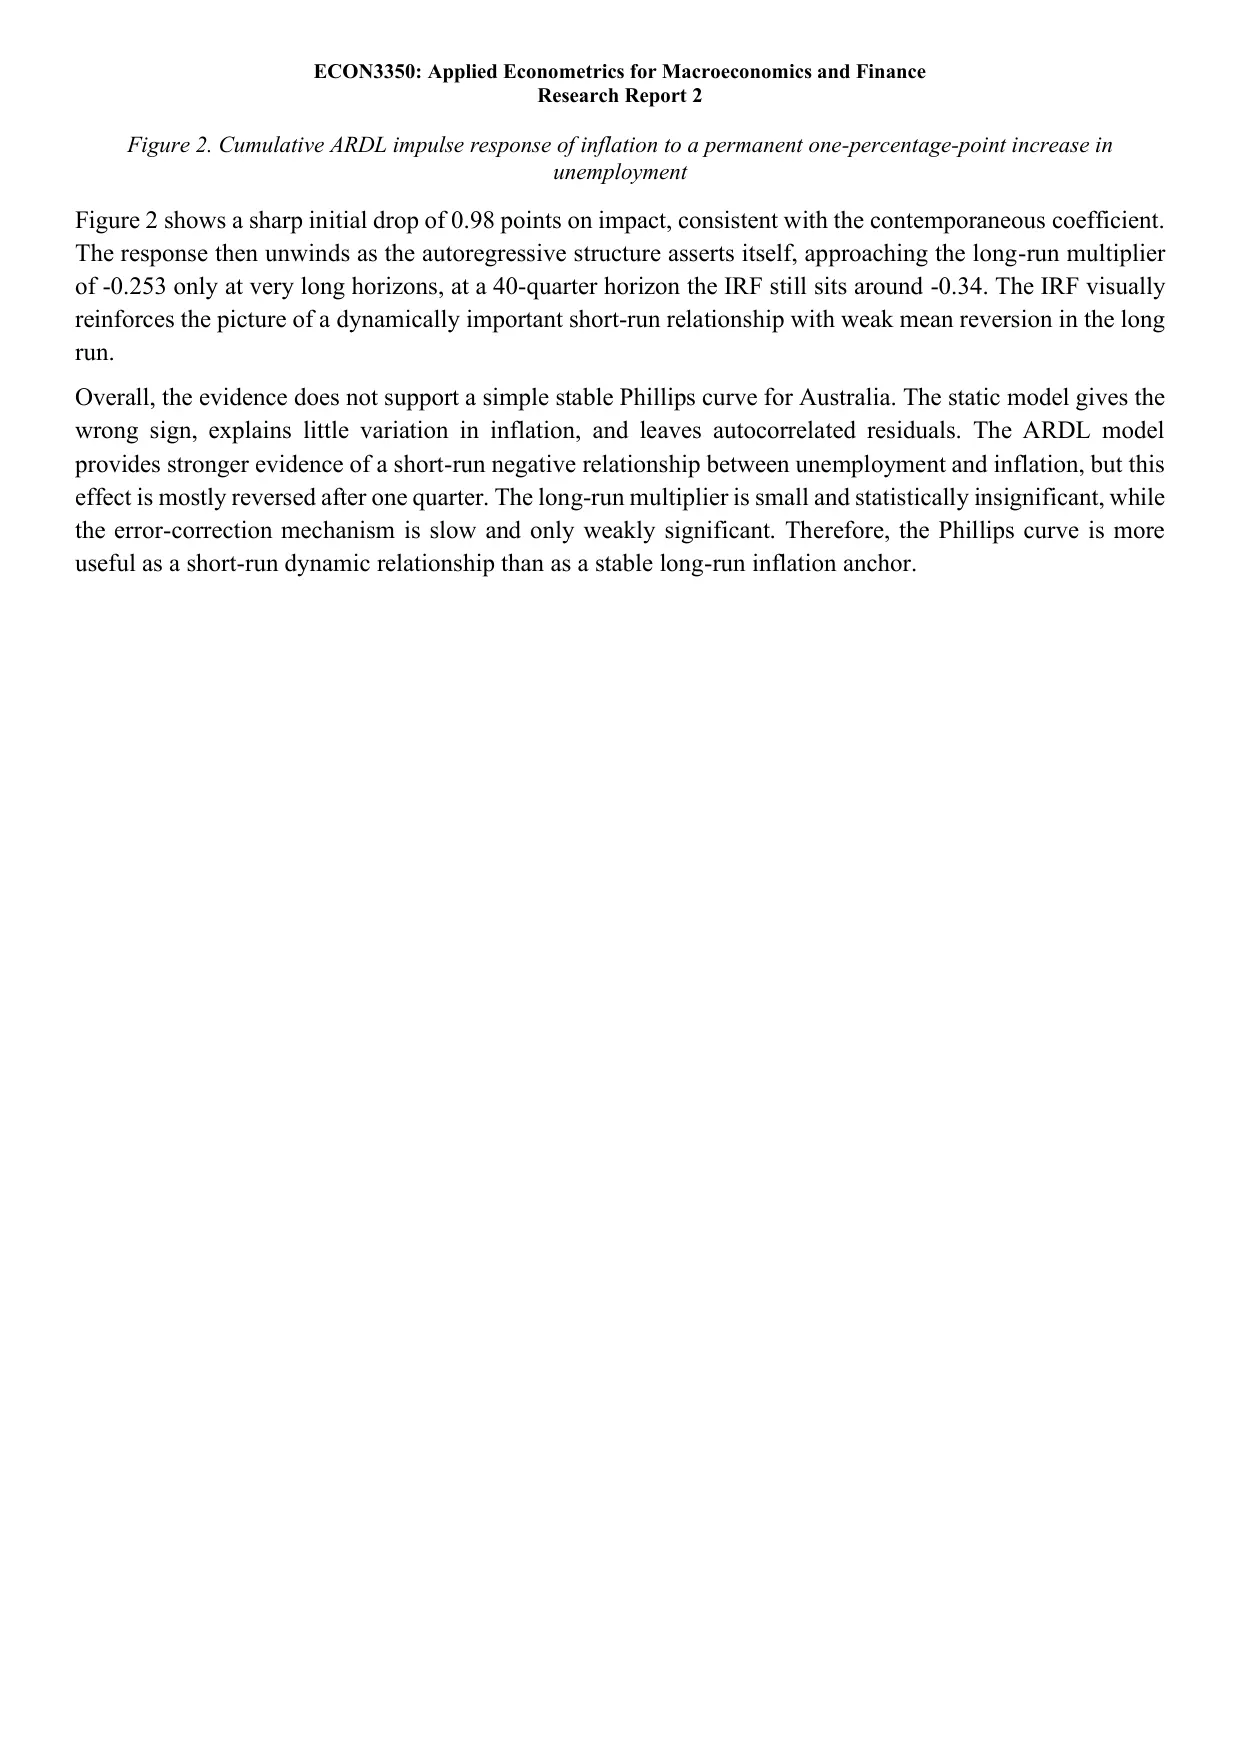
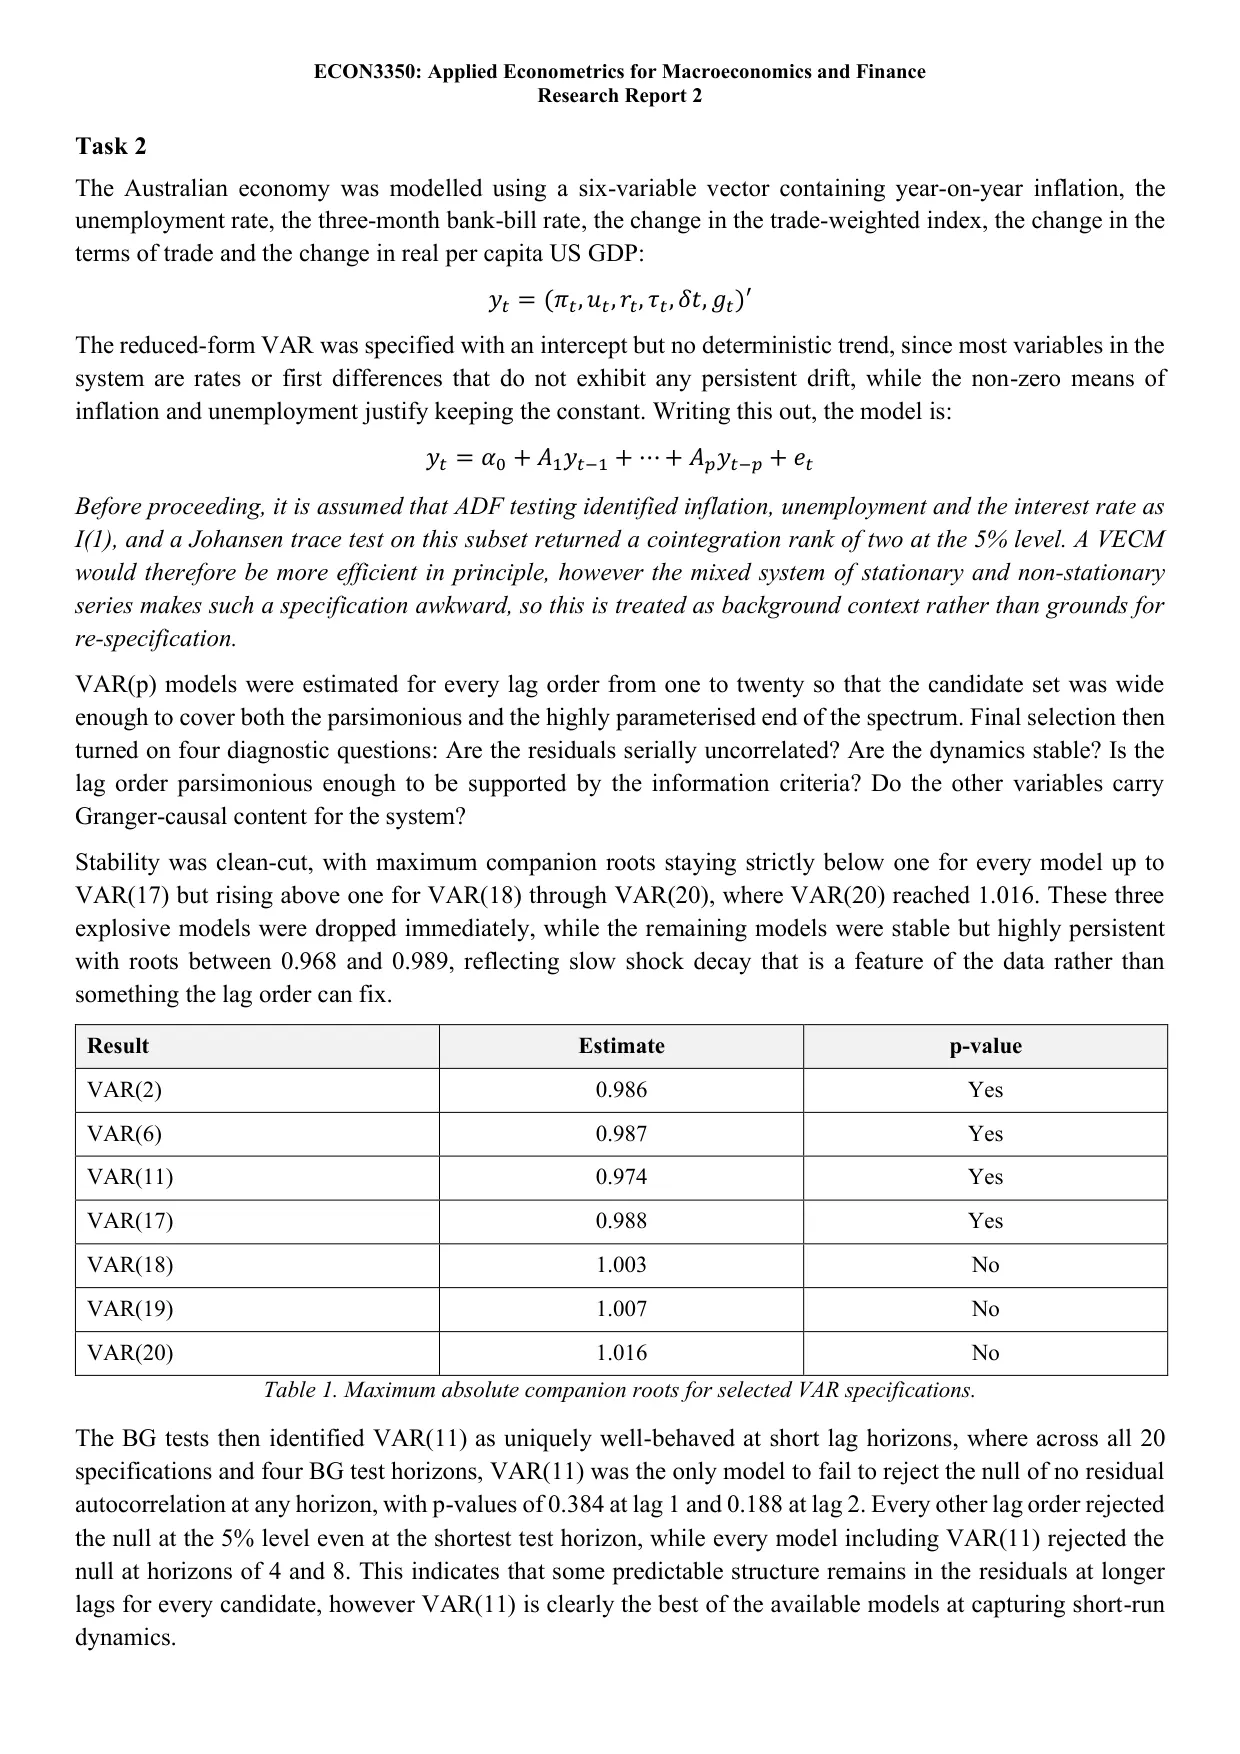
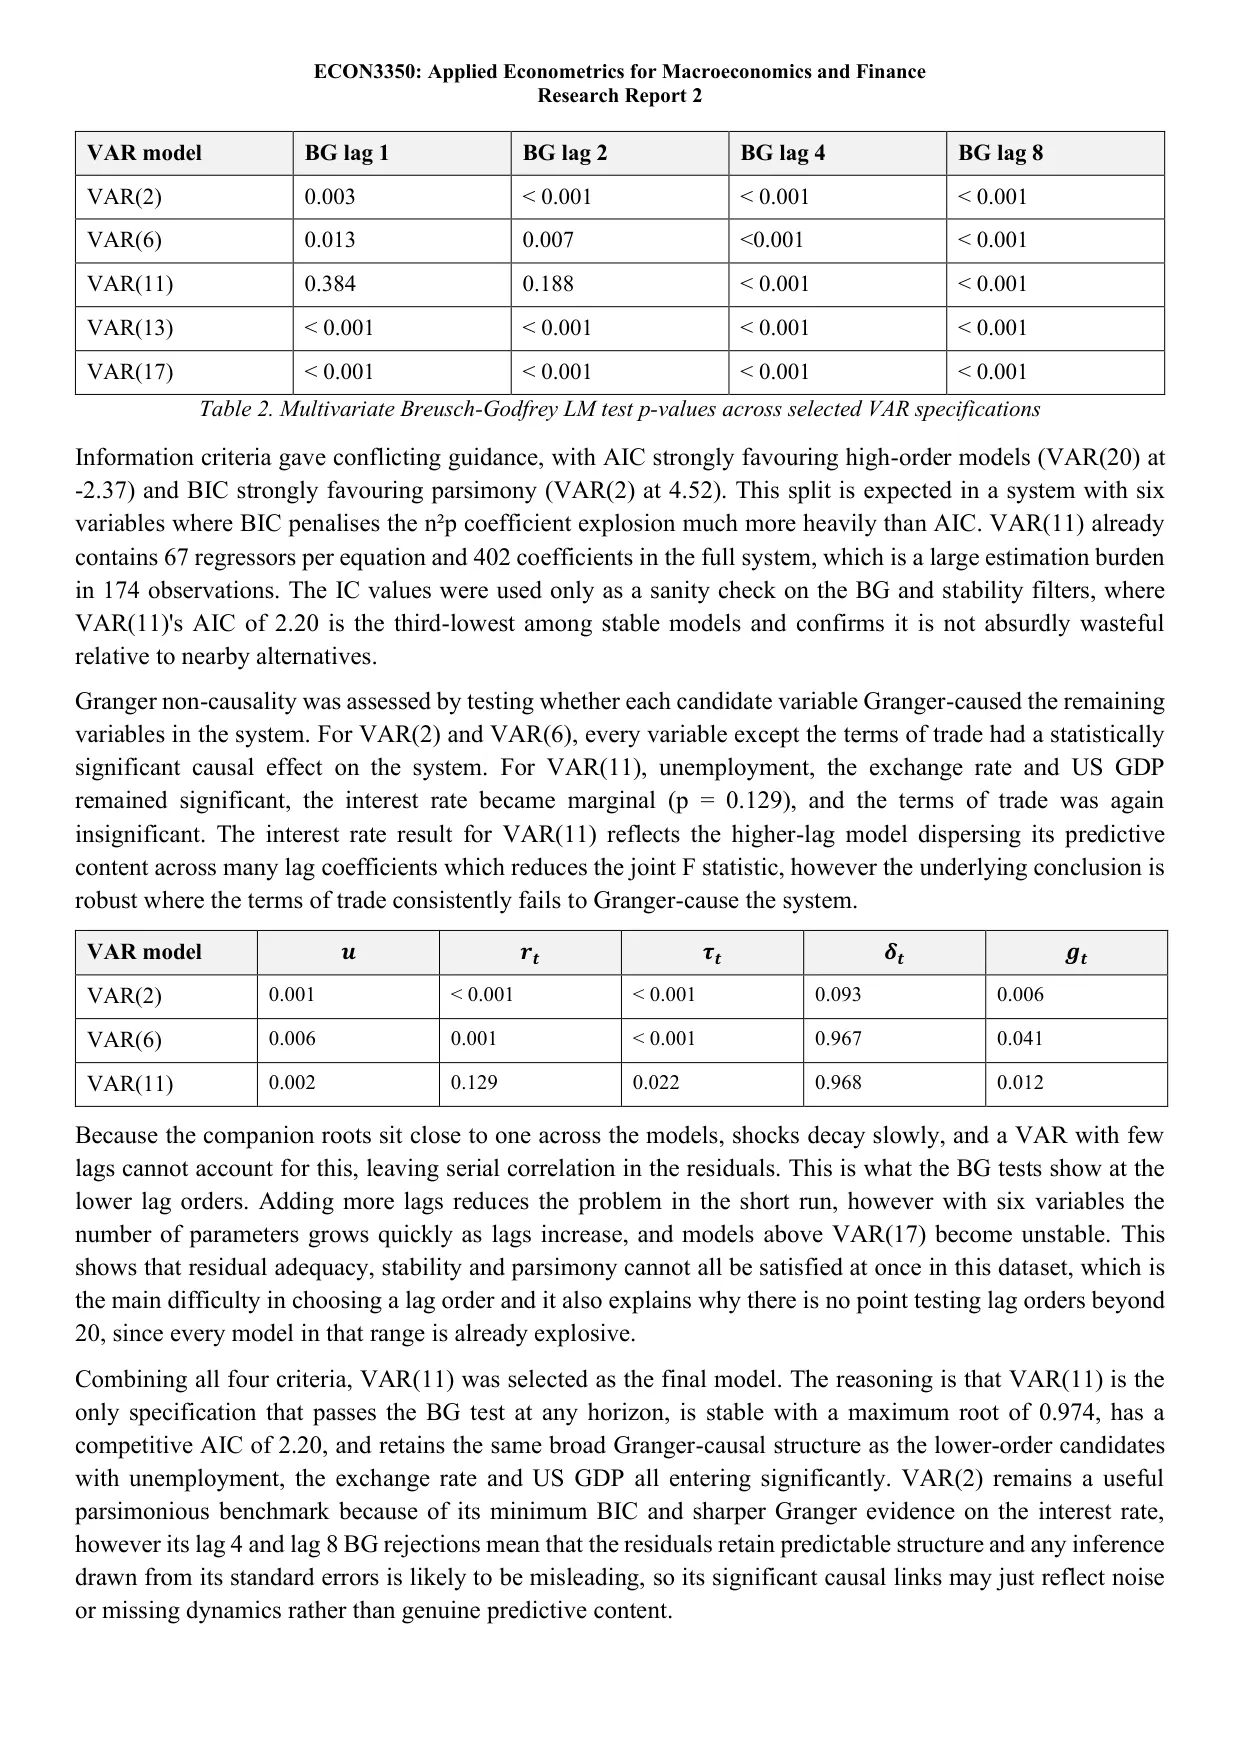
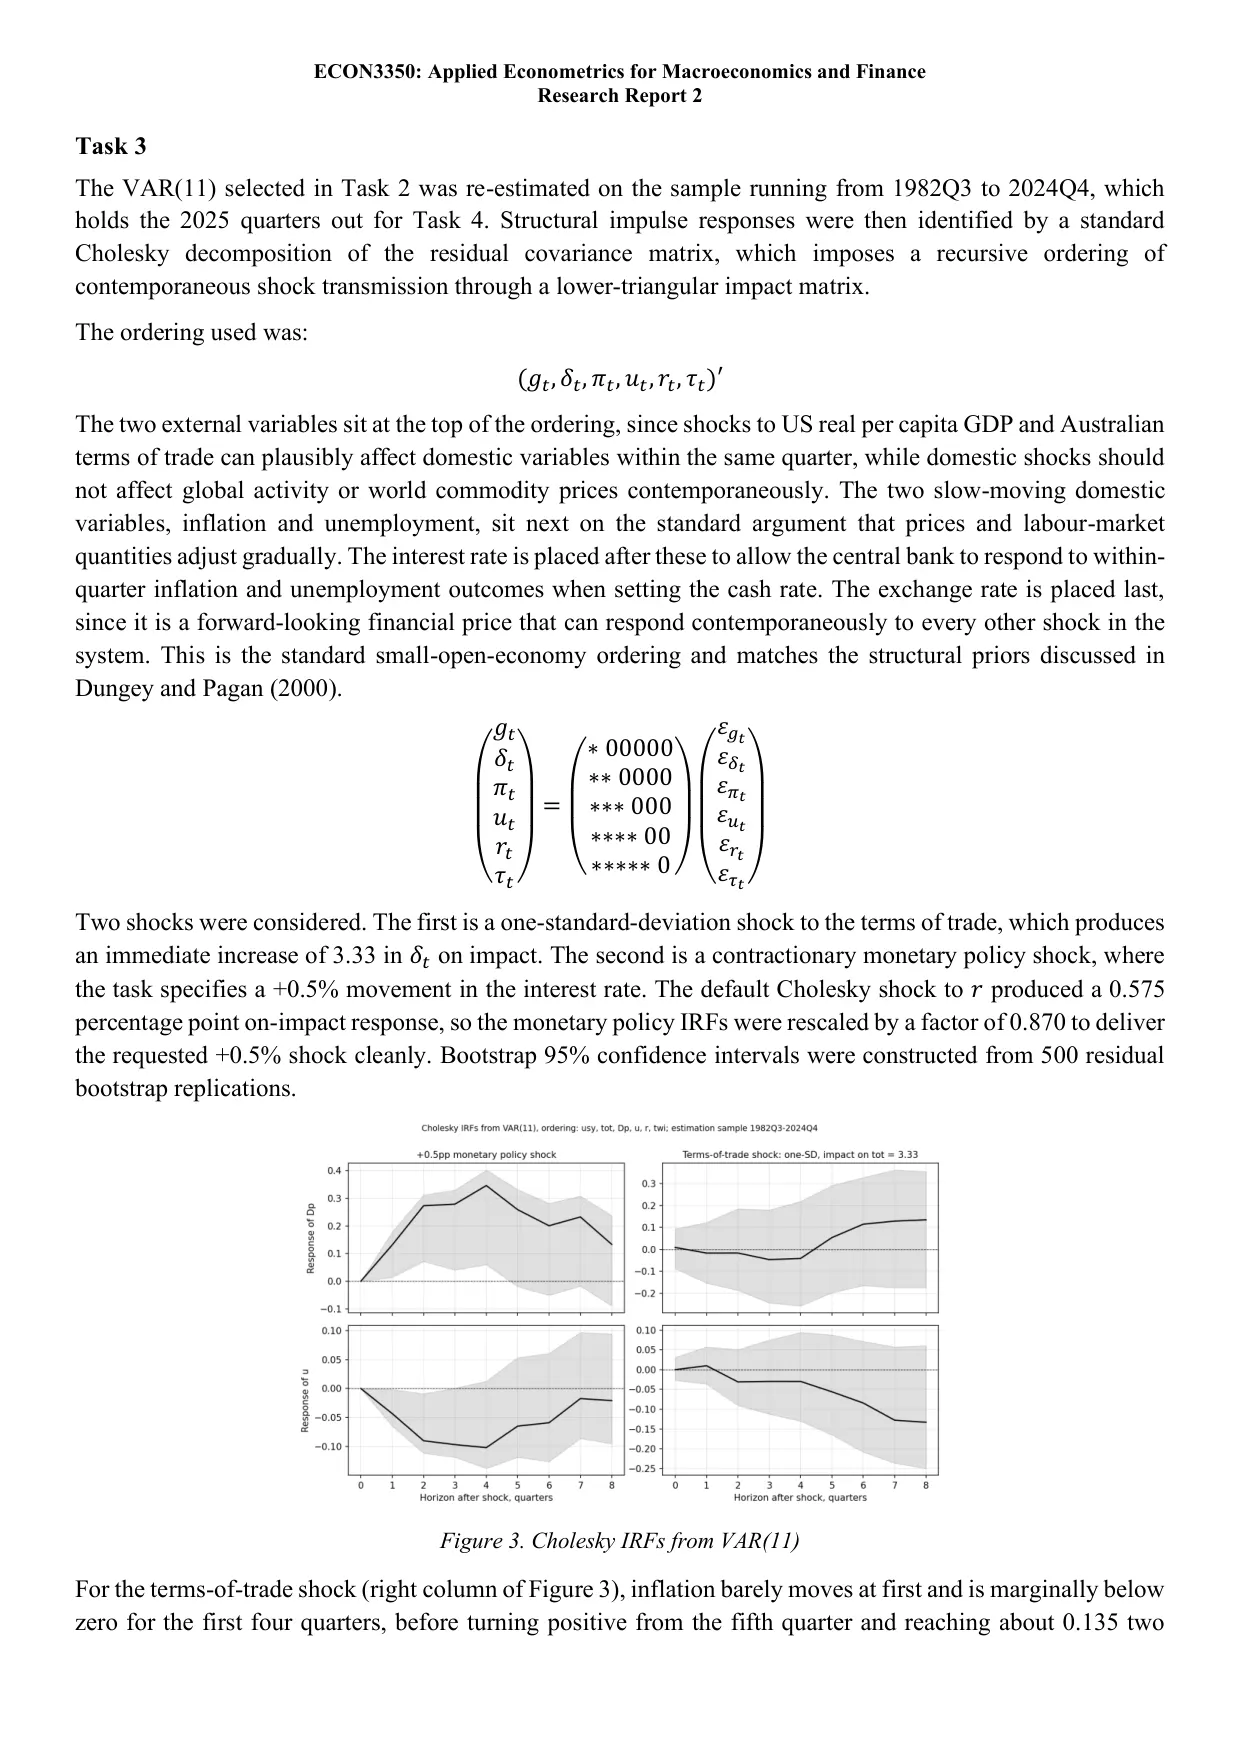
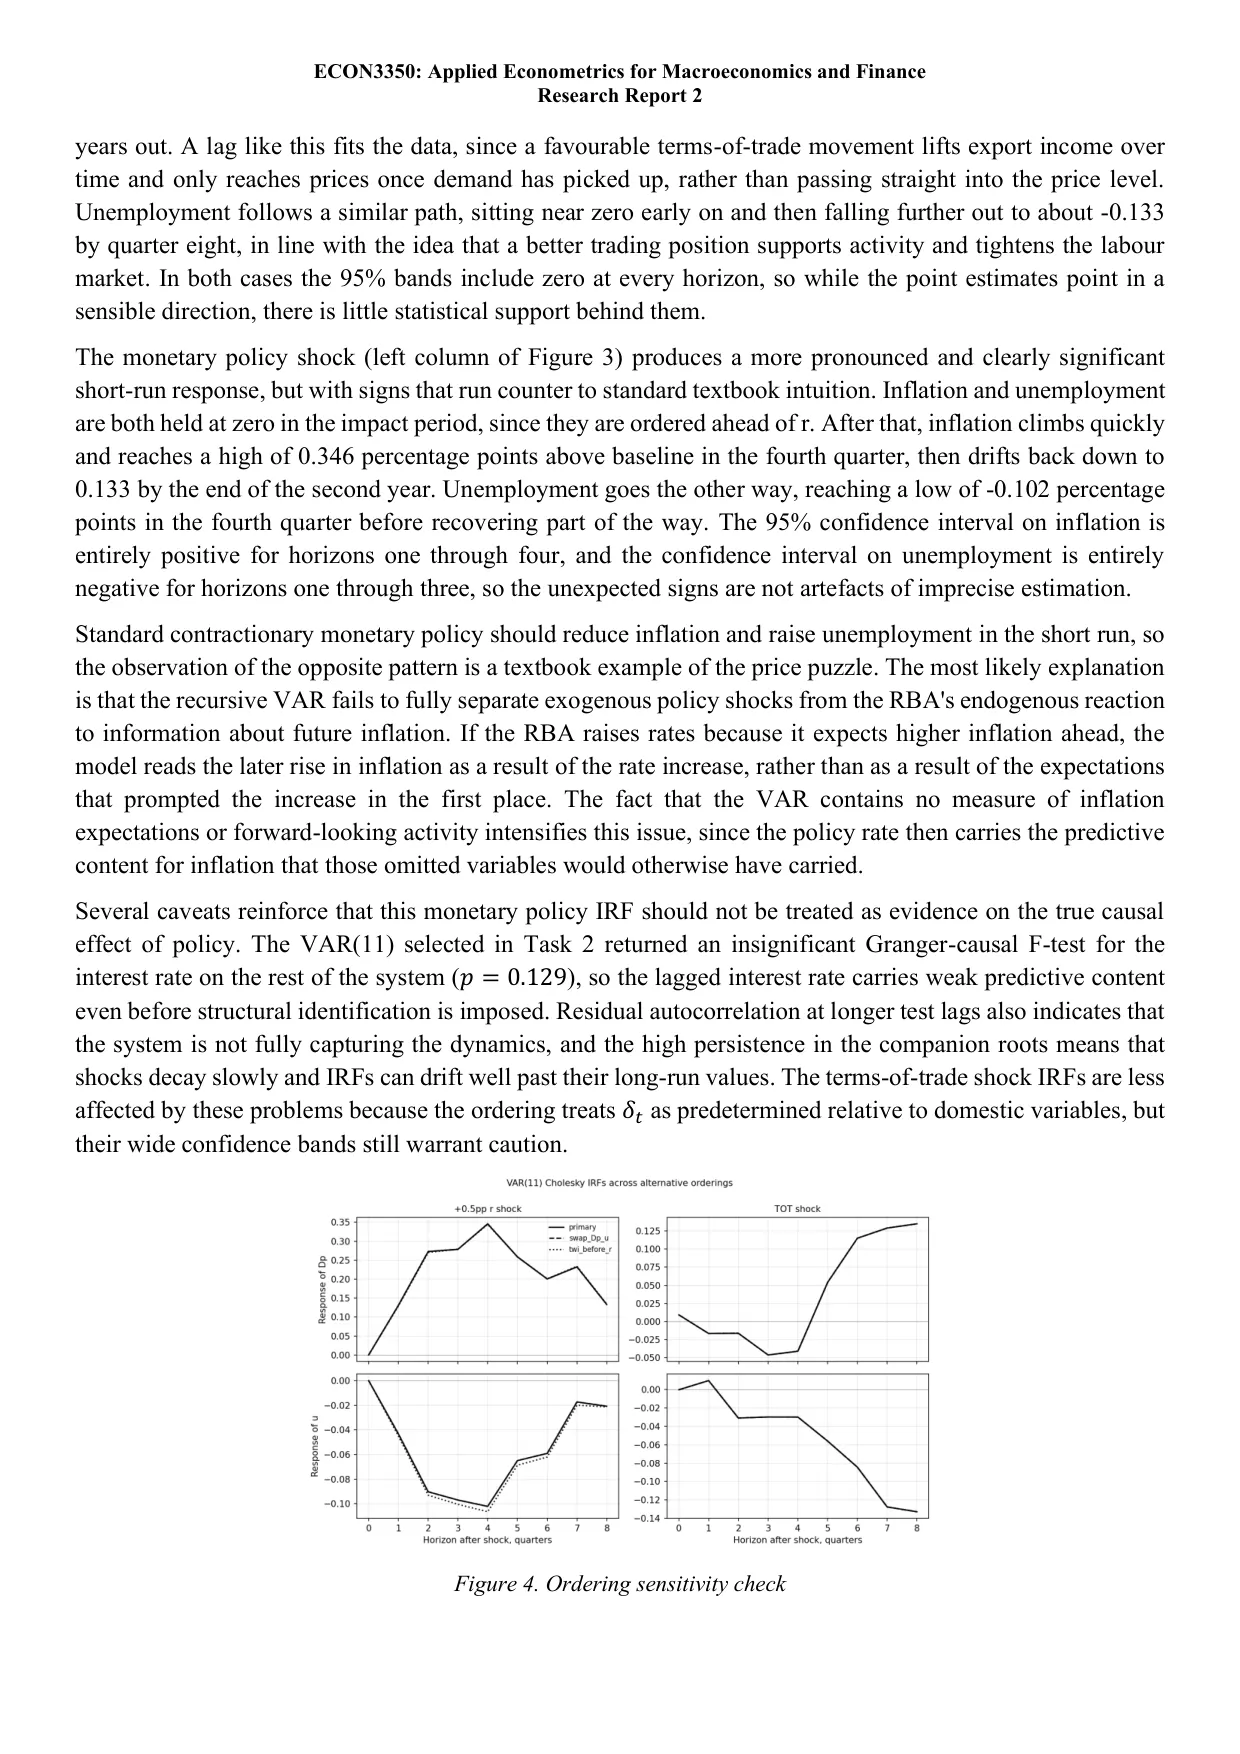
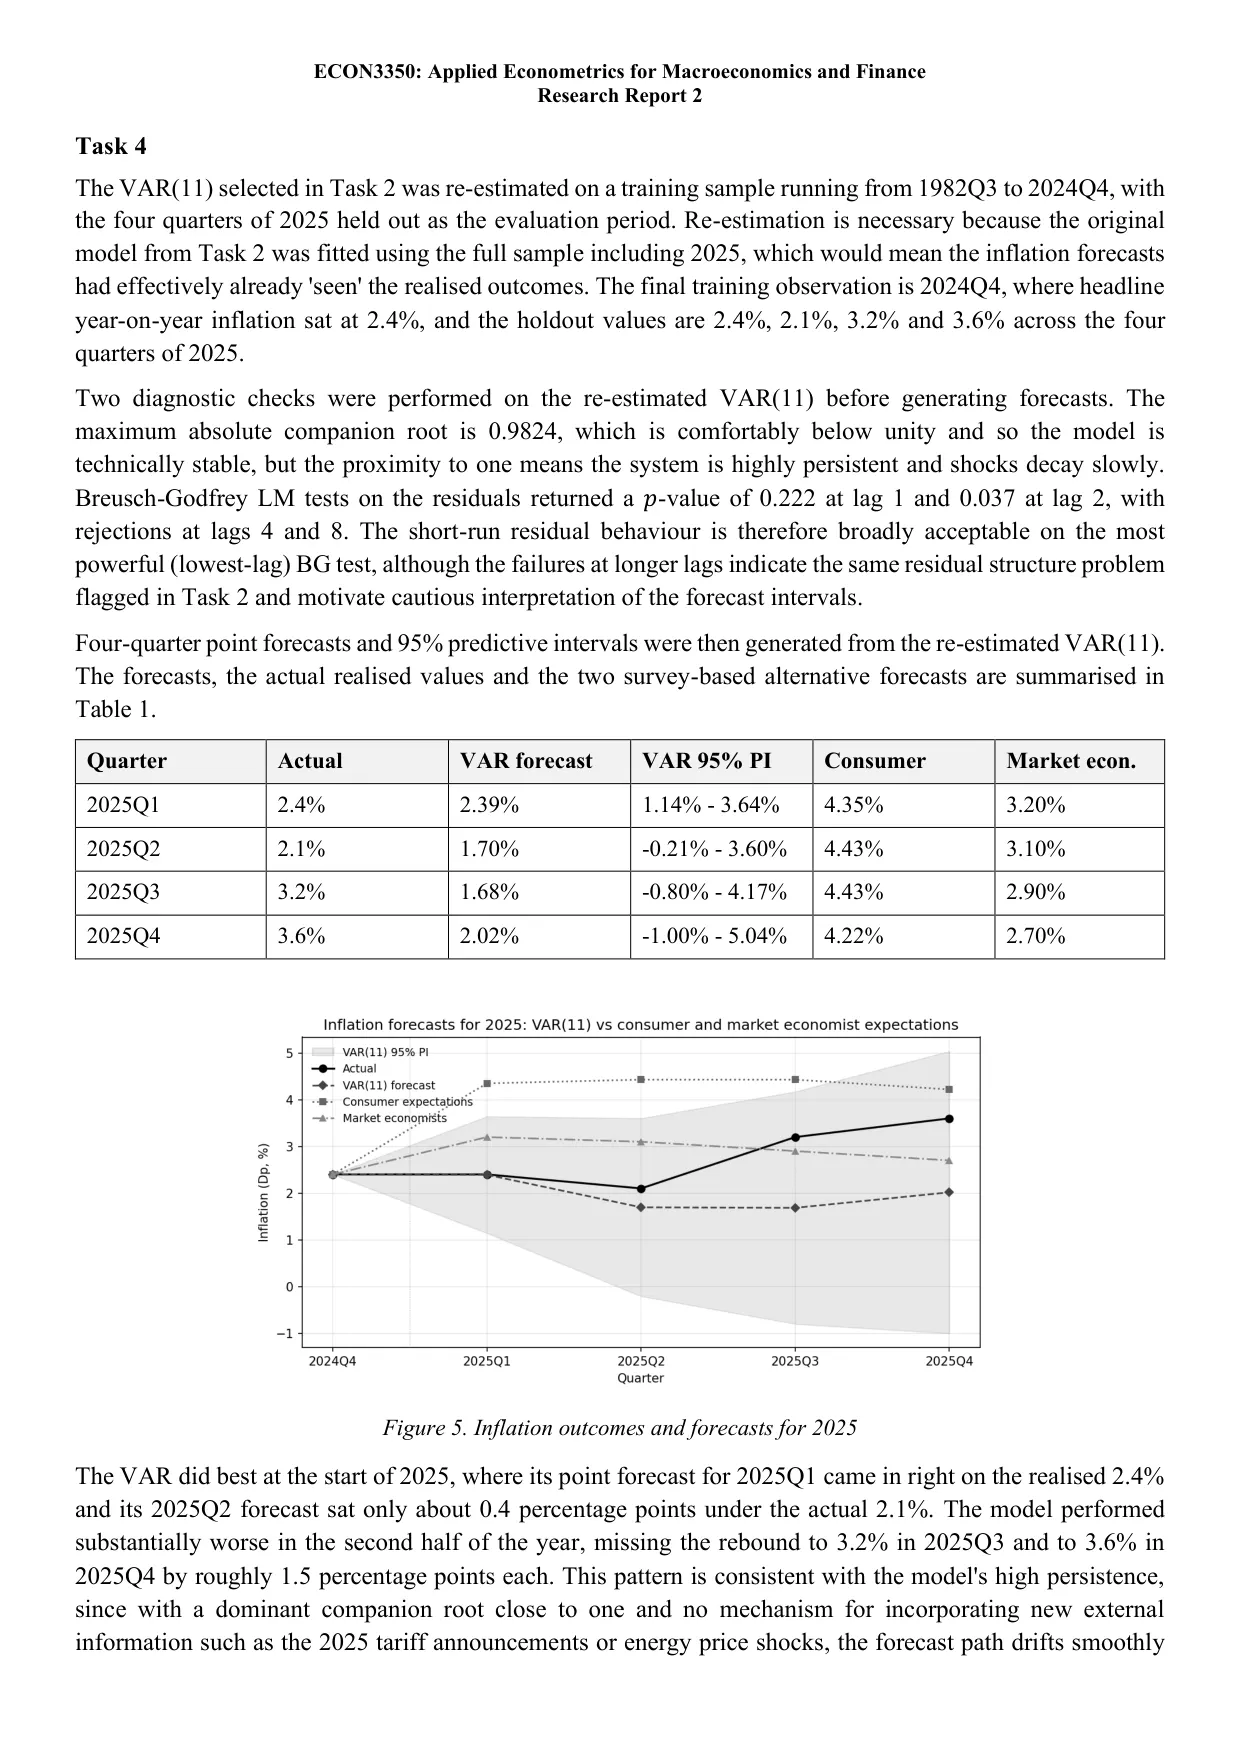
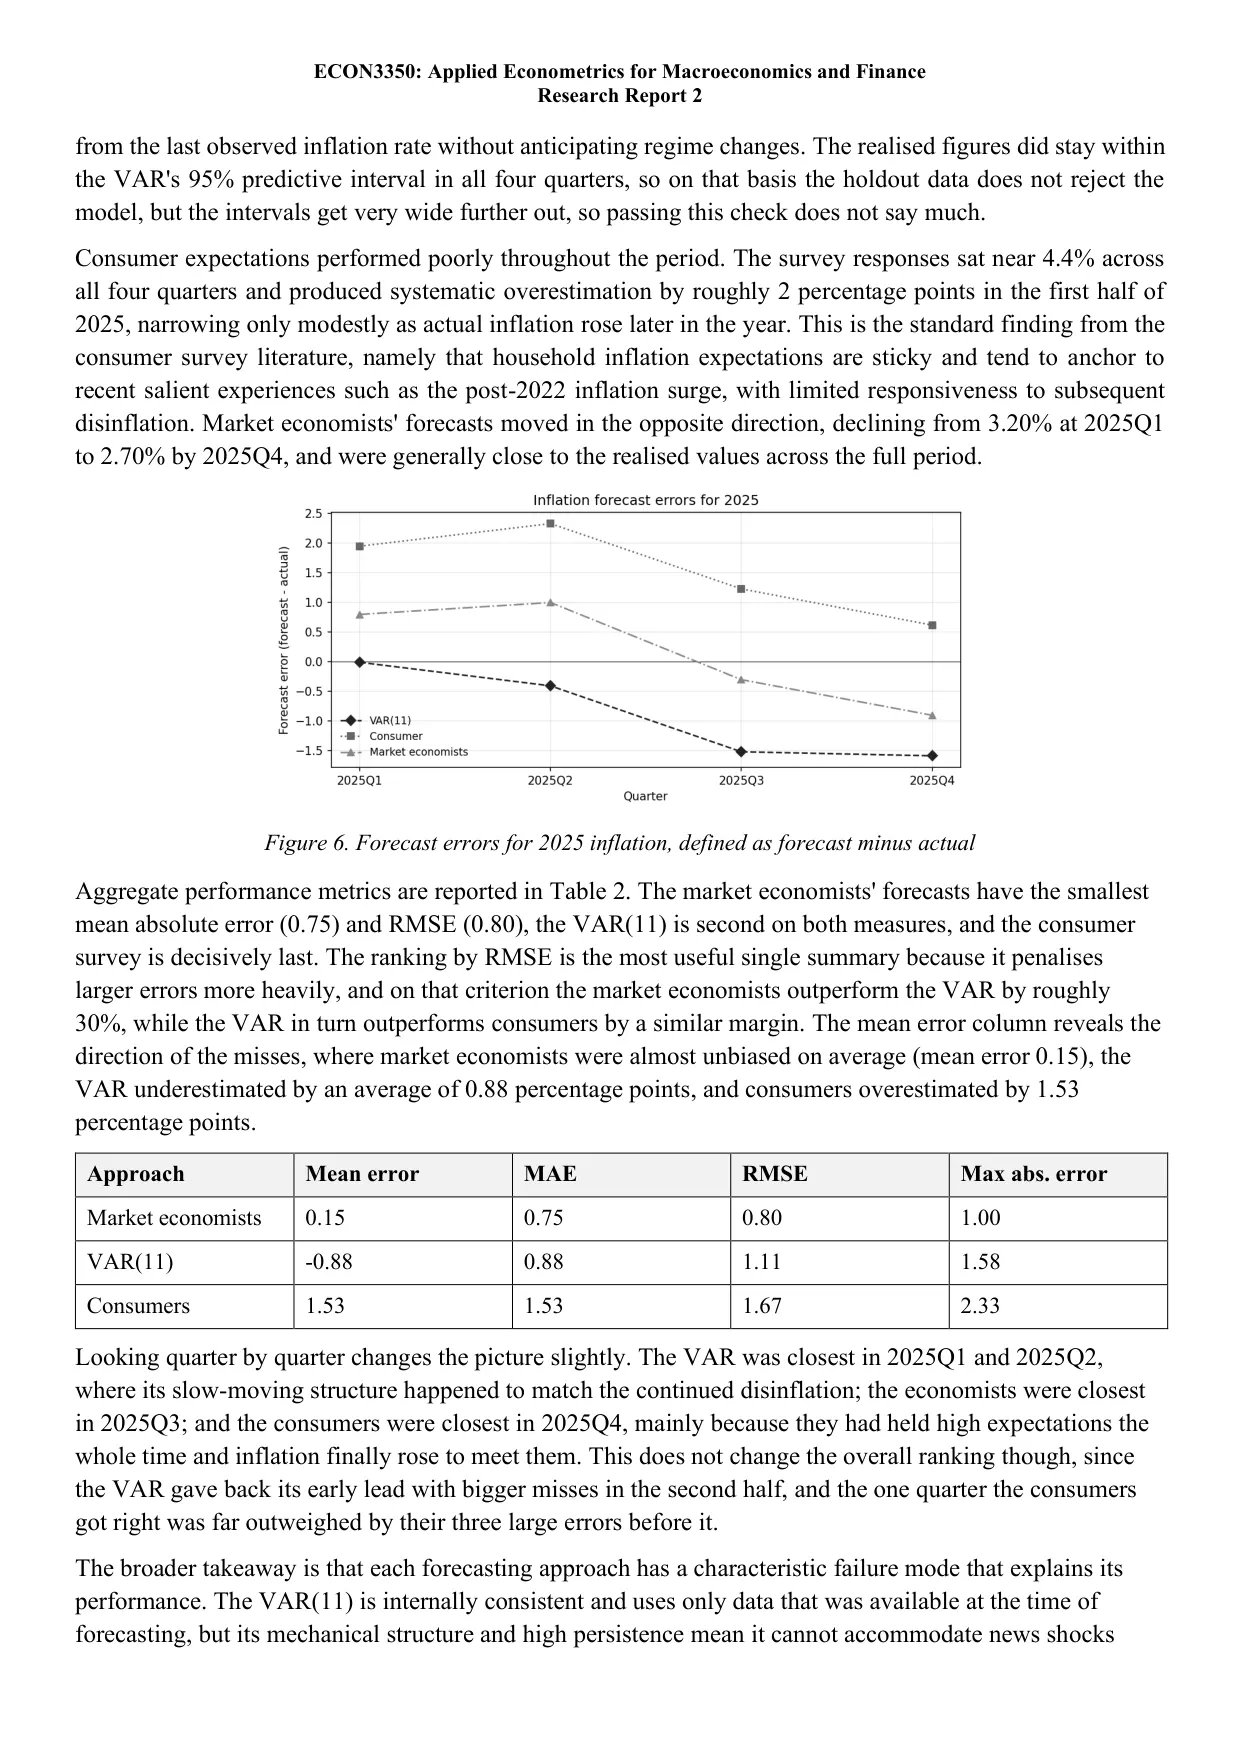
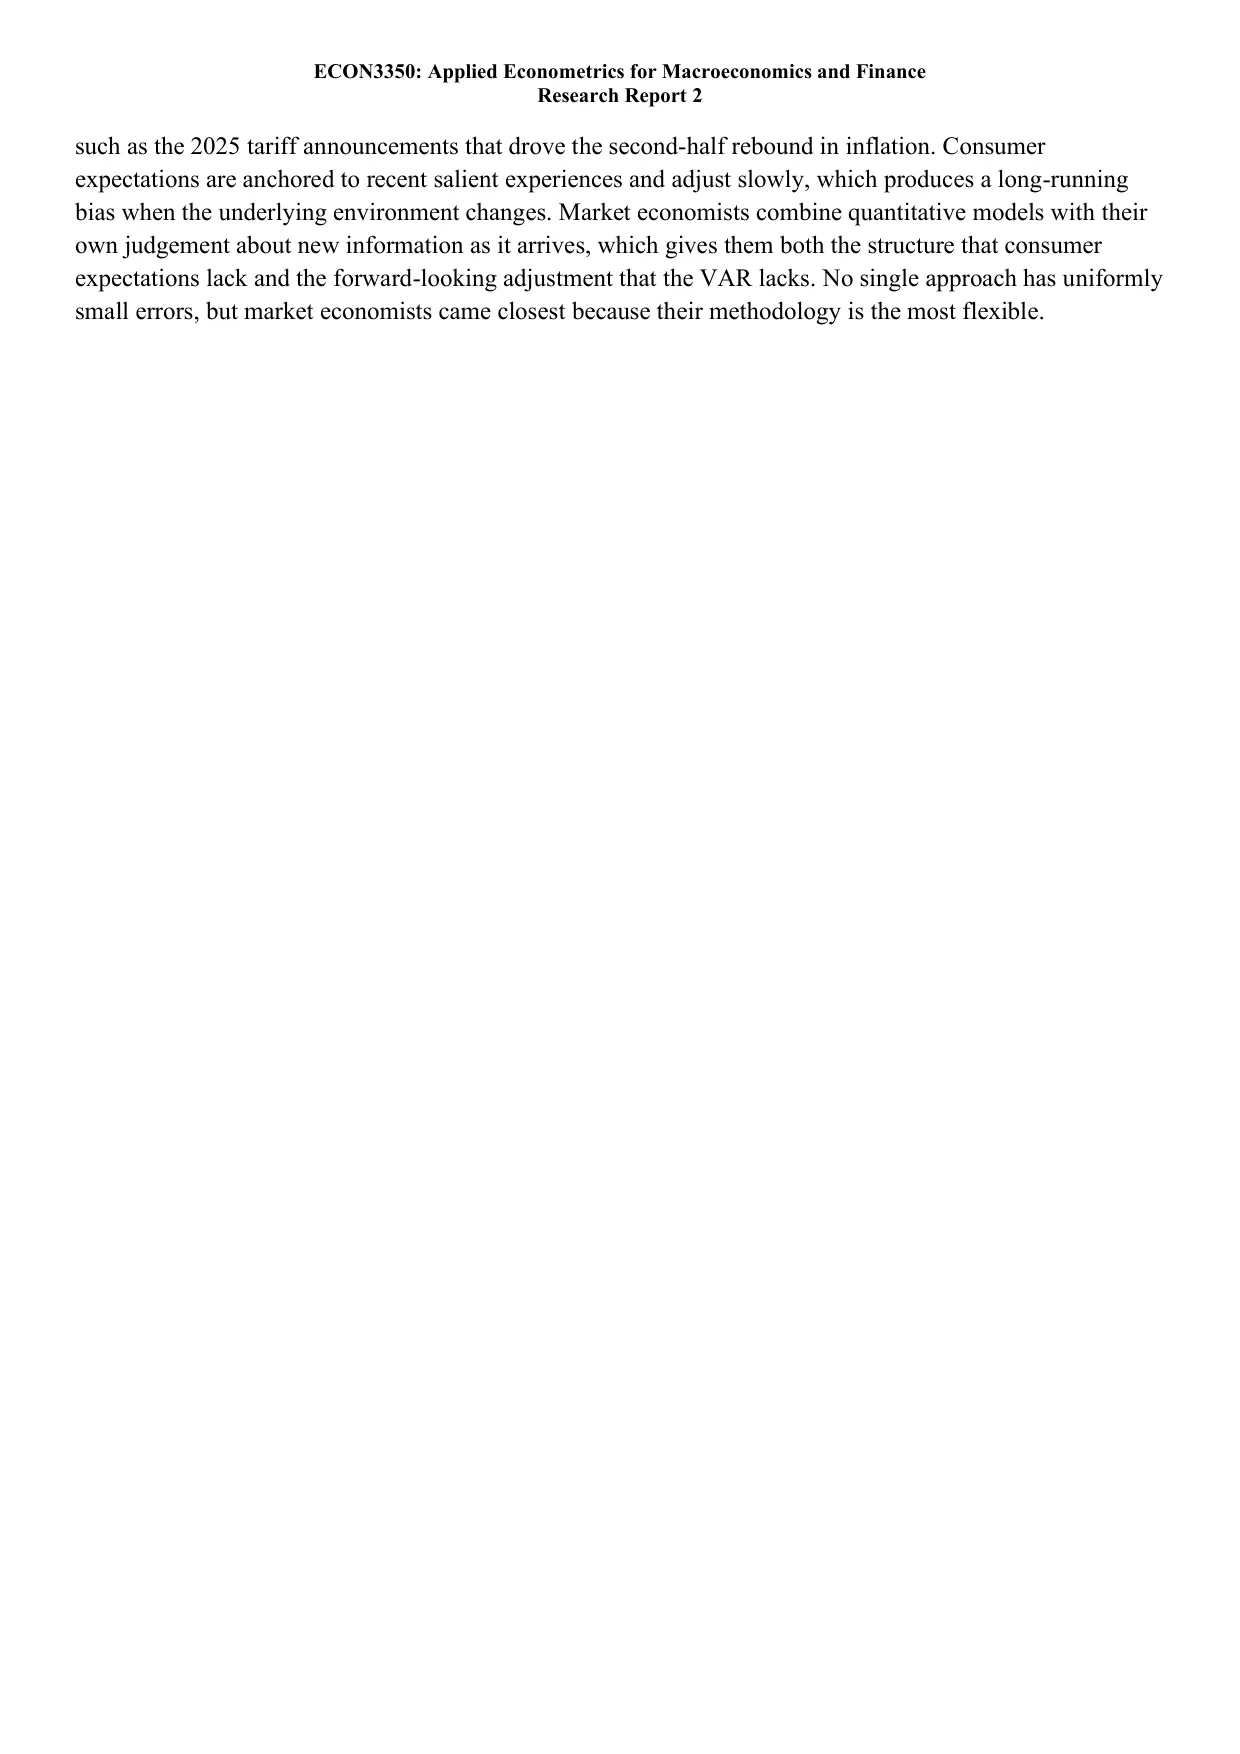
- Is there a Phillips curve in Australia? An ARDL model finds a short-run trade-off between unemployment and inflation that mostly reverses within a quarter, and no significant long-run one. A VAR traces how shocks pass between the variables, and its 2025 inflation forecasts are compared with consumers' and market economists' expectations. Market economists came closest.
Other work
- VALD Performance. An investment thesis.
- GE HealthCare. A short thesis.
The team decks were shared work. I have taken my teammates' names out of them; the analysis is all of ours.
Results
- Connell Griffin Consulting: second place.
- UQ student-managed investment fund stock pitch: finalist.
- FMAA ESG and Shared Value Investment Challenge: national finalist.
- J.P. Morgan Markets Sales: national semi-finalist.
- CBA Global Markets: national semi-finalist.